
 Global Antioxidant Vitamins Market | 2026-2036
Global Antioxidant Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antioxidant Vitamins Market Foresight
Encapsulation technology is fragmenting across multiple delivery platforms, forcing manufacturers to choose between liposomal, microencapsulated, and nano-dispersed formats. Koninklijke DSM N.V. leverages its synthetic biology pipeline to dominate high-purity Vitamin E production. BASF SE anchors its position through backward integration into petrochemical precursors for Vitamin C synthesis. Kemin Industries specializes in plant-derived tocopherol extraction, competing on clean-label positioning against petroleum-based alternatives.
Antioxidant vitamins are organic compounds that neutralize free radicals through electron donation, with Vitamin C (ascorbic acid, C6H8O6) functioning as a water-soluble radical scavenger and Vitamin E (tocopherols, C29H50O2) operating as a lipid-soluble membrane protector in biological systems. The primary commercial purpose spans human nutritional supplementation, cosmetic stability enhancement, and feed additive applications for livestock oxidative stress management. Vitamin C and Vitamin E collectively occupy the mature volume core where margin compression is acute, while Coenzyme Q10 represents the fastest-growing premium tier driven by cardiovascular and mitochondrial health positioning. Softgels and liposomal powders are displacing conventional tablets in the sports nutritionist channel, concentrating value in format innovation rather than commodity active ingredients.
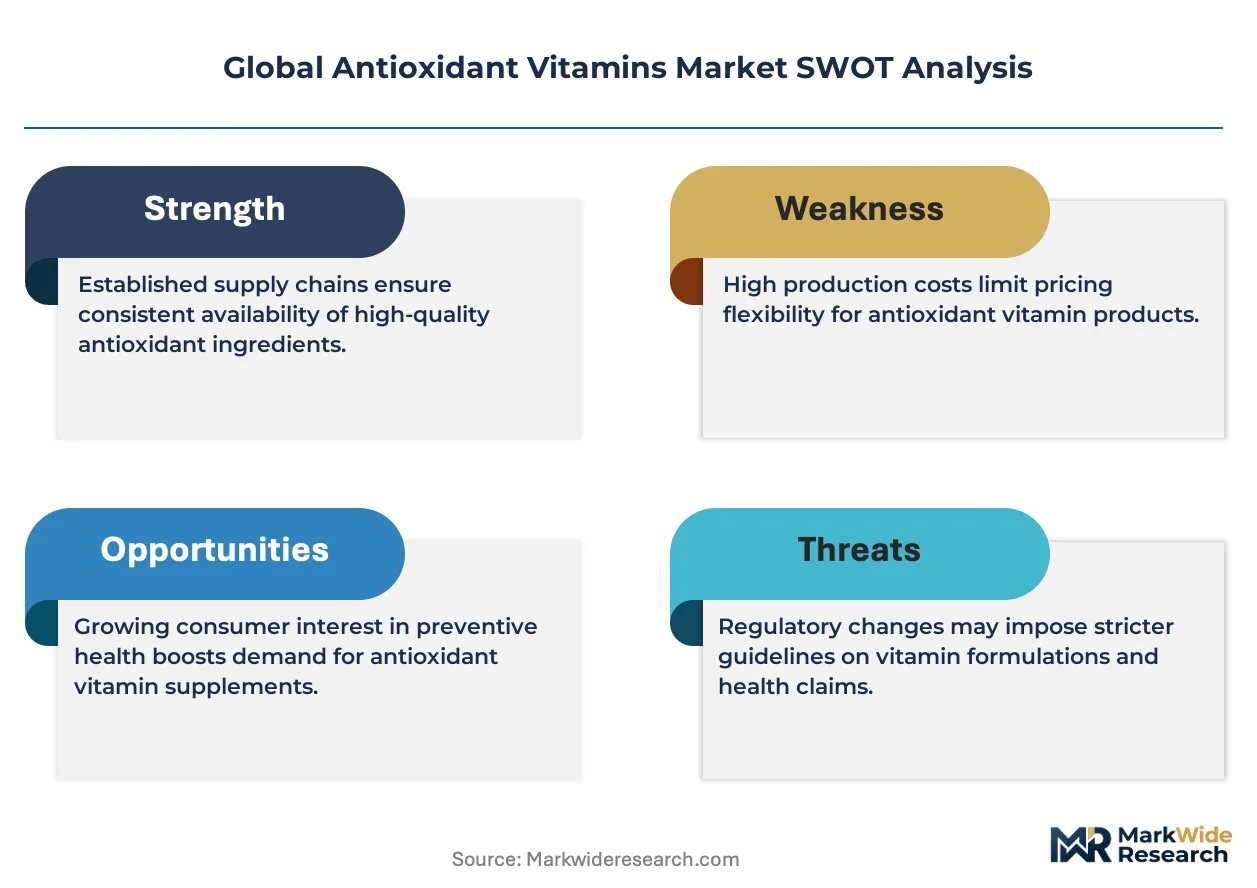
FDA's New Dietary Ingredient notification requirements and the EU's Novel Food Catalogue govern market access for emerging antioxidant formulations, with EFSA health claim substantiation determining permissible marketing language across European member states. India's FSSAI fortification standards and China's NMPA Blue Hat registration create divergent compliance pathways that fragment export strategies for multinational suppliers. Stakeholders must monitor evolving pharmacopeial monograph revisions and adapt manufacturing footprints to regional purity specifications before committing capital to capacity expansion.
Market Dynamics
Encapsulation technology fragmentation is forcing manufacturers to commit capital to single delivery platforms rather than maintaining flexible production, locking in competitive positioning around liposomal, microencapsulated, or nano-dispersed formats for the next investment cycle.
Growth Catalysts
- Sports nutrition channel expansion:Softgels and liposomal powders are capturing shelf space from conventional tablets in performance-focused retail, concentrating value in format innovation.
- EU Novel Food Catalogue updates:EFSA health claim substantiation pathways are clarifying permissible marketing language for fortified products, reducing regulatory uncertainty for new entrants.
- Livestock oxidative stress management:Feed additive applications for antioxidant vitamins are expanding as producers seek alternatives to antibiotic growth promoters under tightening veterinary regulations.
Market Restraints
- Petrochemical precursor volatility:BASF SE's backward integration into Vitamin C synthesis feedstocks exposes the broader market to ethylene and propylene price swings from refining capacity constraints.
- Synthetic biology capacity concentration:High-purity Vitamin E production depends on a narrow base of microbial fermentation facilities, creating single-source vulnerability for pharmaceutical-grade formulations.
- Clean-label petroleum substitution ceiling:Plant-derived tocopherol extraction yields remain below petroleum-based alternatives, limiting Kemin Industries' ability to scale cost-competitive natural positioning.
Strategic Opportunities
- India FSSAI fortification mandates:Staple food fortification standards are creating institutional procurement channels for Vitamin C and Vitamin E premixes in wheat flour and edible oils.
- Mitochondrial health premium tier:Coenzyme Q10 positioning around cardiovascular applications commands pricing multiples over commodity vitamins, attracting R&D investment from dietary supplement manufacturers.
- Cosmetic stability enhancement:Liposomal Vitamin E is penetrating prestige skincare formulations as brands seek antioxidant protection without compromising emulsion integrity.
Industry Challenges
- Pharmacopeial monograph divergence:USP, EP, and ChP purity specifications for ascorbic acid and tocopherols require separate validation batches, complicating unified manufacturing footprints.
- Blue Hat registration timelines:China's NMPA health food approval process extends 18-24 months for imported antioxidant formulations, tying up working capital in regulatory limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antioxidant Vitamins Market |
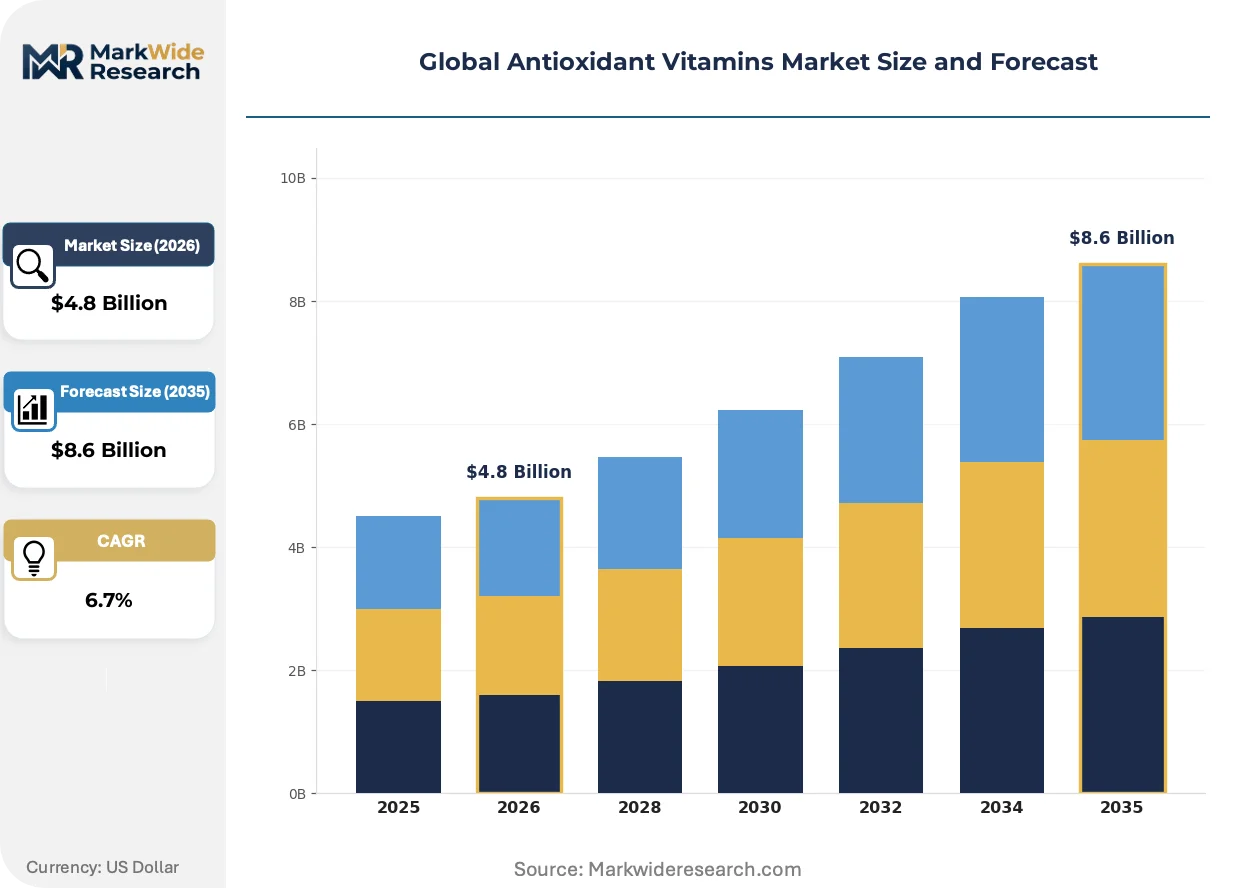
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin C, Vitamin E, Beta-Carotene, Selenium, Coenzyme Q10 Form: Capsules, Tablets, Powders, Softgels, Gummies Application: Dietary Supplements, Functional Foods, Personal Care, Pharmaceuticals, Animal Nutrition End User: Pharmacies, Health Stores, Sports Nutritionists, Dermatology Clinics, Veterinary Clinics |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill Incorporated, Koninklijke DSM N.V., DuPont de Nemours, Inc., Kemin Industries, Inc., Nutreco N.V., Adisseo, Amway Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antioxidant Vitamins Market Shifts & Advancements
Delivery format innovation is compressing margins on commodity active ingredients while concentrating value capture in encapsulation technology licensors and specialized contract manufacturers.
Liposomal encapsulation is migrating from niche pharmaceutical applications toward mass-market dietary supplements. Sports nutrition brands and direct-to-consumer wellness platforms are adopting liposomal Vitamin C at accelerating rates. The technology is migrating from high-cost parenteral formulations to oral powders and softgels, enabling premium positioning that extracts value from bioavailability claims rather than raw material differentiation.
REACH authorization requirements for novel antioxidant derivatives are tightening substance volume thresholds and toxicity data obligations. The European Chemicals Agency's evolving endpoint criteria are extending registration timelines for synthetic tocopherol analogues. Cosmetic ingredient suppliers are reformulating with established rather than novel antioxidants to avoid authorization bottlenecks, favoring incumbent chemistries over innovation.
Direct procurement from encapsulation technology providers is disintermediating traditional excipient distributors. Dietary supplement manufacturers are establishing technical partnerships with liposome specialists rather than sourcing through chemical distributors. Germany's specialized nutrition cluster around Frankfurt and Mannheim exhibits this pattern most visibly, with regional formulators embedding encapsulation partners into NPD workflows.
Global Antioxidant Vitamins Market Segmentation
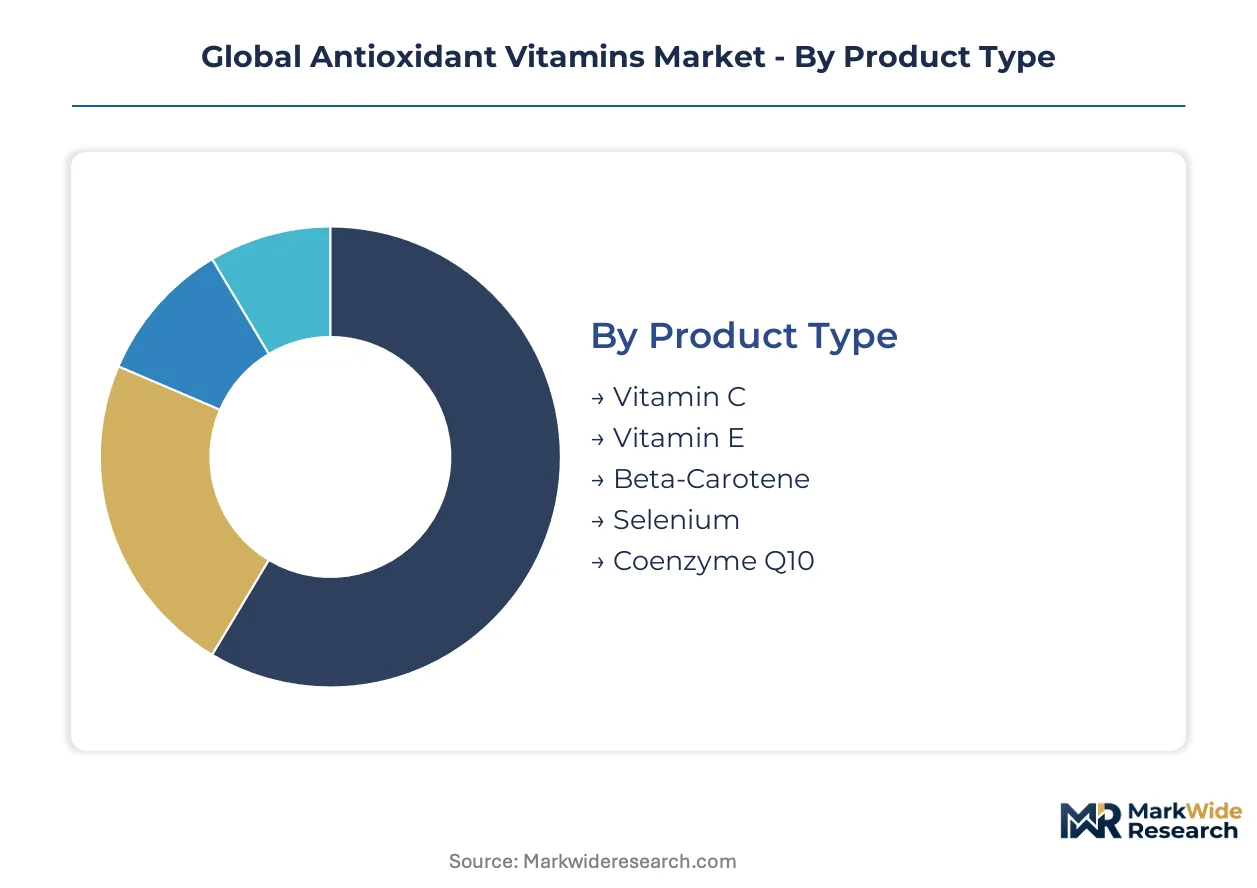
Antioxidant vitamins fragment across incompatible solubility profiles, delivery format preferences, and regulatory pathways that prevent unified manufacturing. Each segment carries distinct purity requirements, stability challenges, and customer procurement behaviors that shape supplier specialization.
Product Type:
Mature commodity vitamins anchor volume while mitochondrial-targeted compounds capture premium positioning.
- Vitamin C:Ascorbic acid operates as a water-soluble radical scavenger with established USP and EP monographs. Demand concentrates in India's FSSAI wheat flour fortification mandates and China's staple food programs, constrained by ethylene precursor volatility from petrochemical feedstocks.
- Vitamin E:Tocopherols function as lipid-soluble membrane protectors with synthetic and plant-derived sourcing bifurcation. Germany's specialized nutrition cluster around Frankfurt and Mannheim drives pharmaceutical-grade demand, limited by petroleum-based yield advantages over natural extraction.
- Beta-Carotene:Provitamin A carotenoid with dual cosmetic and nutritional applications.
- Selenium:Trace mineral antioxidant with narrow therapeutic window requiring precise dosing formats.
- Coenzyme Q10:Ubiquinone compound commanding cardiovascular and mitochondrial health premiums.
Vitamin C handles the majority of throughput; Coenzyme Q10 is the fastest mover on share.
Form:
Delivery technology is concentrating value in encapsulation specialists rather than commodity active ingredient suppliers.
- Capsules:Hard-shell gelatin or HPMC containers for powder and granule delivery. Sports nutrition channels in Germany favor vegetable-derived capsules for clean-label positioning.
- Tablets:Compressed powder matrices with established manufacturing economies. Conventional tablet share is compressing as softgels and liposomal formats displace shelf space in performance retail.
- Powders:Bulk active ingredients for institutional fortification and beverage applications. India's FSSAI edible oil premix procurement favors powder formats for blending efficiency.
- Softgels:Gelatin or plant-based shells enclosing liquid or suspension fills. Liposomal softgels extract value from bioavailability claims in direct-to-consumer wellness platforms.
- Gummies:Pectin or gelatin matrices with flavor masking for pediatric and adult compliance segments.
Powders handle the majority of throughput; softgels are expanding most quickly on share.
Application:
Regulatory fragmentation across jurisdictions forces separate validation batches and marketing language for each pathway.
- Dietary Supplements:Capsule, tablet, and powder formats for human nutritional intake. FDA NDI notifications and EFSA health claim substantiation create divergent compliance costs for multinational suppliers.
- Functional Foods:Fortified beverages, cereals, and dairy with stability challenges in aqueous matrices. EU Novel Food Catalogue classification determines ingredient approval pathways for emerging formulations.
- Personal Care:Topical antioxidant protection in emulsion and serum formulations. Liposomal Vitamin E penetrates prestige skincare as brands seek stability without compromising emulsion integrity.
- Pharmaceuticals:Parenteral and oral dosage forms requiring pharmacopeial-grade purity. USP, EP, and ChP monograph divergence complicates unified manufacturing footprints.
- Animal Nutrition:Feed additives for livestock oxidative stress management. Tightening veterinary antibiotic regulations in the EU and China are expanding tocopherol premix demand.
Dietary supplements handle the majority of throughput; animal nutrition is climbing the fastest on share.
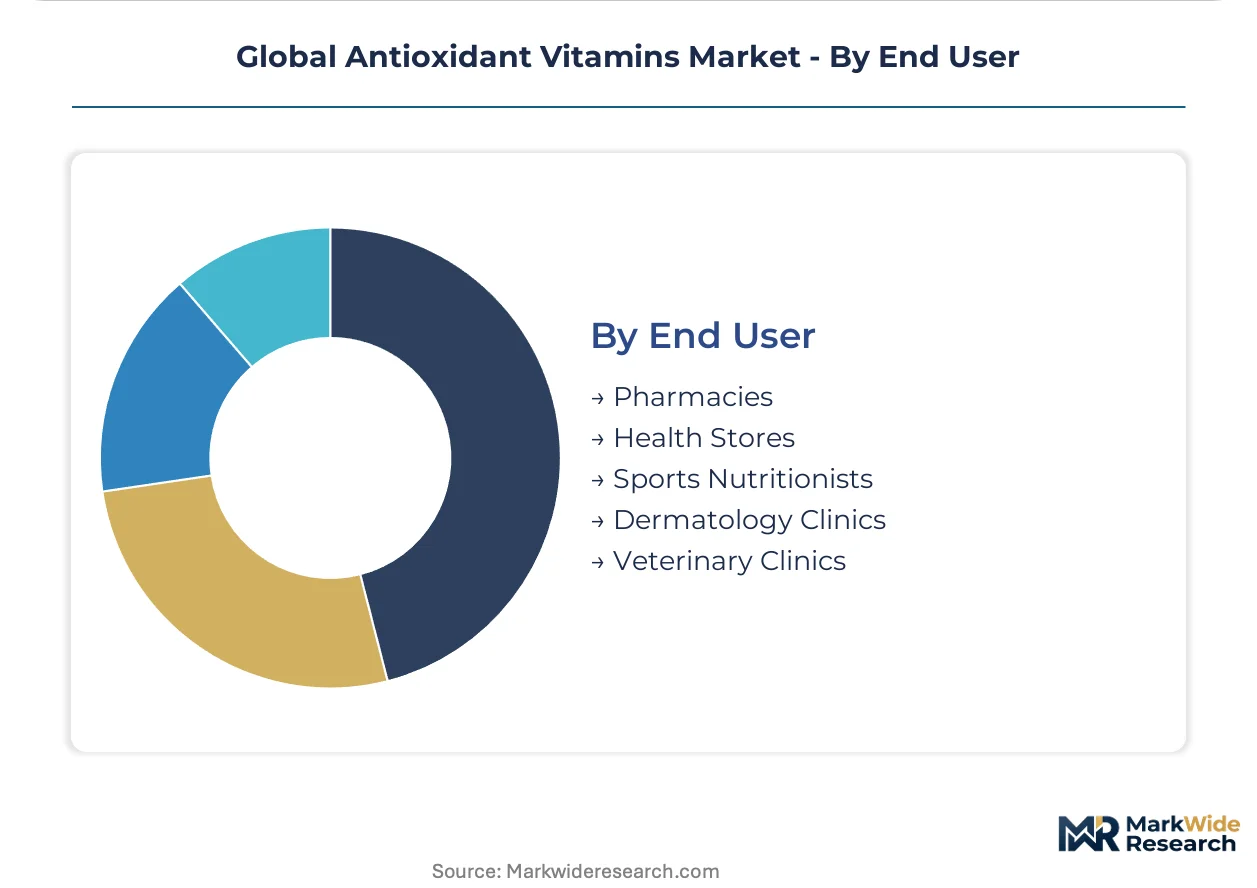
End User:
Channel specialization is fragmenting procurement patterns and technical partnership requirements.
- Pharmacies:Licensed retail with pharmacist consultation and reimbursement pathways. Germany's Mannheim cluster embeds encapsulation partners directly into pharmacy private-label development.
- Health Stores:Independent and chain retailers with natural and organic positioning. Clean-label petroleum substitution pressures concentrate demand for plant-derived tocopherols.
- Sports Nutritionists:Performance-focused retail and practitioner channels. Liposomal powders and softgels are displacing conventional tablets in this channel, concentrating value in format innovation.
- Dermatology Clinics:Medical aesthetic practices with prescription and professional-grade skincare. Prestige formulations favor liposomal Vitamin E for antioxidant protection without emulsion degradation.
- Veterinary Clinics:Companion and livestock health practitioners with feed additive prescriptions. China's NMPA Blue Hat registration extends 18-24 months for imported animal health formulations.
Pharmacies handle the majority of throughput; sports nutritionists are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports tocopherol concentrates to Germany's pharmaceutical-grade formulators, while India ships ascorbic acid premixes to Middle East fortification programs. This trade-flow corridor shapes regional specialization patterns across the antioxidant vitamins supply base.
Germany
Pharmaceutical-grade Vitamin E demand concentrates in the Frankfurt-Mannheim nutrition cluster, where DSM maintains synthetic biology fermentation capacity. EFSA health claim substantiation pathways under the EU Novel Food Catalogue reduce regulatory uncertainty for new entrants. Mannheim-based formulators embed liposome specialists directly into NPD workflows for pharmacy private-label development.
China
Domestic feed additive consumption absorbs expanding tocopherol output as livestock producers seek antibiotic alternatives under tightening veterinary regulations. NMPA Blue Hat registration extends 18-24 months for imported formulations, tying up working capital for foreign suppliers. The Yangtze River Delta houses ascorbic acid synthesis capacity anchored by petrochemical precursor integration.
India
FSSAI wheat flour and edible oil fortification mandates create institutional procurement channels for Vitamin C and Vitamin E premixes. The central food regulator's standards diverge from USP and EP pharmacopeial specifications, requiring separate validation batches. Gujarat-based processors supply powder formats to domestic blending operations and export markets.
United States
Sports nutrition channels drive liposomal softgel adoption in performance-focused retail, displacing conventional tablet formats. FDA New Dietary Ingredient notifications govern market access for emerging antioxidant formulations, creating compliance friction for novel delivery platforms. California-based direct-to-consumer wellness platforms accelerate bioavailability-claim positioning.
Brazil
Livestock oxidative stress management applications expand as producers adapt to EU veterinary export standards restricting antibiotic growth promoters. ANVISA's national health surveillance agency oversees feed additive registration timelines that lag European approval pathways. São Paulo-state nutrition premixers import concentrated actives for local formulation and distribution.
Global Antioxidant Vitamins Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into petrochemical-integrated synthesizers, plant-derived extractors, and encapsulation technology licensors. Three archetypes dominate: backward-integrated chemical conglomerates, synthetic biology fermentation specialists, and clean-label natural positioning players. Competitive moves concentrate on strategic partnerships with delivery-format innovators and capacity expansion in pharmaceutical-grade fermentation.
Among European chemical conglomerates, BASF SE anchors petrochemical-integrated Vitamin C synthesis. Koninklijke DSM N.V. represents synthetic biology fermentation specialists with high-purity tocopherol capacity. Kemin Industries exemplifies plant-derived extraction positioning against petroleum-based alternatives. These three occupy distinct competitive vectors without direct product overlap, reducing price-based confrontation.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Koninklijke DSM N.V. |
| DuPont de Nemours, Inc. |
| Kemin Industries, Inc. |
| Nutreco N.V. |
| Adisseo |
| Amway Corp. |
| Others |
Supply & Pricing Matrix
Petrochemical precursor volatility determines both pricing tier spreads and supply chain shape across antioxidant vitamin manufacturing. BASF SE's backward integration into ethylene and propylene feedstocks for Vitamin C synthesis exposes the broader market to refining capacity constraints, compressing margins on commodity grades while pharmaceutical-grade tocopherols command stability premiums.
Pricing Analysis
Format-generation pricing gaps separate liposomal and nano-dispersed delivery platforms from conventional tablets and unencapsulated powders. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications reflects purity specification divergence under USP, EP, and ChP monographs. Cost compression in commodity Vitamin C runs through ethylene price swings from Asian petrochemical complexes. Feed additive buyers exhibit highest price sensitivity, while dermatology clinics and sports nutritionists absorb premiums for bioavailability-claim formats.
Supply Chain Analysis
Export-control scrutiny over synthetic biology fermentation equipment limits capacity expansion for high-purity tocopherol production. China, India, and Germany anchor global supply, with the Yangtze River Delta housing ascorbic acid synthesis and Gujarat processing powder premixes for FSSAI fortification programs. Ethylene and propylene feedstocks, gelatin and HPMC capsule shells, and phospholipid encapsulation materials constitute critical input dependencies. Single-source vulnerability concentrates in microbial fermentation facilities for pharmaceutical-grade Vitamin E. Distribution runs through specialized nutrition clusters embedding encapsulation partners directly into formulator NPD workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward direct procurement from encapsulation technology providers, fragmenting traditional excipient distributor roles. Dietary supplement manufacturers in Germany's Frankfurt-Mannheim cluster now embed liposome specialists into development workflows, consolidating technical partnership leverage.
For Market Incumbents: Build regulatory certification moats around EFSA health claim substantiation and FDA New Dietary Ingredient notification pathways. BASF SE and Koninklijke DSM N.V. should deepen backward integration into petrochemical precursors and synthetic biology fermentation capacity respectively to defend against clean-label substitution pressures. Channel control through direct technical partnerships with sports nutrition brands protects margin position as format innovation displaces commodity active ingredient value.
For New Entrants and Emerging Players: India's FSSAI wheat flour and edible oil fortification mandates represent the most penetrable entry point for institutional premix procurement. Mitochondrial health positioning around Coenzyme Q10 offers premium tier access with lower capital barriers than commodity vitamin synthesis. Liposomal softgel contract manufacturing partnerships with Mannheim-based formulators provide go-to-market acceleration without captive fermentation investment.
For Investors and Strategic Acquirers: EFSA Novel Food Catalogue updates reshaping permissible marketing language for fortified products alter the acquisition landscape toward encapsulation technology licensors. Long-term viability centers on delivery format innovation rather than active ingredient synthesis across the analysis window. Target synthetic biology fermentation specialists and liposome technology providers with pharmaceutical-grade certification infrastructure. Monitor REACH authorization timelines for novel tocopherol analogues as inflection indicators for incumbent chemistry lock-in versus innovation pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Precursors | BASF SE secures ethylene supply continuity for Vitamin C synthesis against refining capacity constraints. |
| Synthetic Biology Fermentation Scale-Up | Koninklijke DSM N.V. expands high-purity tocopherol capacity for pharmaceutical-grade formulations. |
| Encapsulation Technology Licensing Partnerships | Direct technical collaboration with Mannheim formulators displaces traditional excipient distribution channels. |
| Clean-Label Plant-Derived Extraction Investment | Kemin Industries narrows petroleum-based tocopherol yield gaps through agricultural sourcing optimization. |
| Regulatory Certification Infrastructure Buildout | EFSA health claim substantiation and FDA NDI notification capabilities determine market access speed. |
Research Methodology
Desk research of pharmacopeial monograph databases, customs trade flows, and regulatory filing records preceded structured interviews with encapsulation technology specialists, dietary supplement formulators, feed additive procurement managers, and pharmaceutical-grade fermentation plant directors. Primary fieldwork validated secondary data from EFSA health claim registers, FDA NDI notifications, FSSAI fortification standards, and NMPA Blue Hat approval databases. Bottom-up volume modeling across product type, delivery format, and application segments triangulated against top-down trade flow analysis.
Fixed assumptions held petrochemical feedstock price volatility bands and regulatory approval timeline distributions constant across the projection horizon, while scenario analysis varied encapsulation technology adoption rates and clean-label substitution elasticities. Segmentation dimensions modeled include solubility profile, delivery format, purity grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical volume data adjusted for technology substitution patterns and fortification mandate implementation schedules. Industry-specific inputs incorporated livestock antibiotic regulation phase-out timelines and sports nutrition channel format displacement rates.
Practitioners should monitor REACH authorization bottlenecks for novel antioxidant derivatives and NMPA Blue Hat registration timeline extensions for early signals of supply chain friction. Forecasts reflect documented assumptions regarding encapsulation technology cost curves and regional fortification policy continuity. Material shifts in EU veterinary antibiotic regulations or India's FSSAI premix procurement standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Vitamin Yeast Market