
 Packaged Milkshake Market | 2026-2036
Packaged Milkshake Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Milkshake Market Analytics
Asset-light contract manufacturing and third-party co-packing arrangements is tilting competitive dynamics toward brands that outsource production rather than build owned facilities. Nestlé S.A. leverages its global dairy sourcing network to secure cost-advantaged milk powder inputs across multiple continents. Danone S.A. anchors its position through specialized probiotic and fermented milkshake variants that command shelf space in European health channels. FrieslandCampina competes via backward integration into dairy farming cooperatives, giving it captive supply of fresh milk for premium product lines.
Packaged milkshakes are commercially prepared, ready-to-drink beverages combining dairy milk or milk derivatives with flavoring agents, sweeteners, and stabilizers, typically homogenized and ultra-high-temperature processed to achieve shelf stability without refrigeration. The primary commercial purpose is delivering convenient, portion-controlled dairy-based refreshment through retail and away-from-home channels. Chocolate flavor variants dominate volume due to universal palate acceptance across age demographics, while coffee-flavored formulations are gaining fastest in food service accounts targeting adult caffeine-seeking consumers. Tetra Pack packaging captures margin pools through extended ambient shelf life and reduced cold-chain logistics costs, particularly in emerging markets with underdeveloped refrigerated distribution.
The FDA enforces nutrition labeling and allergen declaration standards that dictate reformulation timelines for US-distributed products, while the EMA and national European regulators coordinate dairy hygiene and additive approvals under EU-wide frameworks. BIS certification requirements in India mandate specific milk solids content thresholds that filter out substandard imports and protect domestic dairy cooperatives. Stakeholders must monitor evolving sugar taxation proposals across multiple jurisdictions and assess whether reformulation investments or geographic portfolio shifts offer superior returns.
Market Dynamics
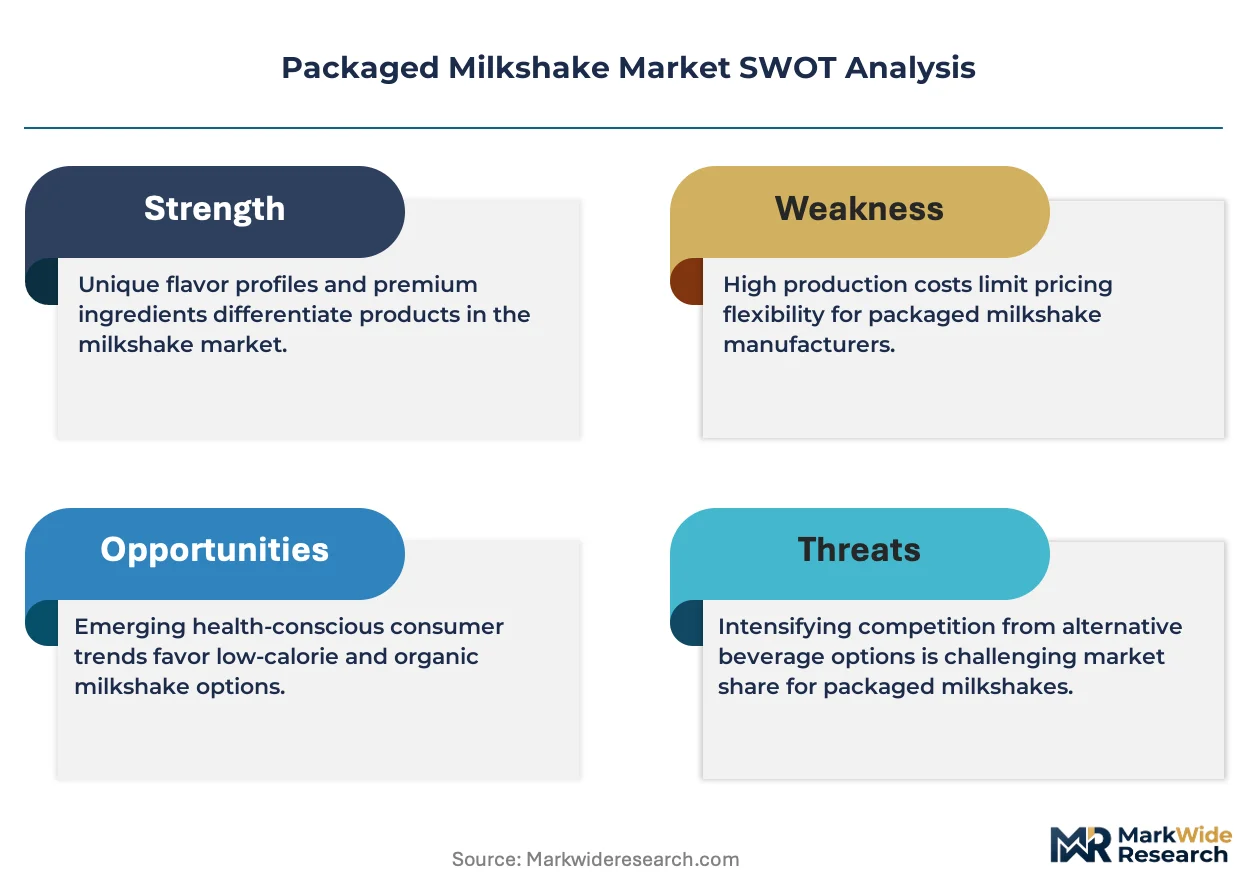
The FDA's updated nutrition labeling requirements for added sugars are forcing rapid reformulation across US product portfolios, while cold-chain infrastructure gaps in emerging markets simultaneously compress margin structures and limit geographic expansion for temperature-sensitive dairy formulations.
Growth Catalysts
- Convenience Store Channel Expansion:Quick-service restaurants and c-store operators are dedicating incremental shelf space to ready-to-drink dairy beverages, creating dedicated cooler sections that normalize impulse purchase behavior.
- EU Dairy Hygiene Framework:Coordinated EMA and national European approvals under unified hygiene standards reduce cross-border compliance friction, enabling standardized production runs across multiple member states.
- UHT Processing Technology:Ultra-high-temperature sterilization extends ambient shelf life without refrigeration, unlocking distribution into markets with underdeveloped cold-chain networks.
Market Restraints
- Milk Powder Input Volatility:Global dairy commodity markets exhibit price swings that compress blender margins during procurement cycles, particularly affecting contract manufacturers without captive supply.
- Sugar Taxation Proposals:Multiple jurisdictions are advancing levies on added sugars that threaten profitability of traditional formulations without costly reformulation investments.
- Plant-Based Substitution:Oat and almond milk alternatives are capturing shelf space in premium retail channels, displacing dairy-based options among health-conscious consumer segments.
Strategic Opportunities
- Indian Market Penetration:BIS certification thresholds for milk solids content protect domestic cooperatives but create partnership opportunities for compliant foreign entrants via joint ventures with established dairy networks.
- Probiotic-Fermented Convergence:Combining traditional milkshake formats with live culture fermentation technologies opens positioning in European health and pharmacy channels.
- Direct-to-Consumer Subscription:E-commerce platforms enable recurring revenue models that bypass traditional retail slotting fees and build direct consumer relationships.
Industry Challenges
- Reformulation Timeline Compression:FDA-mandated label changes require simultaneous R&D, sensory testing, and packaging updates that strain cross-functional coordination.
- Co-Packer Quality Consistency:Asset-light manufacturers depend on third-party facilities where batch-to-batch variation risks brand equity erosion.
- Allergen Cross-Contamination Protocols:Shared production lines demand rigorous cleaning validation that extends changeover times and reduces effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Milkshake Market |
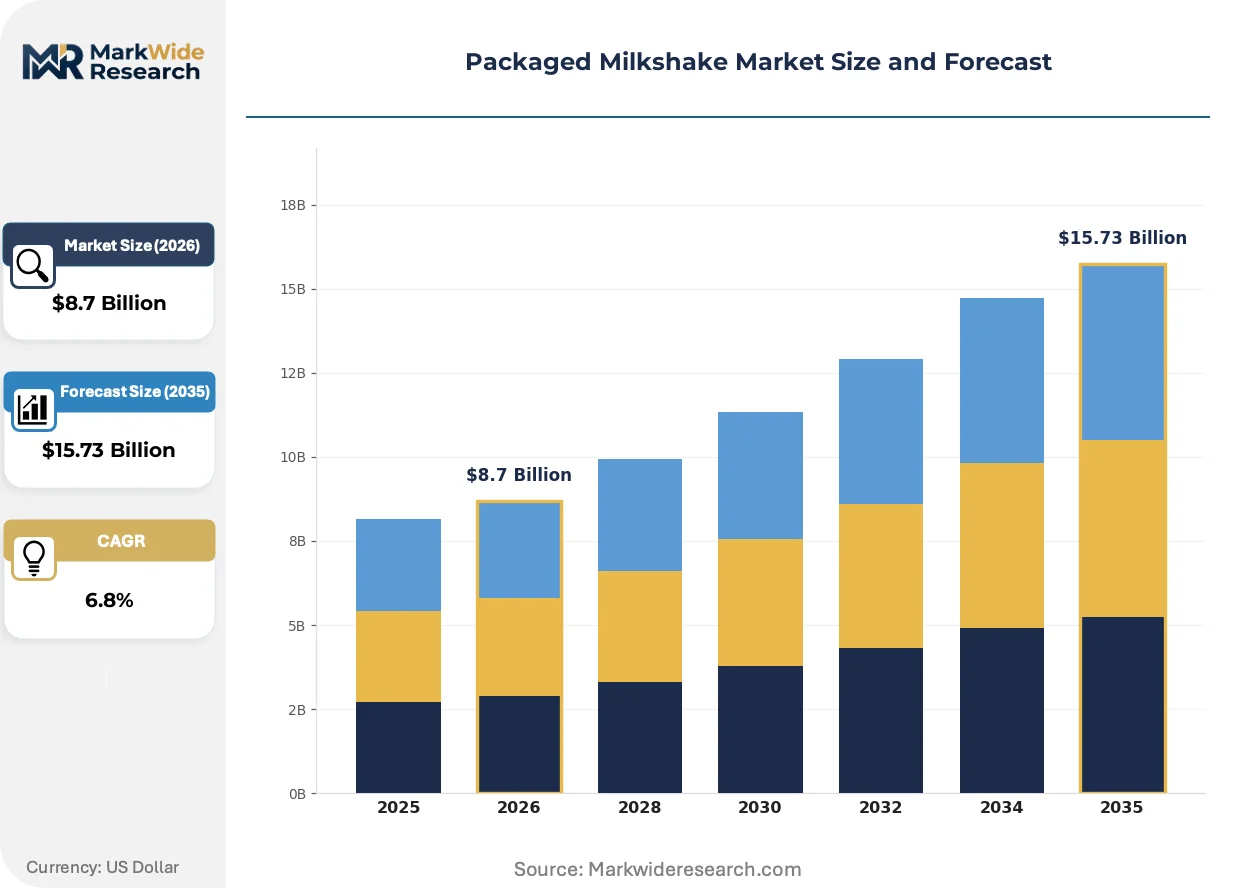
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Strawberry, Vanilla, Coffee End User: Retailers, Food Service, Online Stores, Vending Machines Packaging Type: Bottles, Pouches, Tetra Packs, Cans Size: Single Serve, Multi Serve, Family Pack, Bulk |
| Companies Covered | Nestlé S.A., Danone S.A., The Hershey Company, Arla Foods amba, Müller Group, FrieslandCampina, Dean Foods, Dairy Farmers of America, GCMMF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Milkshake Market Evolving Landscape
Active reformulation is reshaping competitive positioning as stakeholders balance sensory fidelity against regulatory compliance, while packaging technology and distribution models undergo parallel transformation to capture margin in fragmented consumption occasions.
Clean-label stabilizer systems are hybridizing traditional milkshake texture with reduced additive declarations. Mid-tier beverage brands are adopting these systems fastest to bridge premium positioning with mainstream price points. This convergence is compressing the market share of legacy formulations dependent on artificial thickeners.
EU Green Deal implementation is tightening packaging recyclability mandates that affect Tetra Pak and multilayer carton designs. Manufacturers are accelerating fiber-based alternatives and monomaterial structures to preempt compliance deadlines. Dairy beverage categories with premium positioning face disproportionate cost pressure given their reliance on complex barrier packaging.
Food service accounts are unbundling beverage procurement from bundled supplier contracts, creating direct purchasing relationships with specialized dairy blenders. Independent coffee chains and regional QSR operators are leading this disintermediation to secure customized flavor profiles. This pattern is most visible in United States metropolitan markets where operator concentration supports fragmented sourcing.
Packaged Milkshake Market Segmentation
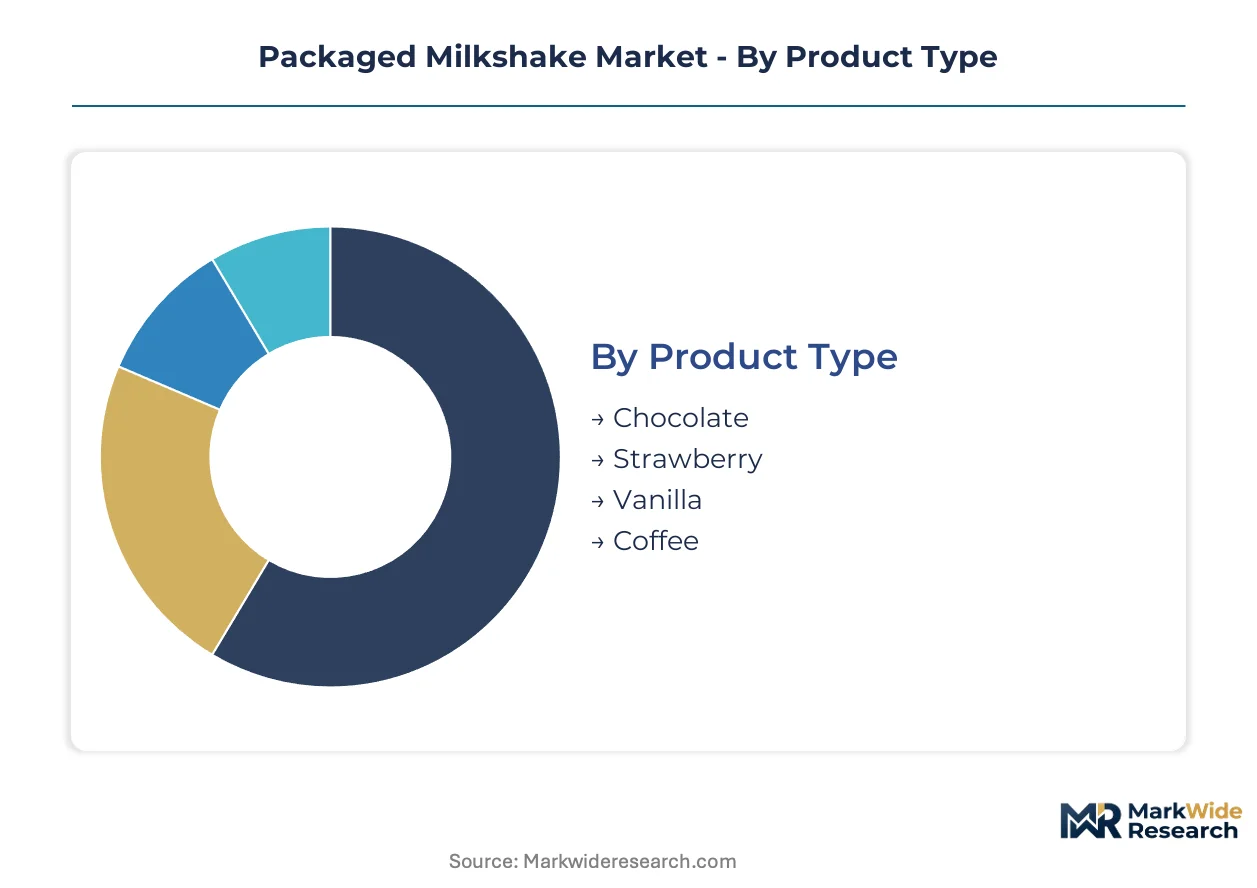
Segmentation in packaged milkshapes reveals how formulation, channel, and format choices determine margin capture and shelf placement. Manufacturers align production configurations to specific demand pockets rather than pursuing undifferentiated volume.
Product Type:
After-sales intensity varies sharply across flavor portfolios, with chocolate and vanilla requiring minimal consumer education while coffee and probiotic variants demand ongoing quality assurance and freshness monitoring.
- Chocolate:Cocoa-based formulations leverage universal palate acceptance across age demographics. United States convenience stores drive volume through dedicated cooler placement and impulse-oriented packaging graphics. Reformulation pressures from FDA added-sugar labeling are compressing margins for legacy recipes.
- Coffee:Caffeine-fortified dairy blends target adult consumption occasions in food service channels. Metropolitan United States coffee chains are disintermediating traditional distributors to secure customized roast profiles and viscosity specifications. Cold-chain requirements limit geographic expansion for temperature-sensitive formulations.
- Strawberry:Fruit-flavored variants rely on natural or nature-identical flavor systems to achieve color stability through shelf life.
- Vanilla:Classic profiles serve as formulation base for private-label programs and co-packing arrangements.
By volume, chocolate leads. By growth pace, coffee is ahead.
End User:
Cost tier stratification separates premium direct-to-consumer subscriptions from commodity vending placements, with food service occupying the intermediate value band.
- Food Service:Quick-service restaurants and independent coffee chains procure through direct relationships with specialized dairy blenders. United States metropolitan operators are unbundling beverage procurement from bundled supplier contracts to secure customized flavor profiles. Tetra Pack ambient formats reduce cold-chain logistics burdens for regional distribution.
- Retailers:Supermarkets and convenience stores command slotting fees and promotional allowances that compress blender net revenue. United States c-store operators are expanding dedicated cooler sections for ready-to-drink dairy beverages. UHT processing enables ambient shelf placement with extended code dates.
- Online Stores:E-commerce platforms enable subscription revenue models that bypass traditional retail gatekeepers and build direct consumer relationships.
- Vending Machines:Ambient-stable formats dominate procurement specifications for unattended retail channels with limited refrigeration.
Food service channels capture the steepest expansion trajectory as operator disintermediation accelerates.
Packaging Type:
Margin concentration tracks barrier complexity, with multilayer cartons commanding premium positioning against commodity bottle formats.
- Tetra Packs:Multilayer carton structures combine paperboard, aluminum, and polymer barriers to achieve ambient shelf stability without refrigeration. Emerging markets with underdeveloped cold-chain infrastructure favor this format for distribution economics. EU Green Deal recyclability mandates are accelerating fiber-based alternative development.
- Bottles:PET and HDPE formats dominate refrigerated channel placement in developed markets with established cold-chain networks. United States retail coolers favor transparent bottles for visual appetite appeal. Lightweighting initiatives reduce resin content per unit.
- Pouches:Flexible film structures offer portion control and reduced shipping cube for e-commerce fulfillment.
- Cans:Aluminum formats serve food service fountain systems and vending applications requiring mechanical durability.
Tetra Packs lead by installed capacity; bottles are climbing the fastest as refrigerated channel expansion continues.
Size:
Application context determines format selection, with on-the-go occasions favoring single units and household replenishment driving larger pack configurations.
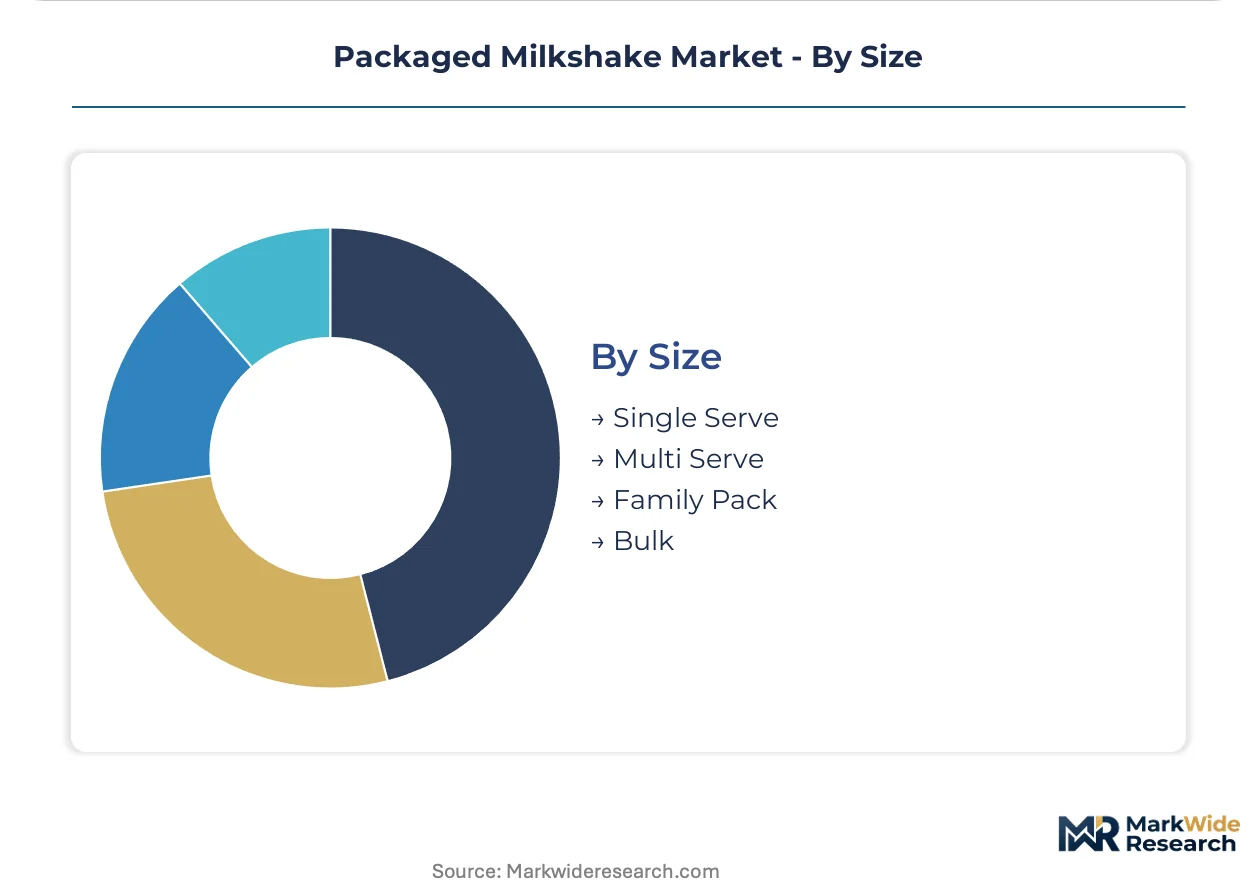
- Single Serve:Portion-controlled formats target impulse purchase occasions in convenience stores and vending channels. United States on-the-go consumption patterns normalize premium pricing per fluid ounce. UHT processing enables ambient distribution without refrigeration dependency.
- Family Pack:Multi-unit configurations serve household replenishment occasions in supermarket channels. Value positioning per ounce competes with private-label alternatives. Refrigerated distribution requirements limit geographic reach for fresh formulations.
- Multi Serve:Intermediate formats bridge individual and household consumption contexts.
- Bulk:Food service fountain systems and institutional accounts procure concentrate or ready-to-dispense volumes.
Single serve dominates by transaction frequency; family packs are gaining share fastest as at-home consumption occasions expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA-mandated added-sugar labeling reforms are accelerating product reformulation timelines across United States distribution networks, while BIS certification thresholds in India and EU Green Deal packaging mandates are redirecting capital toward compliance-ready production configurations.
United States
Convenience store operators are expanding dedicated cooler sections for ready-to-drink dairy beverages, normalizing impulse purchase behavior in metropolitan corridors. The FDA enforces updated nutrition labeling standards that dictate reformulation priorities for added-sugar declarations. Chicago and Dallas-Fort Worth clusters host specialized dairy blender networks serving disintermediated food service accounts.
Germany
Specialized probiotic and fermented milkshake variants command shelf space in health and pharmacy channels across Bavaria and North Rhine-Westphalia. Coordinated EMA and national approvals under unified EU hygiene standards reduce cross-border compliance friction for standardized production runs. The Munich-Stuttgart corridor anchors dairy cooperative processing infrastructure for premium ambient-stable formulations.
India
Domestic dairy cooperatives leverage BIS certification thresholds for milk solids content to filter substandard imports and protect market position. The FSSAI coordinates national food safety standards alongside state-level dairy development boards. Gujarat and Maharashtra industrial clusters concentrate UHT processing capacity for Tetra Pack distribution into tier-two cities with limited cold-chain reach.
Brazil
ANVISA pharmaceutical and food safety frameworks govern additive approvals and dairy hygiene standards for packaged beverage manufacturing. São Paulo and Minas Gerais states concentrate dairy processing infrastructure serving southeast corridor retail expansion. Regional blender networks are adapting formulations to preempt municipal sugar taxation proposals advancing in southern state legislatures.
United Kingdom
London and Southeast England metropolitan markets drive on-the-go consumption patterns for single-serve ambient formats. The Food Standards Agency enforces allergen declaration and dairy hygiene protocols aligned with post-EU regulatory frameworks. Midlands-based co-packing facilities are capturing contract manufacturing volume from brands pursuing asset-light production strategies.
Packaged Milkshake Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base separates into dairy cooperative-backed integrators, multinational beverage conglomerates with global sourcing networks, and regional contract manufacturers serving private-label programs. Two dominant competitive moves are reshaping positions: strategic partnerships with emerging market dairy cooperatives to secure captive milk powder supply, and portfolio diversification into probiotic-fermented convergence formats targeting pharmacy channel placement.
Within the multinational conglomerate tier, Nestlé S.A. and Danone S.A. exemplify divergent sourcing strategies—one leveraging global dairy powder networks across multiple continents, the other anchoring position through specialized fermentation technologies. FrieslandCampina occupies a cooperative-integrated position, representing backward integration into dairy farming structures that deliver fresh milk inputs for premium line differentiation. These three entities collectively illustrate how supply configuration and channel specialization determine competitive positioning.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| The Hershey Company |
| Arla Foods amba |
| Müller Group |
| FrieslandCampina |
| Dean Foods |
| Dairy Farmers of America |
| GCMMF |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Frankfurt rail corridor shapes cost dynamics for milk powder imports into European processing hubs, concentrating supply-side leverage among Dutch dairy cooperatives while downstream price differentiation reflects cold-chain logistics burdens and certification tier.
Pricing Analysis
Certification tier creates the primary spread between commodity and pharmacy-grade formulations. Three-tier pricing structure across premium probiotic, standard UHT ambient, and economy vending formats dominates transaction models. Pricing pressure stems from FDA-mandated added-sugar reformulation investments that compress blender margins. Food service accounts exhibit lowest price sensitivity due to customized flavor procurement, while vending channel operators demand economy positioning.
Supply Chain Analysis
Milk powder feedstock concentrates in New Zealand, the Netherlands, and India as dominant sourcing nodes. Production draws from skim milk powder, cocoa solids, and specialized probiotic cultures as critical inputs. Single-source vulnerability in global dairy commodity markets threatens margin stability during procurement cycles. Distribution runs through Tetra Pak ambient networks in emerging markets and refrigerated cold-chain infrastructure in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across consumption occasions creates niche entry points as on-the-go demand diverges from at-home replenishment patterns, rewarding specialized positioning over undifferentiated volume.
For Market Incumbents: Insulate premium positioning through captive fresh milk supply via cooperative backward integration, while accelerating clean-label reformulation to preempt FDA compliance deadlines. Plant-based substitution threats in health channels demand probiotic-fermented portfolio expansion to defend pharmacy shelf access. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure to bypass retail slotting fee structures, targeting metropolitan United States households with customized flavor profiles. White-space penetration in Indian tier-two cities via BIS-compliant joint ventures with Gujarat dairy networks offers fastest geographic expansion. For Investors and Strategic Acquirers: Asset-light contract manufacturers with established co-packer quality systems represent priority acquisition targets for beverage conglomerates seeking production flexibility. Long-term viability hinges on reformulation agility across sugar taxation jurisdictions; monitor municipal levy adoption in southern Brazilian states as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Probiotic-Fermented Convergence | Opens pharmacy channel placement in Germany and health retail in France. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and builds recurring revenue in United States. |
| Cooperative Joint Venture in India | Secures BIS-compliant milk solids sourcing for Tetra Pack distribution expansion. |
| Clean-Label Reformulation Investment | Preempts EU Green Deal packaging mandates and FDA added-sugar labeling. |
| Food Service Disintermediation | Captures customized procurement relationships with Chicago and Dallas-Fort Worth operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across dairy cooperative managers, beverage brand managers, food service procurement directors, and Tetra Pack packaging engineers. Secondary validation drew from FDA labeling guidance documents, EU dairy hygiene framework directives, BIS certification standards, and FSSAI regulatory filings. Bottom-up volume modeling triangulated against top-down category spend estimates.
Calibration against historical volume trajectories and regulatory milestone timing anchored projection reliability across the analysis window. Segmentation dimensions encompassed flavor variant, end-user channel, packaging format, and geographic regulatory cluster. CAGR derivation synthesized input cost elasticity, channel expansion rates, and reformulation investment cycles as industry-specific forecast inputs.
Stress conditions across milk powder commodity volatility, sugar taxation adoption timelines, and cold-chain infrastructure development gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against Nielsen retail audit velocity data and customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Dairy Beverages Market
Beverages
Smoothies Market
Beverages
Detox Drinks Market
Beverages
Popping Bobas Market
Beverages
Europe Juices Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
North America Energy Drink Market
Beverages
Global Bottled Water Market
Beverages
South America Bottled Water Market
Beverages
Crystal Boba Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Foaming Creamer Market