
 US and Canada Premium Bottled Water Market | 2026-2036
US and Canada Premium Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
US and Canada Premium Bottled Water Market Insights
Asset-light distribution partnerships and third-party logistics leasing is reshaping competitive entry barriers for emerging premium water brands. CORE Nutrition LLC leverages direct-to-consumer subscription infrastructure to sustain recurring revenue without captive bottling assets. Danone Waters of America anchors its position through controlled spring-source agreements in the French Alps, while Voss USA competes via glass-bottle positioning in hotel minibars and fine-dining channels.
US and Canada Premium Bottled Water comprises purified, spring, or mineral water sold at price premiums above standard bottled water, typically featuring total dissolved solids above 250 mg per liter, specific geological source provenance, and packaging designed for conspicuous consumption. The category serves hydration, status signaling, and health-conscious substitution for alcoholic or sugary beverages across commercial and residential settings. Still water dominates volume throughput in household and office channels, while sparkling variants command superior margin pools in restaurant and hotel end uses. Glass bottle packaging captures the highest unit economics despite freight cost penalties, whereas plastic formats drive mass-market penetration through supermarket and convenience store distribution.
FDA enforces bottled water quality standards under 21 CFR 165.110, while Health Canada regulates through the Food and Drugs Act and Guidelines for Canadian Drinking Water Quality, creating dual compliance architectures for cross-border suppliers. EPA Safe Drinking Water Act provisions influence source-protection requirements that premium brands use as marketing differentiation. State-level extended producer responsibility frameworks in California and British Columbia are adding packaging recovery cost layers that stakeholders must model into pricing architecture. Provenance verification systems and real-time supply chain traceability investments will separate defensible premium positions from commodity-adjacent competitors.
Market Dynamics
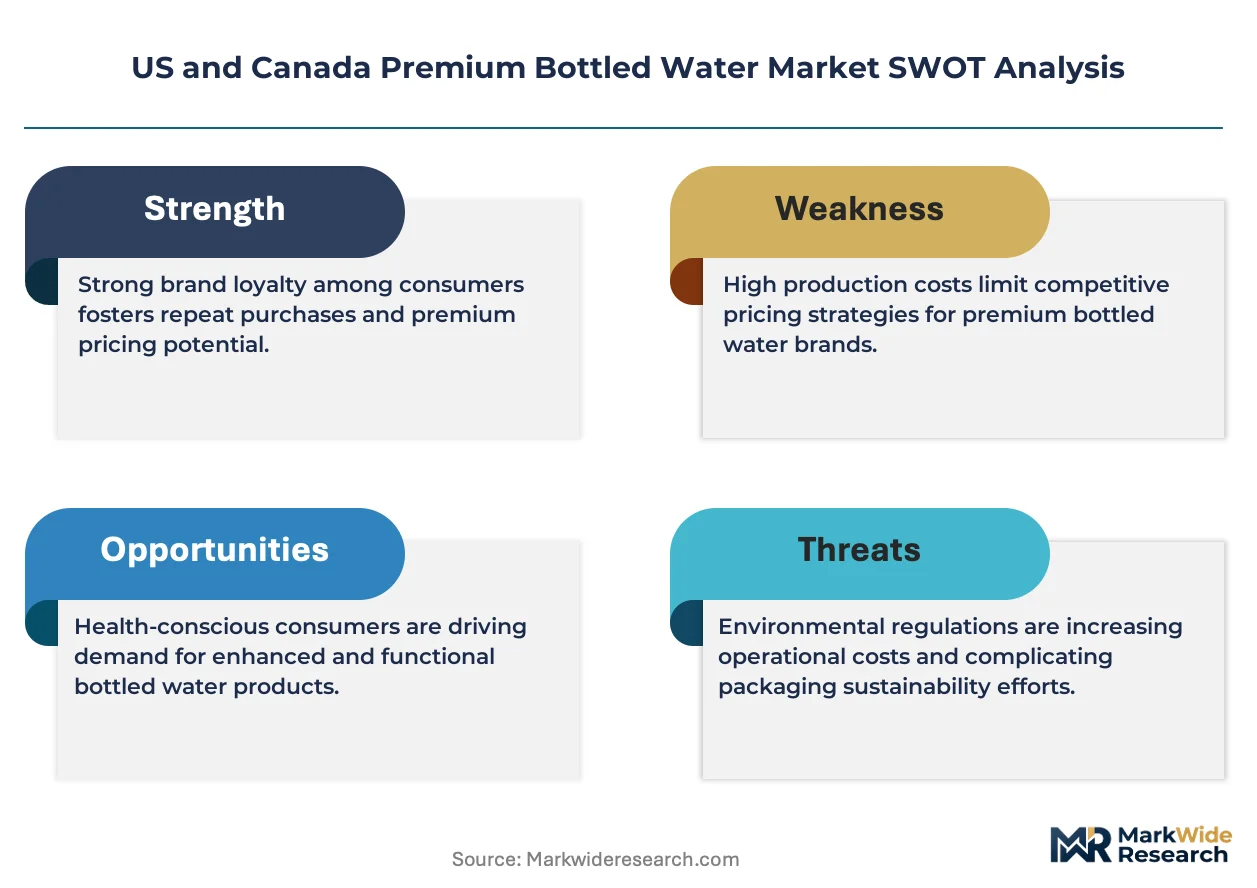
Extended producer responsibility frameworks in California and British Columbia are forcing premium water brands to internalize packaging recovery costs, compressing margin structures and accelerating format innovation toward aluminum and refillable glass systems.
Growth Catalysts
- Hotel and fine-dining channel expansion:Luxury hospitality properties in Miami and Vancouver now stock premium still and sparkling variants as standard amenity offerings, creating predictable offtake agreements.
- FDA source identification mandates:Tightening 21 CFR 165.110 compliance obligations are advantaging established players with captive spring-source documentation and traceability infrastructure.
- Coastal metropolitan demand concentration:Consumer willingness to pay for provenance-branded water in California and British Columbia exceeds interior markets by significant margins.
Market Restraints
- Glass freight cost penalties:Weight-based shipping surcharges erode unit economics for premium packaging formats despite superior shelf price realization.
- Cross-border supply chain dual compliance:Simultaneous FDA and Health Canada regulatory architectures create documentation friction and inspection delays at Detroit and Buffalo corridor crossings.
- Single-use plastic substitution threat:Point-of-use filtration systems in corporate offices and high-end residential buildings displace recurring bottled water purchases.
Strategic Opportunities
- Direct-to-consumer subscription infrastructure:Recurring revenue models bypass retail slotting fees and build proprietary customer data assets for cross-selling.
- Real-time supply chain traceability:Blockchain-verified provenance systems differentiate defensible premium positions from commodity-adjacent competitors.
- Sparkling variant penetration in residential channels:Home carbonation device compatibility and mixer-cocktail substitution applications remain underdeveloped relative to restaurant and hotel deployment.
Industry Challenges
- Source protection and aquifer management expertise:Hydrogeological assessment capabilities and long-term spring stewardship protocols require specialized talent scarce in beverage marketing organizations.
- Extended producer responsibility compliance timeline:California and British Columbia packaging recovery mandates demand capital deployment into reverse logistics systems with uncertain cost recovery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Canada Premium Bottled Water Market |
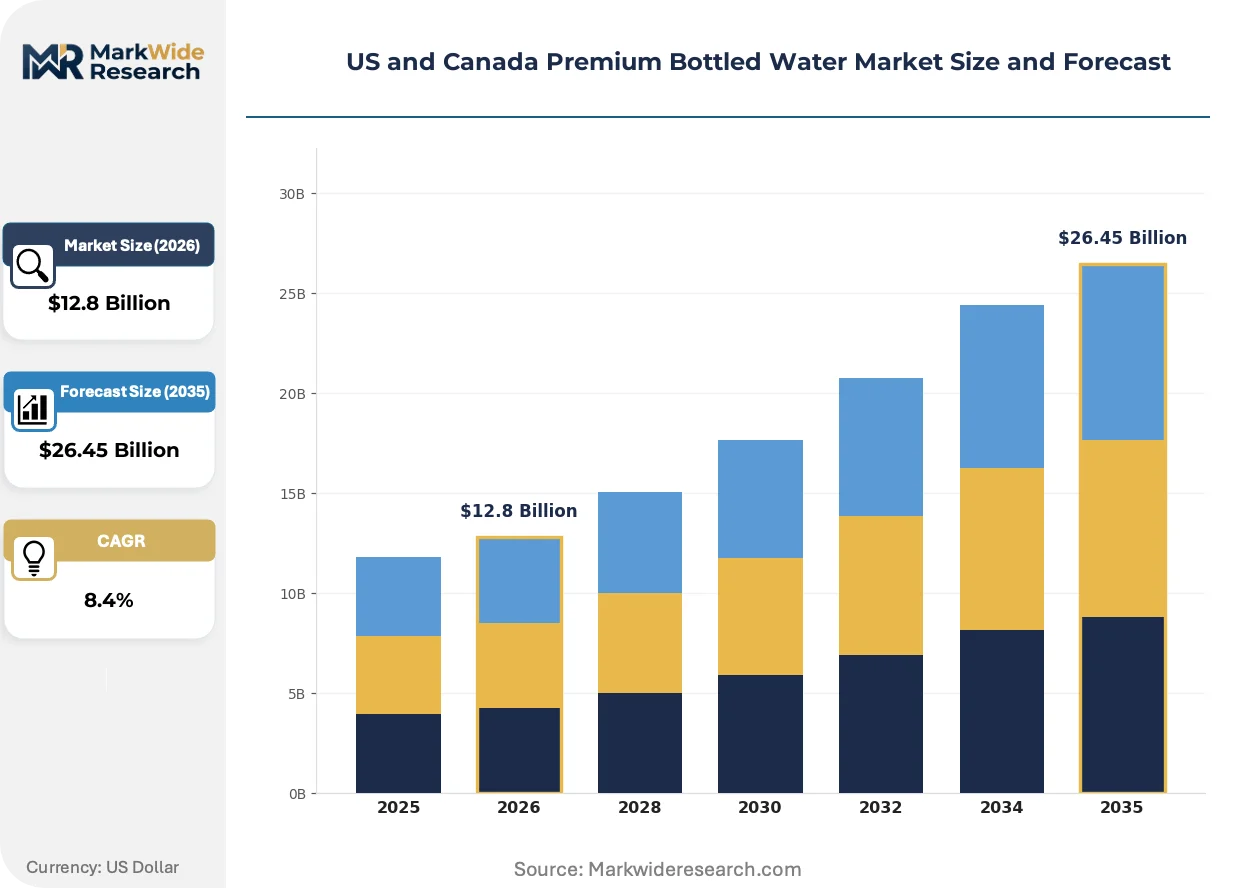
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling, Still, Flavored, Functional Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Others Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Restaurants End User: Households, Offices, Hotels, Gyms |
| Companies Covered | Perrier International, CORE Nutrition LLC, Danone Waters of America (Evian), Voss USA, Inc., The Coca-Cola Company, FIJI Water Company LLC, Acqua Panna, Icelandic Glacial, Inc., Sanpellegrino S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Canada Premium Bottled Water Market Trends and Innovations
Packaging material science, regulatory traceability mandates, and channel-specific consumption rituals are converging to reshape competitive differentiation in premium water. These forces reward capital investment in provenance verification and penalize undifferentiated volume plays.
Blockchain-enabled batch tracking is digitizing end-to-end supply chain documentation from alpine spring extraction through retail shelf placement. Premium hospitality buyers in Vancouver and Miami now require real-time provenance verification as a procurement precondition. This technology is digitizing quality assurance workflows while compressing the timeline for contamination response and recall containment.
Health Canada's Guidelines for Canadian Drinking Water Quality are tightening mineral content disclosure thresholds for imported premium waters. Cross-border suppliers must now maintain dual analytical certification laboratories to satisfy divergent testing protocols. British Columbia and Ontario retail channels are most affected, with distributors accelerating investment in in-house quality assurance infrastructure.
Corporate procurement departments are consolidating beverage supplier relationships into single-source contracts with sustainability reporting obligations. Premium water brands must now deliver Scope 3 emissions documentation and packaging recovery certificates alongside product. This behavioral shift is most visible in California technology sector headquarters, where procurement teams prioritize vendors with closed-loop aluminum programs over traditional glass suppliers.
US and Canada Premium Bottled Water Market Segmentation
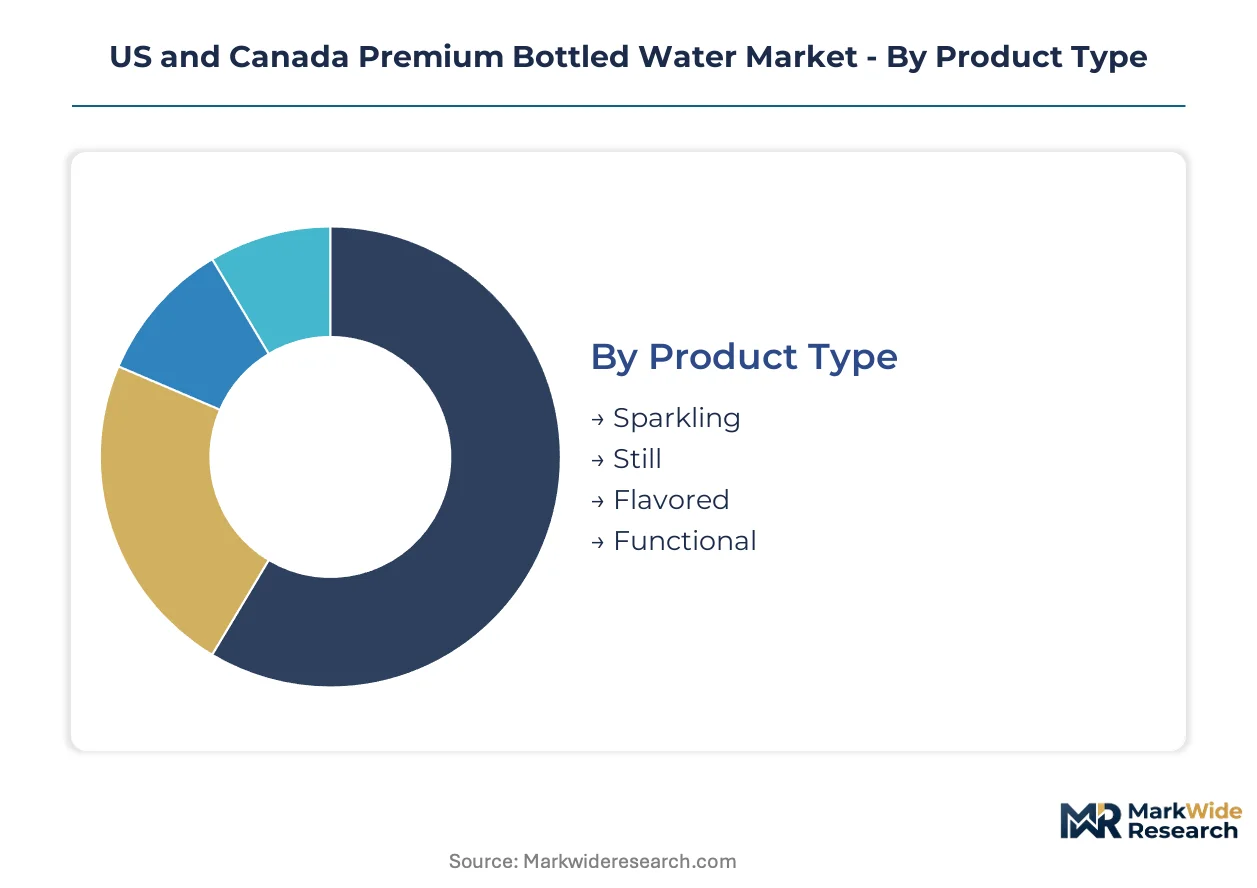
Premium water brands must align product formats, packaging investments, and channel strategies with distinct consumption rituals across still versus sparkling occasions. Segmentation discipline separates volume-scalable positions from margin-dominant niches in this cross-border market.
Product Type:
Still water turns inventory fastest through household bulk purchasing, while sparkling and functional variants exhibit longer purchase cycles tied to occasion-based consumption.
- Still:Un-carbonated spring or mineral water with total dissolved solids above 250 mg per liter serves daily hydration needs in California and British Columbia households. Bulk case formats through supermarket channels drive the highest absolute volume throughput in the category.
- Sparkling:Naturally or artificially carbonated variants command superior per-liter economics in Miami and Vancouver hotel minibars and fine-dining beverage programs. Glass bottle presentation and mixer compatibility sustain price premiums despite freight cost penalties.
- Flavored:Essence-infused still or lightly carbonated waters target health-conscious substitution for sugary beverages in office and gym channels.
- Functional:Electrolyte-enhanced or pH-adjusted variants serve athletic recovery and wellness positioning in premium gym chains and direct-to-consumer subscription models.
Still water anchors the volume base while sparkling gains share at the steepest rate.
Packaging Type:
Material selection maps directly to margin architecture, with freight-intensive formats concentrating in coastal corridors where consumer willingness to pay absorbs logistics premiums.
- Plastic Bottles:PET formats dominate supermarket and convenience store distribution through lower unit costs and lighter shipping weights. California extended producer responsibility mandates are compressing margin structures and accelerating lightweighting investments.
- Glass Bottles:Premium presentation standard in Vancouver and Miami hospitality channels delivers superior shelf price realization despite weight-based freight surcharges. Refillable deposit systems in British Columbia create closed-loop infrastructure requirements.
- Tetra Packs:Aseptic carton formats serve institutional and office channels seeking reduced plastic exposure with ambient storage stability.
- Others:Aluminum cans and paper-based alternatives emerge in sustainability-focused procurement programs, particularly among California technology sector headquarters.
Plastic bottles carry the volume base while aluminum and refillable glass systems expand most quickly under regulatory pressure.
Distribution Channel:
Channel mix determines working capital intensity, with direct-to-consumer subscriptions offering predictable cash conversion versus retail slotting fee burdens.
- Supermarkets:Mass-market penetration depends on trade promotion spending and shelf placement fees in California and Ontario retail corridors. Still water in plastic formats dominates this channel.
- Convenience Stores:Single-serve impulse purchases concentrate in urban corridors and highway corridors, with flavored and functional variants gaining space.
- Online Retailers:Direct-to-consumer subscription infrastructure builds proprietary customer data assets and bypasses retail margin stacking. CORE Nutrition LLC leverages this model for recurring revenue without captive bottling assets.
- Restaurants:Fine-dining and hotel beverage programs in Miami and Vancouver require real-time provenance verification and glass bottle presentation as procurement preconditions.
Supermarkets anchor the volume base while online retailers climb the fastest through subscription model adoption.
End User:
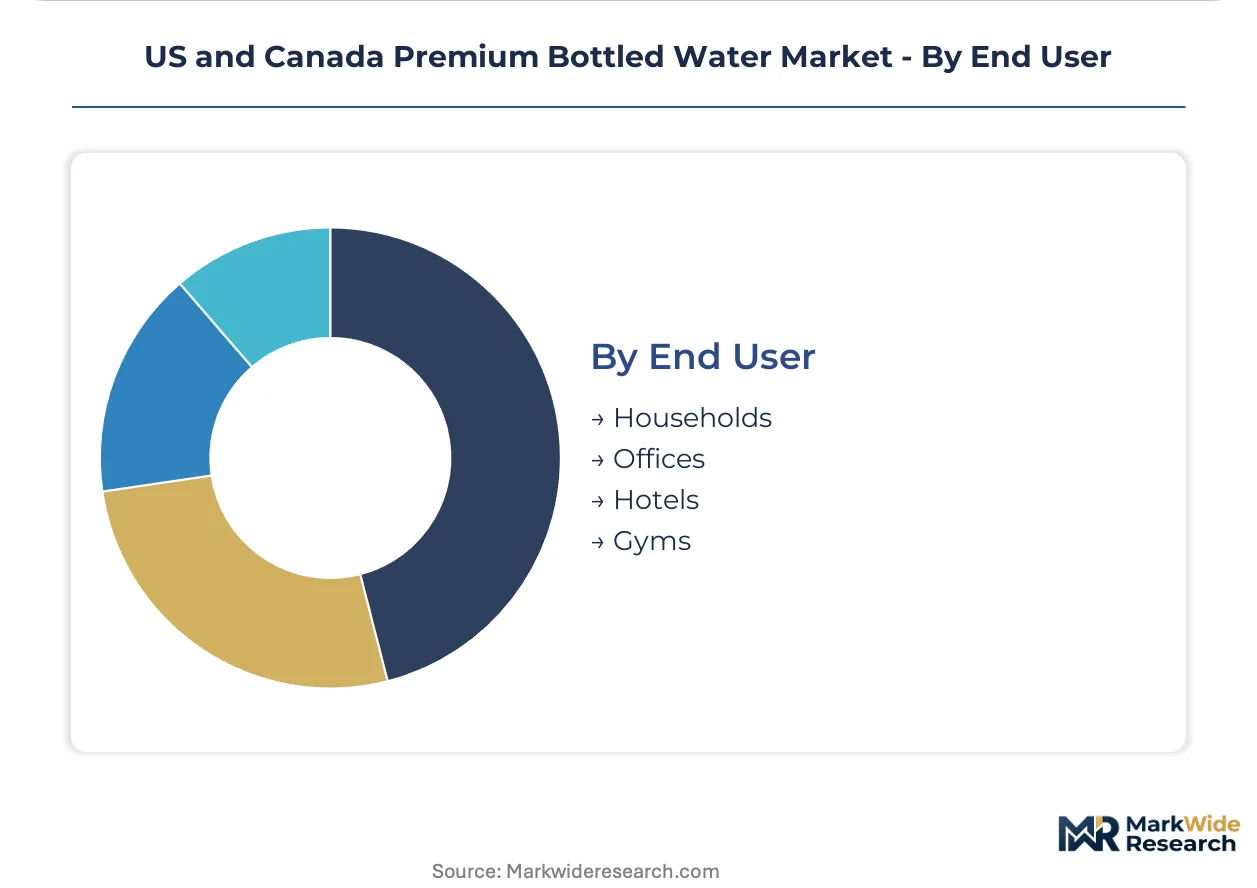
User segments diverge sharply in purchase frequency, with household bulk buying contrasting against hotel amenity replacement cycles and gym single-serve patterns.
- Households:Residential consumption in California and British Columbia concentrates in still water case purchases through supermarket and online channels. Home carbonation device compatibility remains underdeveloped for sparkling variants.
- Offices:Corporate procurement consolidation favors single-source contracts with sustainability reporting obligations, prioritizing closed-loop aluminum programs over traditional glass in technology sector headquarters.
- Hotels:Luxury hospitality properties in Miami and Vancouver stock premium still and sparkling variants as standard amenity offerings, creating predictable offtake agreements with provenance documentation requirements.
- Gyms:Athletic and wellness positioning drives functional water demand in premium fitness chains, with single-serve plastic and aluminum formats dominating.
Households anchor the volume base while hotels and offices gain share through procurement consolidation and sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury hospitality procurement teams in Miami and Vancouver anchor premium water demand through predictable offtake agreements. Coastal metropolitan corridors concentrate consumer willingness to pay for provenance-branded water above interior markets.
California
Silicon Valley technology sector headquarters consolidate beverage procurement into single-source contracts with sustainability reporting obligations. California extended producer responsibility frameworks mandate packaging recovery cost internalization. Los Angeles and San Francisco retail corridors drive still water volume through supermarket channels while corporate offices prioritize closed-loop aluminum programs.
British Columbia
Vancouver luxury hospitality properties require real-time provenance verification as standard procurement precondition. Health Canada Guidelines for Canadian Drinking Water Quality tighten mineral content disclosure thresholds for imported premium waters. Vancouver and Victoria retail channels accelerate investment in in-house quality assurance infrastructure to satisfy divergent testing protocols.
Ontario
Toronto corporate procurement departments consolidate supplier relationships into sustainability-focused contracts. Health Canada Food and Drugs Act provisions govern cross-border supply chain documentation at Detroit corridor crossings. Toronto and Ottawa metropolitan areas concentrate sparkling water demand through fine-dining channel expansion.
Florida
Miami luxury hotel minibars stock premium still and sparkling variants as standard amenity offerings. FDA 21 CFR 165.110 source identification mandates advantage established players with captive spring-source documentation. Miami-Dade hospitality corridor generates predictable recurring revenue through glass-bottle presentation requirements.
New York
Manhattan fine-dining beverage programs demand blockchain-verified provenance systems as procurement preconditions. FDA bottled water quality standards influence source-protection marketing differentiation strategies. New York Metro retail and hospitality channels concentrate demand for conspicuous consumption packaging formats.
US and Canada Premium Bottled Water Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Large beverage conglomerates leverage existing distribution infrastructure while niche spring-source specialists defend margin through provenance documentation. Three archetypes dominate: multinational conglomerates with cross-category leverage, alpine-spring specialists with controlled source agreements, and direct-to-consumer subscription operators. Competitive moves concentrate on strategic partnerships for distribution access and portfolio diversification into functional variants.
Within the direct-to-consumer tier, CORE Nutrition LLC exemplifies asset-light subscription infrastructure without captive bottling assets. Among European-origin specialists, Danone Waters of America and Perrier International occupy positions anchored through controlled spring-source agreements and hospitality channel penetration. Voss USA, Inc. represents glass-bottle positioning archetypes in hotel minibars and fine-dining channels.
| Leading Market Players |
|---|
| Perrier International |
| CORE Nutrition LLC |
| Danone Waters of America (Evian) |
| Voss USA, Inc. |
| The Coca-Cola Company |
| FIJI Water Company LLC |
| Acqua Panna |
| Icelandic Glacial, Inc. |
| Sanpellegrino S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Alpine spring sources in France and Norway concentrate upstream supply control among established European-origin specialists, anchoring margin capture in coastal US and Canadian metropolitan corridors where hospitality procurement teams absorb freight premiums for provenance-branded positioning.
Pricing Analysis
Certification level under FDA 21 CFR 165.110 and Health Canada Guidelines creates the primary spread between commodity-adjacent and defensible premium tiers. Three-tier pricing structure across luxury hospitality, corporate subscription, and mass retail channels stratifies by source documentation depth and packaging format. Price erosion runs through plastic formats in California supermarket channels as extended producer responsibility mandates compress margin structures. Corporate procurement departments in Silicon Valley demonstrate lowest price sensitivity, prioritizing Scope 3 emissions documentation over per-unit cost.
Supply Chain Analysis
Alpine spring extraction in France, Norway, and Iceland feeds raw material inputs for premium still and sparkling variants sold across North American markets. Glass bottle sourcing, carbonation infrastructure, and cold-chain logistics constitute critical component dependencies. Single-source vulnerability concentrates in cross-border Detroit and Buffalo corridor crossings where dual FDA-Health Canada compliance documentation creates inspection delays. Distribution runs through asset-light third-party logistics partnerships for emerging brands, while established players leverage controlled source agreements and captive hospitality channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US and Canada Premium Bottled Water sits in early-cycle expansion as direct-to-consumer subscription infrastructure and real-time provenance verification systems penetrate beyond coastal metropolitan strongholds into interior markets.
For Market Incumbents: Pre-empt point-of-use filtration substitution threats in corporate office channels by accelerating closed-loop aluminum program deployment and deepening hospitality channel lock-in through blockchain-verified batch tracking. Source protection expertise and long-term aquifer stewardship protocols represent scarce defensive capabilities that commodity entrants cannot replicate quickly. Extend controlled spring-source agreements in the French Alps and Nordic regions to foreclose competitor access to premium provenance positioning. For New Entrants and Emerging Players: Residential sparkling water compatibility with home carbonation devices in Ontario and Florida represents the most penetrable entry point for subscription-based customer acquisition. Functional variants targeting athletic recovery in premium gym chains offer white-space expansion with lower incumbent saturation than hospitality channels. Direct-to-consumer infrastructure bypasses retail slotting fee burdens and builds proprietary data assets for cross-selling into adjacent beverage categories. For Investors and Strategic Acquirers: Capital is best deployed toward alpine-spring specialists with controlled source agreements and established hospitality channel penetration rather than undifferentiated volume plays. Long-term viability hinges on provenance verification technology investments and regulatory compliance infrastructure that compound competitive moats over a multi-year horizon. Watch California extended producer responsibility implementation timelines as an inflection indicator for packaging format winners and losers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and builds proprietary customer data assets for cross-selling. |
| Blockchain Provenance Verification Deployment | Meets Vancouver and Miami hospitality procurement preconditions for real-time batch tracking. |
| Closed-Loop Aluminum Program Expansion | Addresses California technology sector sustainability mandates and Scope 3 emissions reporting. |
| Controlled Spring-Source Agreement Extension | Forecloses competitor access to premium French Alps and Nordic aquifer positioning. |
| Functional Variant Pipeline Development | Captures athletic recovery demand in premium gym chains and wellness subscription models. |
Research Methodology
The analysis maps still, sparkling, flavored, and functional water sub-sectors, each validated through beverage brand managers, hospitality procurement directors, supermarket category buyers, and third-party logistics operators. Primary interview data triangulates against FDA enforcement records, Health Canada Guidelines for Canadian Drinking Water Quality, Nielsen retail audit data, and customs import documentation. Bottom-up volume modeling across packaging formats and distribution channels reconciles with top-down market sizing derived from trade association disclosures and regulatory filing cross-references.
Assumption sets held regulatory timelines and coastal metropolitan demand concentration patterns fixed while varying subscription model penetration rates and aluminum format adoption curves across the projection horizon. Segmentation dimensions modeled include product type, packaging material, distribution channel, and end-user vertical with geographic clustering by state and province. CAGRs derive from historical volume trajectories adjusted for channel shift dynamics and compliance cost pass-through elasticity. Forecast inputs incorporate extended producer responsibility implementation schedules and hospitality procurement consolidation trends.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending patterns or cross-border tariff regimes would shift the trajectory for premium positioning viability. Forecasts reflect documented assumptions about regulatory enforcement intensity and source protection litigation risk. Cross-checking against hospitality industry capital expenditure surveys and corporate procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Plant Based Protein Beverages Market
Beverages
Detox Drinks Market
Beverages
Middle East Energy Drinks Market
Beverages
North America Cold Pressed Juices Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Beverage Dispenser Market
Beverages
Popping Bobas Market
Beverages
Baby Drinks Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Italy Bottled Water Market
Beverages
Probiotic Beverage Market
Beverages
Apple Juice Market
Beverages
Baby Drinking Water Market
Beverages
Morocco Bottled Water Market
Beverages
Reconstituted Juice Market
Beverages
Flavored Powder Drinks Market