
 Asia Pacific Fermented Drinks Market | 2026-2036
Asia Pacific Fermented Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fermented Drinks Market Outlook
The EU Green Deal's extraterritorial sustainability benchmarks are rebalancing procurement criteria for Asia Pacific exporters serving European buyers. Yakult Honsha leverages its probiotic R&D infrastructure to sustain formulation leadership across East Asian markets. Kirin Holdings anchors premium positioning through controlled distribution in Japan's convenience store networks. Hakkaisan Brewery differentiates via traditional koji fermentation methods that occupy a defensible craft niche.
Asia Pacific fermented drinks encompass beverages produced through controlled microbial fermentation of substrates including tea, dairy, grains, or fruit, typically yielding live cultures, organic acids, and ethanol at concentrations below distilled spirits, with shelf stability and sensory profiles governed by pH, temperature, and inoculum strain selection. Kombucha commands structural prominence among Product Type categories due to its scalability in industrial brewing and alignment with sugar-reduction trends. Kefir retains concentrated margin pools within dairy-adjacent Health Enthusiasts segments where probiotic density justifies premium positioning. Online Retailers within Distribution Channel categories are capturing accelerated volume as direct-to-consumer cold-chain logistics mature across Southeast Asian markets.
Japan's Ministry of Economy, Trade and Industry (METI) enforces FOSHU (Foods for Specified Health Uses) standards that shape functional claims and product registration timelines for fermented drink manufacturers. China's National Health Commission and SAMR jointly administer GB 7101 beverage safety standards that govern microbial limits and additive permissions for domestic and imported products. India's FSSAI is tightening labeling requirements for probiotic count declarations, affecting market access for regional exporters. Stakeholders must monitor divergence between national probiotic definition frameworks as harmonization failures risk fragmentation of formulation strategies across the region.
Market Dynamics
China's GB 7101 beverage safety standards are compressing formulation timelines for cross-border suppliers while Japan's FOSHU framework creates premium claim pathways that reshape competitive positioning across East Asian markets.
Growth Catalysts
- Functional beverage culture:Japan's metropolitan corridors sustain concentrated demand for probiotic drinks with verified health claims, anchoring regional premiumization trends.
- GB standards harmonization:China's tightening microbial limits and additive permissions under SAMR administration are elevating compliance barriers that favor scaled domestic producers.
- Cold-chain logistics maturation:Direct-to-consumer distribution networks across Southeast Asian markets are unlocking refrigerated fermented beverage penetration previously constrained by infrastructure gaps.
Market Restraints
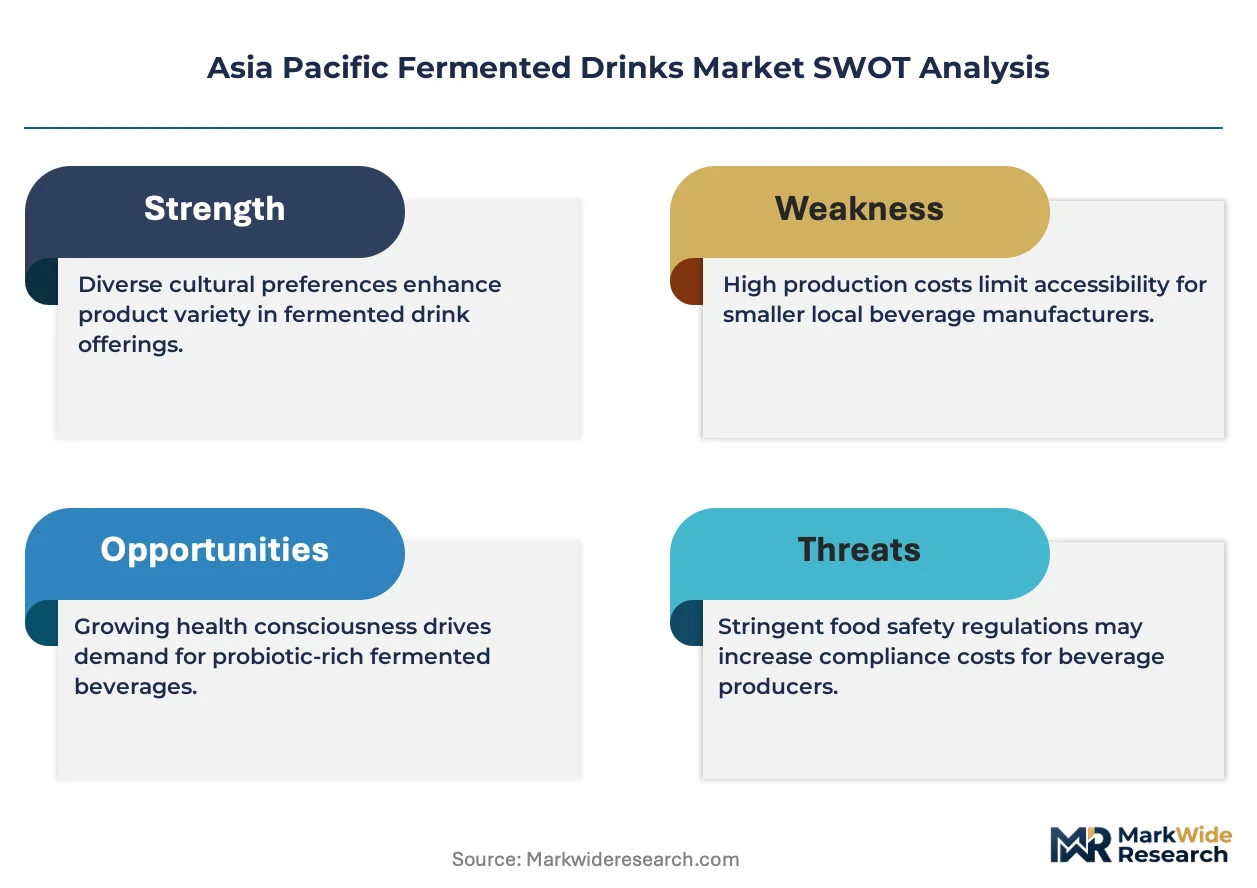
- Input cost volatility:Organic tea substrate prices fluctuate with climate variability in China's Yunnan and Fujian growing regions, compressing kombucha producer margins.
- Regulatory friction:India's FSSAI probiotic count declaration requirements create labeling complexity that delays market access for regional exporters.
- Technical limitation:Shelf stability without pasteurization remains constrained by pH tolerance thresholds in ambient distribution environments.
Strategic Opportunities
- Vietnam and Indonesia penetration:Underdeveloped functional beverage categories in these Southeast Asian markets present first-mover positioning for kefir and water kefir variants.
- Koji fermentation premiumization:Traditional inoculum methods from Japan's craft sake sector are transferring to non-alcoholic fermented drinks, creating defensible sensory differentiation.
- Online Retailer channel expansion:E-commerce platforms with integrated cold-chain fulfillment are capturing accelerated volume as consumer trial behavior shifts from physical retail.
Industry Challenges
- Strain banking and culture maintenance:Specialized microbiology talent for proprietary inoculum preservation commands premium compensation in markets with limited fermentation science pipelines.
- FOSHU registration timelines:Japan's functional claims certification process extends product development cycles by 18-24 months, tying up R&D capital.
- Cross-border compliance fragmentation:Divergent national probiotic definition frameworks between China, Japan, and India force redundant formulation testing and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fermented Drinks Market |
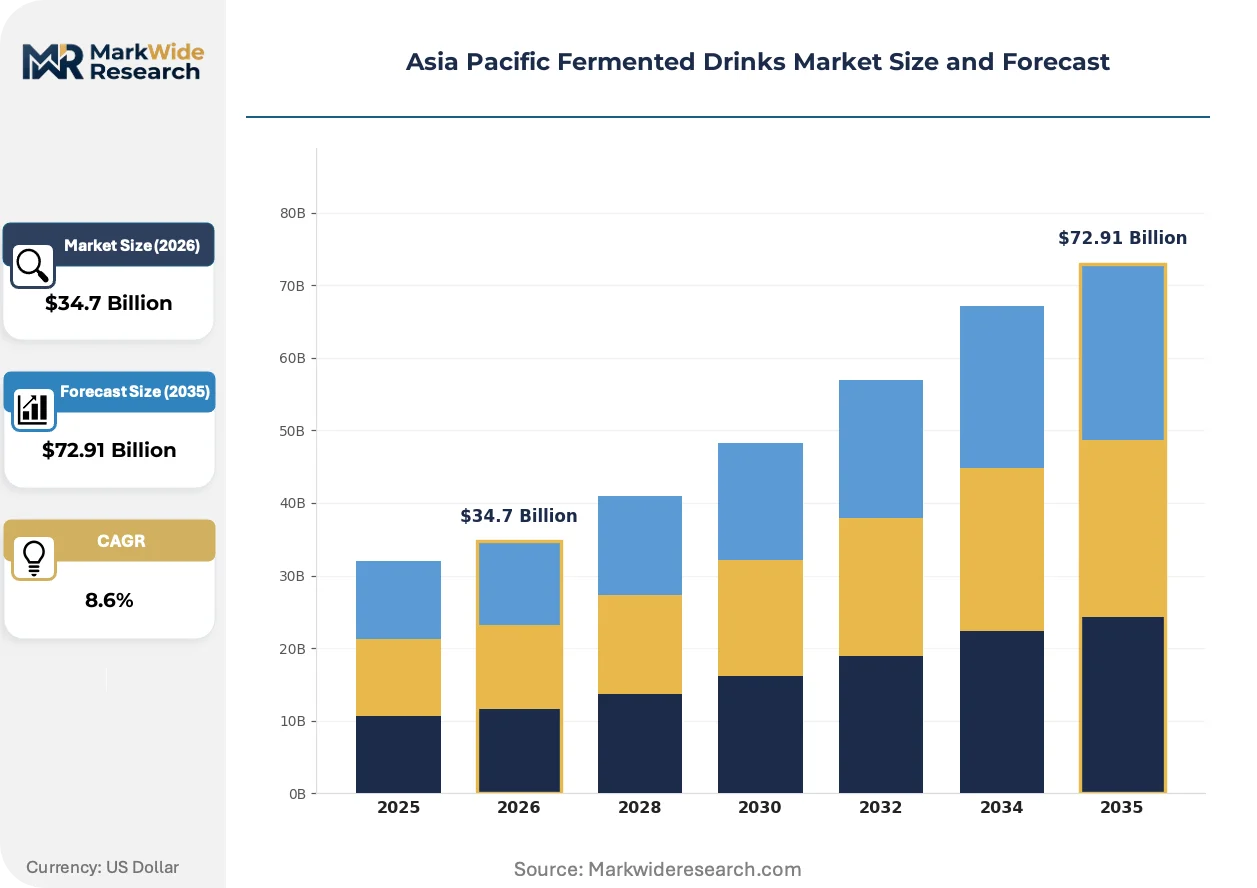
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Miso, Tepache End User: Retail Consumers, Food Service, Beverage Manufacturers, Health Enthusiasts Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Flavor Profile: Fruity, Herbal, Spicy, Savory |
| Companies Covered | Nestlé, PepsiCo, Yakult Honsha, Heineken, Coca-Cola, Kirin Holdings, Danone, Hakkaisan Brewery, Asahi Group Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fermented Drinks Market Strategic Shifts
Automation of brewing processes and regulatory divergence around health claims are actively compressing production economics while reshaping how fermented drinks reach Health Enthusiast segments across the region.
Precision fermentation monitoring systems integrating real-time pH and temperature sensors with strain-specific growth algorithms are automating quality consistency previously dependent on master brewer expertise. Mid-scale kombucha producers in China's Zhejiang and Jiangsu provinces are adopting these platforms fastest, reducing batch failure rates and enabling contract manufacturing arrangements that compress time-to-market for new entrants.
Japan's METI is tightening FOSHU evidentiary standards for gut health claims, requiring expanded clinical documentation that extends registration timelines and elevates R&D spend thresholds. Domestic incumbents with existing approved SKUs are reinforcing portfolio depth around these claims, while challengers pivot toward generic wellness positioning that circumvents functional registration entirely.
Subscription-based replenishment models are displacing conventional retail stocking for probiotic beverages in South Korea and Australia's major metropolitan markets. Direct-to-consumer platforms capture recurring revenue with customized strain blends and flavor rotations, while convenience store networks lose traffic among Health Enthusiast segments that prioritize personalization over immediate availability.
Asia Pacific Fermented Drinks Market Segmentation
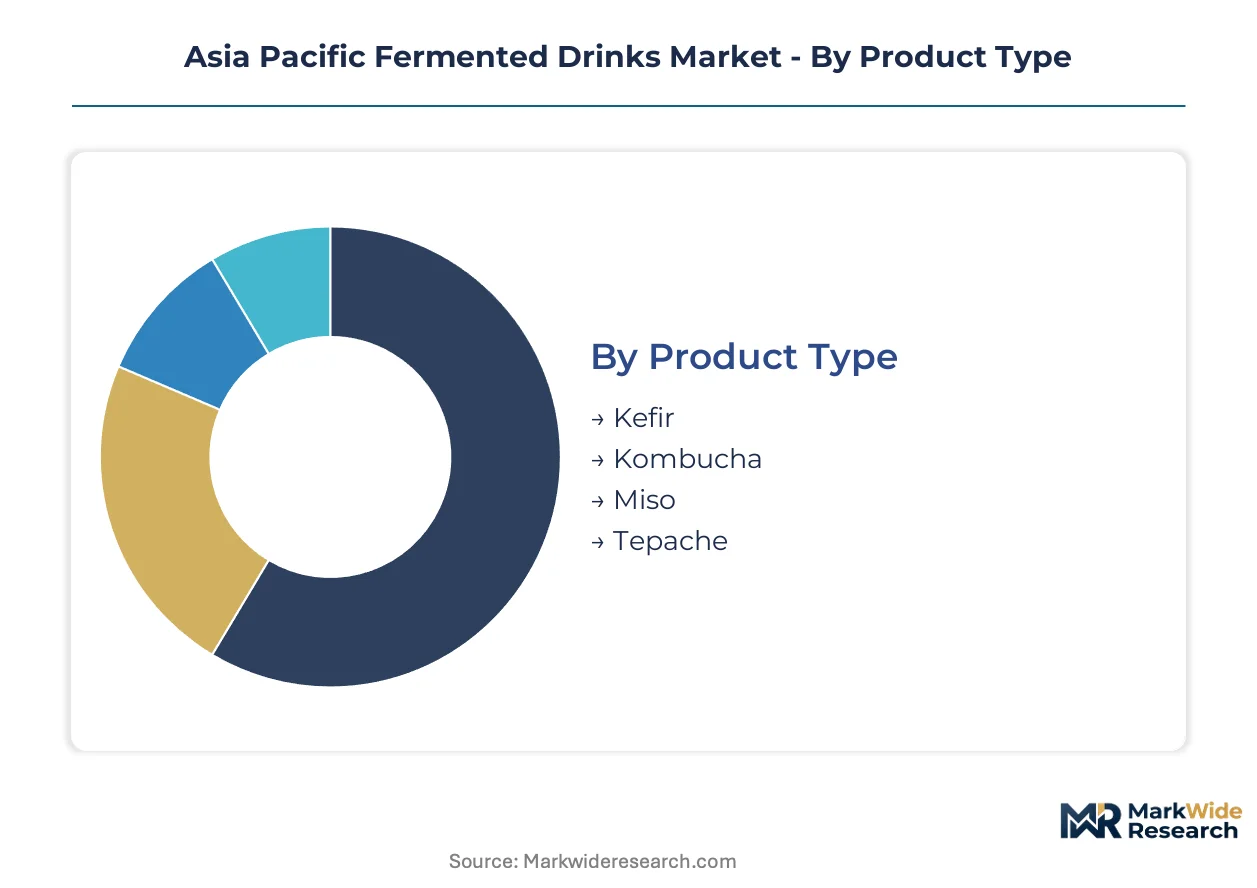
Fermented drinks in the Asia Pacific region fragment across formulation science, buyer sophistication, and temperature-controlled logistics capabilities. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape competitive strategy.
Product Type:
Buyers in this category differentiate by probiotic density, alcohol content thresholds, and cultural familiarity with specific fermentation substrates.
- Kombucha:Tea-based aerobic fermentation yields acetic acid and live cultures at sub-0.5% ABV in commercial formulations. Demand concentrates in Australia's metropolitan markets where sugar-reduction mandates from Food Standards Australia New Zealand drive reformulation toward lower glycemic alternatives. Scalable industrial brewing in China's Zhejiang province anchors supply.
- Kefir:Mesophilic fermentation of milk or water-based substrates produces higher bacterial diversity than yogurt-adjacent products. Health Enthusiasts in South Korea's Seoul-Incheon corridor sustain premium positioning where MFDS dairy safety standards elevate compliance costs for imported variants.
- Miso:Traditional soybean-koji fermentation yields umami-dense beverage applications beyond soup bases. Japanese craft producers dominate sensory differentiation.
- Tepache:Indigenous Mexican pineapple fermentation adapted for tropical fruit substrates across Southeast Asian markets. Emerging niche with limited scaled production.
Kombucha leads volumes today; kefir is gaining share fastest among dairy-adjacent Health Enthusiasts.
End User:
Procurement sophistication and cold-chain requirements separate buyers by operational scale and claim verification needs.
- Retail Consumers:Individual purchasers selecting single-serve formats with visible probiotic counts and FOSHU or FSSAI compliance marks. Japan's convenience store networks capture recurring trial among metropolitan commuters.
- Food Service:Cafes and restaurants incorporating fermented bases into customized beverages. Australia's specialty coffee culture drives on-tap kombucha installations in Melbourne and Sydney.
- Beverage Manufacturers:Industrial buyers sourcing bulk fermented substrates for downstream blending and private label production. China's contract brewing sector in Jiangsu province serves regional brand development.
- Health Enthusiasts:Discriminating buyers prioritizing strain-specific documentation and subscription replenishment models. South Korea's direct-to-consumer platforms capture this segment with personalized flavor rotations.
Retail Consumers anchor current revenue; Health Enthusiasts are expanding most quickly through subscription channels.
Distribution Channel:
Refrigeration infrastructure and last-mile speed determine channel viability for live-culture products.
- Supermarkets:Multi-brand retail with ambient and chilled sections requiring pasteurized or shelf-stable variants. China's Hema Fresh and Yonghui Superstores allocate expanding cold-chain space to functional beverages.
- Online Retailers:E-commerce platforms with integrated cold-chain fulfillment enabling direct-to-consumer trial and replenishment. Southeast Asian markets in Vietnam and Indonesia unlock penetration previously constrained by physical retail gaps.
- Convenience Stores:Immediate-availability formats in Japan's Lawson and 7-Eleven networks where FOSHU-registered SKUs command premium shelf positioning.
- Specialty Stores:Curated retail emphasizing craft provenance and traditional fermentation methods. Australia's independent health food sector sustains kefir and water kefir discovery.
Supermarkets dominate transaction volume today; Online Retailers are climbing the fastest as logistics infrastructure matures.
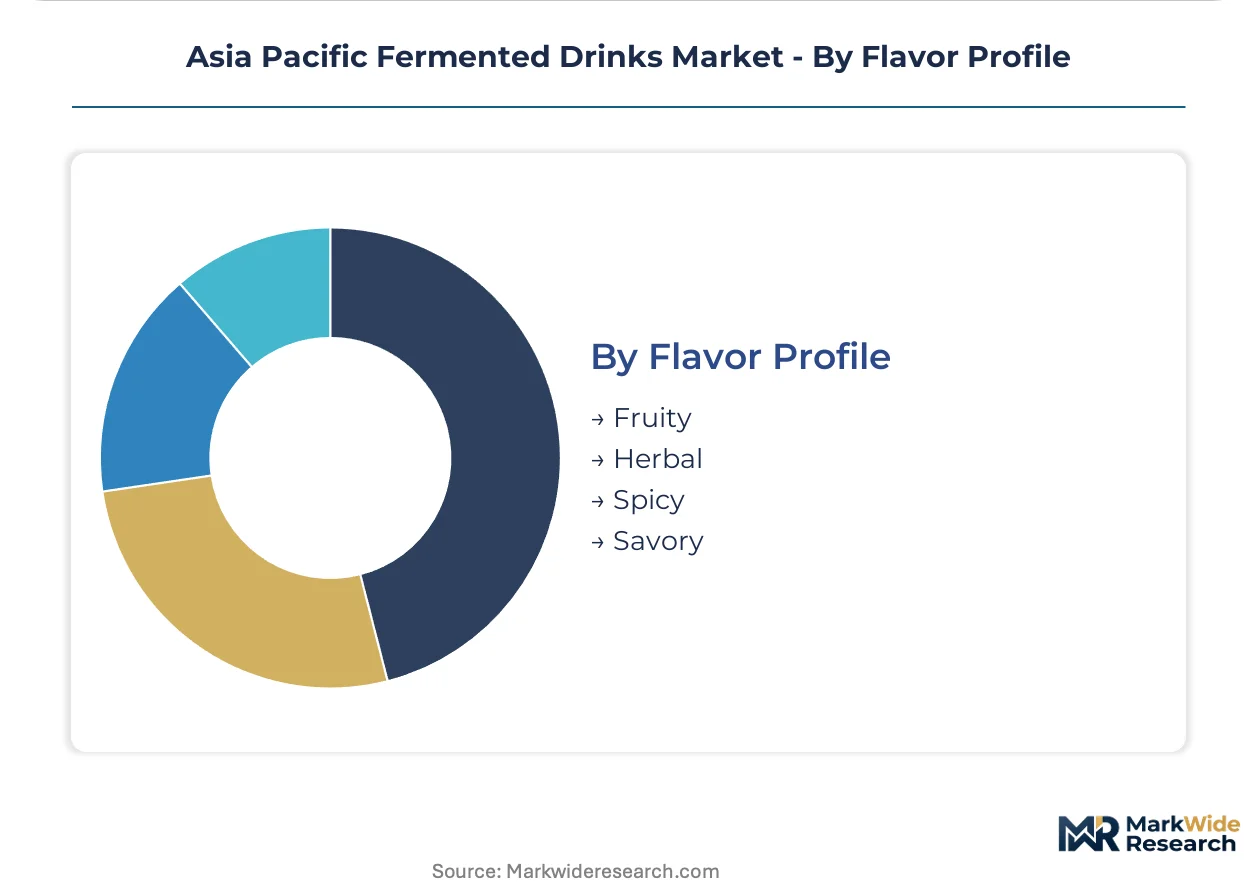
Flavor Profile:
Sensory preference maps to functional positioning and regional palate adaptation.
- Fruity:Berry, citrus, and tropical fruit infusions masking fermentation acidity for mainstream palate entry. Australia's kombucha producers lead flavor innovation.
- Herbal:Botanical additions including ginger, turmeric, and adaptogenic plants aligning with traditional medicine frameworks. Chinese consumers respond to TCM-associated ingredients.
- Spicy:Chili and pepper formulations popular in Southeast Asian markets where heat tolerance shapes beverage acceptance.
- Savory:Umami-forward profiles leveraging miso and koji fermentation heritage. Japanese craft producers occupy defensible positioning.
Fruity profiles sustain the broadest appeal today; Herbal formulations are expanding most quickly among Health Enthusiasts seeking functional ingredient association.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traditional fermentation practices in East Asia, particularly Japan's koji methods and China's tea-based brewing, established the foundational techniques now scaling across industrial production facilities throughout the region.
Japan
Metropolitan corridors in Tokyo and Osaka sustain concentrated demand for FOSHU-certified functional beverages with verified probiotic claims. METI's tightening evidentiary standards for gut health claims extend product registration timelines by 18-24 months. Yakult Honsha leverages its established R&D infrastructure to maintain formulation leadership across domestic convenience store networks.
China
Zhejiang and Jiangsu provinces anchor industrial kombucha brewing capacity serving both domestic consumption and regional export markets. SAMR-administered GB 7101 beverage safety standards compress formulation timelines for cross-border suppliers while elevating microbial limit compliance barriers. Contract manufacturers in these coastal clusters enable rapid brand development for new market entrants.
South Korea
Seoul-Incheon corridor Health Enthusiasts drive premium positioning for kefir variants where MFDS dairy safety standards elevate import compliance costs. Subscription-based replenishment models displace conventional retail stocking among discriminating buyers seeking personalized strain blends. Direct-to-consumer platforms capture recurring revenue through customized flavor rotations.
Australia
Melbourne and Sydney specialty coffee cultures sustain on-tap kombucha installations across food service channels. Food Standards Australia New Zealand sugar-reduction mandates drive reformulation toward lower glycemic alternatives. Independent health food retailers in these metropolitan markets sustain kefir and water kefir discovery among craft-oriented consumers.
Vietnam
Ho Chi Minh City and Hanoi present underdeveloped functional beverage categories with first-mover positioning available for kefir and water kefir variants. E-commerce platforms with integrated cold-chain fulfillment unlock penetration previously constrained by physical retail infrastructure gaps. Online Retailers capture accelerated volume as consumer trial behavior shifts from traditional distribution channels.
Asia Pacific Fermented Drinks Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation science and regulatory certification dimensions, with FOSHU-registered portfolios commanding shelf positioning advantages in Japanese convenience networks. The vendor base clusters around three strategic archetypes: multinational beverage conglomerates with diversified fermentation portfolios, specialized probiotic-focused manufacturers with concentrated R&D infrastructure, and craft-scale traditionalists leveraging heritage inoculum methods. Dominant competitive moves include strategic partnerships with cold-chain logistics providers and portfolio diversification into adjacent functional beverage categories.
Within the specialized probiotic tier, Yakult Honsha and Kirin Holdings exemplify divergent approaches to East Asian market development, while Hakkaisan Brewery occupies a distinct craft positioning rooted in traditional koji fermentation heritage. These three Japanese entities represent the spectrum from scaled industrial production to defensible sensory differentiation, with each archetype responding differently to METI regulatory frameworks and metropolitan distribution dynamics.
| Leading Market Players |
|---|
| Nestlé |
| PepsiCo |
| Yakult Honsha |
| Heineken |
| Coca-Cola |
| Kirin Holdings |
| Danone |
| Hakkaisan Brewery |
| Asahi Group Holdings |
| Others |
Value Chain & Pricing Dynamics
FOSHU-certified premium tiers in Japan's convenience networks command shelf positioning advantages that commodity kombucha producers in China's industrial brewing clusters cannot replicate, creating a bifurcation where certification investment and cold-chain infrastructure separate margin capture from price-taker dynamics. This tier divergence manifests in procurement patterns: premium buyers absorb strain-specific R&D costs while mass-market suppliers compete on organic tea substrate sourcing efficiency and batch automation.
Pricing Analysis
Three-tier pricing structure across FOSHU-registered, standard live-culture, and shelf-stable pasteurized levels governs the Asia Pacific fermented drinks landscape. Price differentiation hinges on probiotic count verification and Japan's METI functional claims certification versus generic wellness positioning. Pricing pressure stems from organic tea cost volatility in Yunnan and Fujian provinces compressing kombucha producer margins. Retail Consumers exhibit highest price sensitivity, while Health Enthusiasts absorbing subscription premiums show least elasticity.
Supply Chain Analysis
Cold-chain logistics costs dominate landed price calculations for live-culture products crossing from China's Zhejiang brewing clusters to Southeast Asian markets. Supply concentrates in Japan's koji fermentation heritage sites, China's industrial kombucha provinces, and South Korea's dairy-adjacent kefir production. Raw material dependencies include organic tea substrates, proprietary inoculum strains, and temperature-controlled packaging. Single-source vulnerability around master brewer talent pools threatens culture maintenance consistency. Distribution runs through Japan's Lawson and 7-Eleven networks, China's Hema Fresh, and Vietnam's emerging e-commerce platforms with integrated fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific fermented drinks market functions as a geographic-arbitrage play where Japan's 18-24 month FOSHU registration timelines and elevated R&D spend thresholds deter challengers, while China's GB 7101 compliance barriers favor scaled domestic producers with existing SAMR relationships.
For Market Incumbents: Cement formulation leadership by deepening proprietary strain banking capabilities and securing exclusive master brewer talent pools before compensation inflation spreads beyond Tokyo and Osaka. Defend against private-label erosion from China's contract manufacturers by accelerating FOSHU portfolio depth around gut health claims before METI evidentiary standards tighten further.
For New Entrants and Emerging Players: Enter via Vietnam and Indonesia's underdeveloped functional beverage categories where first-mover positioning for kefir and water kefir variants remains uncontested. Ho Chi Minh City and Hanoi present white-space penetration through e-commerce platforms with integrated cold-chain fulfillment, bypassing physical retail infrastructure gaps that constrain incumbent distribution.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale kombucha producers in China's Jiangsu and Zhejiang provinces face margin compression from organic tea cost volatility and SAMR compliance escalation. Target acquisition archetypes include automated brewing platform operators with contract manufacturing relationships and established cold-chain logistics partnerships. Watch for inflection signals in Japan's FOSHU registration queue lengths as indicators of regulatory barrier sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Partnership | Integrated fulfillment networks unlock Vietnam and Indonesia penetration previously constrained by infrastructure gaps. |
| FOSHU Registration Acceleration | Compressed timelines before METI evidentiary tightening secure premium shelf positioning in Lawson and 7-Eleven networks. |
| Strain Banking Investment | Proprietary inoculum preservation capabilities command defensible margins as microbiology talent scarcity intensifies. |
| Subscription Platform Launch | Direct-to-consumer replenishment captures Health Enthusiast recurring revenue in Seoul-Incheon and Australian metropolitan corridors. |
| Koji Fermentation Licensing | Traditional method transfer from Japan's craft sake sector creates sensory differentiation in non-alcoholic variants. |
Study Parameters
Multiple input streams — primary interviews with fermentation science directors, brand managers at functional beverage producers, cold-chain logistics operators, and convenience store category buyers, alongside secondary validation through SAMR GB standard filings, METI FOSHU registration databases, and Food Standards Australia New Zealand sugar-reduction mandates — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned Tokyo, Shanghai, Seoul, and Melbourne metropolitan clusters.
Data-stream reconciliation anchored volume and value outputs across product type, distribution channel, end user sophistication tier, and regional regulatory framework segmentation throughout the projection horizon. CAGRs were derived from historical trajectory analysis calibrated against probiotic density trends and cold-chain infrastructure buildout rates. Modeled inputs included FOSHU registration pipeline velocity, organic tea substrate price indices, and e-commerce penetration curves in Southeast Asian markets.
Inputs from SAMR administrative notices and METI functional claims guidelines were available through the study window; gaps in proprietary strain performance data and master brewer compensation benchmarks introduce uncertainty bands around R&D spend forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Plant-Based Energy Drink Market
Beverages
Health Drinks Market
Beverages
Sparkling Water Market
Beverages
Breakfast Drink Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
South America Bottled Water Market
Beverages
Orange Juice Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Bottled Water Processing Market
Beverages
United States and Australia Coconut Water Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Fiber Fortified Beverages Market
Beverages
Caffeine Mint Market
Beverages
Spring Water Market
Beverages
Fruit Juice Market
Beverages
Tonic Water Market