
 High Protein Flour Market | 2026-2036
High Protein Flour Market Size, Share, and Industry Trends Forecast 2026-2036
High Protein Flour Market Foresight
The capital-intensity divergence between integrated millers and regional specialists is reorganizing competitive dynamics in high protein flour milling. Ardent Mills leverages its North American grain elevator network to secure premium hard wheat supply chains. King Arthur Baking Company differentiates through direct-to-baker relationships and specialty blend formulations. General Mills sustains volume advantages in institutional channels through centralized procurement and formulation consistency.
High protein flour refers to milled grain products containing elevated protein content, typically ranging from twelve to fifteen percent for wheat varieties, achieved through selective hard red winter or hard red spring wheat sourcing and controlled tempering processes. Industrial bakers utilize these flours to develop strong gluten networks that support structural integrity in artisan breads, pizza crusts, and high-volume commercial bakery output. Wheat flour occupies the dominant position across product type segments due to established supply infrastructure and functional versatility in gluten-forming applications. Nutritional supplements represent the fastest-expanding application category as protein-fortified powders and meal replacements gain traction in health food stores and online retail channels. Bakeries within the end user segment command concentrated margin pools through contract-based volume purchasing and customized protein level specifications.
The FDA governs flour enrichment standards and allergen labeling under the Food Allergen Labeling and Consumer Protection Act, while the USDA oversees grain grading and protein content certification through its Agricultural Marketing Service. These frameworks elevate compliance costs for smaller millers but simultaneously create quality verification mechanisms that large-scale buyers demand for supply chain qualification. Stakeholders must monitor evolving protein content measurement protocols and emerging plant-based flour regulatory classifications to anticipate reformulation requirements and sourcing adjustments.
Market Dynamics
Protein content standardization is forcing millers to reconfigure sourcing relationships and tempering protocols. The USDA's Agricultural Marketing Service now certifies protein levels with stricter tolerances, compelling facilities to invest in inline near-infrared spectroscopy for real-time quality verification.
Growth Catalysts
- Clean Label Movement:Consumer rejection of synthetic additives drives bakers toward naturally protein-dense hard wheat varieties. The FDA's updated Nutrition Facts labeling requirements amplify protein callouts on packaging.
- Functional Food Expansion:Nutraceutical manufacturers incorporate high protein flour into meal replacement bars and fortified beverages. Sports nutrition brands now specify minimum protein thresholds in supplier contracts.
- Pizza Chain Specifications:National quick-service restaurants mandate 13-14% protein content for dough performance consistency. These volume contracts stabilize offtake for premium hard red spring wheat suppliers.
Market Restraints
- Hard Wheat Supply Concentration:Premium protein wheat production concentrates in the northern Great Plains and Canadian prairies. Weather volatility in these regions creates input cost instability for millers.
- Gluten-Free Substitution:Almond flour, chickpea flour, and other alternative proteins displace wheat in specialty baking segments. Celiac disease diagnosis rates and low-carb dietary trends accelerate this displacement.
- Enforcement Cost Burden:The Food Allergen Labeling and Consumer Protection Act mandates facility segregation and testing protocols. Smaller regional millers face disproportionate compliance expenditures relative to revenue.
Strategic Opportunities
- Plant-Based Protein Blending:Pea protein isolate and wheat gluten combinations create hybrid flours with enhanced amino acid profiles. Sports nutrition and elderly nutrition segments show strong trial rates for these formulations.
- Direct-to-Baker Digital Channels:Specialty millers bypass distributors through subscription platforms offering customized protein specifications. Artisan bakeries in metropolitan corridors prefer this procurement model for traceability.
- Carbon-Labeling Differentiation:The EU Green Deal's Farm to Fork Strategy incentivizes low-carbon wheat sourcing. European millers capturing regenerative agriculture certifications command shelf space premiums.
Industry Challenges
- Milling Technician Shortage:Tempering optimization and protein blending require specialized craft knowledge that vocational programs no longer emphasize. Facilities struggle to staff third-shift operations.
- Legacy Equipment Retrofit Costs:Inline protein measurement systems demand capital outlays exceeding $2 million per production line. Regional specialists lack balance sheet capacity for these upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Protein Flour Market |
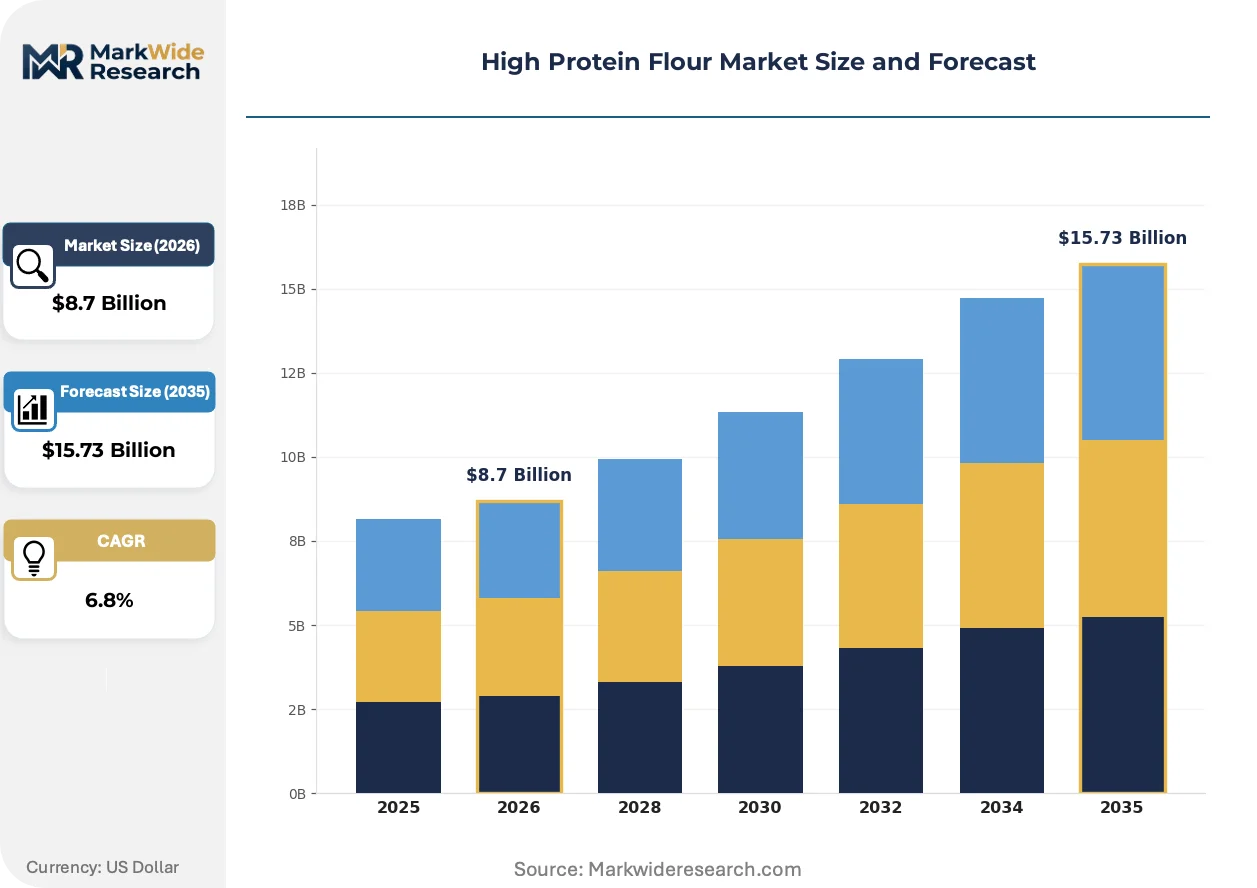
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour, Pea Flour, Almond Flour, Soy Flour Application: Baking, Nutritional Supplements, Snack Foods, Pasta End User: Households, Food Service, Bakeries, Health Food Stores Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Miller Milling Company, Bay State Milling Company, Archer Daniels Midland, King Arthur Baking Company, General Mills, Ardent Mills, Siemer Milling Company, The White Lily Foods Company, Central Milling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Protein Flour Market Shifts & Advancements
Near-infrared spectroscopy and enzyme-assisted processing are compressing quality verification cycles from days to minutes. These technologies enable just-in-time protein adjustments that were previously impossible at commercial scale.
Enzymatic protein modification is decomposing the traditional tradeoff between protein content and dough extensibility. Industrial bakeries in the United States and Germany now deploy fungal amylases and transglutaminase to achieve 14% protein performance from 12% protein wheat. This biotechnology is decomposing premium hard wheat premiums by enabling functional equivalence from lower-cost inputs.
The EU's Farm to Fork Strategy mandates 25% organic farmland conversion by 2030, forcing wheat suppliers to certify regenerative practices. Millers sourcing from the European Union must now document carbon intensity per ton. Organic high protein wheat commands supply chain preference from sustainability-focused bakery chains in France and Germany.
Specification-driven procurement is consolidating buyer power among national bakery chains and contract manufacturers. These buyers now require lot-level protein certificates with third-party verification. Direct miller-to-baker relationships displace traditional distributor intermediaries in urban food manufacturing corridors across the United States and United Kingdom.
High Protein Flour Market Segmentation
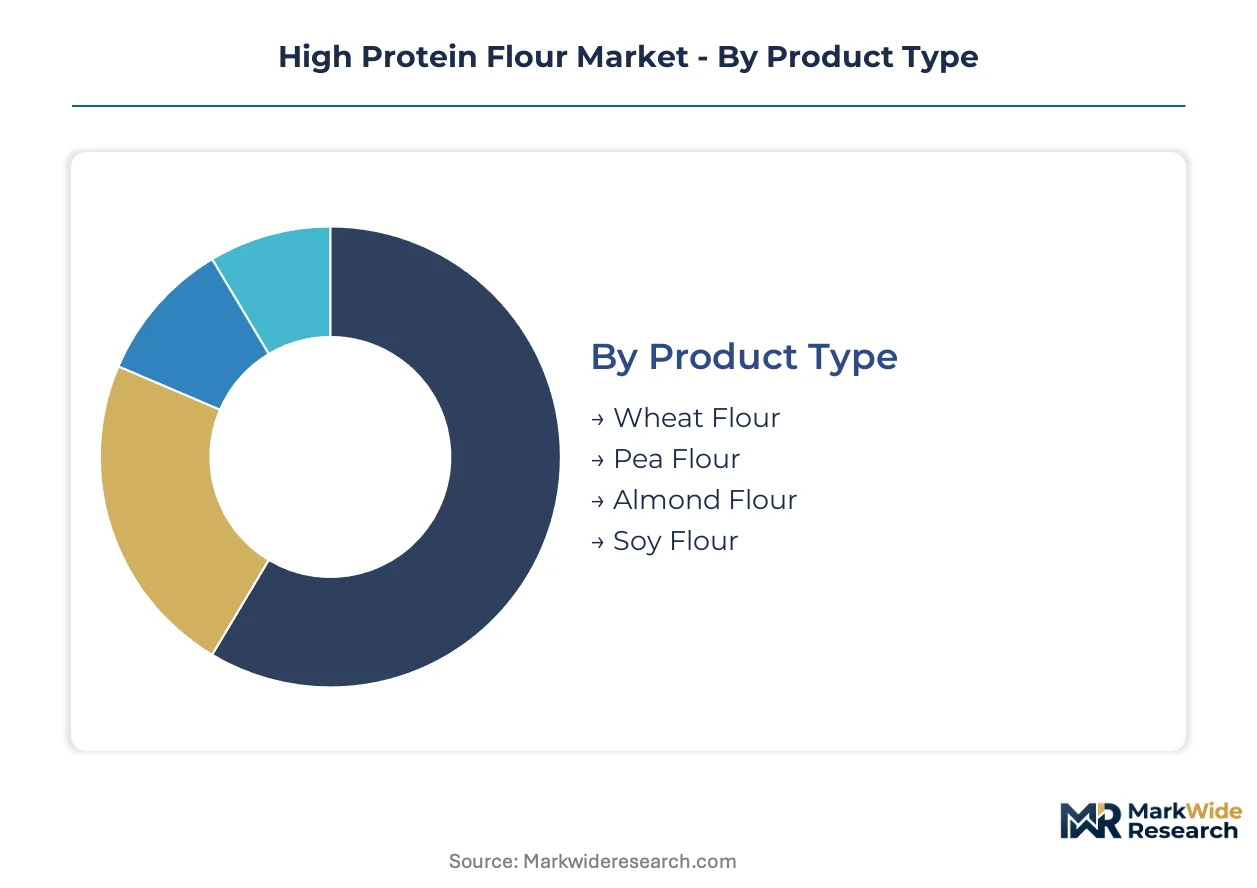
Protein content thresholds and gluten-forming requirements create distinct procurement behaviors across flour categories. FDA enrichment standards and USDA protein certification protocols shape how each segment qualifies for commercial and retail channels.
Product Type:
Regulatory frameworks differentiate wheat-based products from allergen-classified alternatives under the Food Allergen Labeling and Consumer Protection Act.
- Wheat Flour:Hard red winter and hard red spring varieties deliver 12-15% protein content through controlled tempering processes. Commercial bakeries in Minneapolis and Kansas City corridors specify this grade for pizza dough and artisan bread production, with USDA Agricultural Marketing Service certification required for contract eligibility.
- Pea Flour:Isolated protein concentrates blend with wheat gluten to create hybrid amino acid profiles. Sports nutrition manufacturers in Denver and Portland now specify minimum protein thresholds in supplier agreements, bypassing traditional distributor networks.
- Almond Flour:Gluten-free positioning captures specialty baking segments under FDA allergen labeling protocols. Celiac disease diagnosis rates accelerate displacement from wheat in premium retail channels.
- Soy Flour:Defatted varieties serve as protein extenders in institutional baking applications. Food service distributors in Chicago and Dallas specify this grade for cost-controlled formulations.
Established volume favors Wheat Flour; emerging adoption favors Pea Flour.
Application:
End-use specifications concentrate buyer power among national chains and contract manufacturers.
- Baking:Industrial facilities deploy 13-14% protein flour for structural integrity in high-volume output. Quick-service restaurant chains mandate consistent dough performance across thousands of locations, stabilizing offtake for premium hard red spring wheat suppliers.
- Nutritional Supplements:Protein-fortified powders and meal replacement bars gain traction in health food stores and online retail channels. This application climbs the fastest as sports nutrition brands specify minimum protein thresholds in supplier contracts.
- Snack Foods:Extruded products and protein-enriched crackers utilize mid-range protein specifications. Contract manufacturers in Ohio and Pennsylvania corridors dominate procurement for private-label programs.
- Pasta:Durum wheat varieties with elevated protein support extrusion tolerance and cooking stability. Italian-American regional producers in New Jersey specify semolina grades with certified protein content.
Volume concentration anchors Baking; margin expansion concentrates in Nutritional Supplements.
End User:
Procurement scale determines specification stringency and certificate requirements.
- Bakeries:Artisan and commercial operations command concentrated margin pools through contract-based volume purchasing and customized protein level specifications. Direct miller relationships displace traditional distributors in urban food manufacturing corridors.
- Food Service:Institutional channels sustain volume advantages through centralized procurement and formulation consistency. National distributors require lot-level protein certificates with third-party verification.
- Households:Retail packaging emphasizes protein callouts under FDA updated Nutrition Facts labeling requirements. Supermarket placement depends on clean label positioning.
- Health Food Stores:Specialty retailers prioritize regenerative agriculture certifications and carbon intensity documentation. The EU Green Deal's Farm to Fork Strategy influences sourcing preferences for European imports.
Contract scale favors Bakeries; sustainability premium capture favors Health Food Stores.
Distribution Channel:
Channel structure determines traceability requirements and margin allocation.
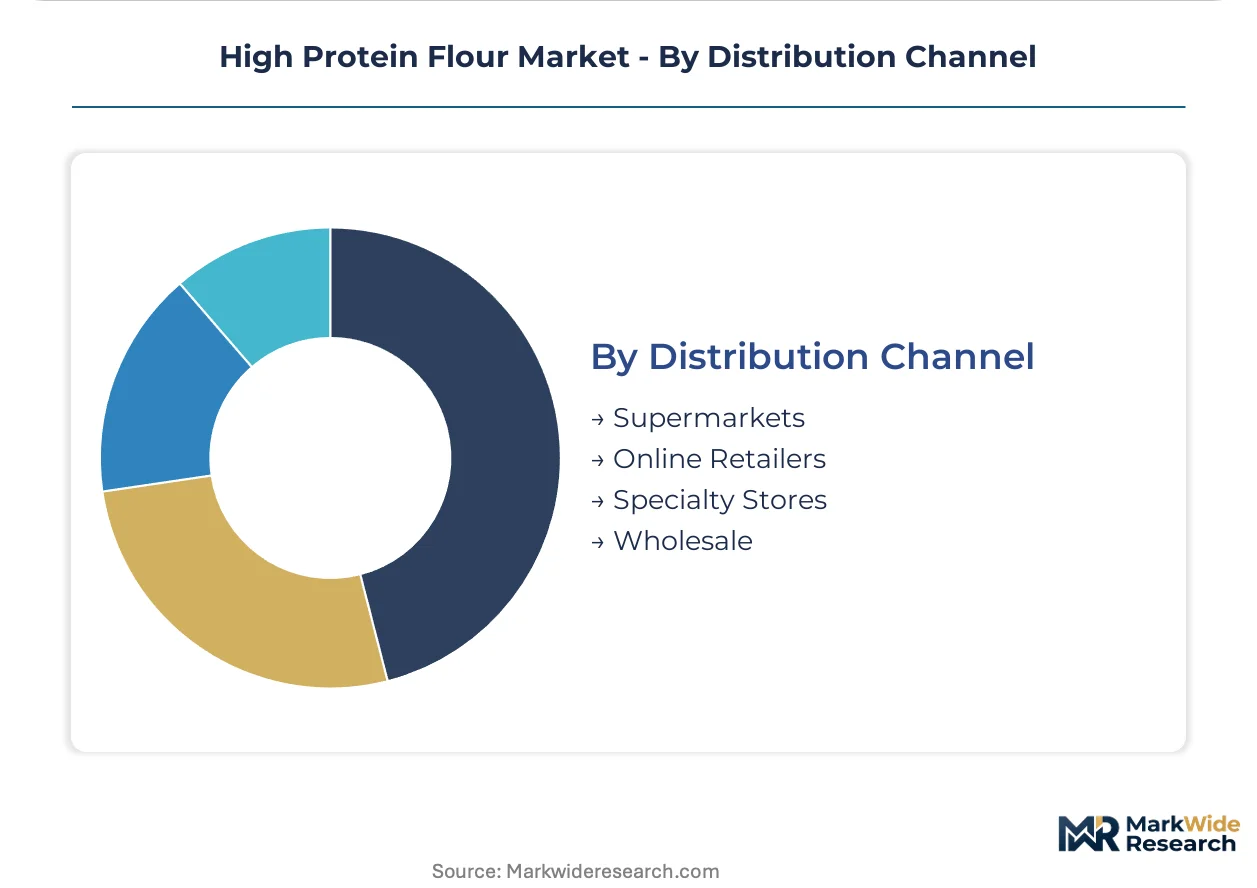
- Supermarkets:Mass retail placement demands consistent supply and standardized protein specifications. National brands compete for shelf space through promotional programming and loyalty data integration.
- Online Retailers:Subscription platforms enable specialty millers to bypass distributors and offer customized protein specifications. Direct-to-consumer fulfillment centers in Phoenix and Atlanta support this model.
- Specialty Stores:Independent retailers emphasize origin documentation and small-batch credentials. Urban corridors in Seattle and Austin show strongest trial rates for traceable supply chains.
- Wholesale:Food service distributors aggregate demand from institutional buyers and regional restaurant groups. Volume contracts stabilize offtake but compress margins for millers.
Volume throughput concentrates in Supermarkets; margin preservation favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium hard wheat pricing power concentrates in the northern Great Plains of the United States and Canadian prairies, while European millers capture sustainability premiums through regenerative agriculture certifications under the EU Green Deal. This geographic asymmetry shapes procurement strategies across major consuming regions.
United States
Commercial bakeries in Minneapolis and Kansas City corridors drive contract demand for 13-14% protein hard red spring wheat. The USDA Agricultural Marketing Service certifies protein content with tightened tolerances, compelling millers to invest in inline near-infrared spectroscopy. North Dakota and Montana elevators anchor premium wheat supply chains for national quick-service restaurant chains.
Canada
Prairie provinces of Alberta, Saskatchewan, and Manitoba export hard red spring wheat to US and Asian millers with protein premiums tied to certified grades. The Canadian Grain Commission enforces protein measurement protocols that align with USDA standards. Winnipeg-based trading houses coordinate cross-border offtake for protein-specified contracts.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia specify high-protein wheat for artisan bread production with carbon intensity documentation. The EU Green Deal's Farm to Fork Strategy mandates 25% organic farmland conversion by 2030. Hamburg millers capture shelf space premiums through regenerative agriculture certifications.
France
Boulangerie chains in Île-de-France and Auvergne-Rhône-Alpes source protein-enriched flour with traceability requirements. ANSM and EFSA frameworks govern allergen labeling and enrichment standards. Lyon and Paris metropolitan corridors show strongest trial rates for direct miller-to-baker procurement platforms.
United Kingdom
Artisan bakeries in London and Southeast England prioritize specialty blend formulations with customized protein specifications. The Food Standards Agency enforces allergen labeling under retained EU regulations. Manchester and Birmingham food manufacturing corridors displace traditional distributors through subscription-based miller relationships.
High Protein Flour Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in high protein flour milling. Integrated millers with captive grain elevator networks dominate volume throughput, while regional specialists capture margin through customized protein specifications and direct baker relationships. Three archetypes define competitive positioning: scale-driven national suppliers, specialty blend formulators, and regional direct-service millers. Consolidation pressure favors acquisition of regional specialists by integrated players, while technology licensing agreements spread inline protein measurement capabilities.
Among integrated North American millers, Ardent Mills, General Mills, and Archer Daniels Midland exemplify scale-driven archetypes with centralized procurement advantages. King Arthur Baking Company occupies a differentiated position as a specialty blend formulator serving artisan and commercial bakeries through direct relationships. These three anchors represent the spectrum from commodity volume to premium customization in protein-specified flour supply.
| Leading Market Players |
|---|
| Miller Milling Company |
| Bay State Milling Company |
| Archer Daniels Midland |
| King Arthur Baking Company |
| General Mills |
| Ardent Mills |
| Siemer Milling Company |
| The White Lily Foods Company |
| Central Milling |
| Others |
Supply & Pricing Matrix
USDA Agricultural Marketing Service protein certification gates both supply qualification and price differentiation simultaneously. Hard red spring wheat from North Dakota and Montana elevators commands protein premiums only after lot-level verification. Commercial bakeries in Minneapolis and Kansas City corridors pay configured-to-order spreads for 13-14% specifications versus standard 12% grades.
Pricing Analysis
Configured-to-order pricing spreads 8-15% above standard commodity grades for protein-specified hard wheat. Contract-based long-term offtake dominates, with price differentiation driven by protein certification tier and volume scale. Cost compression in mid-range specifications intensifies because enzymatic processing enables functional equivalence from lower-protein inputs. National quick-service restaurant chains show least price sensitivity due to dough performance mandates; regional artisan bakeries exhibit highest sensitivity to protein premiums.
Supply Chain Analysis
Just-in-time inventory strategies prevail among urban commercial bakeries, while strategic stockpiling characterizes national chain procurement. Supply concentrates in the United States, Canada, and Australia. Hard red winter and hard red spring wheat varieties, tempering equipment, and inline near-infrared spectroscopy systems constitute critical inputs. Single-source vulnerability runs through northern Great Plains weather exposure. Distribution runs through food service distributors and direct miller-to-baker digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high protein flour market tracks a cyclical recovery anchored to wheat harvest variability and protein content volatility. Premium hard wheat pricing power oscillates with northern Great Plains growing conditions.
For Market Incumbents: Consolidate regional specialist acquisitions to secure customized protein specification capabilities. Invest in backward integration into regenerative agriculture certification programs to defend against EU Green Deal compliance requirements. Channel control through direct-to-baker digital platforms offsets distributor margin compression. For New Entrants and Emerging Players: Direct-to-baker subscription service gaps expose incumbents' distributor dependency. Target artisan bakeries in London and Southeast England corridors through traceability-focused procurement platforms. Lead with carbon intensity documentation and small-batch credentials as the go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated food conglomerates' non-core milling assets. Long-term viability frames around protein fortification tailwinds in sports nutrition and elderly nutrition segments. Watch enzymatic protein modification adoption rates as the inflection indicator for premium hard wheat demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regenerative Agriculture Certification | EU Green Deal compliance secures shelf space premiums in French and German bakery chains. |
| Direct-to-Baker Digital Platform Launch | Subscription models bypass food service distributors and capture margin in urban corridors. |
| Inline Near-Infrared Spectroscopy Deployment | Real-time protein verification satisfies USDA Agricultural Marketing Service tightened tolerances. |
| Enzymatic Processing Capability Investment | Fungal amylase and transglutaminase deployment enables functional equivalence from lower-cost inputs. |
| Hybrid Flour Formulation Development | Pea protein isolate and wheat gluten combinations penetrate sports nutrition contract manufacturing. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation. Interviews encompassed milling operations directors, commercial bakery procurement leads, USDA Agricultural Marketing Service certification specialists, and food service distributor category managers. Secondary sources included USDA grain grading reports, FDA Food Allergen Labeling and Consumer Protection Act guidance documents, EU Farm to Fork Strategy implementation frameworks, and customs trade data for hard wheat flows. Bottom-up volume modeling and top-down market sizing triangulated segment outputs.
Across the projection horizon, the analytical framework modeled protein content tiers, wheat variety sourcing, application segments, end-user scale categories, and regional regulatory clusters. CAGRs derived from historical protein premium spreads, contract volume trajectories, and substitution elasticity estimates for enzymatic processing alternatives. Wheat harvest yield variability and protein content measurement protocol evolution served as industry-specific forecast inputs.
Underlying assumptions cover stable FDA enrichment standards and USDA certification continuity, with deviation risk concentrated in EU organic farmland conversion mandates and gluten-free substitution acceleration. Forecasts reflect these conditions with sensitivity to hard wheat supply concentration in weather-vulnerable regions. Revision becomes warranted when enzymatic protein modification cost curves cross premium hard wheat price thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Bean Ingredients Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Low Calorie Oil Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Global Egg White Peptide Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
North America Lipid Market
Ingredients
Plant Based Premix Market
Ingredients
Casein Hydrolysate Market
Ingredients
Canola Protein Market
Ingredients
Sunflower Protein Market
Ingredients
Cocoa Processing Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Cocoa Liquor Market
Ingredients
Coconut Oil Market