
 Plant Based Protein Beverages Market | 2026-2036
Plant Based Protein Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Protein Beverages Market Analytics
Asset-light contract manufacturing and third-party co-packing arrangements is narrowing the capital barrier for new entrants in plant-based protein beverages. Oatly Group AB leverages its proprietary enzymatic process to sustain premium positioning across European and North American retail channels. Califia Farms anchors its competitiveness through integrated almond sourcing and cold-brew coffee hybrid formulations. Danone S.A. dominates the mass-market shelf-stable segment through Silk's established grocery distribution network.
Plant-based protein beverages constitute ready-to-drink formulations containing isolated or concentrated proteins derived from legumes, grains, or nuts, typically processed through wet milling, enzymatic hydrolysis, and ultra-high temperature pasteurization to achieve shelf stability and amino acid bioavailability comparable to dairy equivalents. These products serve commercial purposes spanning post-exercise recovery, meal replacement, and allergen-free nutrition protocols in both retail and foodservice environments. Pea protein formulations exhibit the fastest volume trajectory among product types due to superior emulsion stability and neutral flavor profiles that accommodate clean-label positioning. Fitness enthusiasts command the deepest margin pool among end users, while online retailers represent the channel segment with the most aggressive growth cadence as subscription replenishment models reduce customer acquisition costs.
The FDA enforces nutrition labeling and health claim substantiation for plant-based beverages under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees organic certification pathways that command price premiums in mainstream retail. The EPA regulates water usage and effluent discharge from protein extraction facilities, particularly affecting almond and pea processing operations in drought-sensitive regions. Stakeholders must monitor evolving amino acid fortification standards and carbon labeling mandates that will determine which processing technologies secure preferred retail placement.
Market Dynamics
Fitness enthusiasts are reshaping formulation priorities as post-workout recovery protocols pivot toward dairy-free alternatives, compressing R&D cycles and forcing ingredient disclosure upgrades under tightening FDA standards.
Growth Catalysts
- Enzymatic Hydrolysis Advancement:Wet milling and ultra-high temperature pasteurization technologies are improving amino acid bioavailability to parity with dairy equivalents, unlocking clean-label positioning for mass-market penetration.
- FDA Labeling Modernization:Updated nutrition disclosure requirements for plant-based products are standardizing ingredient transparency, reducing consumer skepticism and accelerating trial rates among allergen-sensitive households.
- Pea Protein Emulsion Stability:Superior functional properties in pea-derived isolates are enabling neutral flavor profiles that accommodate reduced-sugar formulations without compromising texture.
Market Restraints
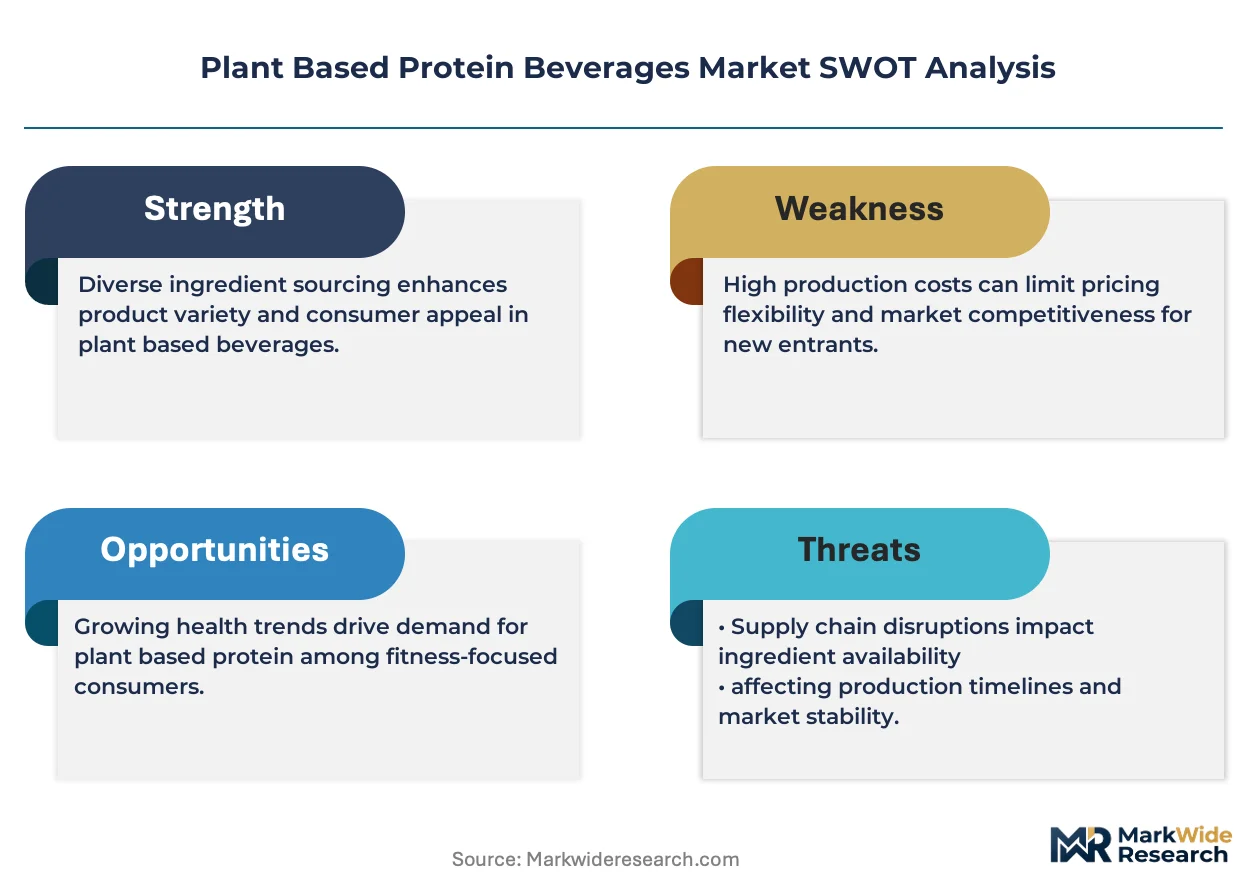
- Almond Water Intensity:Drought-sensitive cultivation regions in California face EPA effluent discharge scrutiny, elevating input cost volatility for nut-based protein extraction facilities.
- Amino Acid Fortification Complexity:Incomplete protein profiles in single-source formulations require expensive lysine and methionine supplementation to achieve nutritional equivalence with dairy.
- Shelf-Stable Distribution Concentration:Mass-market grocery networks dominated by legacy dairy alternatives limit premium pricing power for emerging protein beverage entrants.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Replenishment-based e-commerce platforms are reducing customer acquisition costs and capturing recurring revenue from fitness enthusiasts seeking personalized nutrition protocols.
- Specialty Coffee Chain Integration:Cold-brew coffee hybrid formulations are securing premium placement in United States foodservice channels, commanding price multiples over conventional retail.
- Organic Certification Pathways:USDA organic standards are unlocking price premiums in mainstream retail as consumers associate certification with processing integrity and environmental accountability.
Industry Challenges
- Carbon Labeling Mandate Readiness:Emerging disclosure requirements for processing emissions are forcing facility upgrades and supply chain traceability investments ahead of regulatory deadlines.
- Contract Manufacturing Quality Variance:Asset-light co-packing arrangements are introducing batch inconsistency risks that threaten brand equity and retail placement stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Protein Beverages Market |
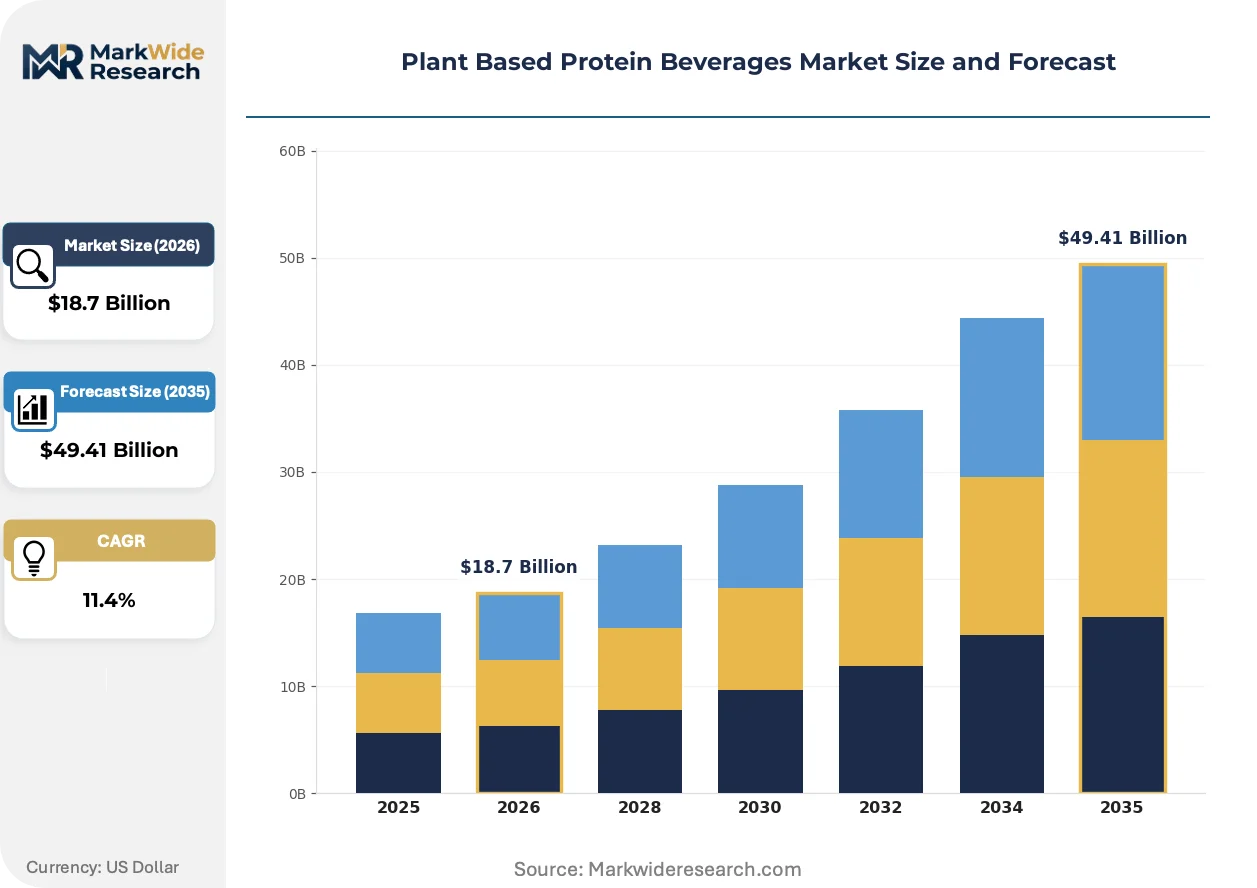
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Pea Protein, Almond Protein, Rice Protein End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Vegans Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Packaging Type: Bottles, Tetra Packs, Pouches, Cans |
| Companies Covered | Califia Farms, ALOHA, Ripple Foods, Malk Organic, Archer Daniels Midland Company, Kerry Group, Oatly Group AB, Silk, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Protein Beverages Market Evolving Landscape
Formulation science and distribution architecture are converging to redefine competitive positioning, with enzymatic processing capabilities and channel-specific product development emerging as decisive capability differentiators.
Precision fermentation-derived proteins are migrating from niche ingredient sourcing to mainstream formulation strategies. Specialty beverage manufacturers are adopting these inputs at accelerated cadences to bypass agricultural commodity cycles. The technology is compressing cost structures for high-purity isolates while enabling novel amino acid profiles previously unattainable through conventional extraction.
EPA water usage regulations are tightening effluent standards for protein extraction facilities operating in drought-sensitive watersheds. Industrial consequence includes mandatory closed-loop processing investments and geographic relocation of capacity toward water-secure regions. Pea and almond processing operations in California are responding through membrane filtration upgrades and alternative sourcing from Midwest cultivation zones.
Subscription replenishment models are displacing traditional retail trial-and-repeat purchase patterns among fitness enthusiasts. Direct-to-consumer platforms are capturing loyalty through personalized nutrition protocols and automated delivery scheduling. The United States represents the most visible geography for this shift, with specialty coffee chains simultaneously driving premium foodservice attachment for ready-to-drink formats.
Plant Based Protein Beverages Market Segmentation
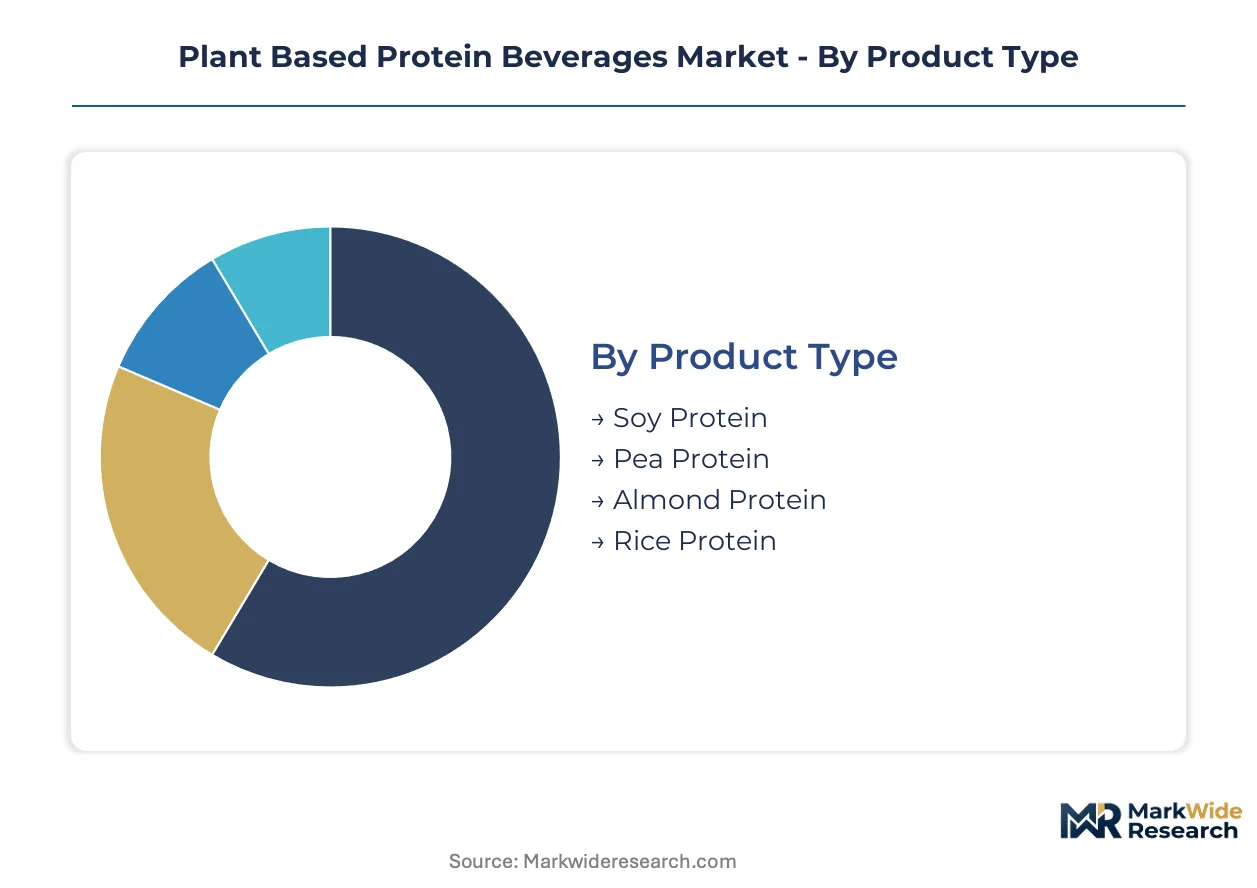
Plant-based protein beverages fragment across four distinct taxonomies that determine formulation chemistry, channel economics, and margin architecture. Product type dictates raw material sourcing and processing complexity, while end-user psychology shapes positioning from performance claims to ethical signaling.
Product Type:
Mature soy formulations coexist with emerging precision-fermented alternatives as enzymatic processing unlocks cleaner taste profiles.
- Pea Protein:Isolates derived from yellow split peas deliver superior emulsion stability and neutral flavor accommodation, enabling reduced-sugar clean-label positioning. Fitness enthusiasts in the United States drive the deepest demand concentration as post-workout recovery protocols abandon dairy.
- Soy Protein:Long-established concentrate and isolate formats retain cost advantages through decades of supply chain optimization, though allergen labeling constraints limit expansion in allergen-sensitive households. Health-conscious consumers in legacy markets sustain volume despite growth deceleration.
- Almond Protein:Byproduct utilization from almond milk production creates circular economy positioning, though California drought exposure elevates input cost volatility under EPA water scrutiny.
- Rice Protein:Hypoallergenic profiles capture vegan and elimination-diet segments where multi-source allergen avoidance is non-negotiable; brown rice concentrates dominate through amino acid fortification flexibility.
Pea protein handles the majority of throughput; almond protein is the fastest mover on share.
End User:
Volume concentration sits with health generalists while margin capture belongs to performance-oriented micro-segments.
- Fitness Enthusiasts:Post-exercise recovery rituals command premium pricing power and subscription loyalty through personalized nutrition protocols. Direct-to-consumer replenishment models in the United States reduce customer acquisition costs for this cohort.
- Athletes:Competitive and recreational performers require amino acid completeness with documented bioavailability, forcing lysine and methionine fortification investments that compress margins.
- Health-Conscious Consumers:Mainstream wellness seekers prioritize convenience and taste accessibility over performance metrics, sustaining mass-market grocery velocity.
- Vegans:Ethical alignment and environmental accountability drive purchase decisions, with USDA organic certification commanding measurable price premiums.
Fitness enthusiasts anchor revenue per liter; athletes are climbing the fastest on formulation investment intensity.
Distribution Channel:
Physical retail retains volume gravity while digital infrastructure reshapes customer lifetime value economics.
- Online Retailers:Subscription replenishment platforms capture recurring revenue through automated scheduling and personalized protocol matching. Fitness enthusiasts in the United States concentrate here, reducing churn through habit formation.
- Supermarkets:Mass-market shelf-stable placement demands slotting fee tolerance and promotional depth, favoring legacy dairy alternative portfolios with established grocery networks.
- Health Food Stores:Curated assortment and educated staff enable premium positioning for emerging brands with differentiated ingredient stories.
- Specialty Shops:Independent retailers and fitness center concessions command localized loyalty through community embedding and sampling access.
Supermarkets handle the majority of throughput; online retailers are gaining share fastest on customer acquisition efficiency.
Packaging Type:
Format selection balances shelf stability requirements, sustainability signaling, and consumption occasion matching.
- Tetra Packs:Aseptic carton technology enables ambient distribution with lower carbon footprint credentials than conventional alternatives, aligning with emerging carbon labeling mandates.
- Bottles:PET and rPET formats dominate ready-to-drink convenience with resealability for multi-serve occasions, though recycling infrastructure gaps limit circular claims.
- Cans:Aluminum delivers infinite recyclability and chill-speed advantages for foodservice and convenience channel penetration.
- Pouches:Flexible format reduces shipping cube and material weight, capturing on-the-go consumption with lower per-unit packaging cost.
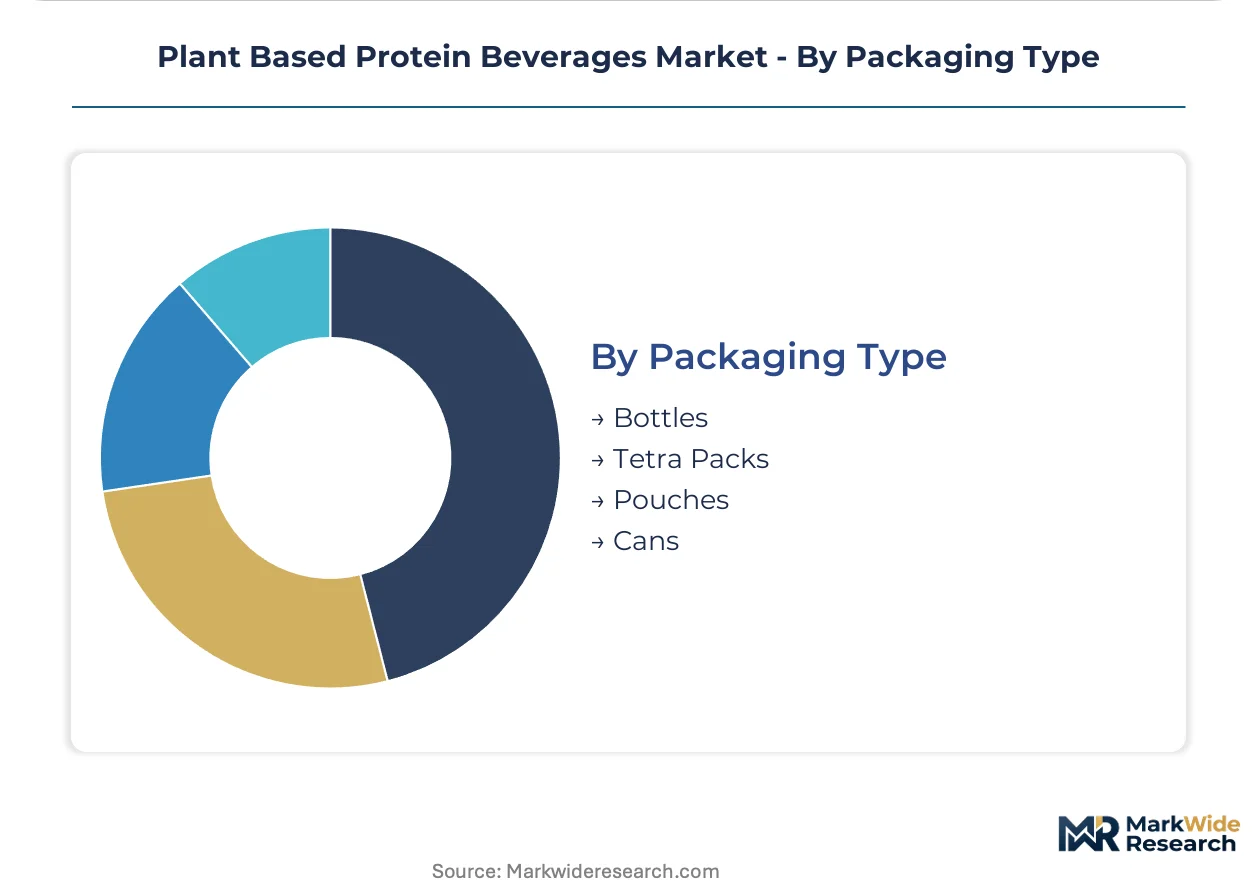
Bottles handle the majority of throughput; Tetra Packs are expanding most quickly on sustainability credentialing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts concentrate demand in the United States, where specialty coffee chains and direct-to-consumer subscription models anchor premium positioning. Germany and the United Kingdom follow as plant-based adoption accelerates in European retail. China and Brazil emerge as volume frontiers with distinct regulatory and supply chain architectures.
United States
Specialty coffee chains drive premium foodservice attachment for ready-to-drink formats, while direct-to-consumer subscription platforms capture recurring revenue from fitness enthusiasts. The FDA enforces updated nutrition labeling requirements for plant-based products under the Federal Food, Drug, and Cosmetic Act. California's Central Valley hosts concentrated almond and pea processing operations facing EPA water usage scrutiny.
Germany
Health-conscious consumers sustain mass-market grocery velocity for shelf-stable alternatives, with organic certification commanding measurable price premiums. EFSA standards govern health claim substantiation and amino acid fortification disclosures. Bavaria's food technology cluster hosts enzymatic processing facilities serving Central European distribution networks.
United Kingdom
Online retailers gain share fastest on customer acquisition efficiency as subscription replenishment models reduce churn through habit formation. The Food Standards Agency enforces allergen labeling constraints that limit soy protein expansion in sensitive households. London's specialty retail corridor anchors premium positioning for emerging brands with differentiated ingredient stories.
China
Urban health seekers prioritize convenience and taste accessibility over performance metrics, sustaining domestic brand velocity in tier-one cities. SAMR oversees nutrition labeling and protein content verification for plant-based beverages. The Yangtze River Delta hosts wet milling and enzymatic hydrolysis capacity serving Asia-Pacific export markets.
Brazil
Vegan and ethical-alignment consumers drive purchase decisions as environmental accountability claims gain traction in metropolitan centers. ANVISA regulates health claim substantiation and ingredient safety for protein-fortified beverages. São Paulo's food manufacturing belt concentrates contract packaging capacity for South American distribution.
Plant Based Protein Beverages Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented shelf-stable and premium fresh segments. Mass-market grocery networks favor legacy dairy alternative portfolios with established slotting fee tolerance, while direct-to-consumer platforms enable emerging entrants to bypass retail gatekeepers. Three archetypes dominate: integrated ingredient-to-brand operators, asset-light co-packers leveraging third-party manufacturing, and precision fermentation technology licensors. Competitive moves concentrate on strategic partnerships for enzymatic processing capabilities and geographic expansion through regional co-packing arrangements.
Within the integrated ingredient-to-brand tier, Danone S.A. and Oatly Group AB exemplify contrasting scale architectures. Califia Farms occupies a position bridging specialty coffee foodservice penetration with retail hybrid formulations. Kerry Group represents the ingredient-specialist archetype supplying enzymatic hydrolysis capabilities to brand marketers lacking in-house processing infrastructure.
| Leading Market Players |
|---|
| Califia Farms |
| ALOHA |
| Ripple Foods |
| Malk Organic |
| Archer Daniels Midland Company |
| Kerry Group |
| Oatly Group AB |
| Silk |
| Danone S.A. |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit cost volatility directly into pea protein isolate pricing, amplifying margin compression for California-based processors while enabling Midwest cultivation zones to capture arbitrage opportunities through rail-linked distribution to Chicago consolidation hubs.
Pricing Analysis
Cost-plus contracts indexed to the Food and Agriculture Organization pulse price index dominate pea protein procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by USDA organic certification and enzymatic processing depth. Brand premiums for established dairy-alternative portfolios command 15-25% markups over private-label equivalents in supermarket channels. Pricing pressure stems from EPA-mandated water recycling investments in California almond processing, which elevates unit economics for nut-derived isolates. Fitness enthusiasts exhibit lowest price sensitivity due to subscription lock-in, while mass-market health-conscious consumers drive volume through promotional responsiveness.
Supply Chain Analysis
Upstream yellow split pea feedstock concentrates in Canada, Russia, and France, with wet milling capacity clustering in Manitoba and Saskatchewan to exploit rail export advantages. Almond protein draws from California Central Valley byproduct streams, exposing formulations to drought-induced harvest volatility. Single-source vulnerability pervades enzymatic hydrolysis equipment, with German and Danish engineering houses controlling membrane filtration system supply. Distribution runs through temperature-controlled intermodal networks serving direct-to-consumer fulfillment centers in Texas and Pennsylvania, bypassing traditional grocery warehouse concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specialty coffee chain procurement consolidation and subscription platform aggregation, fragmenting supplier pricing leverage as direct-to-consumer channels disintermediate legacy retail gatekeepers.
For Market Incumbents: Pre-empt precision fermentation entrants by securing exclusive enzymatic processing partnerships with Kerry Group and accelerating USDA organic certification across Midwest pea sourcing networks. Channel control through direct-to-consumer subscription infrastructure represents the critical defensive lever against emerging asset-light co-packers threatening brand equity through batch inconsistency. For New Entrants and Emerging Players: Mid-market fitness enthusiasts in secondary United States metropolitan areas represent the most penetrable entry point, with cold-brew coffee hybrid formulations offering differentiated positioning against established soy and almond portfolios. Specialty health food stores in Germany and the United Kingdom provide lower slotting-fee barriers than mass grocery, while personalized nutrition protocol subscriptions enable customer acquisition cost efficiency comparable to digital-native incumbents. For Investors and Strategic Acquirers: Asset-light contract manufacturers with proprietary enzymatic capabilities and established retail co-packing relationships constitute the highest-conviction acquisition archetype for platform consolidation. Long-term viability hinges on carbon labeling mandate readiness and water-secure processing geography positioning. Monitor EPA effluent discharge enforcement intensity in California as the decisive inflection signal for input cost trajectory and facility relocation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Bypasses agricultural commodity cycles for amino acid profile customization at compressed cost structures. |
| Direct-to-Consumer Platform Launch | Captures recurring revenue from fitness enthusiasts through automated replenishment and personalized protocols. |
| USDA Organic Certification Investment | Unlocks measurable price premiums in mainstream retail as consumers associate certification with processing integrity. |
| Midwest Processing Facility Expansion | Reduces California water exposure while exploiting rail-linked distribution to Chicago consolidation hubs. |
| Specialty Coffee Chain Integration | Secures premium foodservice placement commanding price multiples over conventional retail channels. |
Research Methodology
Initial hypotheses were tested against primary input from plant-based beverage brand managers, enzymatic processing technology directors, specialty coffee chain procurement leads, and direct-to-consumer platform operators, then refined through secondary validation against FDA nutrition labeling guidance documents, USDA organic certification databases, EPA effluent discharge enforcement records, and trade flow data from U.S. Customs and Border Protection. Bottom-up volume modeling triangulated with top-down market sizing across ingredient sourcing, processing capacity, and channel throughput dimensions.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling incorporating protein source type, end-user psychology archetype, distribution channel format, and packaging technology tier. CAGRs were derived from trend extrapolation of volume trajectories and price elasticity estimates. Forecast inputs included EPA regulatory enforcement intensity projections and precision fermentation technology cost curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices, ocean freight rates, or drought severity patterns would shift the trajectory of input cost assumptions and regional processing economics. Cross-checking against FAO pulse price benchmarks and Drewry container freight indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Yerba Mate Market
Beverages
South America Energy Drink Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Health Drinks Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Global Beverage Emulsion Market
Beverages
Tonic Water Market
Beverages
Mixers Market
Beverages
Fermented Foods and Beverages Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Aloe Vera Drinks Market
Beverages
Orange Juice Market
Beverages
Wellness Water Market
Beverages
Coconut Water Market
Beverages
India Soy Beverages Market