
 Global Vinegar Market | 2026-2036
Global Vinegar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vinegar Market Outlook
Italy is tilting its balsamic vinegar production capacity toward premium export channels. Acetum S.p.A. leverages extended barrel-aging protocols to sustain price premiums in North American and Asian retail. Mizkan Holdings Co., Ltd. anchors its competitive position through deep vertical control over rice vinegar supply chains across East Asia. Burg Groep B.V. competes on scale, operating one of Europe's largest white vinegar fermentation facilities for industrial food processing clients.
Vinegar is an aqueous solution containing acetic acid, typically produced through bacterial oxidation of ethanol with concentrations ranging from 4% to 8% acidity by volume, serving as a preservative, acidulant, and flavoring agent across food manufacturing and household applications. Balsamic and apple cider categories command the deepest margin pools, with aged balsamic from Modena and organic apple cider variants capturing disproportionate shelf-space investment in premium retail channels. Glass bottle packaging dominates positioning for artisanal and gift-segment vinegar, while bulk containers anchor food processing procurement economics.
The FDA governs vinegar acidity standards and labeling claims in the United States, while the EU's CE marking and EFSA food-additive frameworks shape product formulation and cross-border trade compliance for European producers. China's SAMR enforces GB standards on fermented vinegar, directly influencing export eligibility for domestic manufacturers like Shanxi Shuita Vinegar. Stakeholders must monitor divergence between organic certification regimes and emerging plastic-packaging restrictions, as these will determine which production configurations retain market access across major consuming regions.
Market Dynamics
The EU F-Gas Regulation and China's dual carbon goals are compressing packaging material choices while amplifying clean-label fermentation investments across production networks.
Growth Catalysts
- Clean-label fermentation protocols:Food processing manufacturers in North America and Western Europe are mandating additive-free acidulant sourcing, pulling volume toward traditional acetobacter-based methods.
- EU Green Deal packaging mandates:The European Commission's circular economy action plan is accelerating glass bottle and recyclable material adoption in premium vinegar segments.
- China:Domestic consumption of Shanxi aged vinegar and export positioning through SAMR-certified GB standards are concentrating capacity expansion in Shanxi and Jiangsu provinces.
Market Restraints
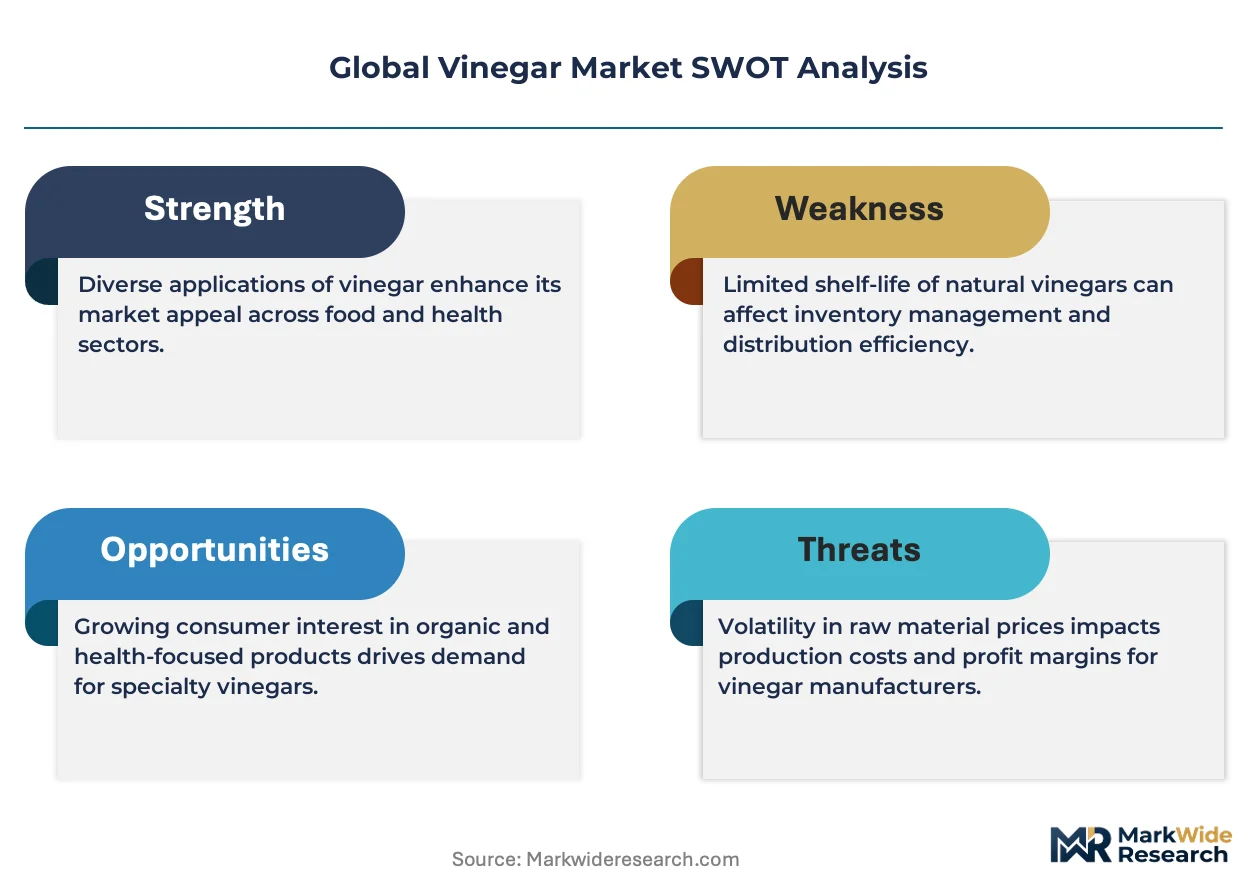
- Input cost volatility:Barley and rice substrate prices fluctuate with agricultural commodity cycles, squeezing margin stability for bulk white vinegar producers.
- Supply concentration risk:Barrel-aging capacity for authentic balsamic vinegar clusters in Modena province, creating bottleneck vulnerability for premium export channels.
- Substitution threat:Citric acid and phosphoric acid alternatives compete in industrial food processing applications where cost minimization dominates sourcing decisions.
Strategic Opportunities
- Southeast Asia underpenetration:Vietnam, Thailand, and Indonesia present white-space expansion for rice vinegar variants adapted to local cuisine profiles.
- Functional vinegar convergence:Probiotic and apple cider vinegar formulations are merging with wellness beverage channels, opening pharmacy and direct-to-consumer distribution.
- USDA organic certification tailwind:The National Organic Program's updated processing standards are incentivizing certified organic apple cider vinegar capacity additions.
Industry Challenges
- Master blender talent scarcity:Traditional balsamic vinegar production requires decades-trained expertise in barrel rotation and acetification monitoring, with aging practitioner populations.
- Legacy equipment integration:Automated fermentation control systems must interface with century-old wooden barrel infrastructure without compromising organoleptic profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vinegar Market |
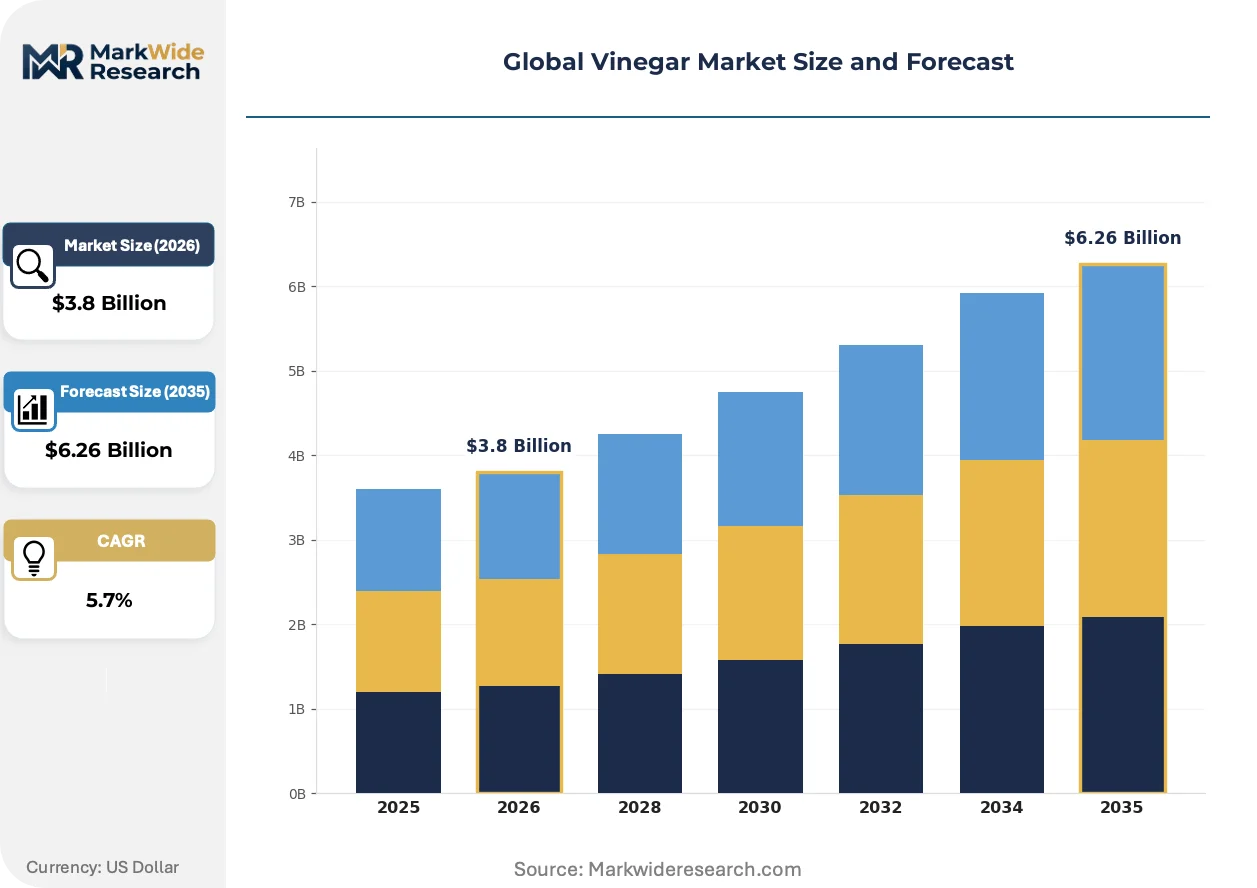
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Apple Cider, Balsamic, Red Wine, White Wine Application: Food Preservation, Salad Dressing, Marinades, Beverage Additive Packaging Type: Glass Bottles, Plastic Bottles, Pouches, Bulk Containers End User: Household, Restaurants, Food Processing, Retail |
| Companies Covered | Mizkan Holdings Co., Ltd., The Kraft Heinz Company, Acetum S.p.A., Burg Groep B.V., Australian Vinegar, Aspall, Carl Kühne KG, Shanxi Shuita Vinegar, Bizen Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vinegar Market Strategic Shifts
Accelerated fermentation technologies and regulatory packaging mandates are compressing traditional production timelines while fragmenting distribution channels across direct-to-consumer and industrial procurement pathways.
Continuous submerged fermentation systems utilizing immobilized acetobacter cells are reducing balsamic vinegar aging from years to months. Mid-tier producers in Emilia-Romagna are adopting these bioreactor configurations to meet volume commitments. Extended barrel-aging protocols for DOP certification are rendering obsolete shorter-cycle competitive positioning in premium retail.
REACH chemical safety evaluations and the EU F-Gas Regulation are tightening specifications for packaging adhesives and sealing materials in glass bottle formats. Italian and Spanish exporters are reformulating label substrates and cap liners to maintain CE marking compliance. Organic and DOP-certified segments face the steepest reformulation timelines given certification body notification requirements.
Direct-to-consumer subscription models for artisanal vinegar assortments are displacing traditional retail slotting fee structures. Specialty food e-commerce platforms in Germany and the United Kingdom are capturing household vinegar purchasers seeking variety packs and barrel-aged exclusives. This channel rotation is most pronounced in gift-segment balsamic and flavored vinegar categories where provenance storytelling drives repeat purchase behavior.
Global Vinegar Market Segmentation
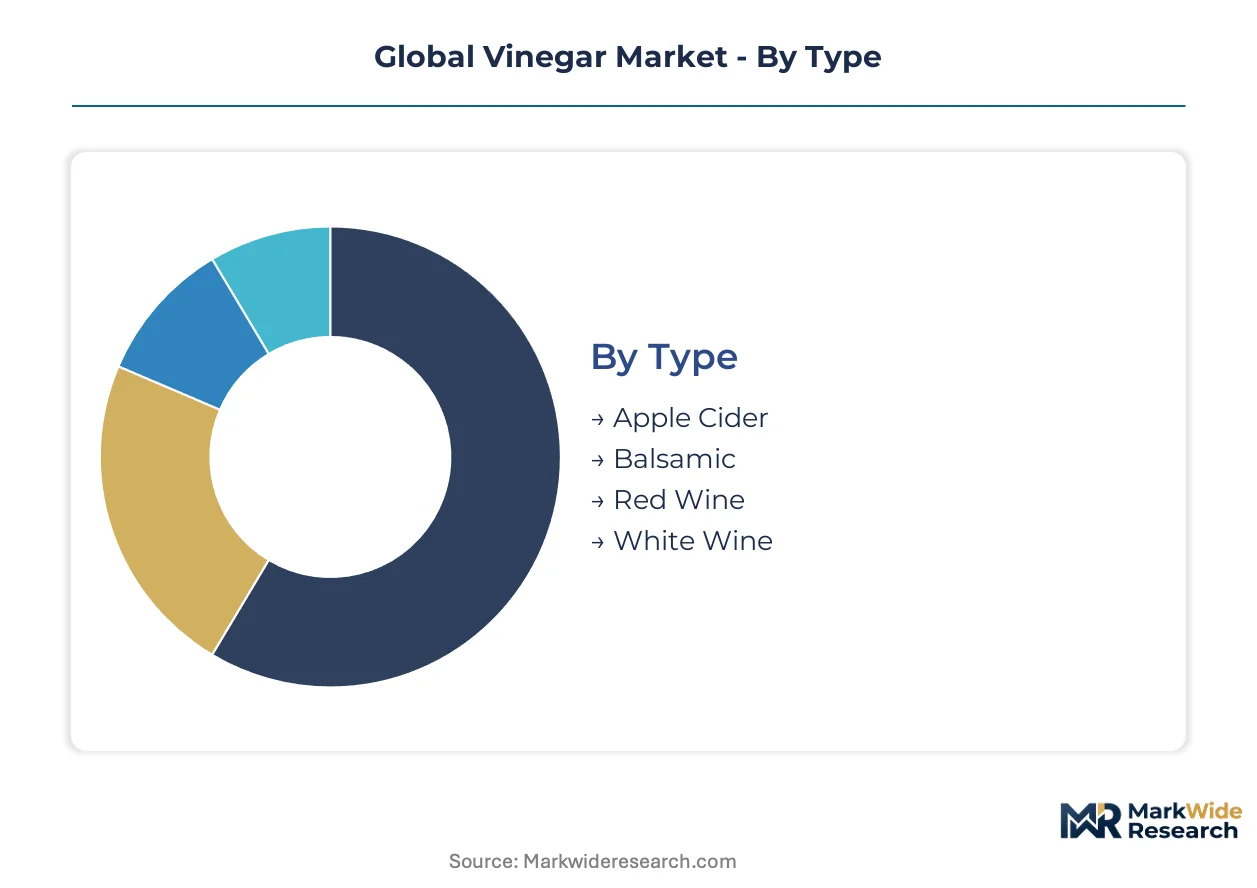
Vinegar segmentation maps directly to margin architecture and channel economics. Type differentiation governs price positioning from commodity white wine to aged balsamic. Packaging and end-user splits determine manufacturing scale and regulatory compliance intensity across production networks.
Type:
After-sales intensity concentrates in barrel-aged categories requiring provenance verification and storage guidance.
- Apple Cider:Fermented apple juice yielding 5-6% acetic acid with pronounced fruit ester profiles. Wellness beverage channels in North America and pharmacy retail in Germany are pulling organic and unfiltered variants. This segment holds the largest share; momentum sits with probiotic-infused formulations.
- Balsamic:Grape must acetified through sequential barrel aging in oak, chestnut, and cherry wood. DOP-certified production clusters in Modena province, with export demand concentrating in Japanese gift retail and US specialty food e-commerce. Extended aging protocols create 10-40 year inventory cycles that constrain volume scaling.
- Red Wine:Derived from Cabernet and Merlot varietals with 6-7% acidity, anchoring Mediterranean cuisine applications in Spanish and French household segments. Bulk procurement dominates food service channels.
- White Wine:Neutral flavor profile from Chardonnay or Sauvignon Blanc bases, preferred in French and German industrial mayonnaise and sauce manufacturing for color stability.
Balsamic commands premium shelf space; apple cider climbs the fastest on functional positioning.
Application:
Cost tier stratification separates artisanal small-batch from industrial commodity procurement.
- Food Preservation:Acetic acid inhibits microbial growth through pH reduction below 4.6. Pickling operations in Poland and Vietnam are scaling automated brine systems that specify standardized 5% acidity white vinegar.
- Salad Dressing:Emulsion stability requirements favor wine vinegar blends with 6-8% acidity. Italian and California premium dressing manufacturers are mandating DOP balsamic for retail label claims.
- Marinades:Enzymatic tenderization combines with flavor penetration in Korean and Brazilian protein processing. Rice vinegar variants dominate East Asian applications.
- Beverage Additive:Shrubs and drinking vinegars in US and UK direct-to-consumer channels require diluted 4-5% acidity with fruit adjuncts. This application expands most quickly.
Food preservation anchors volume; beverage additive gains share fastest on wellness trends.
Packaging Type:
Volume throughput determines material selection between premium positioning and logistics efficiency.
- Glass Bottles:Inert barrier properties protect organoleptic integrity across multi-year shelf life. Italian exporters to Japan and the US are reformulating cap liners to meet REACH adhesive standards under EU F-Gas Regulation timelines.
- Plastic Bottles:PET and HDPE formats reduce freight cost for white vinegar in Brazilian and Indonesian mass retail. Migration testing requirements under EFSA frameworks constrain recycled content ratios.
- Pouches:Flexible laminate structures penetrate South Korean and Thai single-serve condiment markets. Stand-up formats reduce shipping cube versus rigid alternatives.
- Bulk Containers:IBC totes and stainless steel tanks supply German and Dutch industrial mayonnaise manufacturers. Tote return logistics networks concentrate around Rotterdam and Hamburg port zones.
Glass bottles dominate premium positioning; pouches represent the steepest expansion trajectory in Asian convenience retail.
End User:
Customer type dictates formulation specificity and certification burden across procurement pathways.
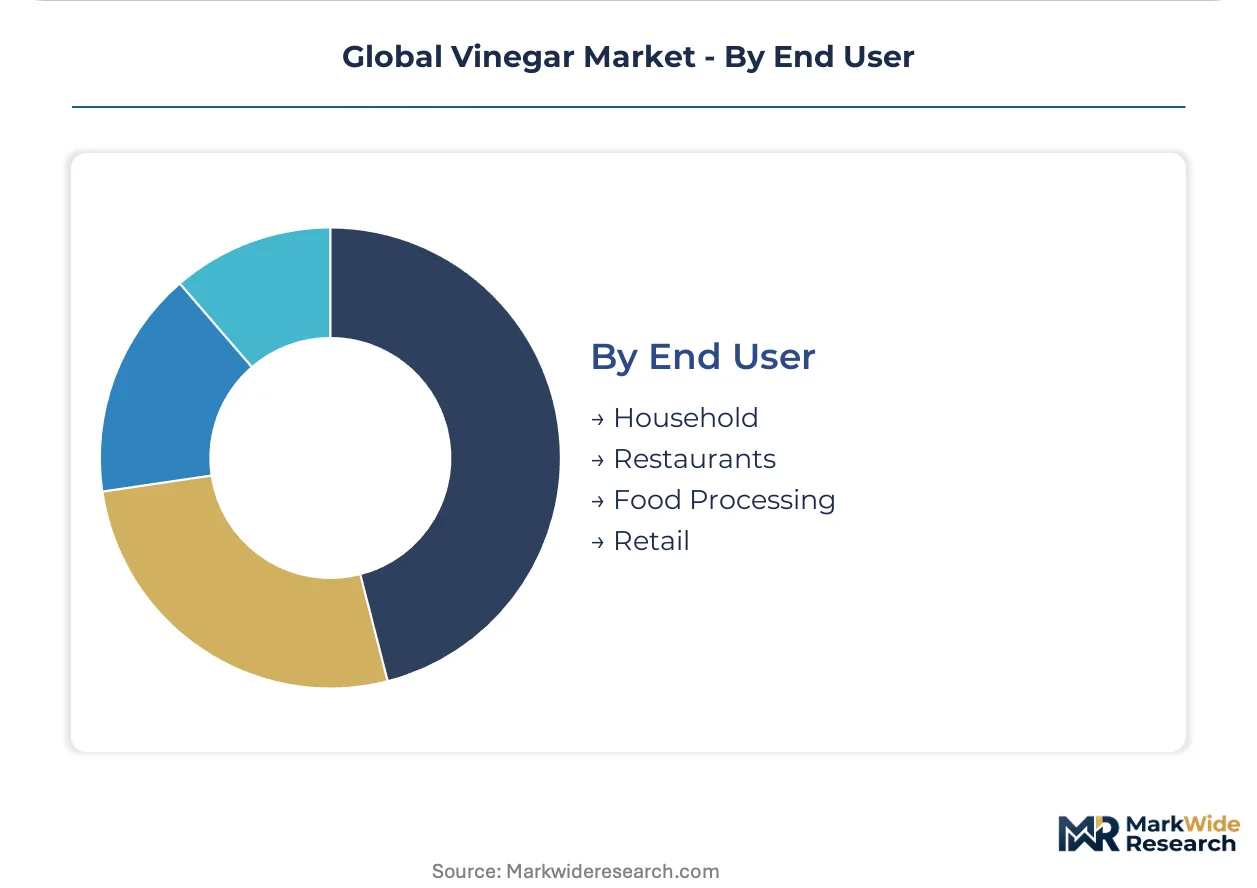
- Household:Supermarket and e-commerce channels in France, the US, and Japan drive assortment breadth from commodity white wine to aged balsamic gift sets. Subscription models displace traditional slotting fees in UK and German specialty platforms.
- Restaurants:Food service distributors in Italy and Spain specify 5-liter bag-in-box formats for back-of-house efficiency. Michelin-tier establishments in Paris and Tokyo maintain dedicated balsamic supplier relationships with barrel rotation services.
- Food Processing:Industrial acidulant procurement in the US and Germany prioritizes 200-liter drum white vinegar with batch consistency certificates. Clean-label mandates from North American manufacturers are pulling volume toward traditional acetobacter methods.
- Retail:Private label programs in UK and Australian supermarkets specify co-manufactured wine vinegar blends with retailer-branded packaging. Organic certification requirements extend formulation timelines.
Food processing commands procurement volume; household segments gain share fastest on channel fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrel-aging capacity for authentic balsamic vinegar clusters in Modena province, while rice vinegar fermentation concentrates in China's Shanxi and Jiangsu provinces. These supply nodes anchor export positioning for premium and commodity grades respectively.
United States
Wellness beverage channels and pharmacy retail are pulling organic apple cider vinegar volumes. The FDA enforces acidity standards and labeling claims that shape formulation compliance. California and New York Metro anchor direct-to-consumer subscription growth for artisanal assortments.
China
Domestic consumption of Shanxi aged vinegar and export positioning through SAMR-certified GB standards are driving capacity expansion. The country's dual carbon goals are compressing packaging material choices. Shanxi and Jiangsu provinces concentrate fermentation infrastructure for traditional acetobacter-based methods.
Italy
Premium export channels for DOP-certified balsamic are tilting production capacity toward gift-segment retail. The EU F-Gas Regulation and REACH chemical safety evaluations are tightening packaging adhesive specifications. Modena province maintains barrel-aging inventory cycles spanning 10-40 years.
Japan
Rice vinegar variants adapted to local cuisine profiles anchor household and industrial procurement. METI standards influence food-additive frameworks for cross-border trade. Tokyo and Osaka metropolitan areas concentrate distribution for premium import categories including aged balsamic.
Germany
Industrial mayonnaise and sauce manufacturers prioritize bulk white vinegar with batch consistency certificates. The EU Green Deal packaging mandates are accelerating recyclable material adoption. Hamburg and Rotterdam port zones anchor tote return logistics networks for food processing clients.
Global Vinegar Market Competitive Environment
Heritage barrel-aging specialists and scale-driven fermentation operators split the market along premium-commodity fault lines. The vendor base organizes around three strategic archetypes: traditional DOP-certified balsamic houses with decades-trained master blenders, vertically integrated rice vinegar producers controlling upstream substrate supply, and industrial white vinegar operators serving food processing procurement at volume tier. Competitive moves concentrate on capacity expansion in SAMR-certified Chinese facilities and portfolio diversification into functional wellness formulations.
Within the heritage archetype, Acetum S.p.A. represents extended barrel-aging protocols for North American and Asian retail positioning. Mizkan Holdings Co., Ltd. anchors the vertically integrated tier through captive supply chain structures across East Asia. Burg Groep B.V. occupies the scale-driven position with fermentation infrastructure serving European industrial food processing clients.
| Leading Market Players |
|---|
| Mizkan Holdings Co., Ltd. |
| The Kraft Heinz Company |
| Acetum S.p.A. |
| Burg Groep B.V. |
| Australian Vinegar |
| Aspall |
| Carl Kühne KG |
| Shanxi Shuita Vinegar |
| Bizen Chemical Co. |
| Others |
Value Chain & Pricing Dynamics
Modena province's barrel-aging capacity anchors premium balsamic pricing power through decade-long inventory cycles that constrain volume scaling and sustain DOP certification premiums in Japanese gift retail and US specialty food e-commerce. The concentration of authentic acetification expertise in this Emilia-Romagna cluster amplifies price inelasticity for aged inventories while compressing margins for mid-tier producers adopting accelerated bioreactor methods.
Pricing Analysis
EU F-Gas Regulation and REACH chemical safety evaluations dictate the pricing tier structure across glass bottle formats, with reformulation costs for adhesive-compliant cap liners and label substrates layering compliance premiums onto organic and DOP-certified segments. Three-tier pricing structure across premium, standard, and economy levels separates decades-aged DOP balsamic from mid-tier bioreactor output and commodity white vinegar. Cost compression in bulk white vinegar intensifies because rice and barley substrate volatility squeezes margin stability for industrial food processing suppliers. Food processing procurement teams exhibit highest price sensitivity due to citric acid substitution availability, while gift-segment household purchasers in Tokyo and New York Metro demonstrate lowest sensitivity to provenance-driven premiums.
Supply Chain Analysis
Extended payment terms from Italian exporters to Japanese distributors and supply-chain finance facilities at Rotterdam port zones lubricate working capital across the value chain. Geographic supply concentration centers on Italy for DOP balsamic, China for rice vinegar fermentation in Shanxi and Jiangsu provinces, and the Netherlands for industrial white vinegar scale. Raw material dependencies draw from grape must, rice substrates, and barley feedstocks. Single-source vulnerability clusters around Modena's master blender talent scarcity and aging practitioner populations. Distribution runs through Hamburg and Rotterdam tote return logistics networks for food processing clients, with direct-to-consumer subscription platforms displacing traditional retail slotting structures in UK and German specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vinegar distribution platforms are consolidating around interoperability between artisanal provenance storytelling and industrial procurement standardization, with clean-label fermentation protocols emerging as the dominant ecosystem coordination mechanism across North American and Western European food processing networks.
For Market Incumbents: Build certification moats through accelerated SAMR-certified GB standard compliance in Chinese facilities and DOP inventory deepening in Modena. Invest in automated fermentation control systems that interface with century-old wooden barrel infrastructure without compromising organoleptic profiles. Secure backward integration into rice substrate supply across East Asia to defend against barley price volatility squeezing bulk white vinegar margins. Channel control through direct-to-consumer subscription platforms insulates against specialty food e-commerce platform disintermediation.
For New Entrants and Emerging Players: Functional wellness vinegar convergence in US and UK pharmacy and direct-to-consumer channels represents the most penetrable entry point, with probiotic-infused apple cider formulations merging beverage and supplement retail. Southeast Asian white-space in Vietnam, Thailand, and Indonesia offers rice vinegar variants adapted to local cuisine profiles with limited incumbent saturation. Co-manufacturing partnerships with established fermentation operators reduce capital intensity for organic certification compliance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated rice vinegar specialists with captive substrate supply and SAMR-certified export infrastructure. Long-term viability rests on dual carbon goal alignment in Chinese production networks and EU Green Deal packaging mandate compliance for European market access. Acquisition targets should demonstrate master blender succession planning or automated acetification monitoring capabilities. The signal to watch is divergence between organic certification regimes and emerging plastic-packaging restrictions determining market access retention.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Shanxi and Jiangsu province fermentation infrastructure additions align with SAMR-certified GB standard export positioning. |
| Backward Integration | Rice substrate supply chain control secures margin stability against agricultural commodity cycle volatility. |
| Green Manufacturing Transition | EU F-Gas Regulation compliance for packaging adhesives preserves CE marking access for Italian exporters. |
| Long-term Supply Agreement | Industrial mayonnaise manufacturers in Hamburg anchor procurement through Rotterdam tote return logistics networks. |
| Joint Venture | Co-manufacturing partnerships accelerate organic certification timelines for private label programs in UK supermarkets. |
Study Parameters
The analysis maps barrel-aged balsamic, rice vinegar, apple cider wellness formulations, and industrial white vinegar acidulants, each validated through master blenders, food processing procurement leads, specialty food e-commerce platform operators, and SAMR regulatory affairs specialists. Primary interviews with fermentation facility managers, barrel-aging cooperage operators, and clean-label mandate compliance officers combined with secondary validation from FDA acidity standard filings, EFSA food-additive framework updates, SAMR GB standard documentation, and EU F-Gas Regulation implementation guidance. Bottom-up volume triangulation across production facility outputs and top-down demand validation through retail channel audits anchored the analytical framework.
Assumptions held fixed include current regulatory enforcement intensity across FDA, EFSA, and SAMR jurisdictions, while substrate price volatility and certification regime divergence were modeled as scenario variables across the analysis window. Segmentation dimensions encompassed vinegar type, application, packaging format, and end-user procurement pathway, with CAGRs derived from production capacity expansion trajectories and channel shift elasticity. Forecast inputs incorporated barrel-aging inventory cycle durations, automated fermentation adoption curves, and direct-to-consumer subscription platform penetration rates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity cycles, carbon-neutrality mandate acceleration, or trade restriction implementation would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Juices Market
Beverages
Japan Kombucha Market
Beverages
Carbonate Drink Maker Market
Beverages
Hydration Infusers Market
Beverages
United States Smoothie Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Apple Cider Vinegar Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Caffeine-Based Drinks Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
Bubble Food and Beverages Market
Beverages
Superfood Infused Beverages Market
Beverages
Juice Concentrates Market
Beverages
Sparkling Water Machine Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Europe Bottled Water Market