
 Probiotic Beverage Market | 2026-2036
Probiotic Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Beverage Market Insights
The probiotic beverage category is expanding along a sharp split between premium live-culture products with verified strain counts and commodity-positioned drinks with minimal functional credibility. Danone SA leverages its refrigerated supply chain to sustain probiotic viability claims across mass retail. Yakult Honsha Co. Ltd anchors its position through dedicated home-delivery networks and single-strain specialization. Chobani LLC differentiates via plant-based formulations that compete for shelf space against traditional dairy probiotic lines.
Probiotic beverages are non-alcoholic drinks containing live microorganisms, typically Lactobacillus or Bifidobacterium strains at minimum viable counts of 10^6 to 10^9 CFU per serving, formulated to deliver digestive or immune benefits through regular consumption. Kefir dominates volume due to established dairy infrastructure, while kombucha captures faster velocity through organic positioning and lower sugar profiles. Plant-based formulations within the formulation dimension are attracting capital as oat and coconut substrates solve allergen constraints that limit dairy-based penetration.
EFSA health claim regulations in Europe and FDA GRAS notifications in the United States enforce stringent substantiation for live-culture efficacy, compressing margins for brands lacking clinical trial backing. Japan's FOSHU system creates a separate compliance pathway that rewards verified functional strains with premium pricing authority. Stakeholders must monitor evolving strain patent landscapes and refrigeration cost inflation as these forces determine which product tiers maintain distribution access.
Market Dynamics
Refrigerated distribution infrastructure expansion is concentrating viable live-culture supply chains in markets with cold-chain density, forcing brands to co-locate production with population centers or absorb spoilage losses that erode strain-count claims.
Growth Catalysts
- EFSA strain-specific labeling mandates:European verification requirements reward clinically substantiated products with shelf-space access, filtering out commodity competitors lacking CFU documentation.
- Home-delivery network specialization:Dedicated cold-chain logistics in Japan sustain viability guarantees for daily-consumption formats that mass retail refrigeration cannot match.
- Plant-based substrate innovation:Oat and coconut fermentation protocols eliminate dairy allergen barriers, opening penetration into lactose-intolerant consumer segments previously excluded from live-culture benefits.
Market Restraints
- Refrigeration cost inflation:Energy-intensive cold-chain requirements compress margins for mid-tier brands unable to pass through electricity and logistics escalation to price-sensitive retail channels.
- Clinical trial substantiation barriers:FDA GRAS notification pathways and EFSA health claim dossiers demand multi-year, multi-million-euro efficacy studies that exclude smaller market entrants lacking pharmaceutical-grade R&D infrastructure.
- Kombucha spoilage sensitivity:Unpasteurized, low-pH formulations face accelerated microbial instability during temperature excursions, constraining distribution radius and retail authorization.
Strategic Opportunities
- Pediatric formulation white space:Strain-tailored, low-sugar live-culture beverages for early childhood immune development remain underdeveloped in North American and European retail despite parental willingness to pay verified premiums.
- Sports nutrition channel expansion:Post-exercise gut microbiome recovery positioning targets endurance athletes through specialty running and cycling retail, bypassing conventional grocery slotting fees.
- Japan FOSHU premium pathway:Verified functional strain authorization under the Foods for Specified Health Uses system commands 40-60% price premiums over unverified live-culture competitors in convenience retail.
Industry Challenges
- Strain patent licensing complexity:Proprietary Lactobacillus and Bifidobacterium isolates held by pharmaceutical and ingredient suppliers require per-unit royalty structures that complicate margin forecasting and long-term cost planning.
- CFU count degradation monitoring:End-of-shelf-life viable culture verification demands specialized laboratory partnerships or in-house microbiology capacity that strains operational resources at scale.
- Cross-category regulatory ambiguity:Beverage-dairy-supplement boundary classifications vary by jurisdiction, forcing dual compliance preparation or market-specific formulation adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Beverage Market |
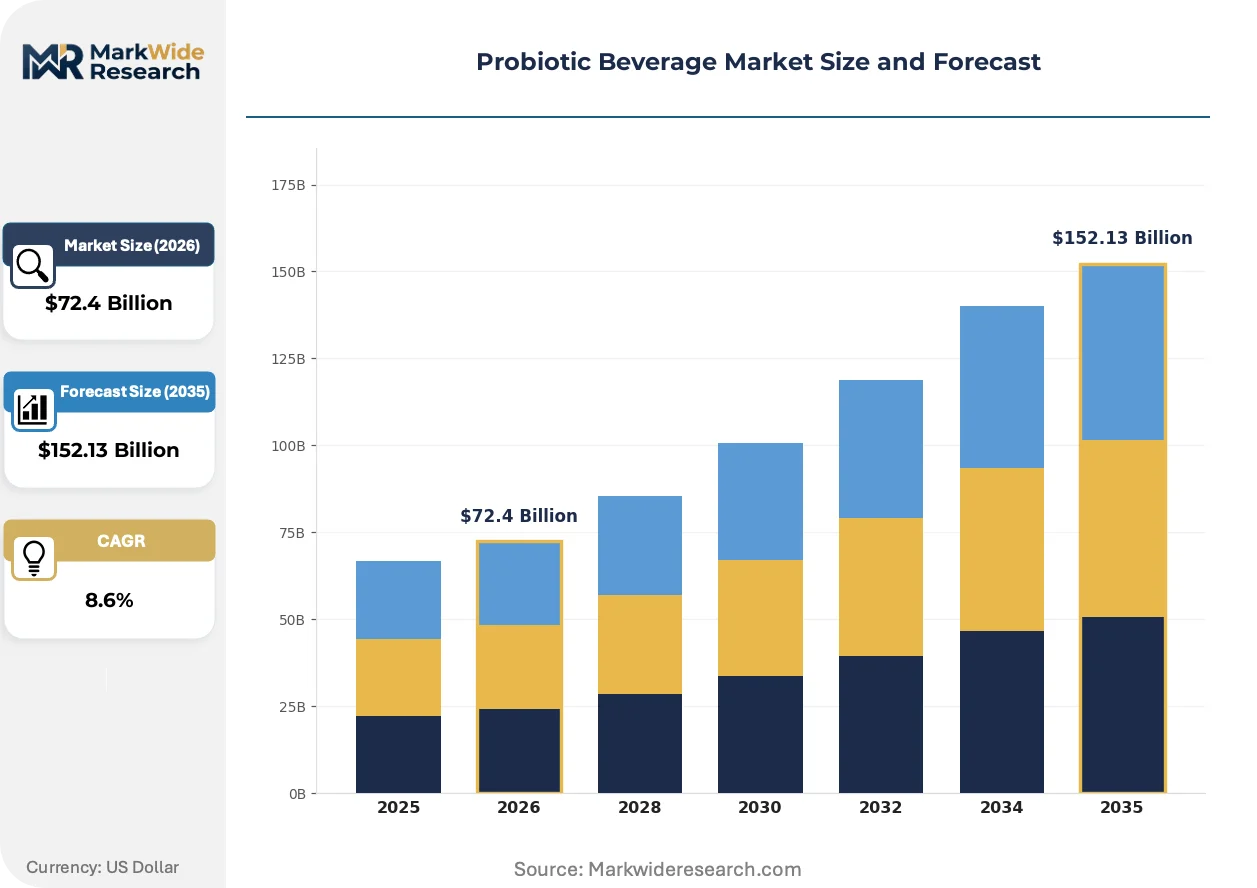
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $152.13 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Probiotic Juices, Probiotic Smoothies Formulation: Low Sugar, Organic, Dairy-based, Plant-based Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Health-conscious Consumers, Fitness Enthusiasts, Dietary Supplement Users, General Population |
| Companies Covered | Yakult Honsha Co. Ltd, Danone SA, Fonterra Co-operative Group Ltd, Nestle SA, PepsiCo Inc, GCMMF (Amul), Chobani LLC, Lifeway Foods Inc, Bio-K Plus International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Beverage Market Trends and Innovations
Microencapsulation and fermentation process control technologies are fragmenting production scale economies, enabling smaller facilities to achieve strain viability parity with legacy dairy conglomerates.
Microencapsulation of live cultures within alginate or protein matrices is modularizing the relationship between production volume and shelf-stability performance. Regional craft fermenters in Germany and the United States adopt spray-drying protocols previously restricted to pharmaceutical-grade facilities. This technology is modularizing entry barriers, allowing sub-scale producers to secure retail authorization without captive cold-chain infrastructure.
F-Gas Regulation phase-down schedules across the European Union are accelerating refrigeration system retrofits that threaten live-culture viability during equipment transition periods. Operators face capital allocation conflicts between compliance deadlines and strain-preservation continuity. German and Dutch dairy-probiotic facilities report the highest retrofit density, compressing near-term production capacity.
Subscription-based replenishment models are displacing impulse-purchase retail for daily-consumption formats. Japanese home-delivery networks and North American direct-to-consumer platforms capture recurring revenue streams that insulate producers from retail slotting volatility. This channel migration concentrates most visibly in urban Japan and coastal United States metropolitan corridors where cold-chain last-mile density supports reliable delivery windows.
Probiotic Beverage Market Segmentation
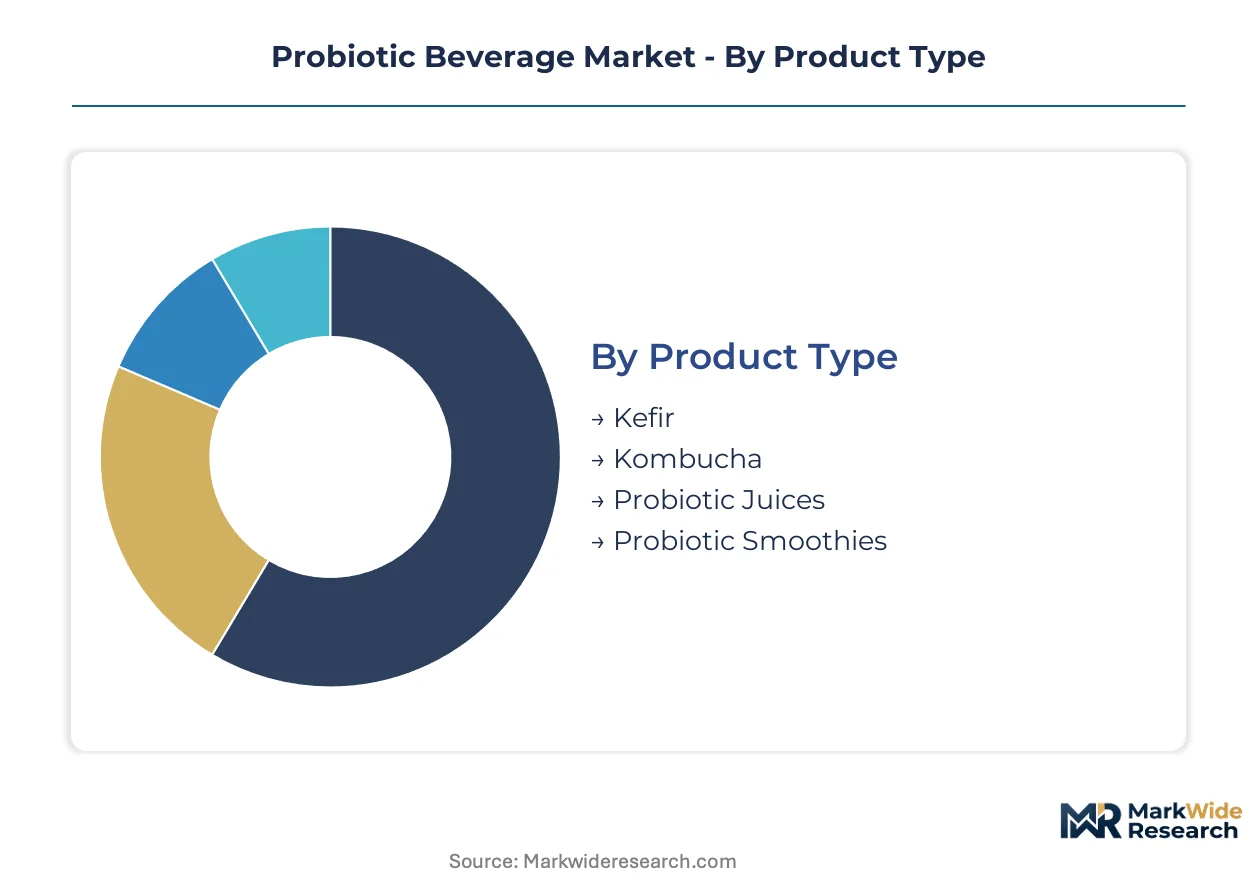
Probiotic beverage segmentation reflects divergent capital requirements across production technologies, formulation complexity, and cold-chain infrastructure. Manufacturers must align facility investments with segment-specific viability thresholds and regulatory substantiation burdens.
Product Type:
Kefir and kombucha demand the heaviest upfront fermentation infrastructure, while probiotic juices and smoothies concentrate blending and aseptic packaging investments.
- Kefir:Fermented milk beverage utilizing kefir grains containing Lactobacillus, Lactococcus, and yeast symbiotic cultures at 10^7 to 10^9 CFU per milliliter. Dairy cooperatives in Germany and the United States anchor volume through established cold-chain partnerships, though refrigerated distribution costs constrain margin expansion for regional entrants lacking Danone's captive logistics.
- Kombucha:Tea-based fermentation employing SCOBY (symbiotic culture of bacteria and yeast) producing organic acids and carbonation. Urban consumers in coastal United States metropolitan corridors drive velocity through organic and low-sugar positioning, yet unpasteurized formulations face spoilage sensitivity during temperature excursions that limit retail authorization radius.
- Probiotic Juices:Fruit or vegetable bases with post-fermentation probiotic addition requiring aseptic processing to maintain viability claims.
- Probiotic Smoothies:Blended formats combining live cultures with fiber, protein, or functional ingredients demanding refrigerated shelf-stable emulsion technology.
Most installed capacity flows through kefir. Expansion is steepest in kombucha.
Formulation:
Plant-based and organic formulations command premium positioning through ingredient sourcing complexity and certification overhead, while dairy-based and low-sugar variants leverage scale economies.
- Plant-based:Oat, coconut, or almond substrates fermented with adapted Lactobacillus strains to achieve dairy-comparable texture and CFU counts. Lactose-intolerant consumer segments in the United States and Germany drive adoption as oat fermentation protocols mature, though strain adaptation R&D extends development timelines versus dairy-native cultures.
- Organic:Certified ingredient sourcing and processing under USDA Organic or EU Organic standards with prohibition of synthetic preservatives. Premium pricing authority in health food retail channels offsets higher input costs, yet supply concentration for certified probiotic cultures limits formulation flexibility.
- Dairy-based:Traditional milk or yogurt-based vehicles leveraging established dairy infrastructure and consumer acceptance.
- Low Sugar:Reduced glycemic formulations targeting metabolic health positioning through stevia, monk fruit, or post-fermentation sugar consumption by cultures.
Organic certification captures the highest margin premiums. Plant-based substrates are climbing the fastest as allergen-free positioning opens new consumer segments.
Distribution Channel:
Channel selection determines cold-chain investment intensity, with home-delivery and specialty retail requiring dedicated logistics versus supermarket scale economies.
- Supermarkets:Mass retail placement demanding slotting fees and refrigerated section negotiations with chains like Kroger or Tesco. Volume concentration in the United States and Germany sustains strain-count viability through high-turnover inventory management, though margin compression from retail consolidation favors multinational scale.
- Online Retail:Direct-to-consumer and platform-based sales enabling subscription replenishment models. Urban Japan's home-delivery networks and North American metro corridors support recurring revenue streams that insulate producers from slotting volatility, yet last-mile refrigeration density determines serviceable geography.
- Health Food Stores:Specialty retail emphasizing organic, non-GMO, and strain-verified positioning with educated staff.
- Specialty Stores:Fitness, natural product, or ethnic retail channels with curated assortment and community credibility.
Supermarket placement anchors volume throughput. Online retail is gaining share fastest through subscription model adoption.
End User:
User segmentation aligns product development with substantiation requirements, from clinical-grade trials for supplement users to taste-forward formulation for general population expansion.
- Health-conscious Consumers:Primary adopters seeking digestive wellness through verified strain counts and clean-label positioning. Concentrated in Germany and Japan where FOSHU and EFSA frameworks reward clinical substantiation with premium pricing authority, though regulatory compliance costs exclude smaller competitors.
- Fitness Enthusiasts:Athletes and gym-goers targeting gut microbiome recovery for performance optimization. Sports nutrition retail in the United States and specialty running/cycling channels bypass conventional grocery fees while commanding loyalty through post-exercise positioning.
- Dietary Supplement Users:Consumers treating probiotic beverages as functional alternatives to capsules or tablets.
- General Population:Mass-market expansion targeting taste and convenience over explicit health claims.
Health-conscious consumers represent the most substantiation-intensive segment. Fitness enthusiasts are expanding most quickly through specialty channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food microbiologists and fermentation specialists cluster in Germany, Japan, and the United States, anchoring the technical workforce that sustains live-culture viability claims across cold-chain networks.
United States
Fitness enthusiasts and health-conscious millennials drive kombucha and kefir adoption through specialty retail channels. FDA GRAS notification requirements enforce strain-specific substantiation for immunity and digestive claims. California's Bay Area hosts the densest concentration of craft fermentation startups, where microencapsulation technology enables smaller facilities to achieve pharmaceutical-grade shelf stability.
Germany
Dairy cooperative infrastructure and established refrigerated distribution partnerships sustain kefir volume leadership across mass retail. EFSA health claim regulations reward clinically documented Lactobacillus and Bifidobacterium strains with premium shelf-space authorization. Bavaria's dairy processing corridor reports the highest retrofit density under F-Gas Regulation phase-down schedules, compressing near-term live-culture production capacity.
Japan
Daily consumption rituals and aging demographics sustain home-delivery network specialization for single-strain probiotic formats. METI-administered FOSHU certification commands 40-60% price premiums for verified functional strains in convenience retail. Tokyo and Osaka metropolitan corridors concentrate subscription-based replenishment models that bypass supermarket slotting volatility through dedicated cold-chain last-mile infrastructure.
China
Rising digestive wellness awareness among urban middle-class consumers accelerates adoption of imported and domestic live-culture beverages. SAMR's evolving functional food classification standards create compliance uncertainty at the beverage-dairy-supplement boundary. Yangtze River Delta manufacturing clusters are retrofitting fermentation facilities to accommodate both dairy-based and emerging oat-substrate production lines.
India
Lactose-intolerant population segments and traditional fermented dairy consumption patterns create dual demand for conventional and plant-based probiotic formats. FSSAI's functional food regulatory framework remains less prescriptive than EFSA or FDA equivalents, enabling faster product launch cycles. Gujarat and Maharashtra dairy cooperatives are expanding aseptic processing capacity to capture viability-sensitive live-culture export opportunities.
Probiotic Beverage Market Competitive Landscape
Capital-heavy producers with captive refrigerated distribution compete with asset-light brand developers outsourcing fermentation to contract manufacturers. The market structure concentrates around three strategic tiers: multinational dairy conglomerates with integrated cold-chain logistics, regional specialists leveraging home-delivery network density, and craft fermenters exploiting microencapsulation to bypass scale requirements. Dominant competitive moves include backward integration into proprietary strain development and geographic co-location of production with high-density urban consumption corridors.
Within the multinational dairy tier, Danone SA and Nestle SA exemplify scale-driven positioning through refrigerated supply chain ownership and mass retail authorization. Yakult Honsha Co. Ltd anchors the home-delivery specialist archetype through single-strain focus and daily-consumption ritual cultivation. Chobani LLC occupies the plant-based innovation vector, competing for shelf space against traditional dairy lines through oat and coconut substrate development.
| Leading Market Players |
|---|
| Yakult Honsha Co. Ltd |
| Danone SA |
| Fonterra Co-operative Group Ltd |
| Nestle SA |
| PepsiCo Inc |
| GCMMF (Amul) |
| Chobani LLC |
| Lifeway Foods Inc |
| Bio-K Plus International Inc |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up craft fermenters in the United States and Germany anchor mid-tier production capacity, linking ownership concentration to disciplined pricing power in premium live-culture segments while compressing margins for commodity-positioned competitors lacking cold-chain scale.
Pricing Analysis
The bundled home-delivery subscription versus unbundled supermarket transactional split defines pricing architecture across the probiotic beverage market. Three-tier pricing structure across premium FOSHU-certified, standard EFSA-verified, and economy unverified tiers separates clinical-grade strain products from commodity live-culture drinks. Cost compression in the economy tier is intensifying because refrigerated distribution cost inflation erodes viability claims for brands lacking captive logistics. Health-conscious consumers in Japan exhibit lowest price sensitivity due to FOSHU premium authorization, while mass-market supermarket shoppers in Germany demonstrate highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Bavaria's dairy processing corridor and Tokyo's fermentation technology clusters concentrate live-culture production expertise in named manufacturing geographies. Supply concentrates in Germany, Japan, and the United States, drawing from kefir grain cultures, SCOBY mother stocks, and microencapsulation alginate matrices. Single-source vulnerability in proprietary Lactobacillus strain licensing creates royalty-dependent margin forecasting risk. Distribution runs through dedicated cold-chain last-mile networks in Japanese metropolitan corridors and refrigerated retail partnerships in German mass-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the probiotic beverage market rests on microencapsulation-driven refrigeration cost avoidance and FOSHU premium-tier pricing authority shifting volume toward verified functional strains.
For Market Incumbents: Acquire captive cold-chain logistics assets in high-density urban consumption corridors to defend against subscription-based home-delivery entrants eroding supermarket slotting control. Secure proprietary strain development capacity through backward integration into pharmaceutical-grade R&D partnerships, insulating margin forecasts from per-unit royalty complexity. For New Entrants and Emerging Players: Specialty sports nutrition retailers in North American running and cycling channels offer lowest competitive density for post-exercise gut microbiome positioning. Pediatric formulation white space in verified low-sugar live-culture segments presents most penetrable target, with direct-to-consumer subscription models enabling bypass of conventional grocery slotting fees. For Investors and Strategic Acquirers: Valuations sit cheapest among regional craft fermenters with microencapsulation technology parity but lacking brand scale, offering acquisition entry before cold-chain infrastructure consolidation accelerates. Five-to-ten year viability hinges on strain patent landscape resolution and FOSHU certification pathway expansion. Watch EFSA health claim dossier approval velocity as inflection indicator for premium-tier pricing authority migration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Development Investment | Backward integration into captive Lactobacillus isolates eliminates royalty-dependent margin forecasting uncertainty. |
| FOSHU Certification Pathway Pursuit | METI authorization commands premium pricing authority in Japanese convenience retail channels. |
| Microencapsulation Technology Deployment | Spray-drying protocols enable regional craft fermenters to achieve pharmaceutical-grade shelf stability without captive cold-chain infrastructure. |
| Home-Delivery Network Expansion | Subscription replenishment models in Tokyo and Osaka metropolitan corridors insulate producers from supermarket slotting volatility. |
| Plant-Based Substrate Line Extension | Oat and coconut fermentation protocols open lactose-intolerant consumer segments previously excluded from live-culture benefits. |
Research Methodology
Bottom-up end-user consumption modeling reconciled against top-down fermentation facility capacity tracking forms the analytical core of this study. Primary interviews with brand managers at multinational dairy conglomerates, category buyers at Kroger and Tesco, supply planners at cold-chain logistics providers, and technical R&D directors at microencapsulation technology firms combined with secondary validation against EFSA health claim dossiers, FDA GRAS notification filings, FOSHU certification databases, and Nielsen retail audit data. Triangulation between demand-side adoption patterns and supply-side production constraints ensures segmentation integrity across product type, formulation, and distribution channel dimensions.
Input-output matrix framing connects fermentation capacity utilization rates, strain viability degradation curves, and refrigerated distribution cost indices to volume and value projections across the analysis window. Segmentation dimensions modeled include product type tier, formulation substrate, distribution channel cold-chain intensity, end-user substantiation requirement, and regional regulatory cluster. CAGRs were derived from slope-intercept trajectory analysis of historical consumption patterns adjusted for F-Gas Regulation retrofit impacts and home-delivery network penetration curves. Forecast inputs incorporate EFSA labeling mandate compliance timelines and FOSHU certification queue velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to strain patent litigation resolution, refrigeration energy cost volatility, and cross-category regulatory reclassification at the beverage-dairy-supplement boundary. Forecasts reflect documented assumptions regarding cold-chain infrastructure expansion rates and clinical trial substantiation cost trajectories. Material deviation in EFSA health claim approval velocity or F-Gas Regulation phase-down schedule acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fusion Beverages Market
Beverages
Global Soda Maker Market
Beverages
Baby Drinks Market
Beverages
Soft Serves Market
Beverages
Mixers Market
Beverages
Craft Soda Market
Beverages
Still Drinks Market
Beverages
Water Flavor Market
Beverages
Double Valve Moka Pots Market
Beverages
Low Fat Drinks Market
Beverages
Italy Probiotic Drinks Market
Beverages
China Orange Juice Market
Beverages
Pineapple Juice Market
Beverages
Smoothies Market
Beverages
Bottled Beverages Market
Beverages
United Kingdom Energy Drink Market