
 Peanut Oil Market | 2026-2036
Peanut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Oil Market Analysis
The capital-intensity divergence between integrated crushers and standalone refiners is unwinding competitive stability across the peanut oil value chain. Bunge Limited leverages its North American origination network to sustain supply continuity for foodservice clients. Cargill, Incorporated anchors its position through crushing assets in key peanut-growing belts. Wilmar International Limited dominates Asian distribution channels with extensive port-based refining infrastructure.
Peanut oil is a vegetable oil extracted from the seeds of Arachis hypogaea, typically containing 40-50% monounsaturated oleic acid and refined to a smoke point exceeding 230°C for high-temperature frying applications. Refined peanut oil leads volume due to its neutral flavor profile and extended fry-life in commercial kitchens, while cold-pressed variants command premium positioning among health-conscious consumers seeking unprocessed alternatives. The food industry end-use segment occupies the dominant share of value flows, though pharmaceutical-grade specifications are gaining traction for injectable formulations and vaccine adjuvant applications.
The FDA governs peanut oil labeling under FALCPA allergen disclosure requirements, while India's FSSAI enforces solvent residue limits that shape refining technology choices for exporters. China's SAMR monitors edible oil safety through GB standards that dictate maximum aflatoxin thresholds, directly influencing pre-crushing sorting and storage protocols. Stakeholders must monitor evolving allergen labeling harmonization between FDA and EFSA frameworks, as divergent threshold definitions threaten cross-border formulation consistency for multinational food manufacturers.
Market Dynamics
India's FSSAI solvent residue limits and China's SAMR aflatoxin thresholds are forcing capital upgrades across crushing and refining assets, compressing margins for processors lacking scale to absorb compliance costs.
Growth Catalysts
- Refining Technology Modernization:India's FSSAI tightening of edible oil quality benchmarks accelerates processor migration toward advanced solvent recovery and deodorization systems.
- Cold-Press Premium Positioning:Food manufacturers across Asia-Pacific expand procurement of unprocessed variants for high-end culinary applications, capturing health-conscious consumer willingness to pay.
- Shandong-Henan Cluster Proximity:Demand concentrates in China's peanut cultivation belts where crushing capacity co-locates with domestic feedstock supply, reducing logistics drag.
Market Restraints
- Input Cost Volatility:Peanut seed prices fluctuate with monsoon-dependent Indian and Chinese harvests, squeezing crush margins for non-integrated refiners.
- Regulatory Friction:Divergent FDA and EFSA allergen labeling thresholds create cross-border formulation complexity for multinational food manufacturers.
- Substitution Threat:High-oleic sunflower and refined avocado oils displace peanut oil in commercial frying where neutral flavor and extended fry-life matter.
Strategic Opportunities
- Pharmaceutical-Grade Specifications:Injectable formulations and vaccine adjuvant applications open premium pricing tiers beyond food industry commoditization.
- EU Green Deal Alignment:Cold-pressed variants with carbon-certified supply chains qualify for sustainability-linked procurement mandates in European foodservice.
- Direct-to-Brand E-Commerce:Bypassing traditional port-based distribution infrastructure allows artisanal producers to capture margin from urban health-conscious consumers.
Industry Challenges
- Skilled Technician Scarcity:Operating advanced refining systems with real-time aflatoxin monitoring requires training pipelines that crush operators lack.
- Certification Timeline Compression:Pharmaceutical-grade cGMP validation cycles extend 18-24 months, delaying revenue conversion for processors pivoting from food-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Oil Market |
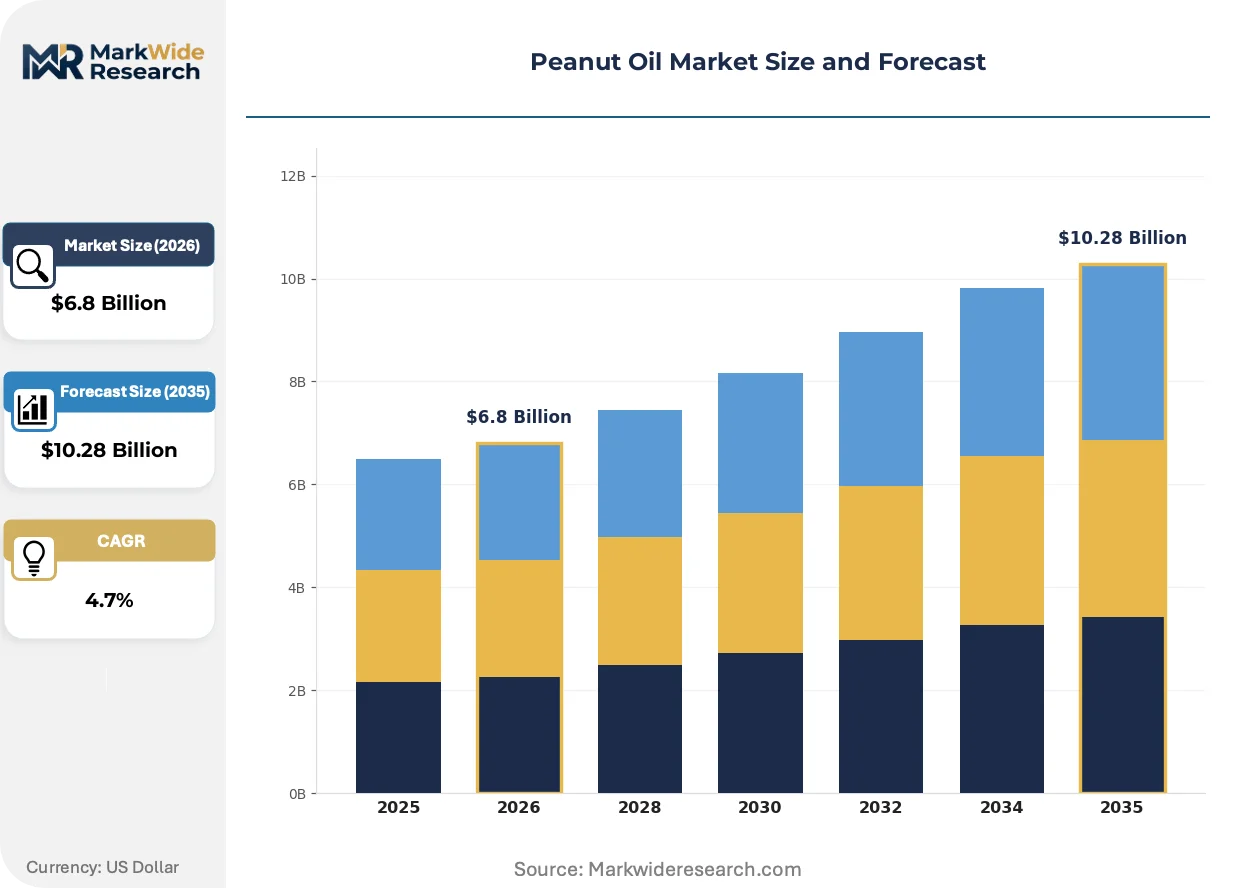
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Peanut Oil, Cold-Pressed Peanut Oil, Roasted Peanut Oil, Organic Peanut Oil End Use: Food Industry, Cosmetic Industry, Biofuel Production, Pharmaceuticals Packaging Type: Bottles, Cans, Drums, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Bunge Limited, COFCO Corporation, Cargill, Incorporated, The Hain Celestial Group, Inc., AAK AB, Archer Daniels Midland Company, Olam International, Tata Consumer Products Limited, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Oil Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are restructuring competitive advantage around traceability infrastructure and extraction method transparency rather than scale alone.
Supercritical CO2 extraction is decomposing the traditional hexane-solvent refining paradigm by eliminating residual solvent concerns entirely. Premium health-food brands in North American and European markets are adopting this technology despite 40% higher unit costs. The shift is compressing addressable market share for conventional refiners unable to fund capital-intensive equipment transitions.
REACH registration requirements for imported food-contact substances are tightening documentation burdens on Asian exporters to European markets. The regulation forces processors to maintain batch-level contaminant testing records spanning cultivation through final packaging. Small and mid-scale crushers in India and China face exclusion or costly third-party certification dependencies.
Restaurant chains and contract food manufacturers now specify extraction method and geographic origin in procurement tenders, displacing commodity-grade spot purchasing. This behavior concentrates volume with processors offering verified cold-press or supercritical credentials. The pattern is most pronounced in coastal Chinese cities and metropolitan Indian markets where consumer-facing brands dominate supply decisions.
Peanut Oil Market Segmentation
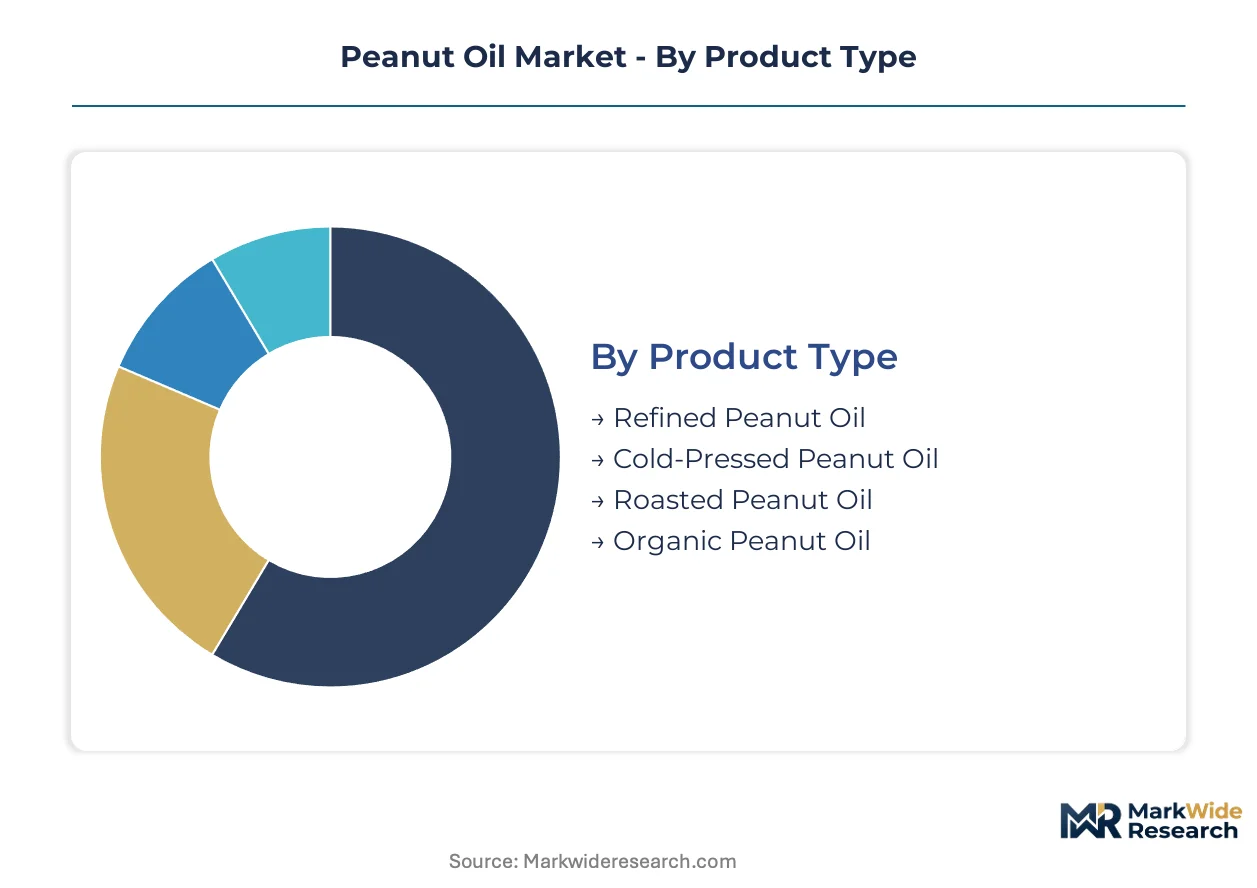
Peanut oil segmentation separates commodity-grade volume from premium-margin niches. Product type and end-use splits determine capital allocation between solvent-based refining infrastructure and cold-press equipment.
Product Type:
Margin pools concentrate in extraction method differentiation, where processing technology separates commodity refiners from premium-positioned operators.
- Refined Peanut Oil:Hexane-extracted and deodorized to neutral flavor with smoke points exceeding 230°C. Commercial kitchens across China's Shandong province specify this grade for extended fry-life in high-volume operations. FDA allergen labeling requirements under FALCPA shape formulation decisions for US-bound exports.
- Cold-Pressed Peanut Oil:Mechanical extraction without solvent retains tocopherols and polyphenols for health-conscious positioning. India's metropolitan markets show strongest procurement growth as FSSAI tightens solvent residue limits. Premium pricing captures 40% higher unit economics versus refined alternatives.
- Roasted Peanut Oil:Pre-crushing roasting imparts nutty flavor profiles for specialty culinary applications.
- Organic Peanut Oil:Certified cultivation with batch-level traceability commands procurement premiums in EU Green Deal-aligned supply chains.
The dominant share belongs to Refined Peanut Oil, while Cold-Pressed Peanut Oil is gaining share fastest.
End Use:
Application splits track divergent specification intensity, with pharmaceutical and food-grade demands pulling processors toward distinct certification investments.
- Food Industry:Dominant volume flow spans commercial frying, salad dressings, and confectionery formulations. China's restaurant chains specify geographic origin and extraction method in procurement tenders. Substitution pressure from high-oleic sunflower oil constrains pricing power in neutral-flavor frying segments.
- Pharmaceuticals:Injectable-grade specifications require cGMP validation cycles of 18-24 months for vaccine adjuvant applications. CDSCO in India and FDA in the US enforce divergent purity benchmarks that complicate cross-border formulation consistency.
- Cosmetic Industry:Emollient properties drive demand in skincare formulations with lower regulatory burden than pharmaceutical grades.
- Biofuel Production:Fatty acid profiles suit biodiesel feedstock in price-sensitive industrial procurement.
Food Industry retains volume leadership, though Pharmaceuticals shows the steepest expansion trajectory.
Packaging Type:
Format selection aligns with customer scale and handling infrastructure, separating retail-facing from industrial procurement channels.
- Bottles:Consumer retail formats dominate urban Indian and Chinese metropolitan markets. E-commerce penetration accelerates direct-to-brand distribution bypassing traditional wholesale structures.
- Bulk Containers:Food manufacturers and contract caterers specify tanker or flexitank delivery to reduce per-unit handling costs. Crushing capacity clusters in Shandong and Henan provinces enable just-in-time bulk supply to coastal processing facilities.
- Cans:Extended shelf-life protection suits export logistics and specialty store distribution.
- Drums:Mid-scale foodservice and artisanal producers favor standardized drum formats for manageable batch handling.
Bulk Containers command the largest volume flow, while Bottles are expanding most quickly via online retail channels.
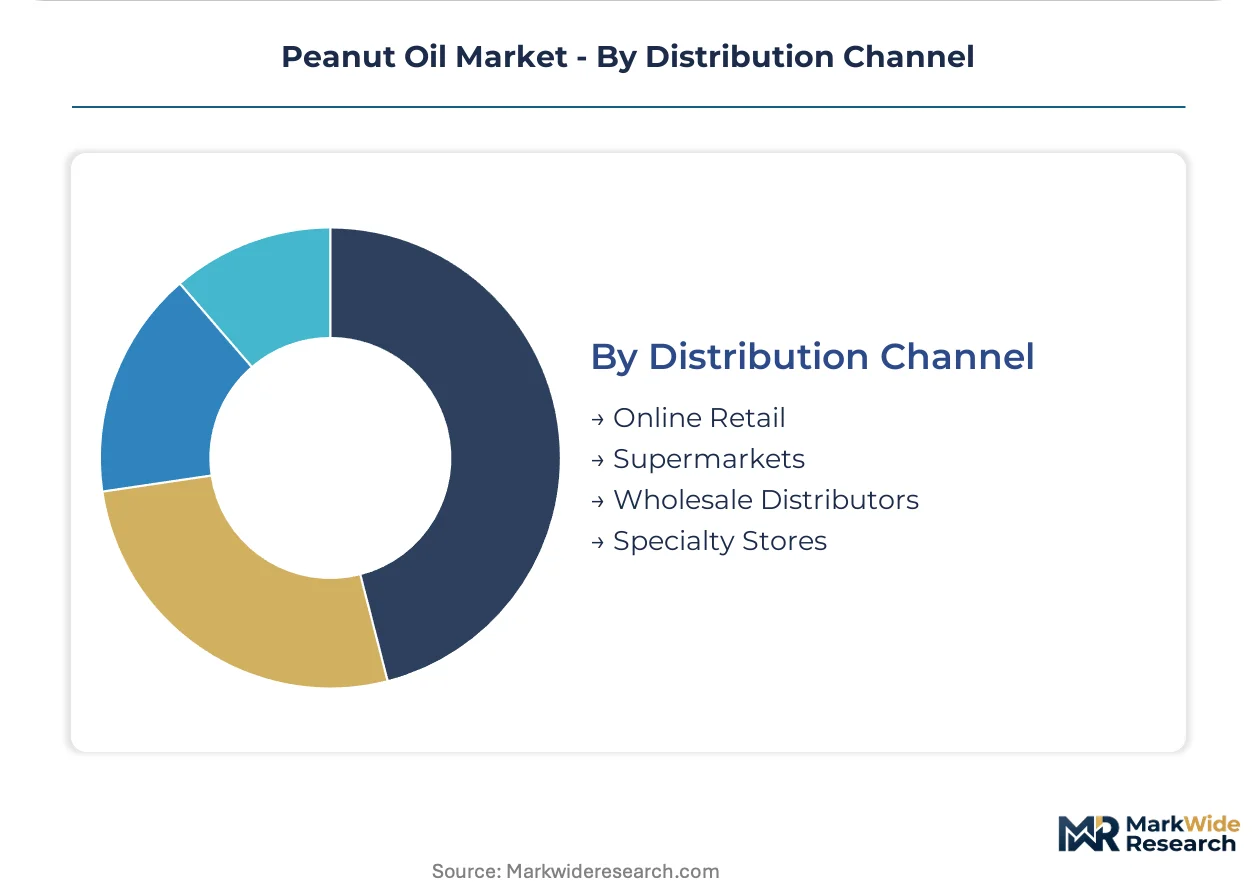
Distribution Channel:
Channel structure reflects urbanization patterns and brand control preferences, with digital platforms eroding traditional port-based wholesale dominance.
- Wholesale Distributors:Established port-based infrastructure in Mumbai, Shanghai, and Rotterdam handles commodity-grade volume flows. Wilmar International and comparable operators leverage terminal assets for cost-efficient bulk distribution.
- Online Retail:Direct-to-consumer platforms enable artisanal cold-press producers to capture urban health-conscious demand. India's Tier-1 cities show fastest platform adoption for premium edible oil categories.
- Supermarkets:Private-label penetration concentrates shelf space for standardized refined grades in mass-market positioning.
- Specialty Stores:Organic and cold-press variants find curated placement in health-food retail formats.
Wholesale Distributors maintain position in commodity volume, while Online Retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers in Shandong and Henan provinces exhibit the lowest price elasticity, absorbing premium cold-pressed grades, while Indian bulk processors remain highly sensitive to seed cost swings. European foodservice procurement shows intermediate elasticity, prioritizing carbon-certified supply chains over absolute price minimization.
China
Restaurant chains in coastal cities now mandate extraction method disclosure in procurement tenders. SAMR enforces GB standards capping aflatoxin thresholds, forcing pre-crushing investment in optical sorting infrastructure. Crushing capacity clusters in Shandong and Henan provinces, where domestic peanut cultivation belts enable just-in-time feedstock supply to port-based refiners.
India
Metropolitan markets in Mumbai and Delhi-NCR drive fastest growth for cold-pressed variants among health-conscious consumers. FSSAI solvent residue limits are accelerating processor migration toward advanced deodorization systems, compressing margins for non-integrated operators. Gujarat and Maharashtra house the dominant crushing infrastructure, with refiners upgrading to meet export quality benchmarks.
United States
Foodservice clients sustain demand for refined grades with extended fry-life specifications in high-volume frying operations. FDA FALCPA allergen labeling requirements shape formulation decisions for domestic and export-bound production. Georgia and Alabama cultivation belts feed crushing assets in the Southeast, with port infrastructure on the Gulf Coast handling bulk export flows.
Germany
EU Green Deal procurement mandates are concentrating demand for carbon-certified cold-pressed oils in foodservice and retail channels. EFSA allergen threshold definitions create documentation burdens that favor large-scale processors with batch-level traceability systems. Hamburg port infrastructure anchors distribution into Benelux and Scandinavian markets, with specialty oil refiners in Bavaria serving premium domestic demand.
Brazil
Domestic consumption of refined peanut oil concentrates in São Paulo's commercial food manufacturing sector. ANVISA pharmaceutical-grade specifications are opening export pathways for processors achieving cGMP validation. São Paulo state and Minas Gerais cultivation zones supply crushing capacity in the Southeast, with port terminals in Santos handling intercontinental bulk shipments.
Peanut Oil Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated crushers with captive seed supply dominate volume economics, while specialized refiners command premium positioning through extraction method differentiation. Three archetypes define the landscape: multinational agribusiness conglomerates with origination networks, Asian port-based refiners with distribution infrastructure, and regional cold-press specialists serving health-food channels. Competitive moves concentrate on backward integration into seed procurement and portfolio diversification into pharmaceutical-grade specifications.
Among multinational agribusiness conglomerates, Bunge Limited and Cargill, Incorporated exemplify the integrated origination model, leveraging North American and South American supply networks. Wilmar International Limited anchors the Asian port-based refiner archetype, dominating distribution channels through terminal infrastructure in Singapore and China. These three occupy positions that represent the scale-driven end of competitive positioning, though cold-press specialists are eroding their share in premium urban markets.
| Leading Market Players |
|---|
| Bunge Limited |
| COFCO Corporation |
| Cargill, Incorporated |
| The Hain Celestial Group, Inc. |
| AAK AB |
| Archer Daniels Midland Company |
| Olam International |
| Tata Consumer Products Limited |
| Wilmar International Limited |
| Others |
Supply Flow & Price Mechanics
India's FSSAI solvent residue limits gate supply qualification for exporters while simultaneously enabling price differentiation between compliant and non-compliant processors. Buyers in China's Shandong province absorb premium cold-pressed grades, whereas Indian bulk refiners face acute margin compression from seed cost volatility.
Pricing Analysis
After-sales service contracts for refining equipment maintenance drive lifetime value for processing technology vendors. Contract-based long-term offtake dominates volume transactions, with price differentiation resting on certification grade and extraction method transparency. Pricing pressure stems from high-oleic sunflower oil substitution in commercial frying segments. Food manufacturers in China's coastal cities show lowest price sensitivity, while Indian standalone refiners operate at highest sensitivity to input cost swings.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for European foodservice procurement of Asian-origin cold-pressed oils. Supply concentrates in China, India, and the United States, with raw material dependencies on peanut seed harvests in Shandong, Gujarat, and Georgia cultivation belts. Single-source vulnerability runs through monsoon-dependent Indian and Chinese harvest cycles. Distribution runs through port-based terminal infrastructure in Mumbai, Shanghai, and Rotterdam for commodity-grade volume flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment maintenance and certification renewal services expand faster than base oil sales for processing technology providers. Recurring revenue from real-time aflatoxin monitoring system subscriptions outpaces hardware margins.
For Market Incumbents: Fortify crushing assets in Shandong and Henan provinces through backward integration into seed procurement. Invest in pharmaceutical-grade cGMP certification to offset substitution pressure from high-oleic alternative oils. Channel control through direct restaurant chain relationships protects margin pools. For New Entrants and Emerging Players: Differentiate on supercritical CO2 extraction credentials to capture premium health-food channel demand in North American and European markets. Target underpenetrated pharmaceutical-grade specifications for vaccine adjuvant applications. Go-to-market through direct-to-brand e-commerce bypasses entrenched wholesale distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical extraction equipment installations, favoring scaled operators with balance sheet capacity. Long-term viability centers on processors with verified carbon-certified supply chains for EU Green Deal alignment. Acquisition targets include regional cold-press specialists with established metropolitan brand presence. Monitor FSSAI enforcement intensity as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Captive supply from Shandong cultivation belts reduces logistics drag and margin volatility. |
| Pharmaceutical-Grade cGMP Certification | CDSCO and FDA validation cycles open vaccine adjuvant pricing tiers beyond food commoditization. |
| Supercritical CO2 Extraction Deployment | Eliminates residual solvent concerns for REACH-compliant European health-food channel access. |
| Direct-to-Consumer E-Commerce Launch | Urban Indian and Chinese metropolitan markets enable margin capture from health-conscious buyers. |
| Carbon-Certified Supply Chain Program | EU Green Deal procurement mandates in German foodservice qualify sustainability-linked premiums. |
Methodological Framework
Cross-validation between primary interviews and customs trade data anchors the qualitative findings. Crushing plant managers, procurement leads at multinational food manufacturers, FSSAI compliance officers, and port terminal operators provided operational perspectives. Secondary validation drew from India DGFT export statistics, China customs records, FDA FALCPA guidance documents, and EFSA allergen threshold publications. Bottom-up capacity modeling triangulates against top-down consumption estimates.
Sensitivity analysis tested forecast robustness across seed price volatility scenarios and regulatory enforcement intensity variations. Segmentation dimensions span extraction method, end-use application, and geographic production cluster. CAGRs derive from trend extrapolation of installed crushing capacity and premium-grade adoption curves. Forecast inputs include monsoon pattern correlations with Indian harvest yields and SAMR aflatoxin inspection frequency trends.
Material uncertainties — regulatory harmonization failures between FDA and EFSA, supercritical equipment cost deflation rates, and pharmaceutical-grade validation timeline compression — sit outside the modeled envelope. Forecasts reflect documented assumptions about seed supply continuity and certification cost absorption capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Nitro-Infused Cola Market
Beverages
Packaged Milkshake Market
Beverages
United States Recovery Drinks Market
Beverages
Solid Beverages Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Fruit Juices and Nectars Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Ready to Drink Premixes Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Rose Floral Water Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Foaming Creamer Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Wellness Water Market
Beverages
Crystal Boba Market
Beverages
Bottled Air Market