
 Alternative Waters (Plant Based Waters) Market | 2026-2036
Alternative Waters (Plant Based Waters) Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Waters (Plant Based Waters) Market Outlook
EU Green Deal compliance is restructuring the cost-of-entry calculus for plant-based water brands entering European markets. Nestle SA leverages its bottling infrastructure to sustain distribution density across regulated jurisdictions. The Coca-Cola Company anchors its portfolio with coconut water lines that navigate evolving carbon-footprint mandates.
Alternative waters encompass aqueous extracts from botanical sources—coconut sap, maple tree xylem, aloe vera mesophyll, and cactus cladode tissue—typically processed through cold pasteurization or high-pressure processing to retain bioactive compounds and electrolyte profiles. These beverages serve commercial purposes as functional hydration alternatives to synthetic sports drinks and sugar-laden sodas. Coconut water occupies the dominant revenue position among product types, while aloe vera juice commands premium shelf placement in health stores and specialty shops due to perceived digestive and dermatological benefits. Cartons and tetra packs capture structural preference from sustainability-focused retailers seeking reduced plastic dependency.
FDA labeling requirements and EFSA novel food assessments shape permissible health claims and ingredient classifications across Atlantic markets. BIS fortification standards in India and FSSAI beverage safety protocols further fragment compliance obligations for multinational portfolios. Stakeholders must monitor escalating regulatory divergence between jurisdictions as plant-based positioning attracts intensified scrutiny from national food safety authorities.
Market Dynamics
Clean-label mandates from the EU Green Deal and FDA disclosure rules are forcing reformulation of plant-based water portfolios, while cold pasteurization investments concentrate processing capacity among capitalized operators.
Growth Catalysts
- EU Green Deal compliance deadlines:Carbon-footprint labeling requirements are pulling coconut water and maple water into mainstream retail channels across Germany, France, and the Netherlands as retailers seek defensible sustainability credentials.
- Fitness and wellness sector expansion:Boutique gyms and endurance sports clubs in the United States and Brazil are replacing synthetic sports drinks with electrolyte-rich botanical alternatives for post-workout hydration protocols.
- High-pressure processing (HPP):This non-thermal preservation method retains bioactive compounds in aloe vera and cactus waters, enabling premium positioning in health stores and specialty shops.
Market Restraints
- Raw material concentration risk:Coconut water supply chains depend heavily on harvests from Indonesia, the Philippines, and Sri Lanka, exposing processors to monsoon variability and port congestion.
- EFSA novel food assessment timelines:New botanical extracts face 12-18 month safety evaluations, delaying product launches and freezing pipeline investments for emerging variants.
- Sugar-sweetened beverage substitution:Flavored sparkling waters and zero-calorie functional drinks compete directly on hydration claims, compressing shelf space allocation for plant-based alternatives.
Strategic Opportunities
- Underpenetrated Indian market:FSSAI fortification standards and rising disposable incomes in Mumbai, Bangalore, and Delhi create entry points for coconut water brands with Ayurveda-aligned positioning.
- Direct-to-subscription channels:Cold-chain delivery networks enable recurring revenue models for premium aloe vera and maple water variants targeting biohacking and longevity consumers.
- CSRD-aligned carbon accounting:Early adoption of scope-three emissions tracking allows brands to preempt retailer sustainability scorecard requirements and secure preferred supplier status.
Industry Challenges
- High-pressure processing capex intensity:Commercial HPP systems require $2-4 million per installation, constraining mid-tier brands to co-packing arrangements with limited quality control.
- Multi-jurisdiction label compliance:Divergent FDA, EFSA, and FSSAI health claim standards force portfolio fragmentation, multiplying packaging SKUs and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Waters (Plant Based Waters) Market |
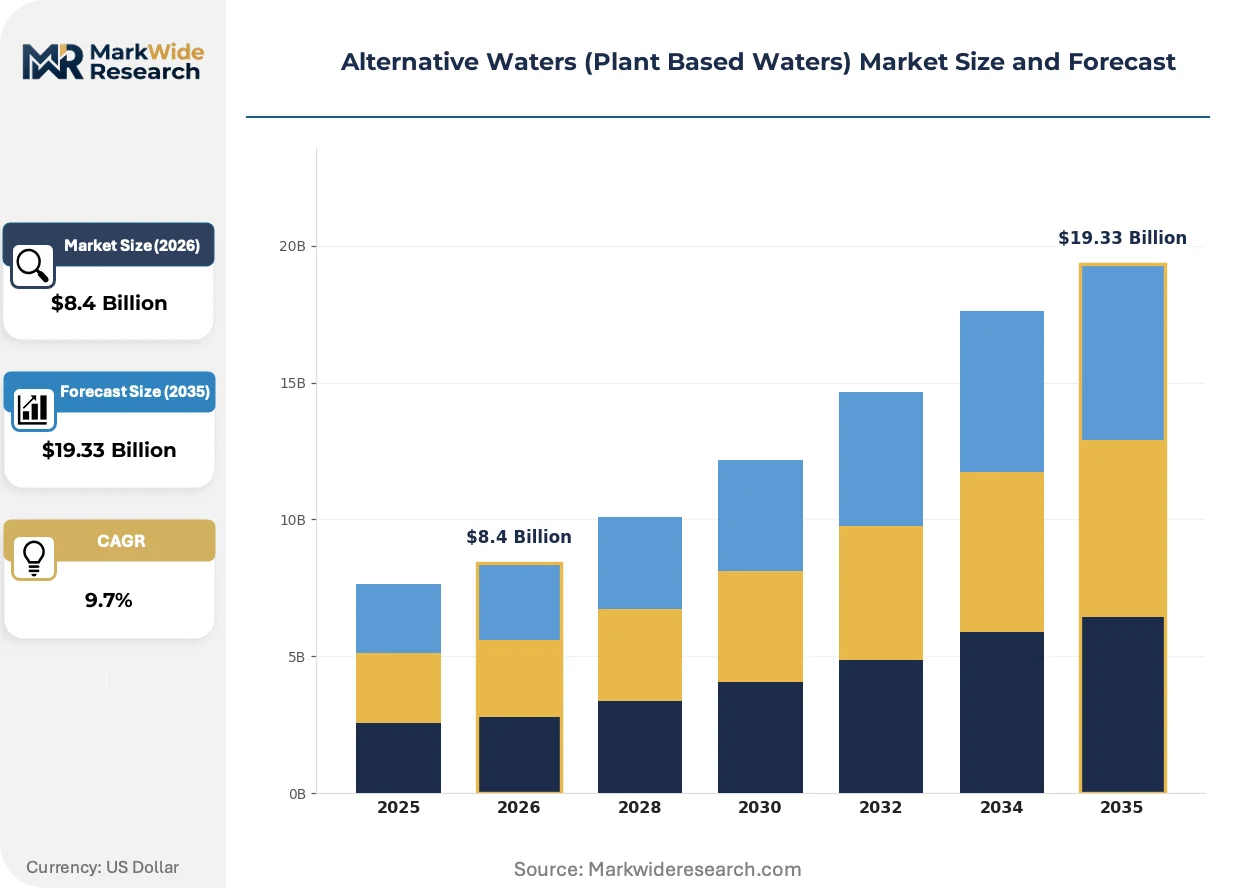
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Water, Maple Water, Aloe Vera Juice, Cactus Water Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Packaging Type: Cartons, Bottles, Pouches, Tetra Packs End User: Fitness Enthusiasts, Health-Conscious Consumers, Restaurants, Cafés |
| Companies Covered | Nestle SA, Hint Water, The Coca-Cola Company, Vitamin Well AB, Flow Beverage Corp, Pepsico Inc., Keurig Dr Pepper Inc., San Benedetto, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Waters (Plant Based Waters) Market Strategic Shifts
Cold pasteurization technologies and regenerative agriculture certifications are rewriting production economics and sourcing protocols across the alternative waters sector, while digital traceability systems reshape buyer verification expectations.
High-pressure processing (HPP) is rewriting shelf-life extension for heat-sensitive botanical extracts. Premium health stores and direct-to-consumer brands in California and New York are adopting HPP-treated aloe vera and maple waters at accelerating rates. This technology is compressing the competitive gap between artisanal small-batch producers and scaled beverage conglomerates.
The EU Green Deal's carbon-border adjustment mechanism is rewriting import cost structures for coconut water entering European ports. German and Dutch distributors are restructuring supplier contracts to secure verified low-emission harvests from Southeast Asia. Coconut water variants with blockchain-tracked provenance command preferential listing terms at sustainability-focused retail chains.
Subscription-based replenishment models are rewriting household purchasing patterns for functional hydration. Urban professionals in São Paulo, London, and Los Angeles are replacing supermarket restocking with curated monthly deliveries of multi-variant plant-based water assortments. This channel shift is most visible among 25-40 year old consumers prioritizing convenience and personalized nutrition stacks over traditional retail discovery.
Alternative Waters (Plant Based Waters) Market Segmentation
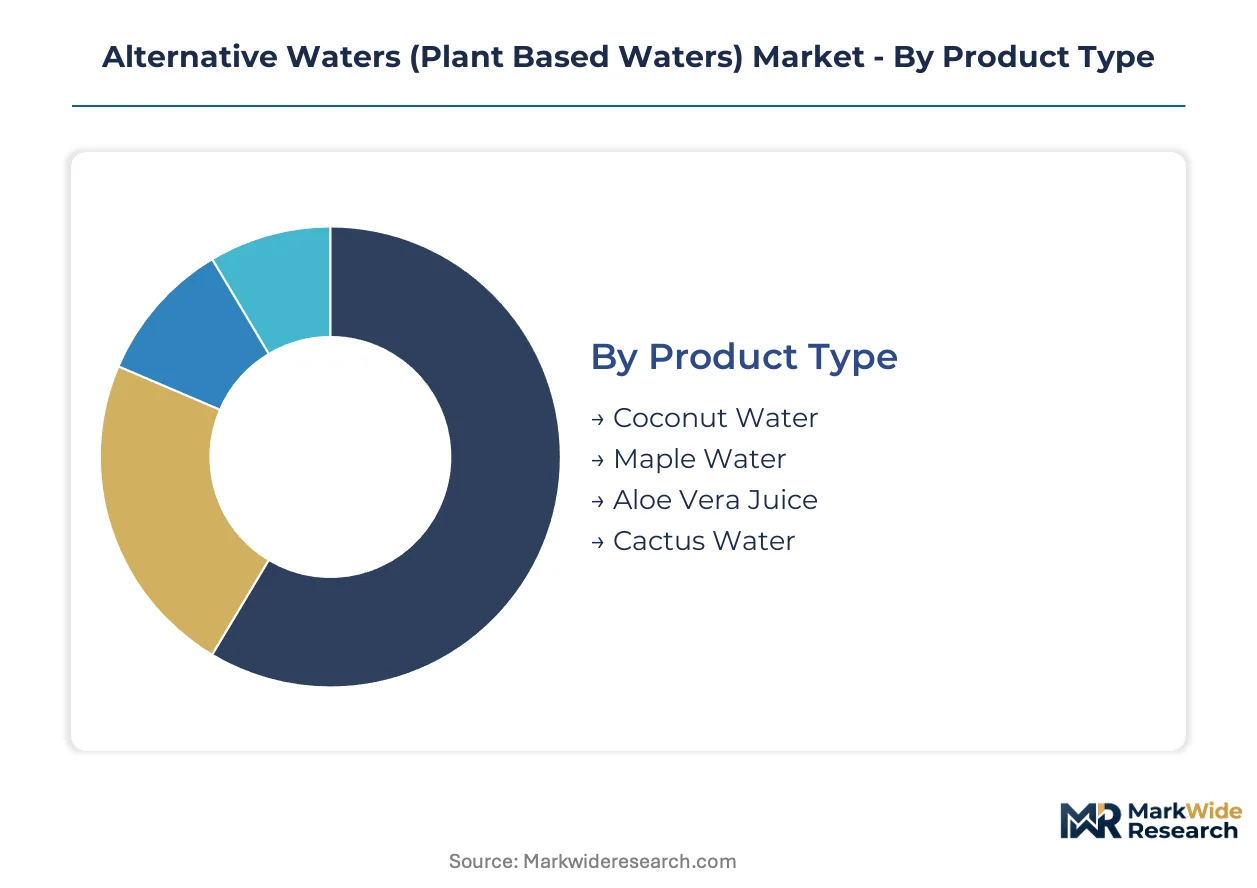
Segmentation in alternative waters reveals how processing economics, channel access, and end-use requirements fragment commercial opportunity. Supply chain configurations and regulatory exposure vary sharply across these dimensions, forcing portfolio-specific strategies rather than universal market approaches.
Product Type:
Harvest concentration and processing intensity create divergent margin structures across botanical sources.
- Coconut Water:Electrolyte-rich aqueous extract from young green coconuts, typically harvested in Indonesia, the Philippines, and Sri Lanka. Demand concentrates in United States fitness clubs and Brazilian urban centers where post-workout hydration protocols favor natural potassium and magnesium profiles over synthetic sports drinks.
- Aloe Vera Juice:Mesophyll-derived gel processed through cold pasteurization to retain polysaccharides and acemannan compounds. Premium positioning in German health stores and California specialty retailers targets digestive wellness and dermatological benefit claims, though EFSA novel food assessments constrain European launch timelines.
- Maple Water:Xylem sap harvested during early spring thaw in Quebec and Vermont maple forests, containing natural minerals and oligosaccharides.
- Cactus Water:Cladode tissue extract from Opuntia species, processed through high-pressure processing to preserve betalain antioxidants and taurine content.
Today's leader: Coconut Water. Tomorrow's challenger: Aloe Vera Juice.
Distribution Channel:
Channel selection determines regulatory exposure and margin capture, with cold-chain requirements filtering viable pathways.
- Online Retail:Direct-to-subscription platforms enable recurring revenue models for premium variants, with cold-chain logistics networks in São Paulo, London, and Los Angeles supporting curated monthly deliveries of multi-variant assortments to biohacking and longevity consumers.
- Supermarkets:Mass retail placement demands shelf-stable packaging and FDA or EFSA-compliant labeling, with German and Dutch chains prioritizing blockchain-tracked provenance to satisfy EU Green Deal carbon-footprint scorecards.
- Health Stores:Specialty retail in California and New York favors HPP-treated aloe vera and maple waters with clean-label positioning and Ayurveda-aligned marketing claims.
- Specialty Shops:Boutique hydration bars and endurance sports clubs in Brazil and the United States stock chilled coconut water for immediate post-workout consumption.
Online Retail captures margin expansion fastest. Supermarkets anchor volume scale.
Packaging Type:
Material selection reflects sustainability mandates and shelf-life engineering tradeoffs across retail formats.
- Cartons:Paperboard laminates with polyethylene barriers, favored by sustainability-focused retailers seeking reduced plastic dependency and supporting EU Green Deal compliance documentation for German and French distribution.
- Tetra Packs:Aseptic carton systems enabling ambient distribution without refrigeration, critical for coconut water exports from Southeast Asian ports to European and North American retail networks.
- Bottles:PET or glass containers for premium chilled segments in health stores and specialty shops where visual clarity and reusability signal quality differentiation.
- Pouches:Flexible film packaging for single-serve fitness and on-the-go consumption in Brazilian and United States gym channels.
Tetra Packs dominate export economics. Cartons gain share on sustainability credentials.
End User:
User context dictates formulation priorities, from electrolyte density for athletic recovery to ingredient simplicity for wellness positioning.
- Fitness Enthusiasts:Boutique gyms and endurance sports clubs in the United States and Brazil specify coconut water with verified mineral content for post-workout rehydration protocols, replacing synthetic sports drinks in membership benefit programs.
- Health-Conscious Consumers:Urban professionals in Mumbai, Bangalore, and Delhi seek Ayurveda-aligned coconut water and aloe vera variants that satisfy FSSAI fortification standards while matching disposable income expansion.
- Restaurants:Fine dining and fast-casual operators in London and Los Angeles incorporate maple water and cactus water into beverage menus and recipe formulations for clean-label appeal.
- Cafés:Coffee shop chains in São Paulo and New York test aloe vera and coconut water as smoothie bases and standalone functional hydration options.
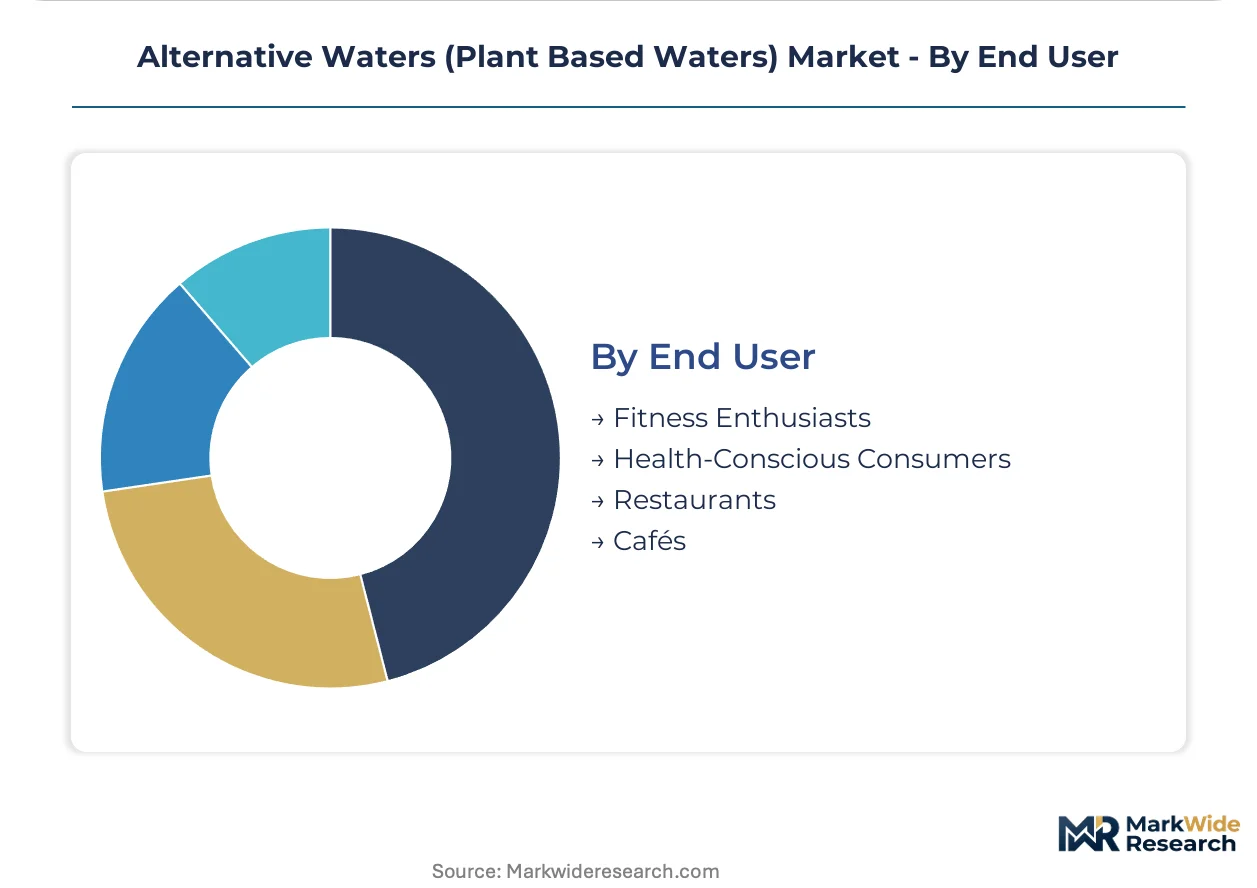
Fitness Enthusiasts drive premium pricing power. Health-Conscious Consumers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut water commercialization traces its modern roots to Brazilian street vendors and Southeast Asian processing cooperatives before scaling through North American fitness culture in the early 2000s. This historical pathway still shapes where capacity concentrates and which regulatory frameworks dominate investment decisions.
United States
Fitness clubs in Los Angeles, Miami, and New York drive chilled coconut water placement for post-workout protocols. FDA labeling requirements for electrolyte content claims force reformulation investments among imported brands. Cold-chain distribution networks from Florida ports supply the Southeast's boutique gym segment.
Germany
EU Green Deal carbon-footprint mandates pull maple water and low-emission coconut variants into mainstream retail across Berlin, Hamburg, and Munich. EFSA novel food assessments delay aloe vera juice launches by 12-18 months. Blockchain-tracked provenance systems command preferential shelf placement at sustainability-focused chains.
Brazil
Urban professionals in São Paulo and Rio de Janeiro sustain domestic coconut water consumption while export-grade processing concentrates in Ceará and Bahia. ANVISA beverage safety protocols align with FSSAI discussions for Indian market entry. Fitness enthusiasts in southeastern megacities replace synthetic sports drinks with chilled ambient variants.
India
Rising disposable incomes in Mumbai, Bangalore, and Delhi create entry points for coconut water brands with Ayurveda-aligned positioning. FSSAI fortification standards and BIS quality mandates reshape import requirements. Domestic processing capacity expands in Kerala and Tamil Nadu to serve both local consumption and Middle East export demand.
Indonesia
Harvest concentration in Sulawesi and Sumatra supplies global coconut water demand while facing EU carbon-border adjustment exposure. The country's national food safety regulator enforces export-grade cold pasteurization standards. Port congestion at Jakarta and Surabaya creates supply variability for European and North American offtake contracts.
Alternative Waters (Plant Based Waters) Market Competitive Environment
The competitive structure tilts toward diversified beverage conglomerates with existing bottling infrastructure and cold-chain networks. Capital intensity for high-pressure processing equipment and multi-jurisdiction label compliance favors scaled operators over artisanal entrants. Two archetypes dominate: legacy soft drink multinationals leveraging distribution density, and regional specialists commanding premium positioning through clean-label certifications. Competitive moves concentrate on co-packing partnerships to access HPP capacity and sustainability scorecard alignment to secure retail listings.
Among diversified beverage conglomerates, Nestle SA and The Coca-Cola Company exemplify the infrastructure-leveraged archetype, while PepsiCo Inc. occupies a parallel position with snack-and-beverage portfolio synergies. These three entities anchor the mass retail channel through existing bottling relationships and refrigerated distribution networks that mid-tier brands cannot replicate without co-packing arrangements.
| Leading Market Players |
|---|
| Nestle SA |
| Hint Water |
| The Coca-Cola Company |
| Vitamin Well AB |
| Flow Beverage Corp |
| Pepsico Inc. |
| Keurig Dr Pepper Inc. |
| San Benedetto |
| Danone |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-caps in Southeast Asian coconut processing anchor supply discipline through generational harvest relationships, while their pricing power erodes under EU carbon-border exposure and cold-chain cost inflation. Sovereign-backed cooperatives in Indonesia and the Philippines now compete for offtake contracts with private-equity-rolled-up specialists who compress procurement economics through volume aggregation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and cold-chain investment intensity. Premium tiers command shelf space through HPP treatment and blockchain provenance, while economy variants compete with commodity coconut water in Brazilian and Indian mass retail. Pricing pressure stems from EU Green Deal carbon-footprint compliance costs that processors cannot fully pass to German and Dutch buyers. Fitness enthusiasts in Los Angeles and São Paulo show least price sensitivity, while Indian urban professionals in tier-two cities drive volume through value-tier substitution.
Supply Chain Analysis
EU organic certification and FDA facility registration now gate entry for Southeast Asian processors seeking European and North American distribution. Raw material draws from young coconut harvests in Indonesia, the Philippines, and Sri Lanka, with tetra pack laminates and cold-chain logistics feeding from Chinese and European packaging suppliers. Single-source vulnerability concentrates around Jakarta and Surabaya port congestion that disrupts just-in-time delivery to German retailers. Distribution runs through co-packing networks that concentrate HPP capacity among capitalized operators with multi-jurisdiction label compliance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon-border adjustments and FDA disclosure mandates continuously revalue compliant assets above non-compliant alternatives.
For Market Incumbents: Cement shelf-stable positioning through backward integration into Indonesian and Philippine harvest networks before carbon-accounting requirements harden. Lock in co-packing arrangements with HPP-equipped processors to constrain mid-tier competitor access. Defend against direct-to-subscription entrants by controlling chilled distribution density in Los Angeles, Miami, and New York fitness channels. For New Entrants and Emerging Players: The gap between premium HPP-treated aloe vera and economy coconut water creates white-space for mid-priced maple water with clean-label positioning. Target underpenetrated Indian metropolitan markets where FSSAI fortification standards favor Ayurveda-aligned entrants over legacy multinationals. Launch through curated subscription assortments that bundle multiple botanical variants for biohacking consumers in London and São Paulo. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with EU organic certification but limited North American distribution infrastructure. Long-term viability hinges on carbon-border adaptation rather than brand equity alone. Watch for EU Green Deal implementation acceleration as the inflection signal that re-rates compliant assets against stranded processing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvest Networks | Secures low-emission coconut supply before EU carbon-border adjustments reshape import economics. |
| HPP Capacity Partnership | Unlocks premium aloe vera and cactus water positioning in California and New York health stores. |
| Direct-to-Subscription Launch | Captures recurring revenue from biohacking consumers in São Paulo and Los Angeles urban clusters. |
| EU Organic Certification Investment | Enables preferential listing terms at German and Dutch sustainability-focused retail chains. |
| Blockchain Provenance Implementation | Satisfies retailer scorecard requirements for carbon-footprint transparency across Atlantic markets. |
Study Parameters
Multiple input streams — executive interviews with beverage brand managers, procurement discussions with Southeast Asian coconut cooperatives, and regulatory filings with FDA and EFSA — were reconciled against secondary validation from customs records, Nielsen retail audit data, and EU Green Deal implementation documents. Primary fieldwork captured perspectives from category buyers at German and Dutch supermarket chains, cold-chain logistics operators in Florida and São Paulo, and HPP equipment vendors serving California processing facilities. Bottom-up volume builds by product type and packaging format were cross-checked against top-down market sizing from trade association disclosures.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, distribution channel, packaging format, and end-user context with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation adjusted for policy implementation timelines and technology adoption curves. Forecast inputs included EU carbon-border phase-in schedules, FSSAI fortification standard evolution, and HPP equipment capacity expansion pipelines.
Caveats apply where EFSA novel food assessment delays, monsoon-driven harvest variability, or port congestion at Indonesian export hubs could materially shift the outlook. Forecasts reflect assumptions about clean-label regulatory convergence and cold-chain infrastructure buildout that may accelerate or stall. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or FSSAI import requirement revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
South America Bottled Water Market
Beverages
United States Soy Beverages Market
Beverages
United States and Australia Coconut Water Market
Beverages
United States Recovery Drinks Market
Beverages
Beverage Premix Market
Beverages
United States Smoothie Market
Beverages
Oat Based Beverages Market
Beverages
Baby Drinking Water Market
Beverages
South America Mate Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Relaxation Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
Sparkling Soda Market
Beverages
Orange Juice Market
Beverages
Soft Serves Market