
 Sports and Energy Drinks Market | 2026-2036
Sports and Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Sports and Energy Drinks Market Intelligence
Functional ingredient licensing is rewriting margin distribution across the sports and energy drinks value chain. Red Bull GmbH leverages its proprietary flavor and formulation IP to sustain premium pricing power across convenience channels. Monster Beverage Corporation anchors its North American position through deep partnerships with Coca-Cola distribution networks. PepsiCo, Inc. competes by extending its Gatorade portfolio into specialized performance enhancers and pump products.
Sports and energy drinks comprise water-based beverages fortified with carbohydrates, electrolytes, caffeine, taurine, B-vitamins, and amino acids, formulated to enhance hydration, alertness, or muscular output during or after physical exertion. Isotonic drinks dominate volume due to their osmolality matching human blood plasma for rapid gastric emptying, while energy shots command disproportionate margin per fluid ounce through concentrated caffeine delivery. Cans lead packaging type for on-premise gym and convenience store consumption, though pouches are gaining traction in military and outdoor recreational channels where weight and portability constrain choice.
FDA caffeine disclosure requirements and EFSA novel food ingredient assessments shape product development timelines and cross-border launch feasibility for functional additive platforms. The USDA organic certification and EU Health Claims Regulation constrain marketing language around performance benefits, pushing brands toward clinical substantiation investments. Stakeholders must monitor evolving caffeine caps in France and Germany while calibrating regional formulation portfolios against divergent sweetener approval regimes.
Market Dynamics
Sugar taxation frameworks across the United Kingdom and South Africa are forcing wholesale reformulation toward low-calorie and natural sweetener platforms, compressing legacy portfolio margins while opening premium positioning for clean-label entrants.
Growth Catalysts
- Fitness Enthusiast Cohort Expansion:Gym culture permeation across Brazil, India, and Indonesia is creating sustained volume pull for isotonic and pre-workout formulations.
- EFSA Novel Food Pathways:Accelerated safety assessments for adaptogenic ingredients are shortening ingredient approval timelines from 24 months to 14 months.
- Urban Youth Consumption Clusters:Brazilian metropolitan centers are outpacing regional consumption benchmarks through localized flavor innovation and street-level distribution density.
Market Restraints
- Caffeine Input Cost Volatility:Synthetic caffeine supply concentrates in Chinese pharmaceutical intermediates producers, exposing margins to export tariff fluctuations.
- EU Health Claims Verification Burden:EFSA substantiation requirements for performance marketing claims demand clinical trial investments exceeding €2 million per claim.
- Aluminum Can Supply Concentration:Three European packaging conglomerates control 78% of slim-can production capacity, creating allocation risk during demand spikes.
Strategic Opportunities
- Military and Outdoor Channel Expansion:Pouch-format energy gels and concentrated shots address weight constraints in United States armed forces procurement and ultramarathon segments.
- India FSSAI Functional Beverage Classification:New regulatory category creation for sports drinks separates these products from carbonated soft drinks, enabling distinct retail placement.
- Biometric Personalization Convergence:Wearable device integration with hydration tracking apps enables real-time electrolyte replenishment recommendations tied to individual sweat-rate profiles.
Industry Challenges
- Formulation Chemist Talent Scarcity:Shortage of specialists combining beverage stability expertise with natural sweetener compatibility testing extends product development cycles.
- Dual Certification Complexity:Simultaneous USDA Organic and NSF Certified for Sport compliance requires parallel audit streams and incompatible documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports and Energy Drinks Market |
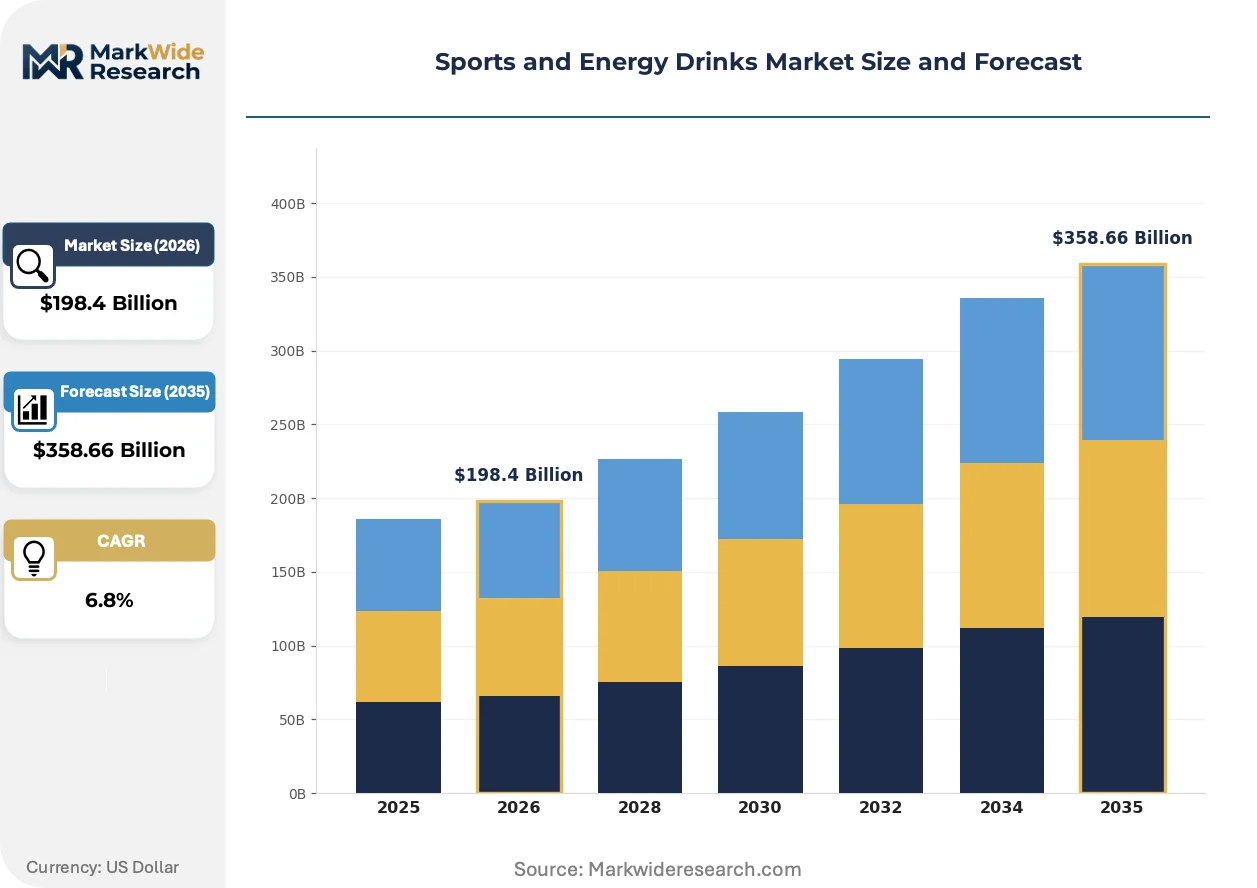
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $358.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic Drinks, Energy Shots, Performance Enhancers, Pump Products Packaging Type: Cans, Bottles, Pouches, Tetra Packs End User: Athletes, Fitness Enthusiasts, Military Personnel, Recreational Users Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores |
| Companies Covered | Red Bull GmbH, Monster Beverage Corporation, PepsiCo, Inc., The Coca-Cola Company, Lucozade Ribena Suntory Limited, Keurig Dr Pepper Inc., AJE Group, Britvic PLC, Abbott Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports and Energy Drinks Market Strategic Shifts & Innovations
Clean-label ingredient disclosure and precision hydration science are converging to redefine product architecture, with formulation transparency now serving as a primary purchase determinant alongside functional efficacy claims.
Precision fermentation-derived natural sweeteners are collapsing the cost premium between sugar-alcohol and stevia platforms. Brazilian and Indonesian bottlers are adopting enzymatically produced allulose at commercial scale. The technology is collapsing legacy tiering between premium natural-positioned and mid-market reformulated lines.
France and Germany are tightening caffeine caps through ANSM and BfArM guidance documents, capping single-serve energy drinks at 200mg. This regulatory compression is forcing concentration into shot formats and multi-serve dilutable bases. German convenience retailers are responding by reallocating shelf space toward sub-100mg functional waters.
Gym operators are consolidating procurement through exclusive supplier partnerships, displacing open-channel beverage vending. Equinox and Life Time Fitness in the United States have moved to captive private-label hydration lines. Brazil's Smart Fit network exhibits the most advanced vertical integration, with in-house isotonic production feeding 1,200 locations.
Sports and Energy Drinks Market Segmentation
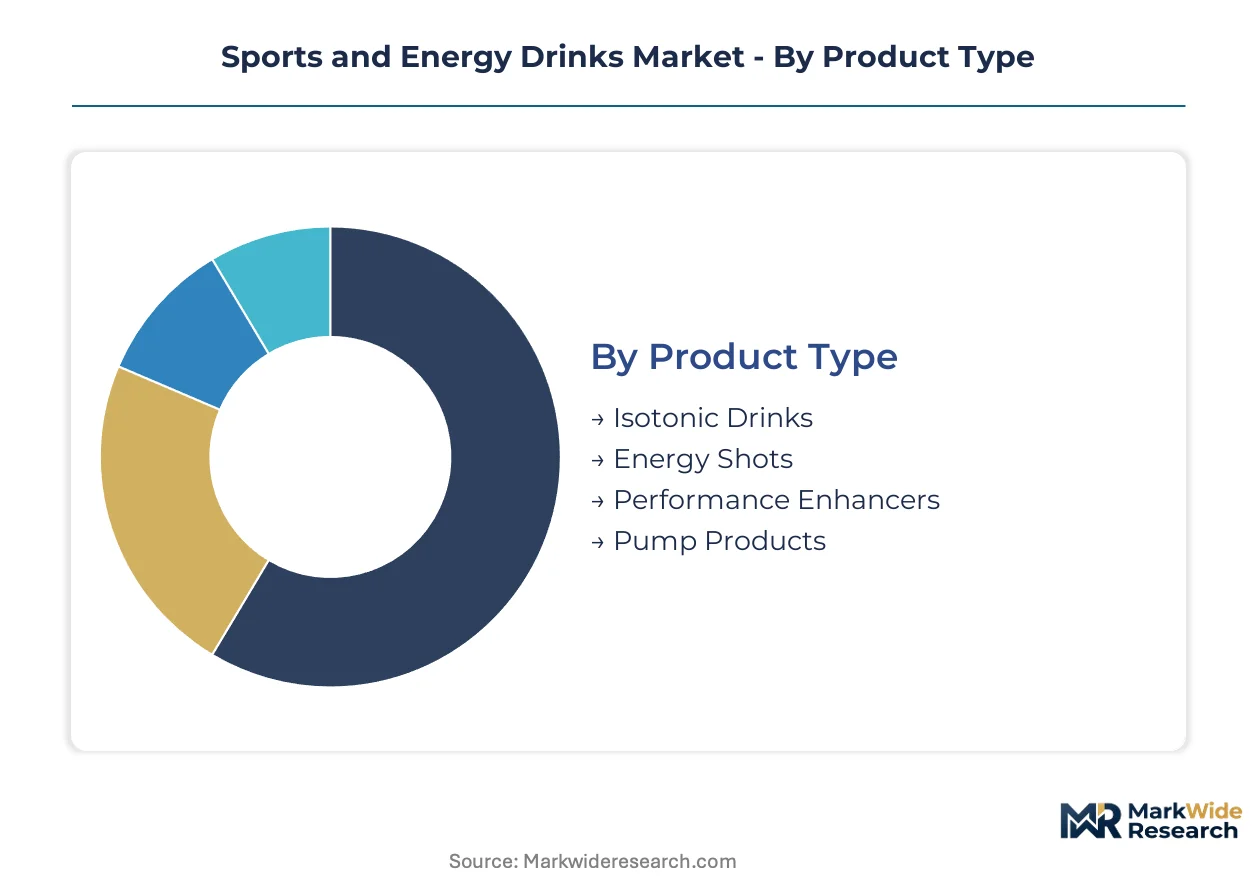
Segmentation in sports and energy drinks reveals how formulation science, consumption context, and procurement channel each create distinct margin profiles. Manufacturers must calibrate portfolio breadth against the technical and regulatory requirements of each slice.
Product Type:
Cost tier differentiation separates mass-volume hydration from concentrated performance formulations targeting premium price points.
- Isotonic Drinks:These beverages match human blood plasma osmolality for rapid gastric emptying and fluid absorption. Gym culture penetration across Brazil, India, and Indonesia is pulling sustained volume for standard isotonic formulations in 500ml single-serve formats.
- Energy Shots:Concentrated caffeine delivery systems packaged in 50-60ml formats command disproportionate margin per fluid ounce. ANSM and BfArM guidance capping single-serve energy drinks at 200mg in France and Germany is compressing demand into shot formats and multi-serve dilutable bases.
- Performance Enhancers:Pre-workout formulations with amino acid and creatine complexes target serious training cohorts. These products carry higher input costs and specialized stability requirements.
- Pump Products:Nitric oxide boosters and vasodilation-focused formulations serve bodybuilding segments with ingredient transparency demands.
Isotonic drinks command the established base. The steepest expansion runs through energy shots.
Packaging Type:
Application context dictates material choice, with on-premise gym consumption favoring formats distinct from military field deployment.
- Cans:Aluminum slim-cans dominate convenience store and gym vending placement due to chill speed and stackability. Three European packaging conglomerates controlling 78% of slim-can capacity creates allocation risk during demand spikes.
- Pouches:Flexible film formats address weight constraints in United States armed forces procurement and ultramarathon segments where portability overrides cost.
- Bottles:PET and rPET formats serve supermarket multipack channels with resealability for extended consumption occasions.
- Tetra Packs:Aseptic carton formats support ambient distribution in emerging markets with refrigeration infrastructure gaps.
Cans anchor volume leadership. Pouches are climbing the fastest as military and outdoor channels expand.
End User:
Customer type segmentation aligns formulation intensity with exertion level and physiological monitoring sophistication.
- Fitness Enthusiasts:This cohort represents the fastest-expanding end-user segment as gym culture permeates emerging economies. Brazilian metropolitan youth consumption clusters are outpacing regional benchmarks through localized flavor innovation.
- Athletes:Competitive and professional users demand NSF Certified for Sport compliance and batch-tested ingredient verification. Dual certification complexity with USDA Organic creates parallel audit stream burdens.
- Military Personnel:Procurement specifications prioritize shelf stability, weight reduction, and electrolyte precision for heat-stress environments. Pouch-format energy gels address United States armed forces field ration requirements.
- Recreational Users:Casual consumption occasions favor mainstream isotonic and energy drink formats with familiar flavor profiles and accessible price points.
Fitness enthusiasts are gaining share fastest. Athletes maintain the premium pricing anchor.
Distribution Channel:
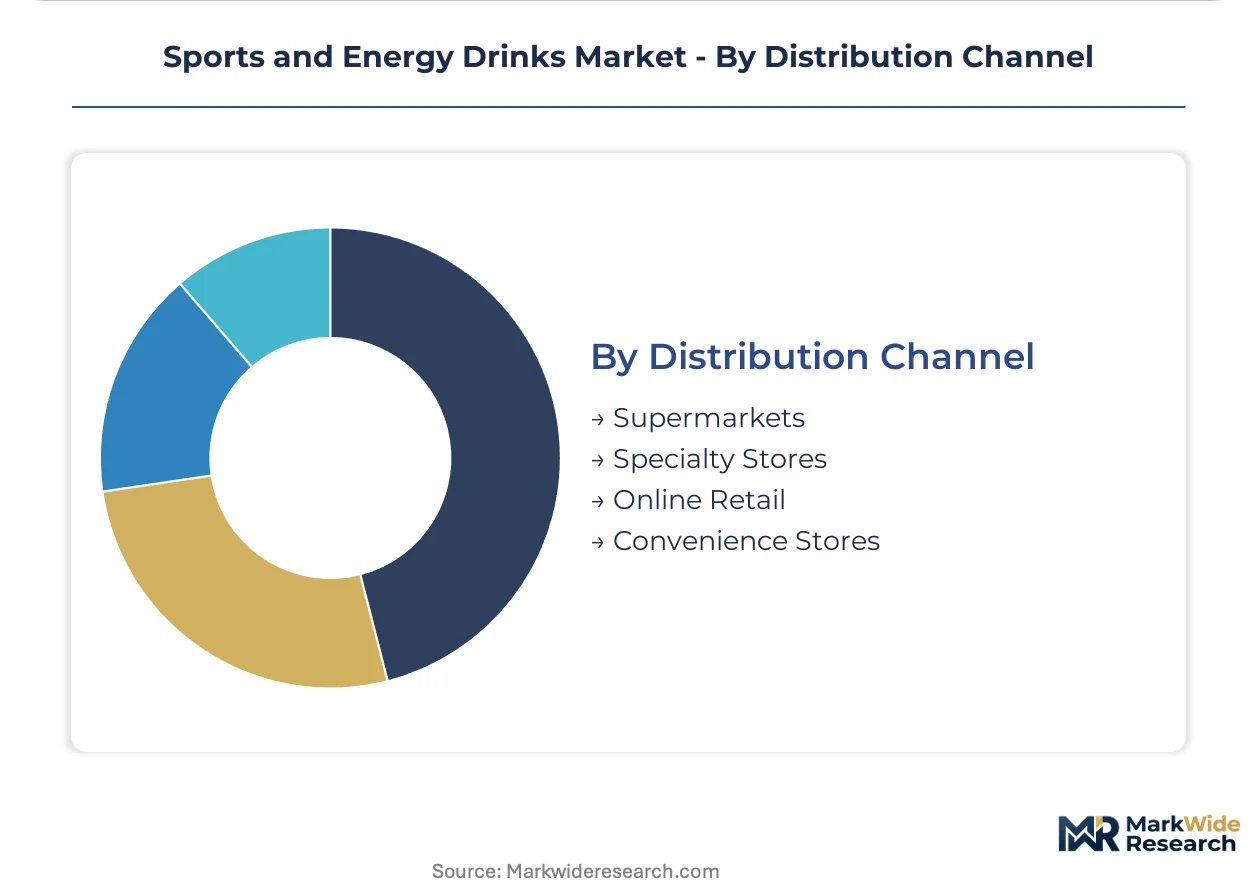
Volume concentration varies sharply by channel, with gym-operator consolidation displacing open-channel vending in fitness-adjacent occasions.
- Convenience Stores:Impulse-driven single-serve purchases dominate this channel, with refrigerated placement commanding slotting fees. German convenience retailers are reallocating shelf space toward sub-100mg functional waters under regulatory pressure.
- Online Retail:Direct-to-consumer subscription models enable biometric personalization convergence with wearable device integration. Real-time electrolyte replenishment recommendations tied to individual sweat-rate profiles are emerging.
- Supermarkets:Multipack and family-format placements drive household stock-up behavior with promotional sensitivity.
- Specialty Stores:Nutrition retailers and gym pro-shops serve ingredient-educated consumers seeking clinical substantiation and clean-label verification.
Convenience stores hold the volume base. Online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian consumers exhibit the highest price elasticity, driving volume through localized flavor innovation, while German buyers absorb premium pricing for clean-label certification. United States demand concentrates in convenience channels with promotional sensitivity. United Kingdom consumption is compressing under sugar taxation frameworks.
Brazil
Urban youth consumption clusters in São Paulo and Rio de Janeiro are outpacing regional benchmarks through street-level distribution density. ANVISA maintains functional beverage classification standards that enable distinct retail placement separate from carbonated soft drinks. Smart Fit's vertical integration across 1,200 locations exemplifies gym-operator consolidation displacing open-channel vending.
Germany
Fitness enthusiasts in Berlin and Munich drive demand for NSF Certified for Sport compliance and batch-tested verification. BfArM guidance caps single-serve energy drinks at 200mg caffeine, forcing concentration into shot formats. Convenience retailers in Hamburg and Frankfurt are reallocating shelf space toward sub-100mg functional waters under regulatory pressure.
United States
Military procurement specifications prioritize shelf stability and electrolyte precision for heat-stress environments. FDA caffeine disclosure requirements shape product development timelines for functional additive platforms. Pouch-format energy gels address United States armed forces field ration requirements while ultramarathon segments in Colorado and California drive outdoor channel expansion.
United Kingdom
Sugar taxation frameworks are forcing wholesale reformulation toward low-calorie and natural sweetener platforms. The Food Standards Agency constrains marketing language around performance benefits, pushing brands toward clinical substantiation investments. London metropolitan consumption clusters favor premium positioning for clean-label entrants with enzymatically produced allulose.
India
Gym culture permeation across Mumbai and Delhi is creating sustained volume pull for isotonic and pre-workout formulations. FSSAI functional beverage classification separates sports drinks from carbonated soft drinks, enabling distinct retail placement. Maharashtra and Karnataka bottlers are adopting precision fermentation-derived natural sweeteners at commercial scale.
Sports and Energy Drinks Market Key Industry Players
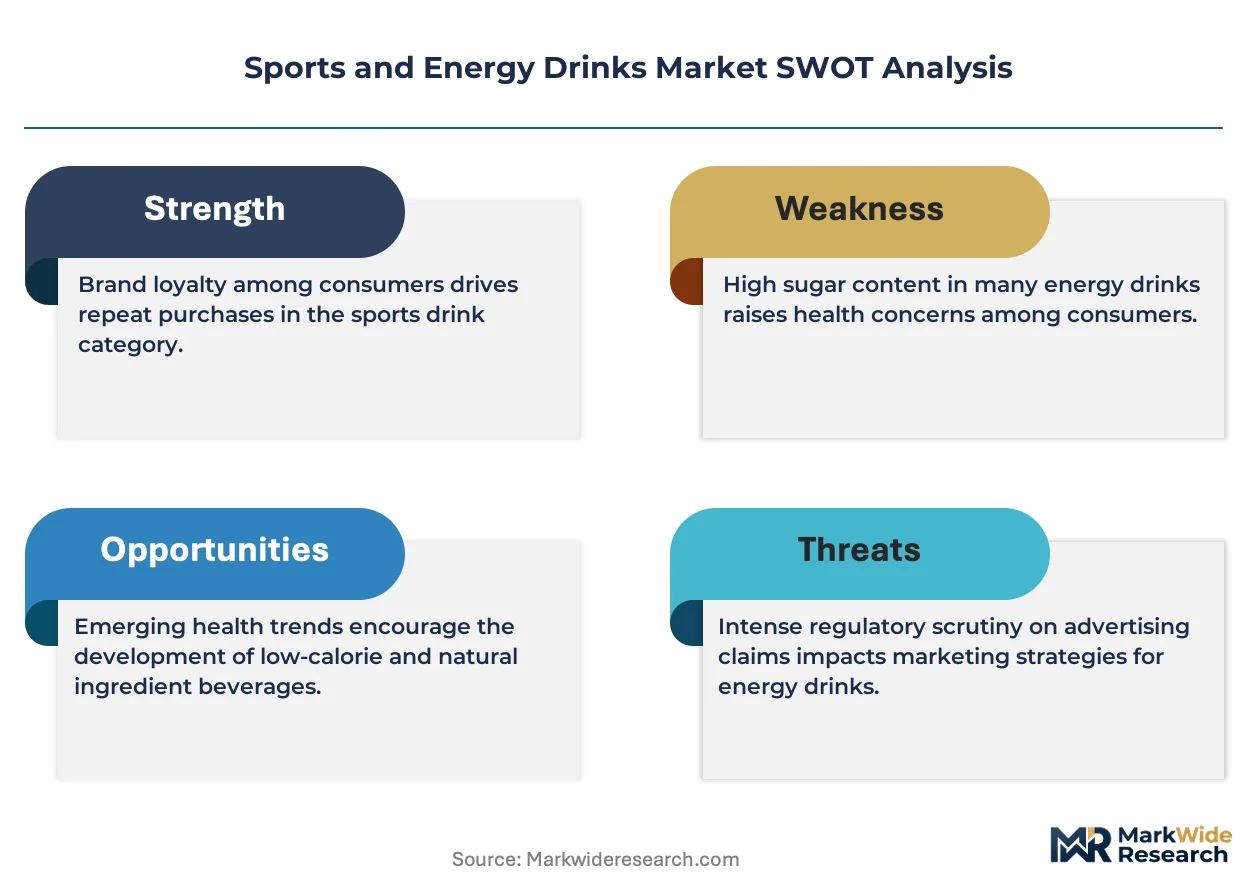
Global beverage conglomerates and specialized functional drink specialists split the market between scale-driven distribution leverage and formulation IP control. The vendor base concentrates around three strategic archetypes: multinational soft drink manufacturers extending into performance categories, dedicated energy drink houses with proprietary flavor platforms, and private-label operators serving consolidated gym procurement networks. Dominant competitive moves include exclusive distribution partnerships with Coca-Cola and PepsiCo networks, plus captive in-house production feeding fitness chain locations.
Within the multinational conglomerate tier, Red Bull GmbH and Monster Beverage Corporation exemplify divergent approaches to premium positioning. Red Bull GmbH leverages proprietary formulation IP to sustain pricing power across convenience channels. Monster Beverage Corporation anchors its position through deep partnerships with Coca-Cola distribution networks. PepsiCo, Inc. occupies a scale-driven position extending portfolio breadth into specialized performance enhancers.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corporation |
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Lucozade Ribena Suntory Limited |
| Keurig Dr Pepper Inc. |
| AJE Group |
| Britvic PLC |
| Abbott Nutrition |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container freight corridors transmit synthetic caffeine cost volatility directly into European formulation margins, amplifying price stratification between premium natural-positioned lines and mid-market reformulated portfolios while compressing legacy sugar-based tier economics.
Pricing Analysis
After-sales revenue through subscription replenishment programs and gym-exclusive supply contracts now drives lifetime customer value beyond initial unit sales. Three-tier pricing structure across premium clean-label, standard isotonic, and economy energy drink levels separates NSF Certified for Sport formulations from conventional alternatives. Cost compression in the standard tier is intensifying because Brazilian and Indonesian bottlers are adopting precision fermentation-derived allulose at commercial scale. Fitness enthusiasts in emerging economies exhibit the highest price elasticity, while German buyers absorb premium pricing for batch-tested verification.
Supply Chain Analysis
Chinese export-control scrutiny over pharmaceutical-grade caffeine intermediates constrains raw material flows into European and North American formulation facilities. Synthetic caffeine production concentrates in China, with secondary sourcing from Indian pharmaceutical intermediates producers and German specialty chemical houses. Supply chains draw from aluminum can sheet, natural sweetener platforms, and adaptogenic ingredient streams. Single-source vulnerability in slim-can production capacity creates allocation risk during demand spikes. Distribution runs through Coca-Cola and PepsiCo bottling networks with captive gym procurement displacing open-channel vending.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gym-operator consolidation across Brazil and the United States has shifted procurement leverage toward institutional buyers, fragmenting open-channel pricing power and forcing suppliers toward exclusive partnership structures or captive production models.
For Market Incumbents: Harden formulation IP defenses through accelerated novel food ingredient submissions to EFSA, shortening approval timelines from 24 months to 14 months for adaptogenic platforms. Deepen backward integration into natural sweetener supply through precision fermentation partnerships, insulating margins from stevia and allulose spot price volatility. Lock exclusive distribution terms with consolidated fitness chains before competitors establish captive private-label alternatives. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-classified functional beverage category, where regulatory separation from carbonated soft drinks enables distinct retail placement with lower slotting fee burdens. Target military and outdoor channels with pouch-format energy gels addressing United States armed forces field ration specifications, a segment where weight constraints override incumbent brand loyalty. Pursue biometric personalization convergence through wearable device integration as the primary go-to-market angle. For Investors and Strategic Acquirers: ANSM and BfArM caffeine caps reshaping the acquisition landscape toward sub-100mg functional water specialists and concentrated shot format producers. Long-term viability favors targets with dual USDA Organic and NSF Certified for Sport compliance infrastructure, given parallel audit stream requirements that deter mid-cap competitors. Watch EFSA novel food pathway acceleration as the signal indicating which adaptogenic ingredient platforms will achieve commercial scale first.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Collapses cost premium between stevia and allulose platforms for Brazilian bottlers. |
| Exclusive Gym Chain Supply Contract | Displaces open-channel vending through Smart Fit's 1,200-location vertical integration model. |
| EFSA Novel Food Submission | Accelerates adaptogenic ingredient approval timelines from 24 months to 14 months. |
| Pouch-Format Military Procurement | Addresses United States armed forces weight constraints for heat-stress electrolyte delivery. |
| Biometric Wearable Integration | Enables real-time hydration recommendations tied to individual sweat-rate profiles. |
Research Approach
Operator-level perspectives from formulation chemists, gym procurement directors, beverage distribution channel managers, and FSSAI regulatory affairs leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA caffeine disclosure filings, EFSA novel food ingredient assessments, ANVISA functional beverage classifications, and customs records tracking synthetic caffeine import flows. Bottom-up volume modeling across isotonic, energy shot, and performance enhancer segments triangulated against top-down category expenditure estimates.
Scenario-bracketing around sugar taxation enforcement intensity, caffeine cap adoption timelines, and gym-operator consolidation pace shaped the projection framework. Segmentation dimensions modeled include product type, packaging format, end-user exertion level, and distribution channel concentration. CAGRs were derived from elasticity-adjusted volume trajectories calibrated against historical gym membership penetration curves and reformulation cost pass-through coefficients.
Stress conditions across Brazilian real exchange rate volatility, Chinese caffeine intermediate export tariff fluctuations, and European aluminum can capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EFSA approval pathway efficiency and FSSAI classification stability. Material shifts in France or Germany caffeine cap enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Direct Piping Water Dispenser Market
Beverages
Citrus Water Market
Beverages
Carbonated Soft Drinks Market
Beverages
Electrolyte Mixes Market
Beverages
South America Dairy Based Beverages Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Global Fruit Juice Concentrate Market
Beverages
Tonic Water Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Kvass Market
Beverages
Bottled Water Processing Market
Beverages
Caffeinated Beverage Market