
 GCC Solar Water Heater Market | 2026-2036
GCC Solar Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Solar Water Heater Market Intelligence
The gap between premium European-engineered systems and commodity Asian-sourced units is realigning procurement patterns across GCC project pipelines. Viessmann Middle East leverages its forced-circulation engineering heritage to dominate high-spec commercial tenders in Qatar and Kuwait. Ariston Thermo Middle East anchors the residential replacement segment through established distribution across UAE retail channels. Saudi Ceramic Company competes on localized manufacturing scale, supplying flat-plate collectors to Saudi Vision 2030 housing developments.
A solar water heater converts solar radiation into thermal energy through absorber plates or evacuated tubes, transferring heat to potable water via direct or indirect circulation loops operating at 60–80°C delivery temperatures. Evacuated tube collectors capture premium margins in high-temperature industrial pre-heat applications across Gulf petrochemical facilities. Flat-plate collectors sustain volume leadership in residential roof-mounted installations where thermosiphon technology eliminates pump dependency. Forced circulation systems extend into commercial segments requiring pressurized distribution across multi-story buildings.
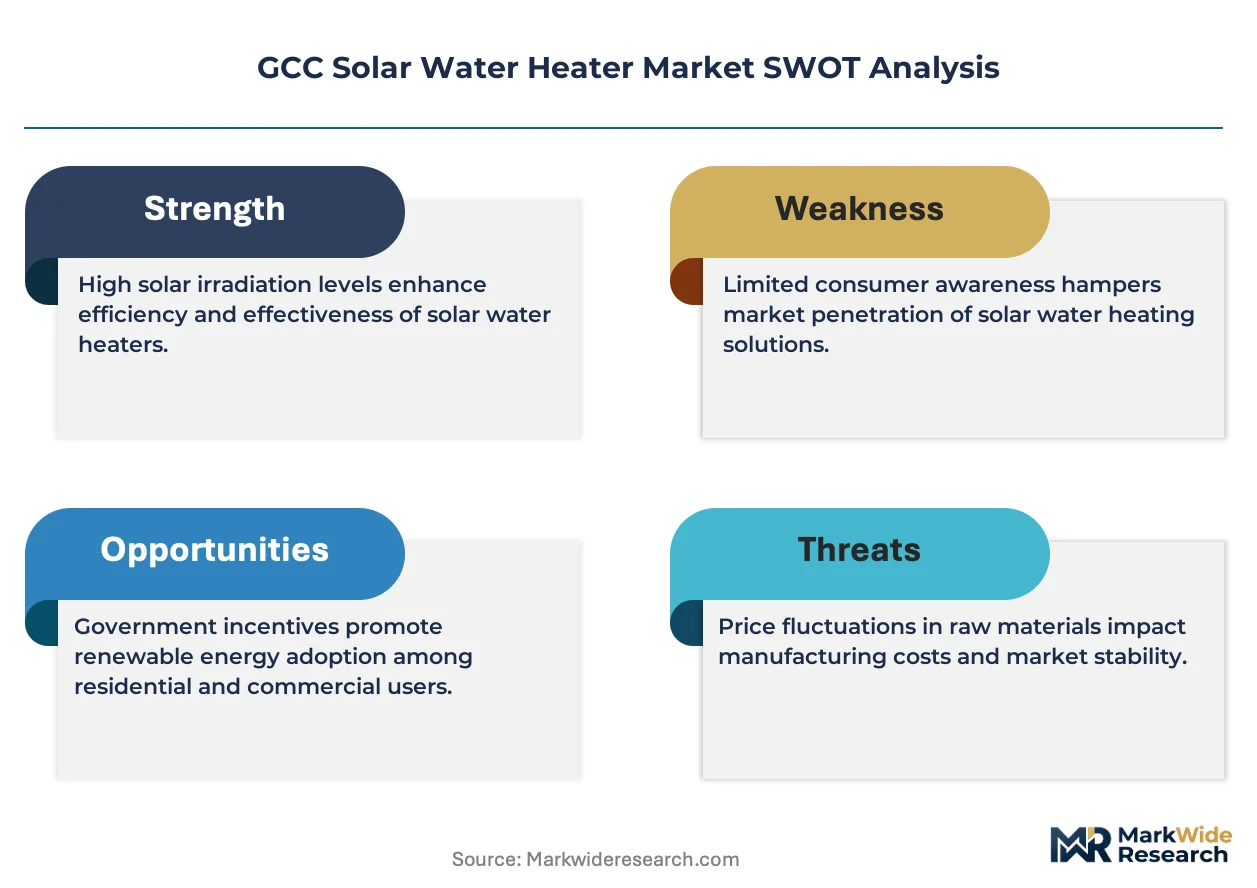
Saudi Building Code mandates solar-ready plumbing in new residential construction above specified floor areas, while UAE's Estidama Pearl Rating System awards credits for renewable thermal integration. The Saudi Standards, Metrology and Quality Organization (SASO) and Emirates Authority for Standardization and Metrology (ESMA) enforce collector efficiency testing protocols that filter non-compliant imports. Stakeholders must monitor how Saudi Arabia's Renewable Energy Project Development Office and UAE's Al Dhafra Solar PV program redirect utility-scale investment toward distributed thermal applications.
Market Dynamics
Mandatory renewable thermal integration in Saudi and Emirati building codes is compressing installation timelines and forcing specification upgrades across project pipelines. Developers now front-load solar water heater procurement to secure Pearl Rating credits and SASO compliance certificates before concrete pours begin.
Growth Catalysts
- Estidama Pearl Rating System:UAE's green building framework mandates renewable energy credits that solar thermal systems satisfy cost-effectively. Abu Dhabi developers embed collectors during shell construction to secure certification.
- Saudi Vision 2030 housing:Government-backed residential programs in the Eastern Province specify flat-plate collectors for mass-scale deployment. Local manufacturing satisfies procurement localization requirements.
- Evacuated tube efficiency gains:Advanced selective coatings push thermal conversion rates above 80% in high-temperature pre-heat applications. Gulf petrochemical facilities specify these for process heat integration.
Market Restraints
- Copper and aluminum input volatility:Absorber plate manufacturing depends on non-ferrous metals priced on LME benchmarks. Margin compression hits when commodity cycles spike.
- Import concentration from East Asian supply bases:Commodity vacuum tube assemblies ship from concentrated manufacturing zones. Geopolitical friction or shipping disruptions strain project timelines.
- Thermosiphon limitations in high-rise construction:Passive circulation fails above 15-meter hydraulic heads. Pump-dependent forced systems add capex and maintenance burdens.
Strategic Opportunities
- Kuwait's stalled regulatory framework:Absence of mandatory solar thermal codes leaves white space for first-mover positioning. Early entrants shape technical specifications before codification.
- Qatar's district cooling integration:Solar pre-heat for absorption chillers creates hybrid thermal-electric value propositions. Lusail City developments pilot combined systems.
- Oman's rural electrification gaps:Off-grid residential clusters in Dhofar and Al Wusta lack gas infrastructure. Solar thermosiphon systems bypass grid dependency entirely.
Industry Challenges
- Skilled installer scarcity:Proper collector mounting, sealing, and glycol charging require certified technicians. Training pipelines lag deployment targets in Saudi Arabia's housing push.
- SASO efficiency testing bottlenecks:Import clearance requires third-party thermal performance verification. Laboratory capacity constraints delay project starts.
- Legacy tank compatibility:Existing electric heater footprints resist solar coil retrofits. Demolition and replumbing costs erode payback calculations in replacement segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Solar Water Heater Market |
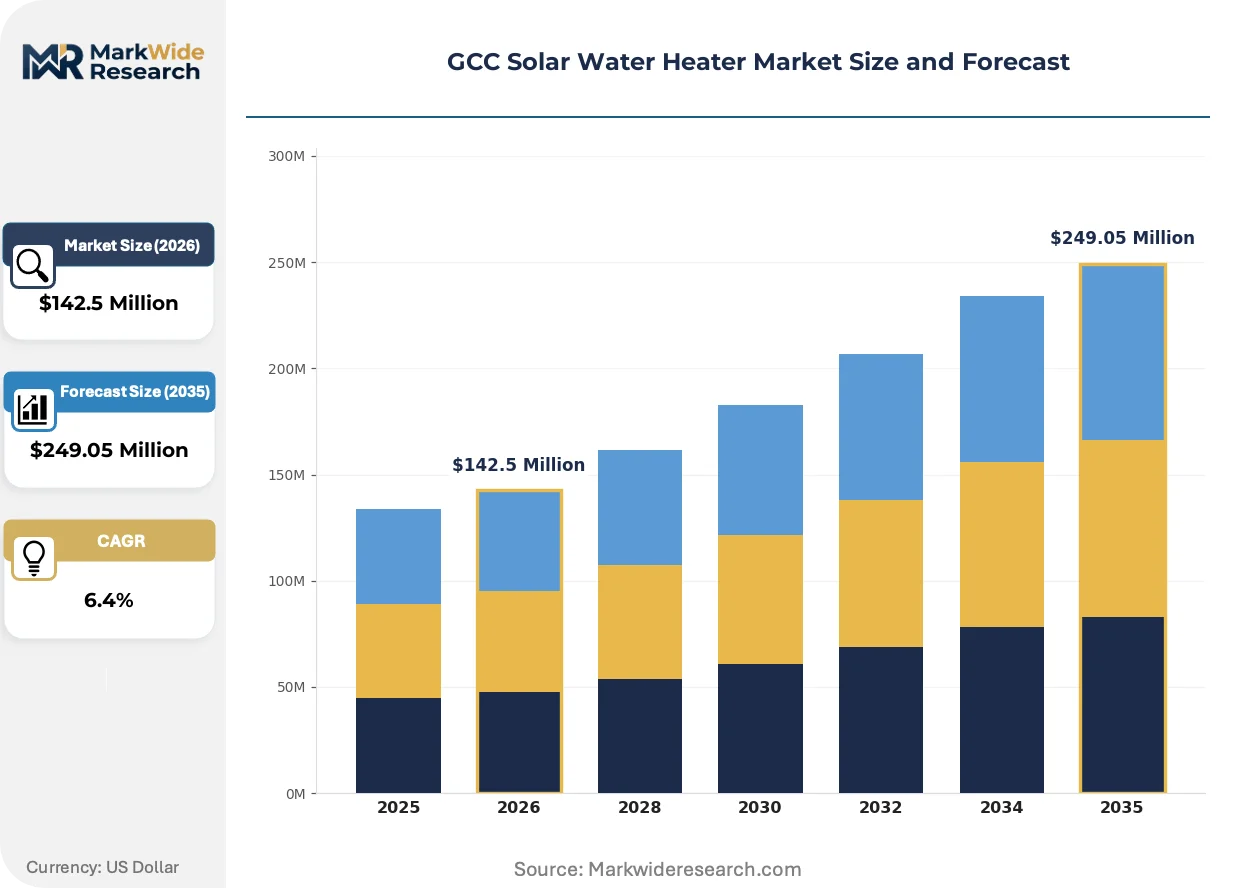
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate Collectors, Evacuated Tube Collectors, Integrated Systems, Heat Exchangers End User: Residential, Commercial, Industrial, Government Installation Type: Roof-mounted, Ground-mounted, Integrated, Standalone Technology: Thermosiphon, Forced Circulation, Drainback, Hybrid |
| Companies Covered | Ariston Holding N.V., Orbital Horizon, Saudi Ceramic Company, Viessmann Group, Ecotherm Austria GmbH, Rheem Middle East, Ariston Thermo Middle East, Viessmann Middle East, A.O. Smith, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Solar Water Heater Market Strategic Shifts & Innovations
Heat pump-solar hybrid architectures are reconfiguring system economics across Gulf commercial specifications. Manufacturers now engineer integrated controllers that optimize between solar gain and coefficient-of-performance thresholds.
Phase-change material thermal storage is electrifying project feasibility in high-consumption hospitality and healthcare verticals. Dubai hotel operators specify PCM-integrated systems to buffer against intermittent solar availability. The technology compresses auxiliary heating runtime and shrinks battery-electric backup requirements.
Saudi Standards, Metrology and Quality Organization thermal performance protocols are tightening collector import eligibility. Non-compliant Asian-sourced units face automatic customs rejection. European and regional manufacturers with certified testing partnerships capture specification slots in Riyadh and Jeddah mega-projects.
Direct procurement from engineering-procurement-construction consortia is displacing traditional distributor channels in commercial segments. Bahrain and Qatar developers now issue solar thermal packages as integrated MEP lots. This rotation concentrates volume with firms offering turnkey design-build-finance structures.
GCC Solar Water Heater Market Segmentation
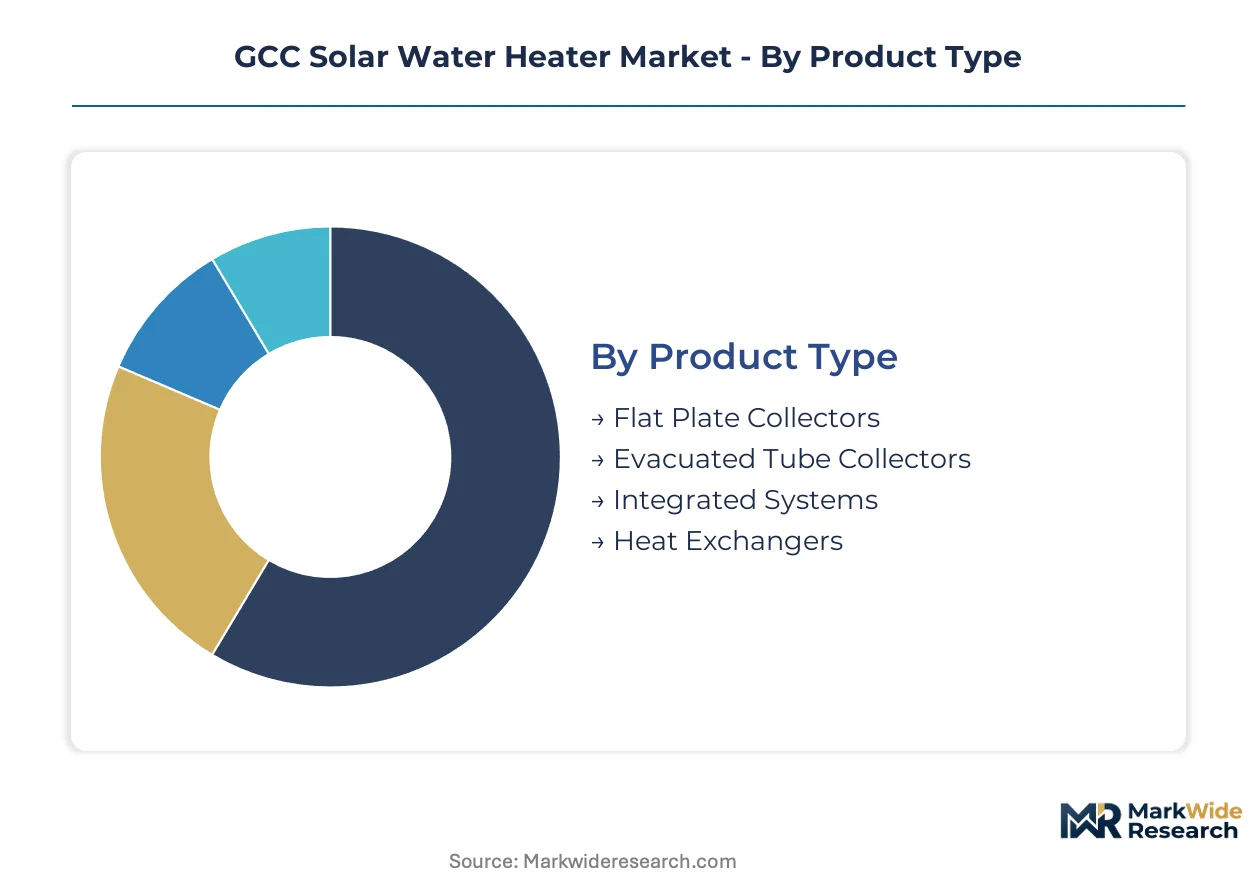
Segmentation in the GCC solar water heater market reveals how procurement specifications diverge across building typologies and thermal load profiles. Upgrade cycles and replacement demand vary sharply between residential retrofits and new commercial construction, reshaping vendor targeting strategies across Saudi Arabia and the UAE.
Product Type:
Replacement cycles in Saudi Vision 2030 housing developments and Dubai's Estidama-certified stock are accelerating specification upgrades from basic flat-plate units toward higher-performance evacuated tube and integrated system architectures.
- Flat Plate Collectors:Aluminum-copper absorber plate assemblies with tempered glass glazing dominate mass residential deployment in Saudi Arabia's Eastern Province housing programs. Riyadh and Jeddah developers specify these for cost-sensitive, high-volume installations where thermosiphon simplicity reduces maintenance overhead.
- Evacuated Tube Collectors:Borosilicate glass vacuum tubes with selective absorption coatings deliver superior thermal conversion in high-temperature pre-heat applications across Gulf petrochemical facilities. Abu Dhabi and Qatar industrial buyers specify these for process heat integration where delivery temperatures exceed standard flat-plate thresholds.
- Integrated Systems:Factory-assembled collector-storage combinations streamline installation timelines for UAE retail channel distribution.
- Heat Exchangers:Indirect circulation components enable freeze-protected operation in northern GCC climates.
Volume placements concentrate in Flat Plate Collectors; the faster expansion belongs to Evacuated Tube Collectors.
End User:
Cost tier stratification separates premium-engineered commercial and industrial specifications from standardized residential units, with government procurement occupying a mid-tier position emphasizing localization compliance.
- Residential:Thermosiphon roof-mounted systems serve villa and low-rise apartment stock across Dubai's Al Barsha district and Riyadh's suburban developments. Estidama Pearl Rating credits and Saudi Building Code mandates are compressing installation timelines for new construction while replacement demand builds in 10-15 year installed base.
- Commercial:Forced circulation multi-collector arrays address hotels, hospitals, and office complexes in Abu Dhabi's Al Reem Island and Doha's Lusail City. Heat pump-solar hybrid architectures are gaining specification share in high-consumption hospitality verticals where phase-change material storage buffers intermittent solar availability.
- Industrial:Process heat pre-heat applications concentrate in Eastern Province petrochemical clusters.
- Government:Saudi Vision 2030 and UAE federal housing programs drive standardized procurement at scale.
Residential channels deliver the highest absolute unit volumes; commercial segments are climbing the fastest as green building codes tighten across the Emirates and Qatar.
Installation Type:
Application context determines mounting configuration, with urban density in Dubai and Doha favoring roof-integrated solutions while Saudi Arabia's horizontal development patterns accommodate ground-mounted arrays.
- Roof-mounted:Standard configuration for villa and low-rise construction across GCC residential stock.
- Ground-mounted:Industrial-scale collector fields serve process heat applications in Jubail and Yanbu industrial cities.
- Integrated:Building-integrated solar thermal (BIST) systems embed collectors within facade and roofing assemblies for high-spec commercial projects in Kuwait City and Manama.
- Standalone:Off-grid thermosiphon units address rural electrification gaps in Oman's Dhofar and Al Wusta governorates.
Roof-mounted configurations retain volume leadership; integrated installations are gaining specification share fastest in premium commercial segments.
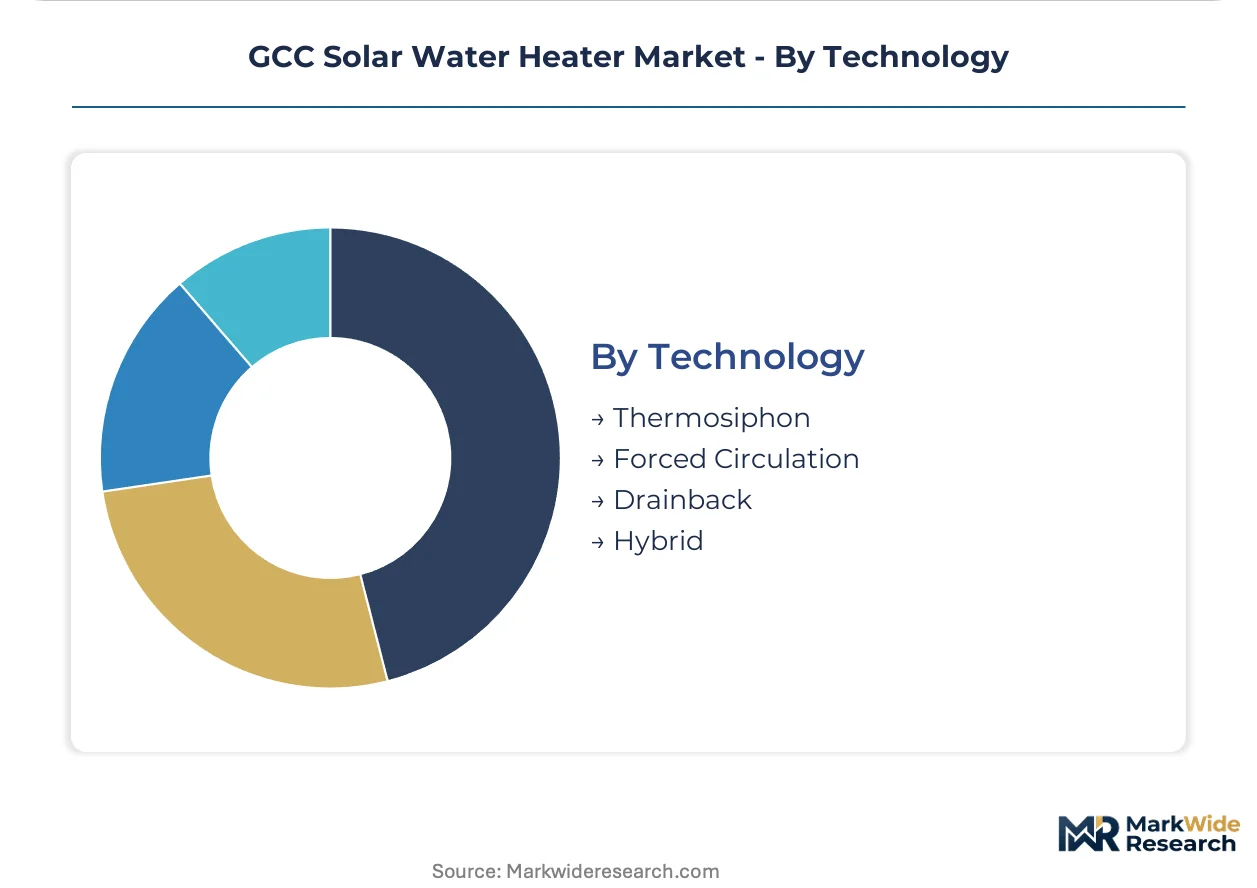
Technology:
Customer type segmentation separates passive gravity-driven systems for price-sensitive residential buyers from active pumped configurations serving multi-story commercial and industrial clients with pressurized distribution requirements.
- Thermosiphon:Passive circulation via density differential eliminates pump dependency in single-story and low-rise residential applications across Saudi Arabia's mass housing programs. The technology's 15-meter hydraulic head limitation constrains deployment in high-rise construction.
- Forced Circulation:Pump-driven closed-loop systems with expansion vessels and glycol charging extend into commercial multi-story buildings and industrial process heat networks. Qatar's Lusail City district cooling integration and Dubai hotel specifications rely on these for reliable high-pressure distribution.
- Drainback:Freeze-protection without glycol simplifies maintenance in northern GCC climates.
- Hybrid:Solar-heat pump combinations optimize between thermal gain and coefficient-of-performance thresholds.
Thermosiphon technology dominates unit placements; forced circulation systems are expanding most quickly as commercial construction intensifies across Doha and Abu Dhabi.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Al Barsha district and Riyadh's suburban corridors concentrate residential thermosiphon deployments as Saudi Vision 2030 and Estidama mandates compress installation timelines. Developers across both metros front-load collector procurement to secure compliance certificates before construction begins.
Saudi Arabia
The Eastern Province housing programs drive flat-plate collector volumes at mass scale. SASO efficiency testing protocols filter non-compliant imports at customs checkpoints. Jubail and Yanbu industrial cities specify evacuated tube arrays for process heat pre-heat in petrochemical clusters.
United Arab Emirates
Abu Dhabi's Al Reem Island developments embed collectors during shell construction to secure Pearl Rating credits. Dubai hotel operators specify phase-change material storage systems to buffer intermittent solar availability. Emirates Authority for Standardization and Metrology enforces collector efficiency benchmarks that redirect procurement toward certified suppliers.
Qatar
Lusail City pilots solar pre-heat integration with district cooling absorption chillers. Forced circulation multi-collector arrays address hospitality and healthcare verticals in Doha's expanding commercial core. The absence of mandatory solar thermal codes leaves specification flexibility for hybrid thermal-electric architectures.
Kuwait
Kuwait City's premium commercial segments specify building-integrated solar thermal systems for high-spec facade applications. The stalled regulatory framework creates white space for first-mover positioning before codification. Early entrants shape technical specifications that will anchor future compliance requirements.
Oman
Dhofar and Al Wusta governorates deploy off-grid thermosiphon units where rural electrification gaps persist. Standalone configurations bypass gas infrastructure dependency entirely. The country's mountainous terrain and dispersed settlement patterns favor passive circulation systems over pump-dependent alternatives.
GCC Solar Water Heater Market Key Industry Players
Capital-heavy manufacturers with in-house absorber plate production compete with asset-light distributors importing vacuum tube assemblies from concentrated East Asian supply bases. The market structure fragments across three strategic tiers: European-engineered premium specialists, regional fabricators leveraging localization requirements, and commodity traders supplying price-sensitive residential retrofits. Dominant competitive moves include backward integration into copper and aluminum sourcing to hedge LME volatility, and strategic partnerships with engineering-procurement-construction consortia to capture integrated MEP lot awards.
Within the European-engineered tier, Viessmann Middle East and Ariston Thermo Middle East exemplify specification-driven positioning in high-value commercial tenders and established retail channels respectively. Saudi Ceramic Company anchors the regional fabrication archetype, supplying flat-plate collectors to government-backed housing programs where procurement localization requirements filter import dependency. These three entities represent the competitive spectrum from premium forced-circulation engineering to mass-market thermosiphon deployment across the GCC project pipeline.
| Leading Market Players |
|---|
| Ariston Holding N.V. |
| Orbital Horizon |
| Saudi Ceramic Company |
| Viessmann Group |
| Ecotherm Austria GmbH |
| Rheem Middle East |
| Ariston Thermo Middle East |
| Viessmann Middle East |
| A.O. Smith |
| Others |
Cost & Logistics Intelligence
European-engineered forced-circulation systems and commodity Asian-sourced thermosiphon units diverge across a certification ladder anchored by SASO thermal performance protocols and ESMA efficiency benchmarks, with this bifurcation manifesting in project-based procurement premiums for certified suppliers versus spot-market vulnerability for non-compliant imports. Pricing power concentrates with manufacturers holding in-house absorber plate production and accredited testing partnerships, while distributors of vacuum tube assemblies face margin compression from LME copper and aluminum volatility.
Pricing Analysis
Value-based pricing anchored to Estidama Pearl Rating compliance and SASO certification throughput dominates commercial tender awards in Riyadh and Abu Dhabi. Price differentiation separates European-engineered forced-circulation systems with full testing documentation from commodity Asian units facing customs rejection. Cost compression in the thermosiphon residential tier intensifies because Saudi Vision 2030 housing programs drive volume procurement at standardized specifications. Government-backed developers exhibit lowest price sensitivity; retail channel replacement buyers in Dubai's Al Barsha district demonstrate highest sensitivity to upfront capex.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Dammam operate hub-and-spoke patterns serving project sites across the GCC. Manufacturing concentrates in China for vacuum tube assemblies, Germany for selective coating technology, and Saudi Arabia for localized flat-plate collector fabrication. Raw material inputs draw from LME-tracked copper and aluminum for absorber plates, borosilicate glass for evacuated tubes, and tempered glass for glazing. Single-source vulnerability in East Asian vacuum tube supply strains project timelines when shipping disruptions occur. Distribution runs through engineering-procurement-construction consortia capturing integrated MEP lot awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC solar water heater market sits in a technology-transition phase as heat pump-solar hybrid architectures displace legacy thermosiphon dominance in commercial specifications. Phase-change material thermal storage and integrated control systems are replacing passive circulation in high-consumption verticals.
For Market Incumbents: Deploy backward integration into copper and aluminum sourcing to hedge LME volatility exposure threatening absorber plate margins. Incumbents must secure SASO and ESMA testing partnerships before customs protocols tighten further, while expanding captive distribution through EPC consortium relationships to defend against distributor disintermediation in commercial segments.
For New Entrants and Emerging Players: Engineering-procurement-construction consortia represent the most penetrable channel for bypassing established retail distribution. New entrants should target Kuwait's stalled regulatory white space before mandatory solar thermal codes crystallize, and position for Qatar's district cooling integration pilots in Lusail City through hybrid thermal-electric system offerings.
For Investors and Strategic Acquirers: Re-rating potential sits with regional fabricators holding localized manufacturing scale and government procurement relationships given Saudi Vision 2030 localization requirements. Long-term viability favors absorber plate producers with in-house production over asset-light distributors. The signal to watch is SASO laboratory capacity expansion indicating enforcement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Materials | Captive copper and aluminum supply hedges LME volatility for absorber plate manufacturers. |
| SASO Certification Investment | Accredited testing partnerships unlock customs clearance for Riyadh and Jeddah mega-project specifications. |
| EPC Consortium Partnerships | Integrated MEP lot awards displace traditional distributor channels in commercial segments. |
| Heat Pump-Solar Hybrid Development | Phase-change material integration addresses Dubai hospitality vertical demand for thermal buffering. |
| Kuwait First-Mover Positioning | Early technical specification influence before mandatory solar thermal codification closes white space. |
Research Approach
Independent corroboration across primary interviews with solar thermal engineering directors, EPC procurement leads, and regulatory compliance officers at SASO and ESMA underwrites the qualitative findings. Secondary validation draws from customs import databases, green building certification registries, and housing program procurement disclosures. Bottom-up collector shipment data triangulates against top-down construction permit analysis across Saudi Arabia's Eastern Province and UAE's Abu Dhabi emirate.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation across product type, end user, installation configuration, and circulation technology. CAGRs derive from installed base replacement cycles, new construction mandates, and industrial process heat adoption curves. Forecast inputs include copper price trajectories, laboratory certification throughput capacity, and housing program deployment schedules.
Caveats apply where SASO enforcement intensity, LME commodity spikes, or shipping route disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation timelines and construction activity levels. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Biohybrid Solar Cell Market