
 Solar Water Pump Market | 2026-2036
Solar Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Water Pump Market Intelligence
Chinese photovoltaic module production is shifting toward dedicated agricultural supply chains, altering component economics for pump assemblers worldwide. LORENTZ GmbH leverages its German engineering base to dominate high-efficiency submersible systems for off-grid irrigation. Tata Power Solar Systems Limited anchors India's institutional procurement channel through state-level nodal agency partnerships. Shakti Pumps (India) Limited competes on cast-component backward integration, controlling foundry-to-assembly cost structures.
A solar water pump converts photovoltaic DC output into mechanical energy for fluid movement, typically achieving 30-50 meters of total dynamic head in submersible configurations for borewell extraction. Submersible pumps command the largest installed base due to deep aquifer access requirements across South Asian and Sub-Saharan agricultural belts. Surface pumps retain margin advantages in shallow riverine and canal-fed irrigation schemes where lift demands stay below 10 meters. The 3 to 5 HP power capacity tier captures accelerating replacement cycles as smallholder cooperatives consolidate land parcels and centralize water distribution.
India's Ministry of New and Renewable Energy administers PM-KUSUM Component B, mandating standalone solar pumps for off-grid farmers while BIS certification governs motor efficiency and safety interoperability. The EPA regulates groundwater withdrawal rates in US agricultural zones, indirectly constraining pump sizing and duty cycle specifications in drought-prone counties. REACH compliance within the EU restricts certain elastomer and cable sheath chemistries, elevating material substitution costs for European market entrants. Stakeholders must monitor how subsidy disbursement velocity and component localization rules reshape competitive cost positions in the next procurement cycle.
Market Dynamics
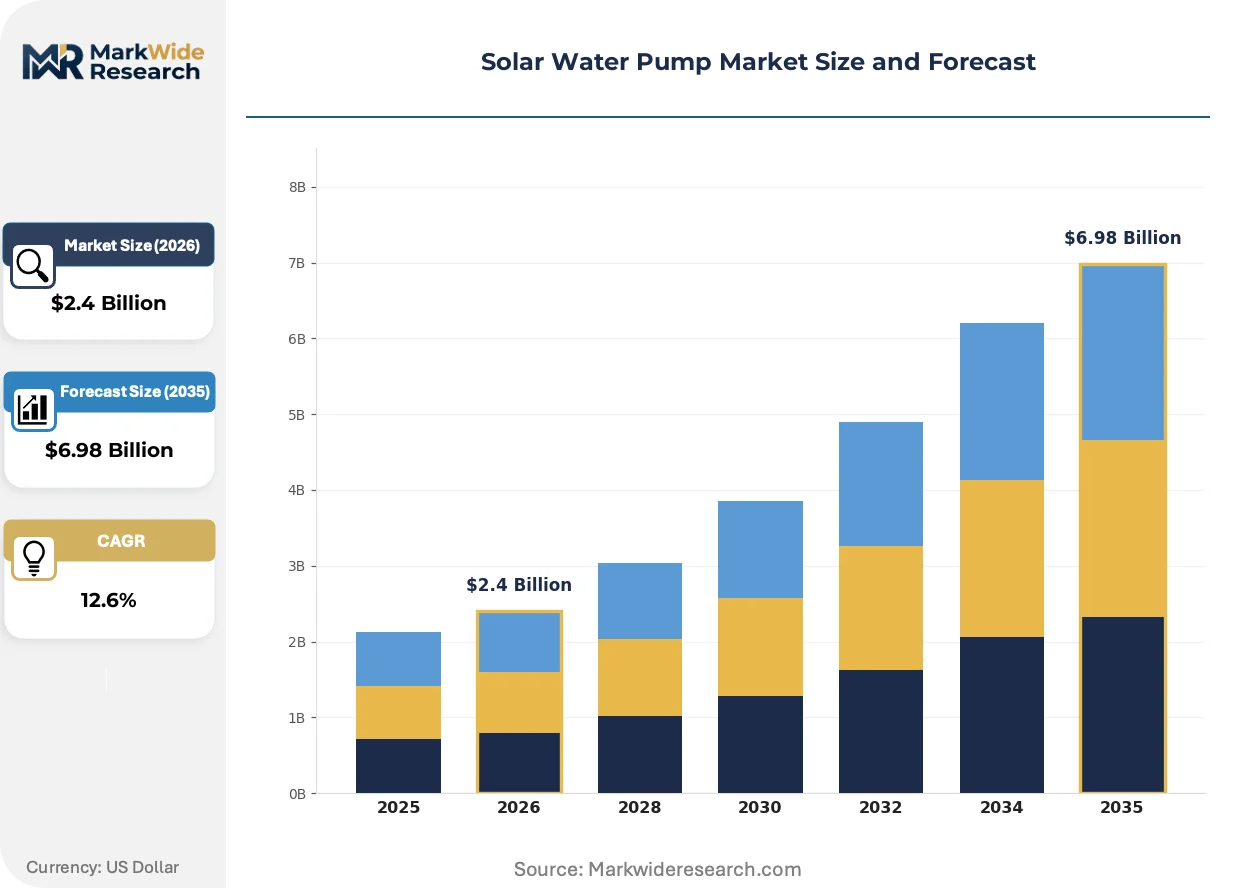
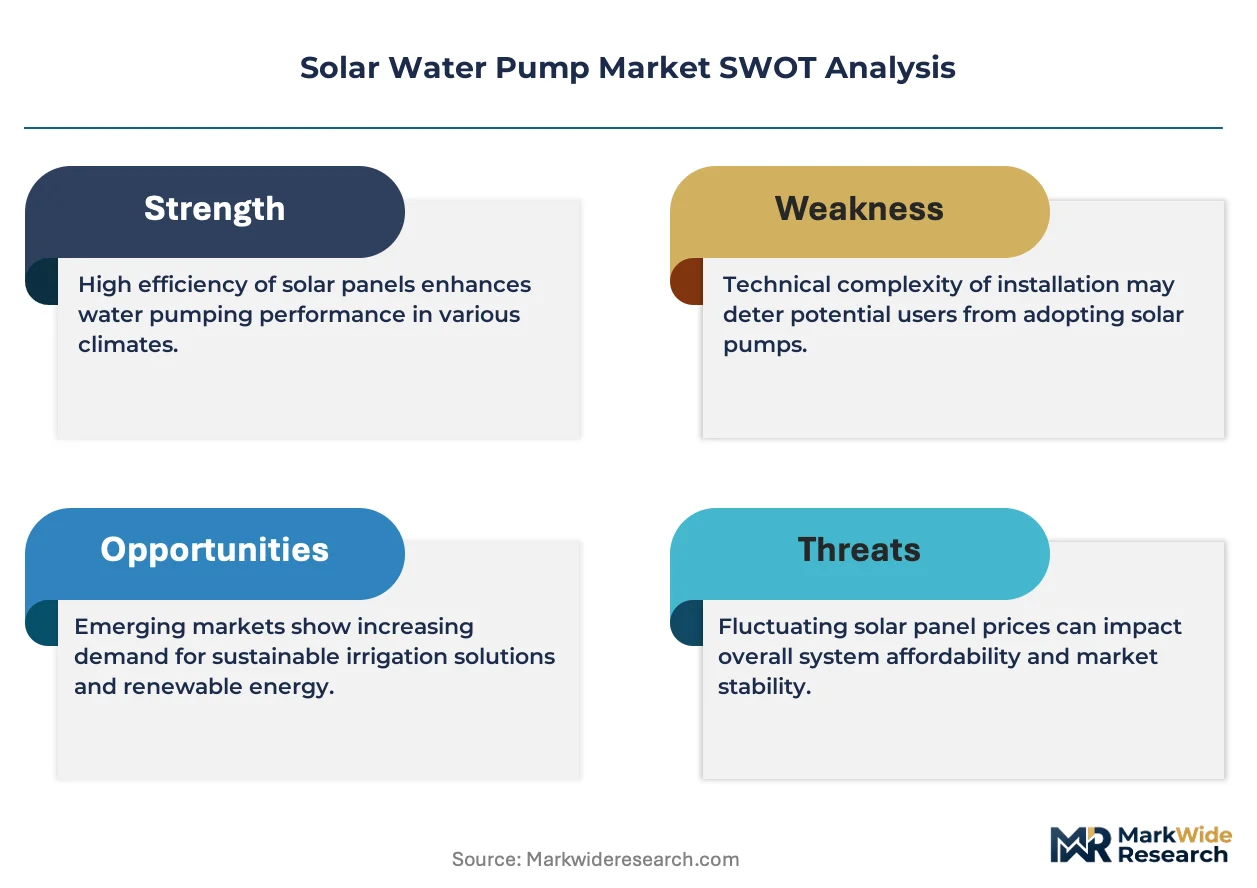
Subsidy disbursement velocity in India is compressing procurement cycles for agricultural cooperatives while photovoltaic module oversupply from Chinese manufacturers is collapsing component costs for pump assemblers.
Growth Catalysts
- PM-KUSUM Component B:India's Ministry of New and Renewable Energy mandates standalone solar pumps for off-grid farmers, accelerating rural electrification alternatives across Rajasthan and Gujarat.
- Photovoltaic module cost deflation:Chinese production shifting toward dedicated agricultural supply chains alters component economics for pump assemblers worldwide.
- Agricultural cooperative consolidation:Smallholder cooperatives in arid zones represent the fastest-expanding buyer segment as land parcels centralize water distribution.
Market Restraints
- Groundwater withdrawal constraints:EPA regulations in US agricultural zones indirectly constrain pump sizing and duty cycle specifications in drought-prone counties.
- Material substitution costs:REACH compliance within the EU restricts certain elastomer and cable sheath chemistries, elevating costs for European market entrants.
- Deep aquifer technical limitations:Submersible configurations face total dynamic head constraints beyond 50 meters in South Asian borewell extraction.
Strategic Opportunities
- Sub-Saharan agricultural belts:Underpenetrated shallow riverine irrigation schemes offer margin advantages for surface pump configurations below 10-meter lift demands.
- State-level nodal agency partnerships:Institutional procurement channels in India enable volume concentration through centralized tendering mechanisms.
- 3 to 5 HP replacement cycles:Power capacity tier acceleration creates white space as existing diesel pumps reach end-of-life in consolidated farming operations.
Industry Challenges
- BIS certification timelines:Motor efficiency and safety interoperability testing creates procurement delays for component localization rules.
- Foundry-to-assembly integration:Cast-component backward integration requires capital intensity for controlling cost structures through captive supply.
- Legacy grid-tied infrastructure:Off-grid solar pump deployment faces integration friction with existing electrical distribution in partially electrified rural zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Water Pump Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Pumps, Submersible Pumps, Floating Pumps, Booster Pumps Power Capacity: Up to 1 HP, 1 to 3 HP, 3 to 5 HP, Above 5 HP Application: Irrigation, Livestock Watering, Residential Usage, Commercial Agriculture End User: Farmers, Agricultural Cooperatives, Water Utilities, Plantations |
| Companies Covered | LORENTZ GmbH, Tata Power Solar Systems Limited, Shakti Pumps (India) Limited, KSB SE, Saatvik Green Energy, Grundfos Holding A/S, Kirloskar Brothers Ltd., HYBSUN, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Water Pump Market Strategic Shifts & Innovations
Photovoltaic-to-pump system integration is reshaping how fluid movement equipment is specified, financed, and maintained across agricultural value chains.
Brushless DC motor technology is unifying power conversion efficiency with variable speed control in submersible configurations. Agricultural cooperatives in Gujarat are adopting these systems at accelerating pace as subsidy frameworks mature. This convergence is unifying pump and inverter supply chains, compressing vendor margins through bundled procurement.
India's BIS certification regime is tightening motor efficiency standards for solar pump interoperability. The industrial consequence is accelerated R&D spending on permanent magnet synchronous motor designs. Surface pump manufacturers serving canal-fed schemes face compressed compliance timelines compared to submersible specialists.
Cooperative bulk purchasing is displacing individual farmer procurement across Rajasthan's groundwater-depleted districts. State nodal agencies are consolidating tender volumes, disintermediating traditional distributor networks. This concentration is most visible in 3 to 5 HP system categories where replacement demand clusters.
Solar Water Pump Market Segmentation
Solar water pump procurement patterns diverge sharply across product architecture and power rating tiers. Understanding these fault lines reveals where subsidy capture concentrates and which configurations face replacement pressure from electrification policy.
Product Type:
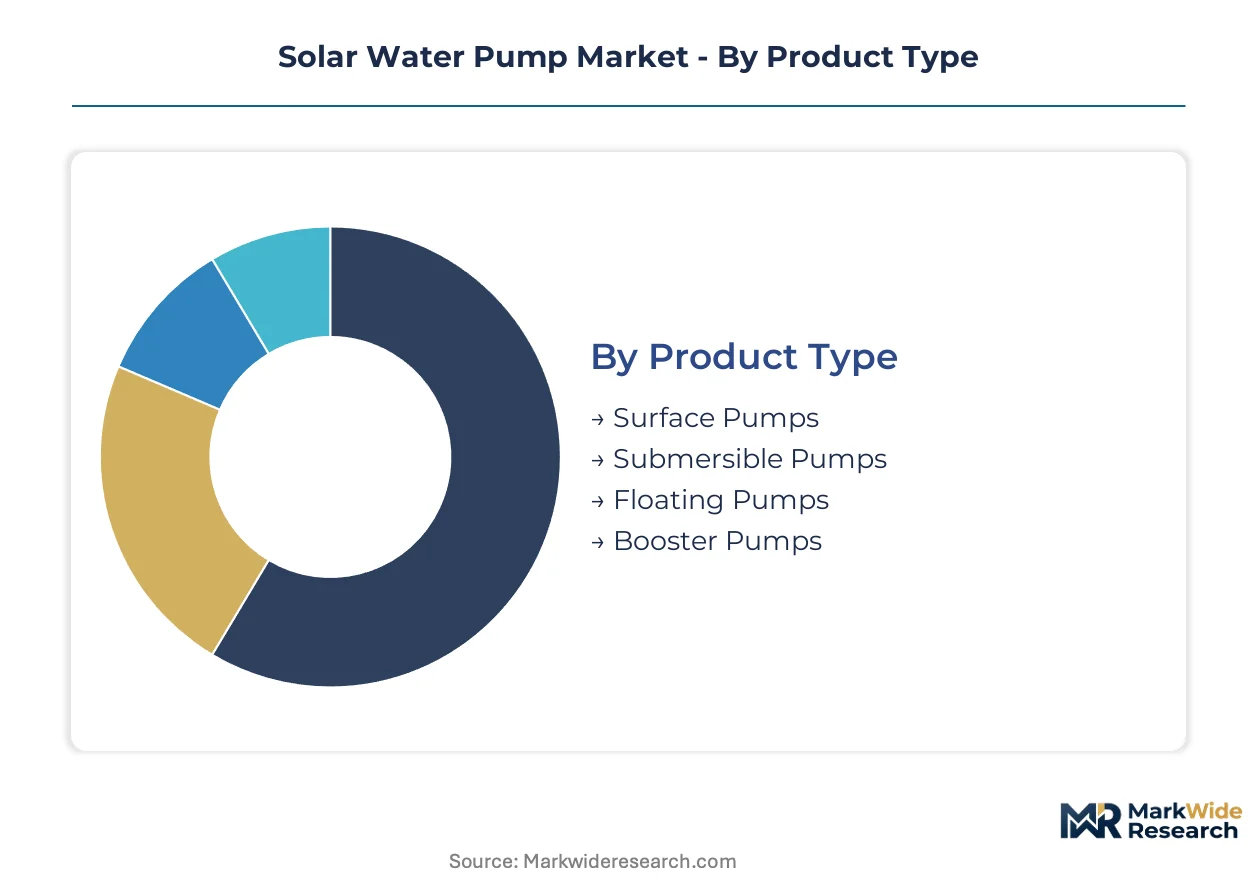
Volume concentrates in deep-well extraction systems while margin pools in specialized surface configurations for canal-fed schemes.
- Submersible Pumps:Designed for borewell deployment with total dynamic head ratings of 30-50 meters, these systems dominate South Asian and Sub-Saharan agricultural belts where aquifer depths exceed surface pump limits. Demand clusters in Rajasthan and Gujarat as groundwater depletion forces deeper drilling and PM-KUSUM Component B accelerates diesel replacement cycles.
- Surface Pumps:Optimized for shallow riverine and canal-fed irrigation below 10-meter lift requirements, these units retain cost advantages in gravity-fed distribution networks. Margin structures compress faster than submersible categories due to simpler motor specifications and lower BIS certification barriers for entry.
- Floating Pumps:Reservoir-mounted configurations for large-scale water bodies serving plantation estates and utility-scale storage. Penetration remains limited to coastal Kerala and Tamil Nadu where monsoon catchment infrastructure supports floating deployment.
- Booster Pumps:Pressure-augmentation units for centralized distribution systems in consolidated cooperative operations. Adoption tracks land parcel consolidation velocity in Maharashtra and Karnataka.
Today's leader: Submersible Pumps. Tomorrow's challenger: Surface Pumps.
Power Capacity:
Cooperative procurement is shifting the demand center toward mid-range horsepower tiers as individual farmer purchases fragment.
- 3 to 5 HP:The replacement sweet spot for diesel pump conversions in consolidated farming operations, this tier captures accelerating cooperative tender volumes under state nodal agency frameworks. Rajasthan's groundwater-depleted districts show the steepest procurement velocity as smallholders pool resources for centralized distribution.
- 1 to 3 HP:Individual farmer segments in partially electrified zones favor these units for marginal land holdings below five acres. Subsidy disbursement friction and BIS certification delays create longer procurement cycles compared to higher-horsepower categories.
- Up to 1 HP:Residential and kitchen garden applications in peri-urban Gujarat. Penetration depends on rooftop solar adoption rates rather than agricultural policy.
- Above 5 HP:Plantation estates and water utilities operating centralized lift irrigation schemes. Capital intensity restricts adoption to institutional borrowers with balance sheet capacity for large-scale photovoltaic arrays.
Volume dominance: 3 to 5 HP. Fastest expansion: Above 5 HP in utility tenders.
Application:
Irrigation commands installed base while livestock watering offers untapped shallow-well penetration.
- Irrigation:The core demand driver spanning kharif and rabi season water delivery, with surface and submersible configurations selected based on aquifer depth and canal proximity. PM-KUSUM Component B targets this segment exclusively for standalone pump deployment.
- Livestock Watering:Remote pasture and dairy cluster applications favor portable surface pumps below 3 HP. Underpenetration in arid zone pastoral belts creates white space as animal husbandry cooperatives formalize.
- Residential Usage:Rural homestead drinking water and small-plot vegetable cultivation. Demand fragmentation limits vendor interest despite subsidy eligibility.
- Commercial Agriculture:Floriculture, horticulture, and export-oriented crop operations requiring precise pressure control and backup pumping capacity. Premium pricing tolerance supports brushless DC motor adoption.
Policy focus: Irrigation. Margin expansion: Commercial Agriculture.
End User:
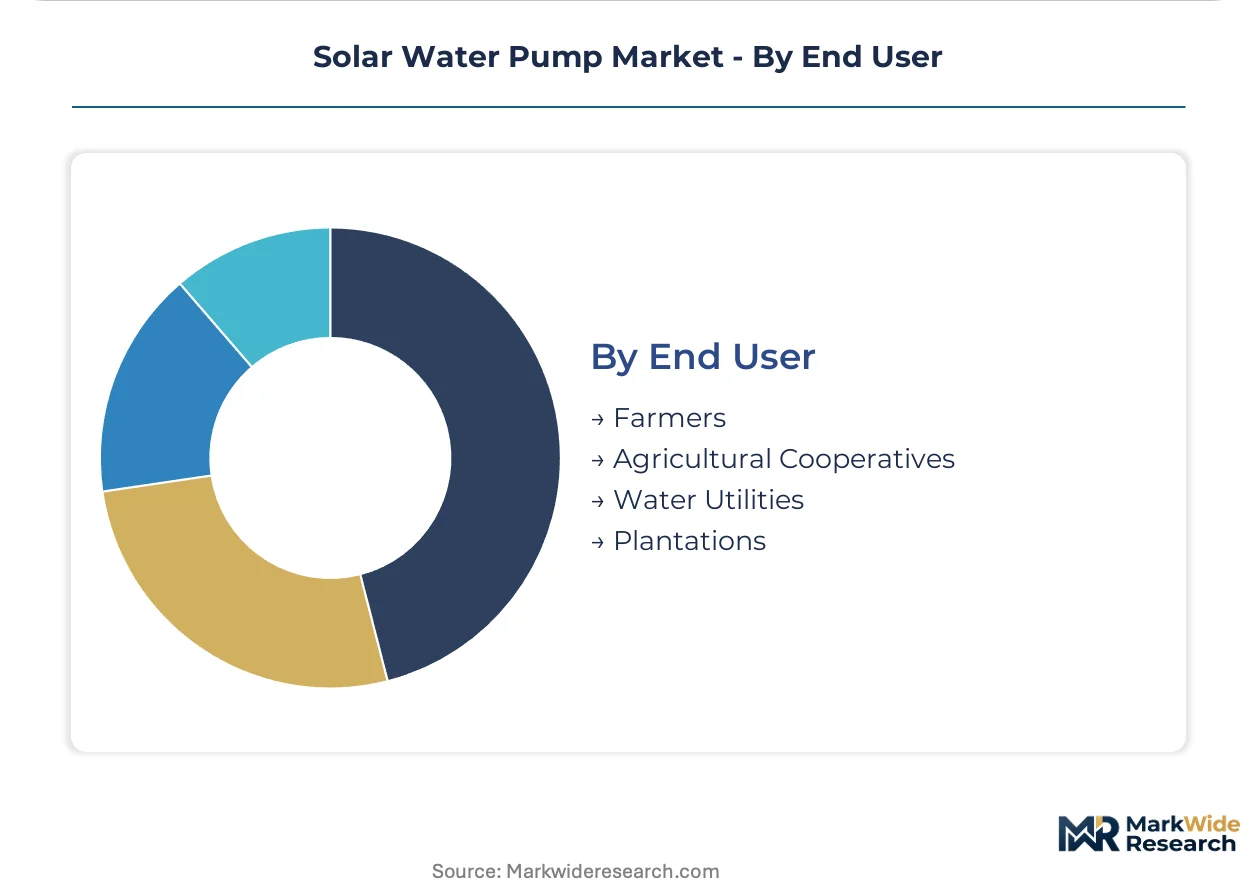
Procurement authority is migrating from individual farmers to consolidated entities with tender execution capacity.
- Agricultural Cooperatives:Fastest-expanding buyer segment as land parcel consolidation centralizes water distribution decisions. State nodal agency partnerships in Rajasthan and Gujarat disintermediate traditional distributor networks through volume tendering.
- Farmers:Individual procurement persists in fragmented landholding zones below subsidy aggregation thresholds. Transaction costs and BIS compliance delays disadvantage this segment against cooperative alternatives.
- Water Utilities:Rural drinking water schemes and lift irrigation projects above 5 HP. Budget cycle alignment with state renewable energy targets determines procurement timing.
- Plantations:Tea, coffee, and sugarcane estates with captive solar arrays and maintenance infrastructure. Long replacement cycles and direct vendor relationships bypass nodal agency channels.
Current procurement volume leader: Agricultural Cooperatives. Structural growth vector: Water Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as Chinese photovoltaic producers exploit REACH compliance gaps to undercut European pump assemblers on component costs. Module oversupply from dedicated agricultural supply chains is collapsing landed costs for pump integrators in import-dependent markets. Subsidy disbursement velocity in India now outpaces bureaucratic procurement cycles in the EU and US, tilting deployment momentum toward South Asian agricultural belts.
India
Rajasthan and Gujarat concentrate demand as groundwater depletion intersects with high solar irradiance and PM-KUSUM Component B subsidy acceleration. The Ministry of New and Renewable Energy mandates standalone solar pumps for off-grid farmers through state nodal agency partnerships. Shakti Pumps and Tata Power Solar anchor procurement channels via foundry-to-assembly integration and institutional tender execution.
China
Photovoltaic module production is shifting toward dedicated agricultural supply chains, altering component economics for pump assemblers worldwide. MIIT industrial policy supports dual carbon goals through solar manufacturing scale expansion. Zhejiang and Jiangsu provinces host the dominant concentration of DC motor and controller fabrication for export-oriented pump integrators.
Germany
REACH compliance restricts certain elastomer and cable sheath chemistries, elevating material substitution costs for European market entrants. LORENTZ GmbH leverages its German engineering base to dominate high-efficiency submersible systems for off-grid irrigation. Bavaria and Baden-Württemberg retain precision manufacturing clusters for permanent magnet synchronous motor R&D.
United States
EPA regulations on groundwater withdrawal rates indirectly constrain pump sizing and duty cycle specifications in drought-prone counties across California and Texas. The Inflation Reduction Act extends tax credit eligibility to agricultural solar installations, though implementation lags Indian subsidy velocity. Central Valley farming cooperatives show emerging interest in 3 to 5 HP replacement cycles.
Brazil
Underpenetrated shallow riverine irrigation schemes in the Cerrado and Pantanal regions offer margin advantages for surface pump configurations below 10-meter lift demands. ANVISA and national agricultural credit programs (PRONAF) are piloting solar pump financing for smallholder cooperatives. São Paulo and Minas Gerais states concentrate early adoption through sugarcane plantation estate procurement.
Solar Water Pump Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular component supply and regional assembly partnerships. The vendor base stratifies across three tiers: German-engineered premium specialists, Indian integrated manufacturers with backward foundry control, and Chinese module-scale assemblers competing on photovoltaic-to-pump bundling. Dominant competitive moves include state nodal agency partnership capture for institutional tender access and captive photovoltaic array development to compress system-level pricing.
Within the premium-engineering tier, LORENTZ GmbH exemplifies German precision positioning for high-efficiency submersible configurations. Tata Power Solar Systems Limited and Shakti Pumps (India) Limited occupy the integrated-manufacturing archetype, with the former anchoring institutional procurement channels and the latter representing cast-component backward integration. Among diversified industrial conglomerates, KSB SE and Grundfos Holding A/S sit within pump-specialist divisions of broader fluid technology portfolios.
| Leading Market Players |
|---|
| LORENTZ GmbH |
| Tata Power Solar Systems Limited |
| Shakti Pumps (India) Limited |
| KSB SE |
| Saatvik Green Energy |
| Grundfos Holding A/S |
| Kirloskar Brothers Ltd. |
| HYBSUN |
| Xylem Inc. |
| Others |
Cost & Logistics Intelligence
Brushless DC motor unification with variable speed controllers is collapsing power conversion costs while compressing vendor margins through bundled photovoltaic-to-pump procurement. This technological convergence simultaneously reshapes cost economics for pump assemblers and concentrates supply leverage among Chinese module-scale producers serving agricultural supply chains.
Pricing Analysis
Distributor margins in traditional pump networks face compression as state nodal agency tendering disintermediates conventional channels. Three-tier pricing structure across premium German-engineered submersibles, Indian integrated-manufacturing standards, and Chinese module-bundled economy units dominates procurement. Pricing pressure stems from photovoltaic module oversupply collapsing component landed costs. Agricultural cooperatives exhibit highest price sensitivity through volume aggregation, while plantation estates show lowest sensitivity due to captive maintenance infrastructure requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese photovoltaic module production for DC motor and controller fabrication. Manufacturing gravity centers on Zhejiang and Jiangsu provinces, with secondary concentration in German precision motor R&D clusters and Indian foundry-to-assembly operations. Raw material dependencies include permanent magnet rare earth elements, silicon wafers, and REACH-compliant elastomer sheathing. Tariff exposure on Chinese photovoltaic imports creates structural risk for pump integrators in import-dependent markets. Distribution runs through state nodal agency tendering in India, traditional agricultural equipment distributors in Brazil, and direct vendor relationships for plantation estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Indian subsidy velocity and European regulatory compliance costs, with PM-KUSUM disbursement timelines outpacing REACH certification timelines by substantial margins.
For Market Incumbents: Hedge against Chinese module-scale assemblers by deepening backward integration into permanent magnet synchronous motor production and securing BIS certification pre-approval for interoperability standards. Channel control through state nodal agency partnership capture remains the priority defensive lever against distributor disintermediation.
For New Entrants and Emerging Players: Begin with underpenetrated shallow riverine irrigation schemes in Brazil's Cerrado and Sub-Saharan agricultural belts where surface pump configurations below 10-meter lift demands retain margin advantages. Target livestock watering cooperatives in arid pastoral belts through portable sub-3 HP unit specialization as the most penetrable white-space segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among Indian integrated manufacturers with captive foundry operations and established state nodal agency relationships. Long-term viability across the analysis window hinges on subsidy regime durability and groundwater withdrawal regulatory tightening. Watch PM-KUSUM Component B disbursement velocity as the critical inflection signal for deployment momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motor Production | Captive supply of brushless DC motors compresses cost structures against Chinese module bundlers. |
| State Nodal Agency Partnership Capture | Institutional tender access in Rajasthan and Gujarat disintermediates traditional distributor networks. |
| BIS Certification Pre-Approval Investment | Accelerated motor efficiency compliance timelines secure procurement eligibility before competitors. |
| Surface Pump Configuration Specialization | Margin advantages in shallow riverine schemes below 10-meter lift demands avoid submersible competition. |
| Photovoltaic Array Captive Development | System-level pricing compression through in-house module sourcing challenges bundled competitors. |
Research Approach
Coverage spans India, China, Germany, the United States, and Brazil, with primary inputs from each market. Primary interviews with solar pump procurement officers at agricultural cooperatives, state nodal agency tender administrators, photovoltaic module procurement leads, and irrigation scheme engineers combined with secondary validation from MNRE subsidy disbursement records, BIS certification databases, EPA groundwater withdrawal filings, and REACH compliance registries. Bottom-up deployment tracking across horsepower tiers and product configurations triangulated against top-down subsidy allocation analysis.
Granularity-level modeling segmented by product architecture, power capacity tier, application type, and end-user procurement authority across the projection horizon. Submersible versus surface pump configurations, 1-3 HP versus 3-5 HP versus above-5 HP tiers, and cooperative versus individual farmer procurement channels each carried discrete growth assumptions. CAGRs derived from subsidy velocity correlation with diesel replacement cycle timing and photovoltaic module cost deflation trajectories. Groundwater depletion rates and solar irradiance mapping provided industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential PM-KUSUM framework modifications, groundwater withdrawal regulatory tightening beyond current EPA constraints, and photovoltaic trade policy shifts affecting module landed costs. Forecasts reflect documented assumptions regarding subsidy disbursement continuity and cooperative formation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Europe Water Pump Market