
 Bacteria Powered Solar Cell Market | 2026-2036
Bacteria Powered Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Bacteria Powered Solar Cell Market Outlook
The gap between laboratory-grade biohybrid systems and commodity microbial fuel cells is rebalancing as manufacturing scale determines cost viability. LanzaTech leverages its gas fermentation infrastructure to anchor upstream bioprocessing capabilities for bacterial photovoltaic substrates. Algenol Biotech sustains a dominant position in cyanobacterial strain development, while Novozymes differentiates through enzyme optimization for electron transfer efficiency in organic photonic devices.
Bacteria powered solar cells harness electrogenic microorganisms such as Shewanella or Geobacter species to transfer electrons across anode surfaces, generating current densities typically ranging from 0.1 to 10 watts per square meter depending on strain engineering and electrode nanostructuring. The primary commercial purpose centers on decentralized power generation for remote sensing and low-energy environmental applications. Photovoltaic cells capture the largest share of current product revenue, though microbial fuel cells represent the fastest-growing segment due to wastewater treatment co-benefits. Bio-Solar Technology leads the technology dimension in patent filings, while nanostructured materials concentrate margin pools through specialized electrode coatings.
The EPA regulates genetically modified bacterial strains under TSCA and FIFRA frameworks, constraining field deployment timelines for engineered electrogenic organisms. The EU Green Deal and REACH compliance requirements shape material selection for dye-sensitized cell components across European research consortia. Stakeholders must monitor how the IRA's bioenergy tax provisions and the EU AI Act's research data governance rules will reshape capital allocation between pilot-scale demonstration and commercial manufacturing commitments.
Market Dynamics
The central structural force reshaping bacteria powered solar cells is the convergence of electrogenic strain engineering with nanostructured electrode manufacturing, compressing the cost gap between laboratory prototypes and field-deployable units.
Growth Catalysts
- EU Green Deal funding mechanisms:Direct capital allocation into electrogenic bacteria research clusters accelerates pilot-to-production scaling for biohybrid photovoltaic systems.
- Denmark's integrated biorefinery infrastructure:Co-location of microbial fuel cell development with agricultural waste processing creates captive feedstock supply and reduces substrate logistics costs.
- Off-grid environmental monitoring demand:Remote sensing applications in marine and forest ecosystems pull decentralized power generation toward commercial viability thresholds.
Market Restraints
- Electrode material cost volatility:Specialized nanostructured coatings and rare-earth catalysts concentrate input cost exposure in supply chains dominated by East Asian refiners.
- EPA TSCA field deployment timelines:Genetically modified Shewanella and Geobacter strains face extended review cycles that delay commercial outdoor installations.
- Solid-state photovoltaic substitution:Conventional silicon and perovskite cells continue compressing unit economics for low-power remote applications.
Strategic Opportunities
- IRA bioenergy tax provisions:Section 45Q credits for carbon capture integration create stacking incentives for bacterial systems co-located with fermentation facilities.
- Wastewater treatment co-benefit monetization:Municipal utilities in water-stressed regions can capture dual revenue streams from energy generation and effluent remediation.
- AI-driven strain optimization:Machine learning convergence with synthetic biology compresses electrogenic pathway engineering cycles from months to weeks.
Industry Challenges
- Electrochemist-microbiologist interdisciplinary talent scarcity:Cross-functional teams capable of integrating electrode nanostructuring with bacterial metabolism engineering command premium compensation and extended recruitment cycles.
- ISO 10993 biocompatibility certification complexity:Field-deployable systems require extended validation protocols for environmental release that strain startup capitalization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacteria Powered Solar Cell Market |
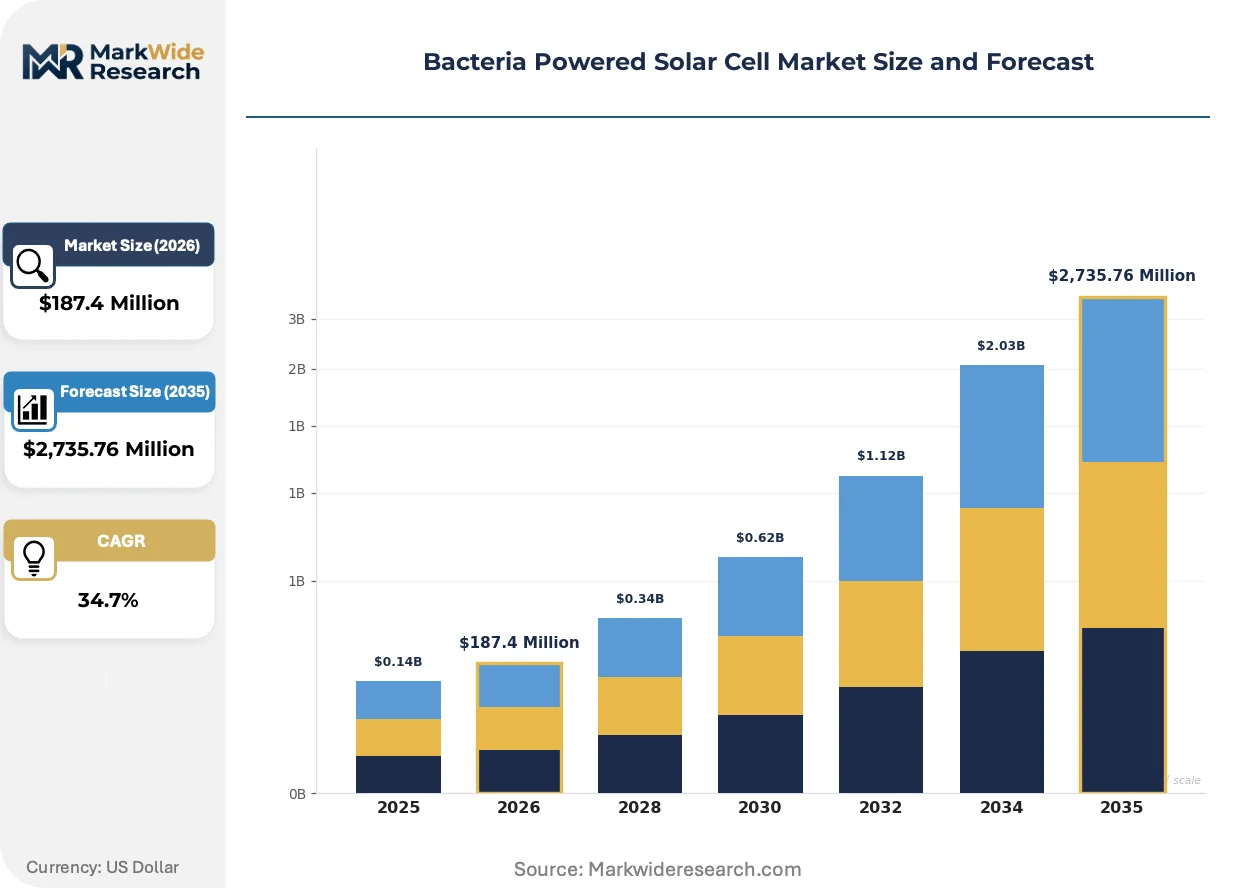
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Cells, Biohybrid Systems, Organic Photonic Devices, Microbial Fuel Cells Technology: Bio-Solar Technology, Electrogenic Bacteria, Nanostructured Materials, Dye-Sensitized Cells End User: Residential, Commercial, Agricultural, Research Institutions Application: Off-Grid Power Supply, Environmental Monitoring, Wastewater Treatment, Renewable Energy Generation |
| Companies Covered | LanzaTech, Algenol Biotech, Global Algae Innovations, Cyanotech Corporation, Synthetic Genomics, Novozymes, Genomatica, Angel Yeast Co., Ltd, Lallemand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacteria Powered Solar Cell Market Strategic Shifts
Active research frontiers in bacterial photovoltaics center on automation of strain-electrode interface engineering, regulatory frameworks for environmental GMO release, and procurement restructuring around wastewater-utility partnerships.
Automated microfluidic screening platforms are accelerating the identification of high electron-transfer-efficiency Shewanella mutants. Research consortia in Germany and the Netherlands deploy these systems to compress strain optimization cycles. The technology is automating the translation from laboratory phenotypes to manufacturing-ready inoculum production, reducing pilot-scale validation timelines.
REACH compliance requirements for dye-sensitized cell components are reshaping material selection across European research programs. ECHA substance restrictions on volatile organic solvents force electrode fabrication toward aqueous-processable alternatives. Danish and Dutch pilot installations are responding by qualifying bio-based conductive polymers that bypass hazardous substance authorizations.
Utility procurement departments are consolidating vendor qualification around integrated service contracts that bundle microbial fuel cell hardware with long-term substrate supply and maintenance obligations. Danish water authorities pioneered this model. The shift is most visible in Scandinavia, where municipal ownership of waste streams enables captive biogas-to-electron conversion economics.
Bacteria Powered Solar Cell Market Segmentation
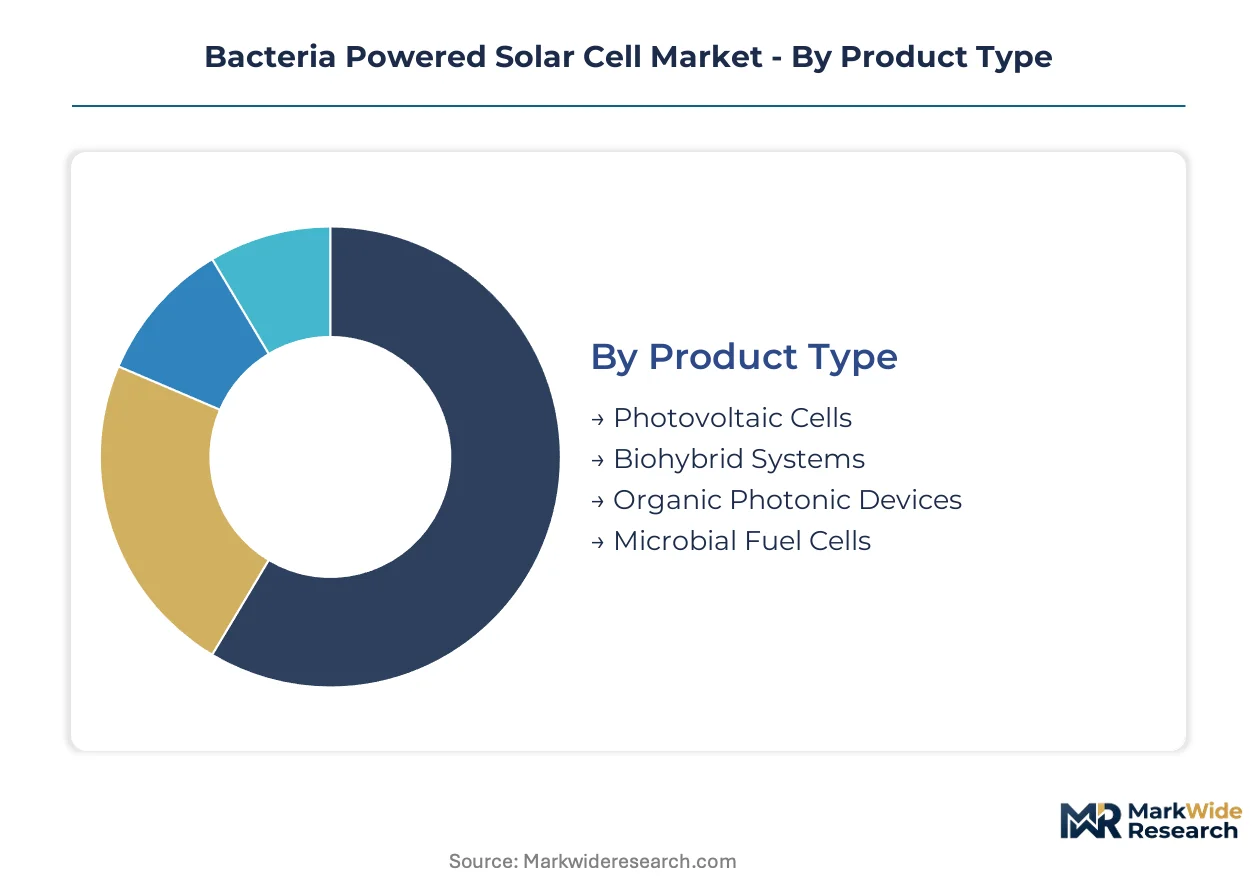
Segmentation in bacteria powered solar cells reveals how technical specifications map to deployable use cases. Strain engineering maturity and electrode manufacturing readiness determine which configurations achieve commercial viability versus laboratory demonstration status.
Product Type:
Electrode surface area and bacterial colonization density define the power density achievable across form factors.
- Photovoltaic Cells:Standardized planar configurations using Shewanella or cyanobacterial films on conductive glass substrates. Danish agricultural clusters deploy these for barn-level microgrids where grid connection costs exceed bacterial system capital expenditure.
- Biohybrid Systems:Integrated architectures combining living electrogenic cultures with inorganic semiconductors. German research consortia scale these for marine sensor networks requiring continuous power without battery replacement logistics.
- Organic Photonic Devices:Flexible polymer substrates with embedded bacterial electron transfer layers. Lightweight form factors suit wearable environmental monitors in Netherlands field biology programs.
- Microbial Fuel Cells:Chambered designs separating anode biofilms from cathode reactions via proton exchange membranes. Wastewater treatment facilities in Denmark monetize dual revenue streams from effluent remediation and electricity generation.
Photovoltaic Cells leads on scale; Microbial Fuel Cells leads on momentum.
Technology:
Cost tiers separate laboratory-grade innovations from field-deployable manufacturing standards.
- Bio-Solar Technology:Cyanobacterial photosynthetic electron harvesting coupled to external circuits. Algenol Biotech dominates strain IP, constraining licensing costs for second-tier developers.
- Electrogenic Bacteria:Engineered Shewanella and Geobacter species with enhanced extracellular electron transfer pathways. EPA TSCA review timelines delay outdoor deployment of genetically modified variants.
- Nanostructured Materials:Specialized electrode coatings—carbon nanotubes, graphene oxides, gold nanoparticles—that amplify current density. East Asian refiners concentrate supply of rare-earth catalyst precursors, injecting price volatility.
- Dye-Sensitized Cells:Synthetic chromophores replacing biological light-harvesting complexes. REACH solvent restrictions force European manufacturers toward aqueous fabrication processes.
Electrogenic Bacteria commands premium R&D allocation; Nanostructured Materials captures margin concentration.
End User:
Volume requirements and technical sophistication stratify customer procurement patterns.
- Residential:Distributed rooftop or garden installations with sub-watt power demands. German building code exemptions for experimental renewable systems accelerate pilot adoption.
- Commercial:Corporate sustainability mandates drive pilot installations in Netherlands office parks. Procurement departments prioritize integrated service contracts bundling hardware with substrate supply.
- Agricultural:Livestock operations and greenhouse complexes with organic waste streams. Danish biorefinery clusters co-locate microbial fuel cells with manure processing infrastructure.
- Research Institutions:Universities and national laboratories validating strain-electrode interfaces. German and Dutch consortia dominate peer-reviewed publication output and patent filings.
Agricultural end users anchor installed base expansion; Research Institutions concentrate IP generation.
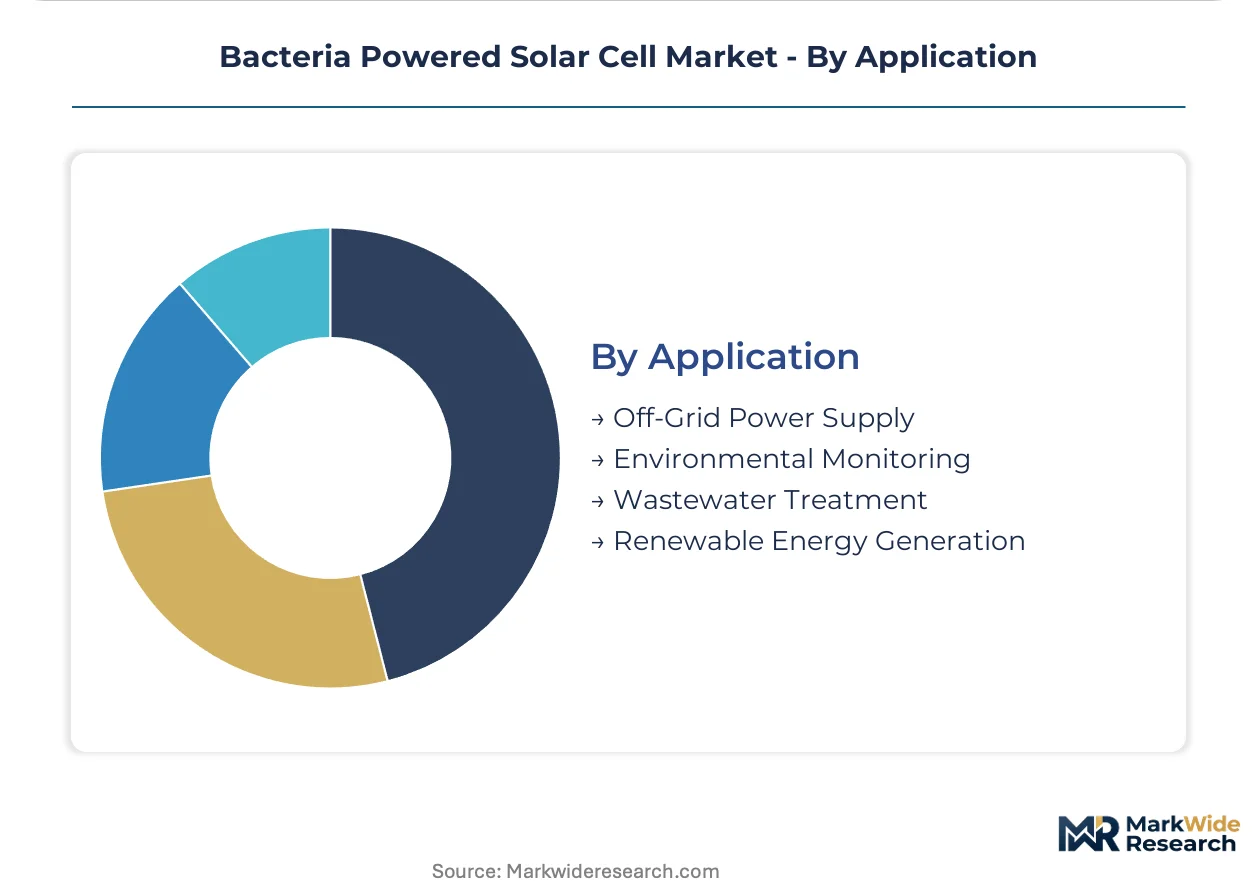
Application:
Customer type determines performance specifications and regulatory exposure for field deployment.
- Off-Grid Power Supply:Remote installations replacing diesel generators or battery swaps. Marine and forest ecosystem monitoring in Germany and Netherlands pulls demand toward commercial viability thresholds.
- Environmental Monitoring:Continuous sensor power for air quality, water chemistry, or wildlife tracking. Biohybrid systems minimize maintenance intervals in inaccessible terrain.
- Wastewater Treatment:Municipal and industrial effluent processing with energy recovery. Danish water authorities pioneered vendor qualification around long-term substrate supply contracts.
- Renewable Energy Generation:Grid-connected or microgrid installations competing with conventional solar. Solid-state photovoltaic cost compression constrains bacterial system economics.
Wastewater Treatment secures policy support through co-benefit monetization; Off-Grid Power Supply climbs fastest toward unsubsidized competitiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemist-microbiologist talent clusters in Denmark, Germany, and the Netherlands anchor pilot-scale deployment of biohybrid systems, while US and Japanese research consortia advance strain engineering capabilities.
Denmark
Integrated biorefinery infrastructure co-locates microbial fuel cell development with agricultural waste processing. The Danish Energy Agency funds electrogenic bacteria research through national renewable energy directives. Copenhagen and Aarhus host captive feedstock supply chains that reduce substrate logistics costs for bacterial photovoltaic substrates.
Germany
Research institutions scale pilot installations for off-grid environmental monitoring in marine ecosystems. ECHA REACH compliance requirements shape material selection for dye-sensitized cell components across German research consortia. Bavaria and North Rhine-Westphalia concentrate automated microfluidic screening platforms that accelerate Shewanella mutant identification.
Netherlands
Field biology programs pull demand for lightweight organic photonic devices in wearable environmental monitors. The EU Green Deal accelerates funding for electrogenic bacteria research through Dutch national implementation frameworks. Wageningen and Eindhoven anchor consortia validating strain-electrode interfaces for biohybrid marine sensor networks.
United States
Corporate sustainability mandates drive pilot installations leveraging IRA bioenergy tax provisions. EPA TSCA and FIFRA frameworks regulate genetically modified bacterial strains, constraining field deployment timelines for engineered electrogenic organisms. Greater Boston and the San Francisco Bay Area concentrate synthetic biology startups targeting electrogenic pathway engineering.
Japan
METI-funded research programs advance cyanobacterial strain development for photosynthetic electron harvesting. JIS standards shape electrode fabrication protocols for biohybrid system manufacturing. The Kanto region around Tokyo hosts national laboratories integrating machine learning with synthetic biology for strain optimization cycles.
Bacteria Powered Solar Cell Market Competitive Environment
Top-tier vendors anchor gas fermentation and enzyme optimization infrastructure, while mid-tier specialists concentrate on strain IP and automated screening platforms. The vendor base stratifies across integrated bioprocessors, cyanobacterial developers, and enzyme engineering houses. Three archetypes dominate: upstream substrate controllers, biological IP licensors, and electrode nanostructuring specialists. Competitive moves center on strategic partnerships for pilot-scale validation and technology licensing for manufacturing-ready inoculum production.
Within the integrated bioprocessing tier, LanzaTech leverages gas fermentation infrastructure to anchor upstream capabilities for bacterial photovoltaic substrates. Algenol Biotech exemplifies the cyanobacterial strain development archetype, constraining licensing costs for second-tier developers through dominant IP positions. Novozymes occupies the enzyme optimization vector, differentiating through electron transfer efficiency improvements in organic photonic devices.
| Leading Market Players |
|---|
| LanzaTech |
| Algenol Biotech |
| Global Algae Innovations |
| Cyanotech Corporation |
| Synthetic Genomics |
| Novozymes |
| Genomatica |
| Angel Yeast Co., Ltd |
| Lallemand |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal compliance requirements gate qualified supply for bacterial photovoltaic substrates and restrict premium-tier pricing access to vendors with REACH-certified electrode materials and validated environmental release protocols. Danish and Dutch procurement departments filter vendor pools through integrated service contract structures that bundle hardware with captive substrate supply, compressing margins for unbundled equipment-only suppliers.
Pricing Analysis
Bundled long-term service contracts versus unbundled equipment-only sales define the pricing split in bacterial solar cell procurement. Danish water authorities pioneered integrated contracts combining microbial fuel cell hardware with multi-year substrate supply and maintenance obligations, commanding 40-60% premiums over transactional equipment sales. Price differentiation rests on ISO 10993 biocompatibility certification tier and volume scale of inoculum production. Cost compression in laboratory-grade systems is intensifying because solid-state photovoltaic substitution erodes the economic case for low-power remote applications. Agricultural end users in Denmark exhibit highest price sensitivity due to thin operating margins in livestock operations, while German research institutions show lowest sensitivity given dedicated grant funding streams.
Supply Chain Analysis
Specialized nanostructured electrode coatings rest on East Asian refiners in China, Japan, and South Korea for carbon nanotube precursors and rare-earth catalysts. Bacterial inoculum production draws from captive fermentation facilities in Denmark and the Netherlands, while conductive glass substrates feed from German and Japanese specialty glass manufacturers. Single-source vulnerability concentrates in graphene oxide supply chains dominated by Chinese producers, exposing European system integrators to tariff and export restriction risks. Distribution runs through research consortium procurement channels and municipal utility tender processes rather than open market retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bacteria powered solar cells function as a stable compounder anchored by wastewater treatment co-benefit monetization, where dual revenue streams from energy generation and effluent remediation insulate demand from pure power market volatility.
For Market Incumbents: To counter solid-state photovoltaic substitution in low-power remote sensing, Algenol Biotech and LanzaTech should deepen backward integration into cyanobacterial strain production and gas fermentation substrate supply respectively. Capacity addition in Denmark's integrated biorefinery clusters captures captive feedstock economics, while EPA TSCA pre-submission investment accelerates field deployment timelines for genetically modified electrogenic organisms.
For New Entrants and Emerging Players: Capture wastewater-utility procurement consolidation in Scandinavia by positioning as integrated service contractors rather than equipment vendors. Agricultural microgrids in Denmark's livestock regions represent the most penetrable segment given grid connection cost premiums. Novozymes-style enzyme optimization partnerships with electrode nanostructuring specialists offer a defensible go-to-market angle without competing on strain IP.
For Investors and Strategic Acquirers: Roll-up economics work for automated microfluidic screening platform operators because strain-electrode interface engineering talent scarcity prevents organic scaling by mid-tier research consortia. Five-to-ten year viability hinges on IRA bioenergy tax provision permanence and EU Green Deal funding continuity. Watch EPA TSCA review cycle acceleration for genetically modified Shewanella and Geobacter strains as the inflection signal for outdoor deployment commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Expansion | Danish water authority procurement models bundle hardware with substrate supply, locking out unbundled competitors. |
| Backward Integration into Fermentation | LanzaTech's gas fermentation infrastructure anchors captive bacterial photovoltaic substrate production economics. |
| AI-Driven Strain Optimization Platform | Machine learning convergence with synthetic biology compresses electrogenic pathway engineering cycles for German consortia. |
| REACH-Compliant Material Qualification | ECHA solvent restrictions force European manufacturers toward aqueous-processable bio-based conductive polymers. |
| Utility Partnership Procurement Consolidation | Municipal ownership of waste streams in Scandinavia enables captive biogas-to-electron conversion economics. |
Study Parameters
Direct dialogue with microbial fuel cell engineering leads, electrochemist-microbiologist research directors, municipal utility procurement officers, and EPA regulatory affairs specialists grounded qualitative assessment of pilot-to-production scaling barriers. Secondary validation drew from ECHA substance restriction databases, EU Green Deal implementation frameworks, EPA TSCA filing records, and Danish Energy Agency funding disclosures. Bottom-up strain-electrode interface cost modeling and top-down renewable energy policy impact assessment triangulated market sizing.
Installed base projections across the analysis window reflect segmented modeling by product type, technology maturity tier, end-use vertical, and application use case. CAGRs derived from policy funding trajectory analysis, laboratory-to-field deployment timeline compression rates, and substitution elasticity against solid-state photovoltaics. Key inputs included electrogenic bacteria patent filing velocity, automated screening platform deployment counts, and wastewater utility tender award patterns.
EPA TSCA review timeline extensions, EU Green Deal funding reallocation, and solid-state photovoltaic cost breakthroughs are the dominant revision risks to bacterial solar cell adoption curves. Forecasts embed assumptions regarding regulatory pathway clarity and research consortium commercialization intent. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market