
 Solar Mirror Market | 2026-2036
Solar Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Mirror Market Analytics
Multi-source procurement among tower and trough developers is restructuring supply relationships across the solar mirror value chain. Saint-Gobain Solar leverages its European float-glass heritage to sustain premium positioning in parabolic trough projects. Rioglass Solar anchors the aftermarket refurbishment segment with specialized re-silvering capabilities. FLABEG FE GmbH competes on precision-curved mirror engineering for utility-scale installations.
A solar mirror is a high-reflectance optical component, typically silver-coated low-iron glass with reflectivity exceeding 94%, manufactured through float-glass forming, precision grinding, and protective coating application to concentrate incident solar radiation onto a receiver or thermal fluid system. Parabolic mirrors command the steepest technical barriers and associated margin pools due to exacting curvature tolerances. Glass substrates dominate material selection for utility applications where decades-long thermal cycling resistance proves essential. The utility end-user segment leads absolute volume, though commercial solar thermal systems represent the fastest-expanding application category as distributed energy mandates tighten.
China's MIIT enforces GB standards on mirror durability and reflectance decay that filter out subscale domestic suppliers. The EU F-Gas Regulation and REACH compliance frameworks shape import requirements for coated aluminum and polymer alternatives entering European concentrated solar power projects. Saudi Arabia's SFDA and local content rules under Vision 2030 redirect procurement toward in-region manufacturing partnerships. Stakeholders must weigh technology transfer commitments against the capital intensity of captive mirror production as project pipelines scale.
Market Dynamics
Utility-scale concentrated solar power procurement in Saudi Arabia and the UAE is forcing mirror suppliers to localize production under strict domestic content rules, compressing traditional European supply chains.
Growth Catalysts
- China's dual carbon goals:MIIT enforcement of updated GB standards on reflectance decay and thermal cycling resistance is filtering out subscale domestic suppliers, consolidating manufacturing capacity among qualified producers.
- NEOM and Red Sea gigaprojects:Saudi Arabia's Vision 2030 infrastructure pipeline is generating concentrated demand for parabolic trough and tower mirror systems at unprecedented single-site volumes.
- Silver-coated low-iron glass:Advances in protective coating chemistry are extending mirror service life beyond 25 years, reducing levelized cost of energy for thermal solar developers.
Market Restraints
- Float-glass feedstock concentration:High-purity silica sand and soda ash supply chains concentrate in select mining regions, exposing mirror manufacturers to input cost volatility and logistics bottlenecks.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases used in certain coating processes create compliance friction for aluminum and polymer mirror alternatives entering European projects.
- Precision curvature tolerances:Parabolic mirror fabrication demands sub-millimeter geometric accuracy that few glass processors can achieve, limiting qualified supplier pools for tower installations.
Strategic Opportunities
- Commercial solar thermal systems:Distributed energy mandates in industrial heat applications represent the fastest-expanding end-use category as factories seek to decarbonize process steam generation.
- Aftermarket refurbishment:Specialized re-silvering and coating restoration services for aging utility-scale installations create recurring revenue streams independent of new project cycles.
- Saudi SFDA localization incentives:Technology transfer partnerships with domestic glass producers offer market access in exchange for in-region manufacturing commitments.
Industry Challenges
- Optical metrology expertise:Shortage of technicians trained in interferometric surface measurement and precision grinding slows quality assurance throughput at expansion facilities.
- REACH compliance documentation:Extended chemical substance registration timelines for novel coating formulations delay product certification for European utility tenders.
- Multi-source procurement complexity:Tower developers splitting orders across mirror suppliers face integration risks at receiver alignment and field assembly stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Mirror Market |
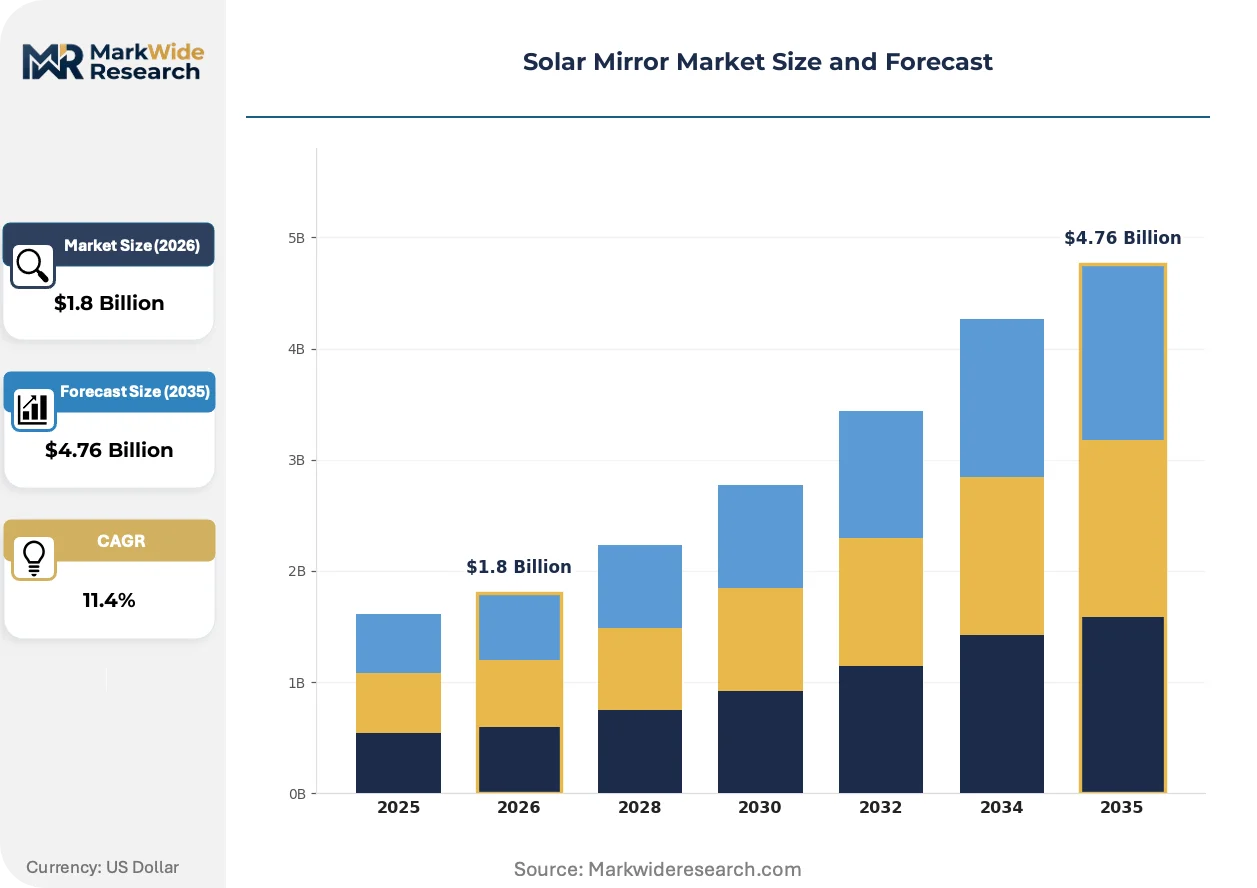
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Mirrors, Parabolic Mirrors, Concentrated Solar Power Mirrors, Vacuum Mirrors Material: Glass, Polymer, Metal, Coated Aluminum Application: Concentrated Solar Power, Solar Thermal Systems, Solar Air Heating, Solar Water Heating End User: Residential, Commercial, Industrial, Utility |
| Companies Covered | 3M Company, Saint-Gobain Solar, Nippon Sheet Glass, Guardian Glass, Flat Glass Group, Rioglass Solar, Abengoa Solar, FLABEG FE GmbH, BrightSource Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Mirror Market Evolving Landscape
Automation of mirror fabrication and inspection workflows is compressing production timelines while tightening optical tolerances. Regulatory frameworks in major demand centers are rewriting import and content requirements. Buyer procurement models are evolving from single-source contracts toward segmented supplier strategies.
Robotic grinding and polishing systems are automating the final curvature correction of parabolic mirror substrates. Tower developers in the Middle East are deploying these systems at greenfield facilities to achieve micron-level surface precision without European technician dependency. This automation is compressing the gap between float-glass blank delivery and field-ready mirror shipment from months to weeks.
China's MIIT has tightened GB standard enforcement on mirror durability testing, mandating accelerated thermal cycling protocols that simulate 25-year field exposure. Subscale domestic producers lacking environmental simulation chambers are exiting the certified supplier pool. Qualified manufacturers are responding by integrating in-house aging test facilities to maintain GB compliance documentation.
Developer procurement teams are unbundling mirror supply from engineering-procurement-construction contracts, creating direct purchasing relationships with glass processors. This disintermediation shifts specification responsibility to project owners and enables multi-source strategies for risk mitigation. Saudi gigaprojects are most visible in this transition, with NEOM entities issuing separate mirror tenders distinct from balance-of-plant awards.
Solar Mirror Market Segmentation
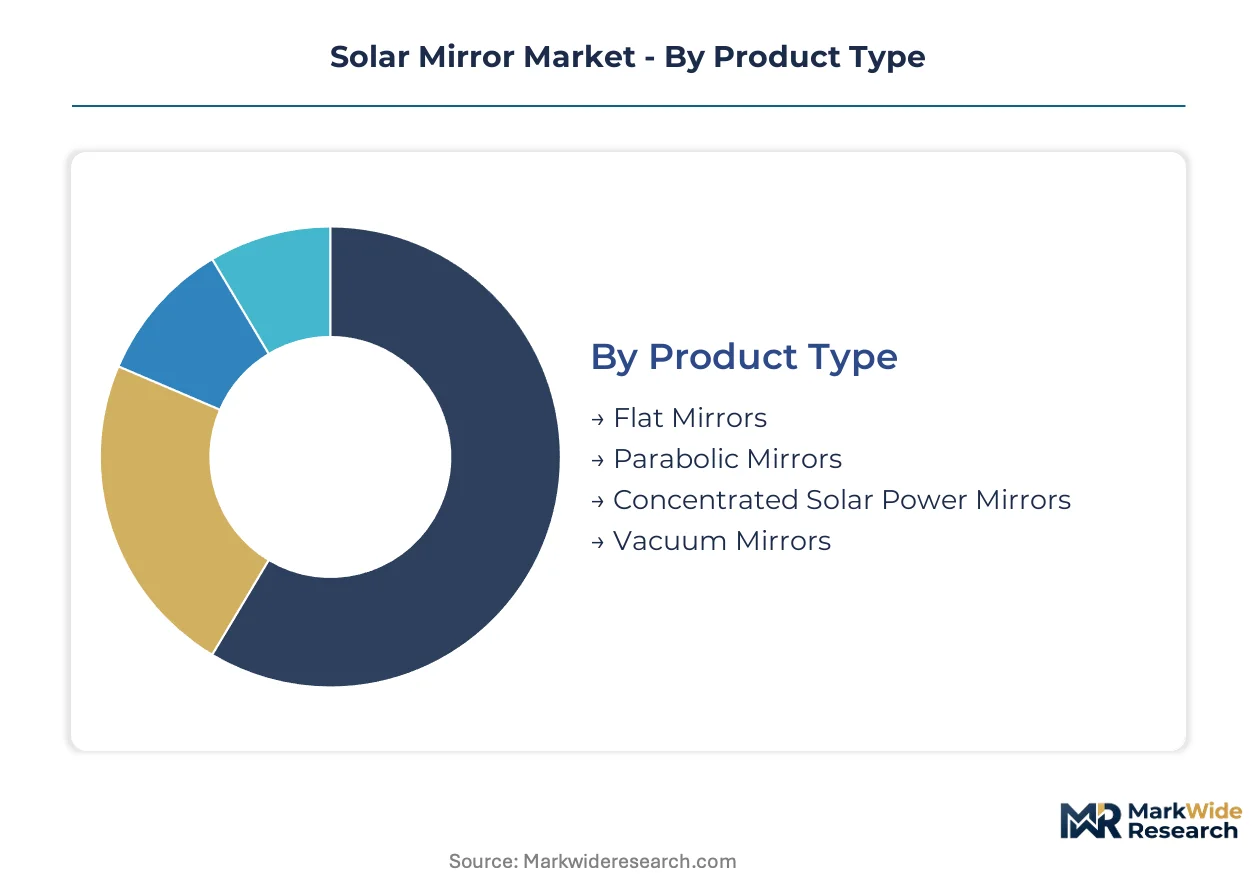
Segmentation in the solar mirror market reveals how technical specifications, material choices, and end-use requirements fragment procurement strategies across project scales. Understanding these divisions exposes where margin pools concentrate and where standardization gives way to custom engineering.
Product Type:
Customization intensity spans from commodity flat glass to precision-engineered curved substrates, with fabrication complexity determining supplier qualification thresholds.
- Parabolic Mirrors:Precision-curved silver-coated substrates requiring sub-millimeter geometric tolerances for trough and tower concentrators. Demand concentrates in Saudi Arabia's NEOM and Red Sea gigaprojects where single-site procurement volumes force multi-source supplier strategies.
- Concentrated Solar Power Mirrors:Utility-grade optical assemblies engineered for 25-year thermal cycling resistance in desert environments. Procurement is accelerating in the UAE and Morocco as developers unbundle mirror supply from EPC contracts to manage receiver alignment risks.
- Flat Mirrors:Standardized low-iron glass panels for linear Fresnel and industrial heat applications.
- Vacuum Mirrors:Evacuated-tube assemblies for high-temperature process steam generation in European industrial facilities.
Leading the category by volume: Concentrated Solar Power Mirrors. Expanding most quickly: Parabolic Mirrors.
Material:
Cost tiers separate premium glass substrates from alternative formulations, with durability requirements dictating material selection across climate zones.
- Glass:Silver-coated low-iron float glass exceeding 94% reflectivity, dominating utility installations where decades-long thermal cycling resistance proves essential. China's MIIT enforces GB standards on reflectance decay that filter out subscale domestic suppliers lacking environmental simulation chambers.
- Coated Aluminum:Lightweight polymer-backed alternatives for commercial rooftop installations where structural load limits constrain glass deployment. EU F-Gas Regulation creates compliance friction for fluorinated coating processes entering European tenders.
- Polymer:Flexible mirror films for portable and temporary solar thermal applications.
- Metal:Polished aluminum substrates for extreme-environment military and aerospace solar concentrators.
Glass commands the revenue concentration. Coated Aluminum gains share fastest in distributed commercial segments.
Application:
Volume concentration sits with utility-scale power generation while regulatory mandates accelerate adoption in industrial process heat.
- Concentrated Solar Power:Utility-scale electricity generation through steam turbine integration, anchoring absolute market volume. Procurement in Saudi Arabia and the UAE is forcing mirror suppliers to localize production under strict domestic content rules.
- Solar Thermal Systems:Distributed heat generation for industrial process steam and district heating, climbing the fastest as factories decarbonize under tightening emissions mandates.
- Solar Water Heating:Residential and commercial building-integrated systems for domestic hot water supply.
- Solar Air Heating:Ventilation pre-heating and agricultural drying applications in cold-climate regions.
Concentrated Solar Power leads absolute volume. Solar Thermal Systems show the steepest expansion trajectory.
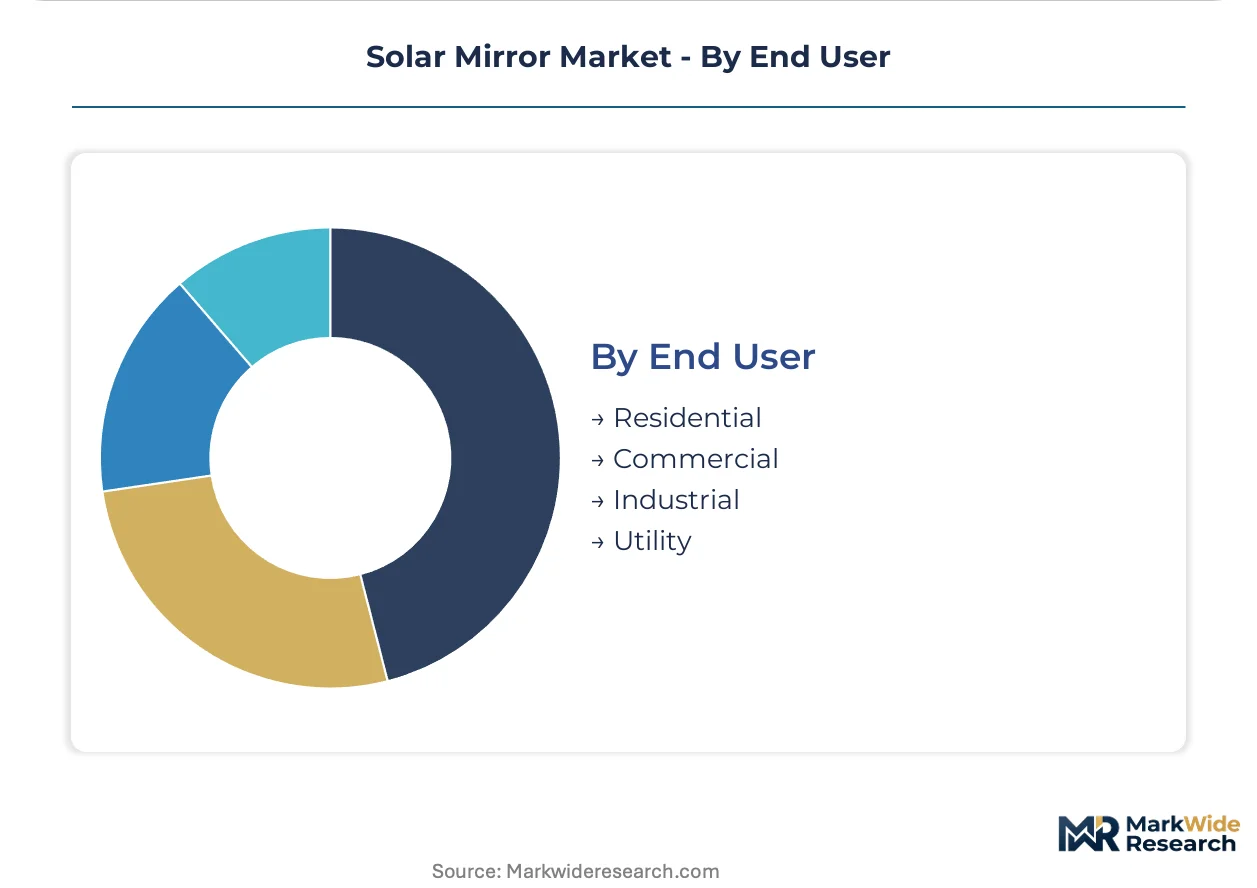
End User:
Customer type determines specification stringency, from residential commodity procurement to utility-grade optical metrology requirements.
- Utility:Gigawatt-scale concentrated solar power plants requiring 25-year service life guarantees and field-proven durability documentation. Tower developers splitting orders across suppliers face integration risks at receiver alignment stages.
- Industrial:Process steam and thermal energy for manufacturing facilities, where aftermarket refurbishment services create recurring revenue independent of new project cycles.
- Commercial:Building-integrated solar thermal and rooftop concentrator installations.
- Residential:Small-scale water heating and space conditioning systems.
Utility segment dominates procurement value. Industrial end-use shows the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand deposits in northern Saudi Arabia and soda ash mining in Wyoming anchor solar mirror feedstock supply chains. These localities concentrate float-glass precursor material access that shapes manufacturing geography.
Saudi Arabia
NEOM and Red Sea gigaprojects drive concentrated procurement of parabolic trough and tower mirror systems at unprecedented single-site volumes. The SFDA enforces local content rules under Vision 2030 that redirect procurement toward in-region manufacturing partnerships. Yanbu and Jubail industrial clusters host emerging glass processing facilities serving gigaproject demand.
China
Dual carbon goals accelerate domestic concentrated solar power deployment and manufacturing upgrades. MIIT enforcement of updated GB standards on reflectance decay and thermal cycling resistance filters out subscale domestic suppliers. Jiangsu and Shandong provinces concentrate qualified float-glass and mirror finishing capacity among certified producers.
United Arab Emirates
Mohammed bin Rashid Al Maktoum Solar Park and Al Dhafra solar installations sustain utility-scale mirror procurement. MOHAP and local content frameworks shape procurement toward domestic value-add requirements. Dubai Industrial City and Khalifa Industrial Zone Abu Dhabi attract mirror assembly operations seeking market access.
Germany
Industrial process heat applications and district heating networks sustain commercial solar thermal demand. EU F-Gas Regulation and REACH compliance frameworks create import friction for coated aluminum alternatives entering European projects. Saxony-Anhalt and Bavaria host precision glass processing clusters serving thermal solar engineering requirements.
Morocco
Noor Ouarzazate and Midelt solar complexes anchor North African concentrated solar power capacity expansion. European financing conditionality shapes procurement toward EU regulatory compliance. Oujda and Casablanca industrial zones concentrate mirror logistics and assembly operations for desert installations.
Solar Mirror Market Competitive Landscape
Global majors compete with regional champions across precision curvature engineering and float-glass heritage. The supplier base organizes around three tiers: European heritage float-glass processors, Chinese integrated glass-to-mirror manufacturers, and specialized curvature engineering boutiques. Competitive moves center on automation of grinding and polishing workflows and technology transfer partnerships for Saudi and UAE market access.
Within the heritage float-glass tier, Saint-Gobain Solar and Nippon Sheet Glass occupy positions defined by decades of optical glass processing lineage. FLABEG FE GmbH exemplifies the precision-curvature engineering archetype through its German GmbH structure. These three anchors represent how geographic origin and corporate form signal capability segmentation across utility-scale project procurement.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain Solar |
| Nippon Sheet Glass |
| Guardian Glass |
| Flat Glass Group |
| Rioglass Solar |
| Abengoa Solar |
| FLABEG FE GmbH |
| BrightSource Energy |
| Others |
Value Network & Pricing Analysis
Backward integration into float-glass blank production anchors pricing power for European heritage processors, while Chinese integrated manufacturers compete on volume scale. This structural divergence separates warranty-backed premium supply from unbundled commodity procurement in Saudi gigaprojects.
Pricing Analysis
Warranty bundling separates premium mirror supply from unbundled commodity procurement, with 25-year service life guarantees commanding substantial premiums in utility-scale tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by curvature precision and thermal cycling certification under MIIT GB standards. Cost compression in standard-grade flat mirrors is intensifying because Chinese integrated manufacturers are absorbing coating chemistry costs. Industrial process heat buyers show highest price sensitivity, while NEOM tower developers prioritize optical metrology documentation over unit cost.
Supply Chain Analysis
Freight costs from European precision-grinding facilities to Middle Eastern gigaprojects add substantial landed cost premiums, incentivizing Yanbu and Jubail localization. High-purity silica sand deposits in northern Saudi Arabia, soda ash mining in Wyoming, and float-glass capacity in Jiangsu province anchor upstream material flows. Single-source vulnerability concentrates in specialized re-silvering chemistry supply. Distribution runs through EPC contractor networks shifting toward direct developer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified precision-curvature capacity scarcity props pricing power for certified suppliers, with sub-millimeter tolerance fabrication bottlenecks limiting rapid supply expansion.
For Market Incumbents: Lock in multi-year direct procurement contracts with NEOM and Red Sea developers before unbundling trends mature. Defend against Chinese integrated manufacturers by embedding aftermarket refurbishment services into original supply agreements. Prioritize captive float-glass supply through backward integration into high-purity silica sand access. For New Entrants and Emerging Players: Begin with aftermarket re-silvering and coating restoration services for aging Spanish and Moroccan trough installations, where incumbent presence thins. Target commercial solar thermal systems for industrial process heat in Germany and Japan, where distributed energy mandates outpace utility-scale deployment cycles. Pursue technology transfer partnerships with Saudi domestic glass producers as market access mechanism. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by energy infrastructure funds seeking vertical integration into solar thermal engineering. Long-term viability hinges on positioning within Saudi and UAE localization frameworks as gigaproject pipelines mature. Watch for MIIT GB standard enforcement tightening as signal for Chinese supplier consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Grinding Automation | Tower developers in Saudi Arabia deploy German-engineered systems to achieve micron-level surface precision without European technician dependency. |
| In-House Aging Test Facilities | Qualified Chinese manufacturers integrate environmental simulation chambers to maintain MIIT GB compliance documentation as subscale competitors exit. |
| Technology Transfer Partnerships | European curvature engineering specialists exchange process know-how for Saudi SFDA market access under Vision 2030 localization mandates. |
| Aftermarket Refurbishment Services | Rioglass Solar anchors recurring revenue streams through specialized re-silvering capabilities independent of new project cycles. |
| Direct Developer Procurement | NEOM entities unbundle mirror supply from EPC contracts, shifting specification responsibility to project owners and enabling multi-source risk mitigation. |
Research Methodology
Independent corroboration across EPC contractor procurement officers, solar thermal engineering directors, and float-glass plant managers underwrites the qualitative findings in this analysis. Primary interviews with utility-scale project developers, precision optical metrology technicians, and aftermarket service operators combined with secondary validation from EIA concentrated solar power databases, IEA technology roadmaps, and Saudi Vision 2030 infrastructure disclosures. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment triangulate volume estimates.
Rate-of-change decomposition across the analysis window segments expansion by product type, material substrate, application end-use, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed gigaproject procurement timelines and manufacturing capacity expansion announcements. Forecast inputs incorporate MIIT GB standard enforcement trajectories and Saudi local content rule implementation pace.
Underlying measurement precision varies by segment; utility-scale concentrated solar power installations carry tighter precision than distributed commercial thermal systems. Forecasts reflect assumptions about gigaproject execution timelines and certification standard harmonization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Austria Solar Energy Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Bifacial Solar Panels Market