
 Chile Renewable Energy Market | 2026-2036
Chile Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Renewable Energy Market Analysis
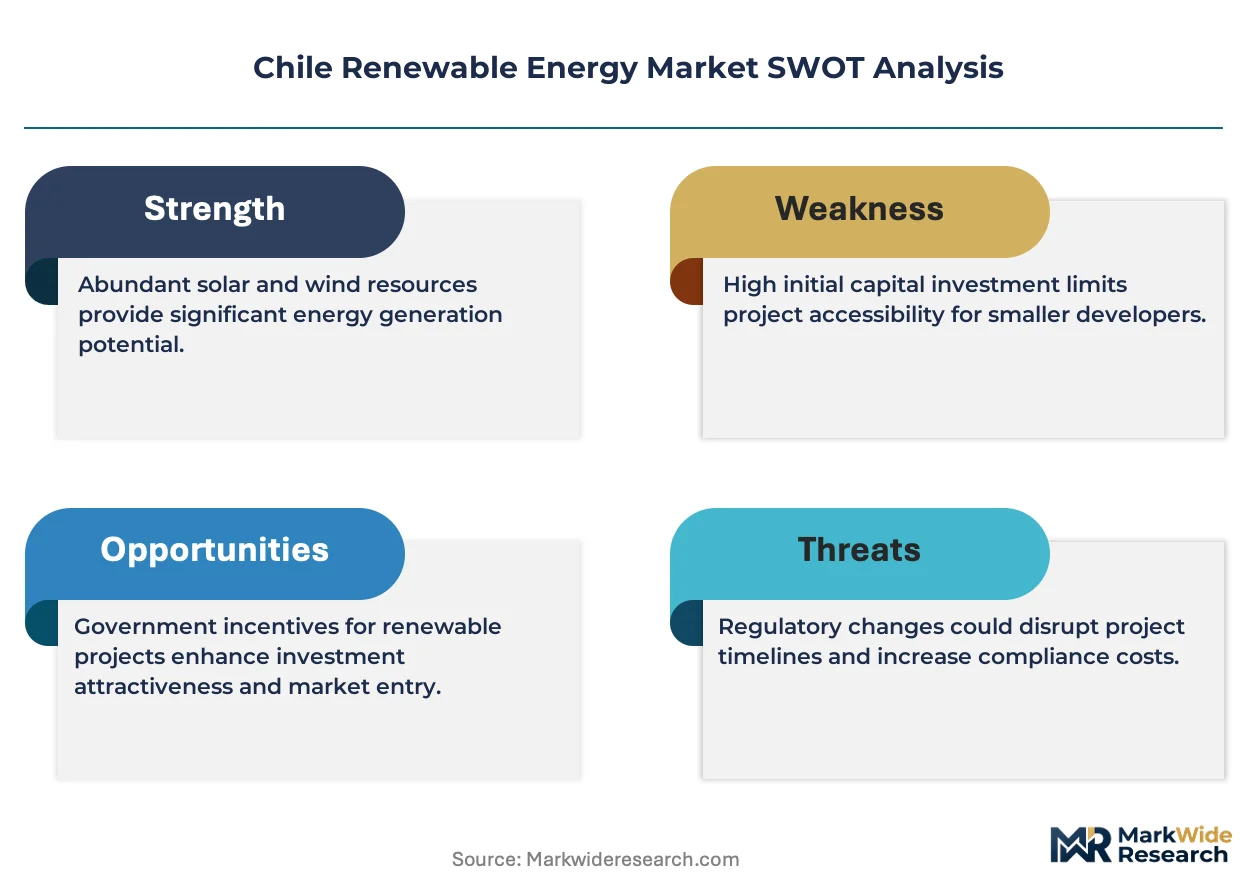
A shift from single-source to multi-source power procurement is restructuring how Chilean energy buyers contract capacity. Colbún S.A. anchors its position through diversified renewable assets across multiple regions. Enel Green Power Chile SpA leverages extensive transmission access to dominate utility-scale solar development. Mainstream Renewable Power competes aggressively in wind with established project pipelines in southern zones.
Chile renewable energy encompasses electricity generated from solar, wind, geothermal, and biomass resources through photovoltaic panels, concentrated solar power systems, wind turbines, and hybrid configurations, with utility-scale installations typically exceeding 5 MW capacity and feeding into the national SIC or SING grids. The primary purpose centers on decarbonizing Chile's power matrix while supplying competitively priced electricity to mining, industrial, and residential consumers. Solar photovoltaic technology leads installed capacity due to exceptional irradiance in the Atacama Desert, while concentrated solar power with thermal storage commands premium margins by delivering dispatchable evening supply. Wind turbines gain share in the Los Lagos and Magallanes regions where sustained patagonian gusts support high capacity factors. Utility-scale installations concentrate investment and financing activity, though distributed generation accelerates among commercial users seeking to bypass regulated tariff volatility.
Chile's Ministry of Energy enforces the Non-Conventional Renewable Energy law requiring progressively higher clean electricity quotas, while the Superintendency of Electricity and Fuels monitors grid compliance and generator certification standards. The Environmental Evaluation Service reviews project permits under Law 19.300, creating procedural timelines that shape developer capital deployment schedules. Stakeholders must track transmission expansion timelines and curtailment risk in northern zones where solar saturation tests grid absorption limits.
Market Dynamics
Long-term power purchase agreements from mining conglomerates are compressing merchant risk exposure and redirecting developer capital toward contracted capacity rather than spot-market exposure.
Growth Catalysts
- Non-Conventional Renewable Energy Law:Chile's escalating clean electricity quotas force conventional generators to procure renewable certificates or build green assets, sustaining offtake demand.
- Atacama Desert irradiance:Exceptional solar resource concentration reduces levelized cost of energy and attracts international project finance to northern Chilean zones.
- Mining sector electrification:Copper and lithium producers face Scope 3 emission scrutiny from European and Asian buyers, compelling clean power contracting.
Market Restraints
- Transmission saturation:Grid absorption limits in Antofagasta and Tarapacá regions force curtailment during peak solar hours, degrading project returns.
- Lithium carbonate volatility:Battery storage project costs fluctuate with Chilean export-driven lithium pricing, complicating long-term financing assumptions.
- Environmental permitting delays:Law 19.300 review timelines at the Environmental Evaluation Service extend development schedules by 18-36 months.
Strategic Opportunities
- Magallanes wind expansion:Patagonian corridors with capacity factors exceeding 45% remain underdeveloped relative to northern solar concentration.
- Green hydrogen integration:Electrolyzer deployments at port facilities create anchor demand for otherwise curtailed renewable generation.
- Distributed generation acceleration:Commercial users in Santiago and Valparaíso bypass regulated tariff volatility through behind-the-meter solar installations.
Industry Challenges
- Grid synchronization expertise:Utility-scale inverter and battery control system specialists remain scarce in Chilean labor markets.
- Land tenure conflicts:Indigenous consultation requirements under ILO Convention 169 create procedural uncertainty for projects on ancestral territory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Renewable Energy Market |
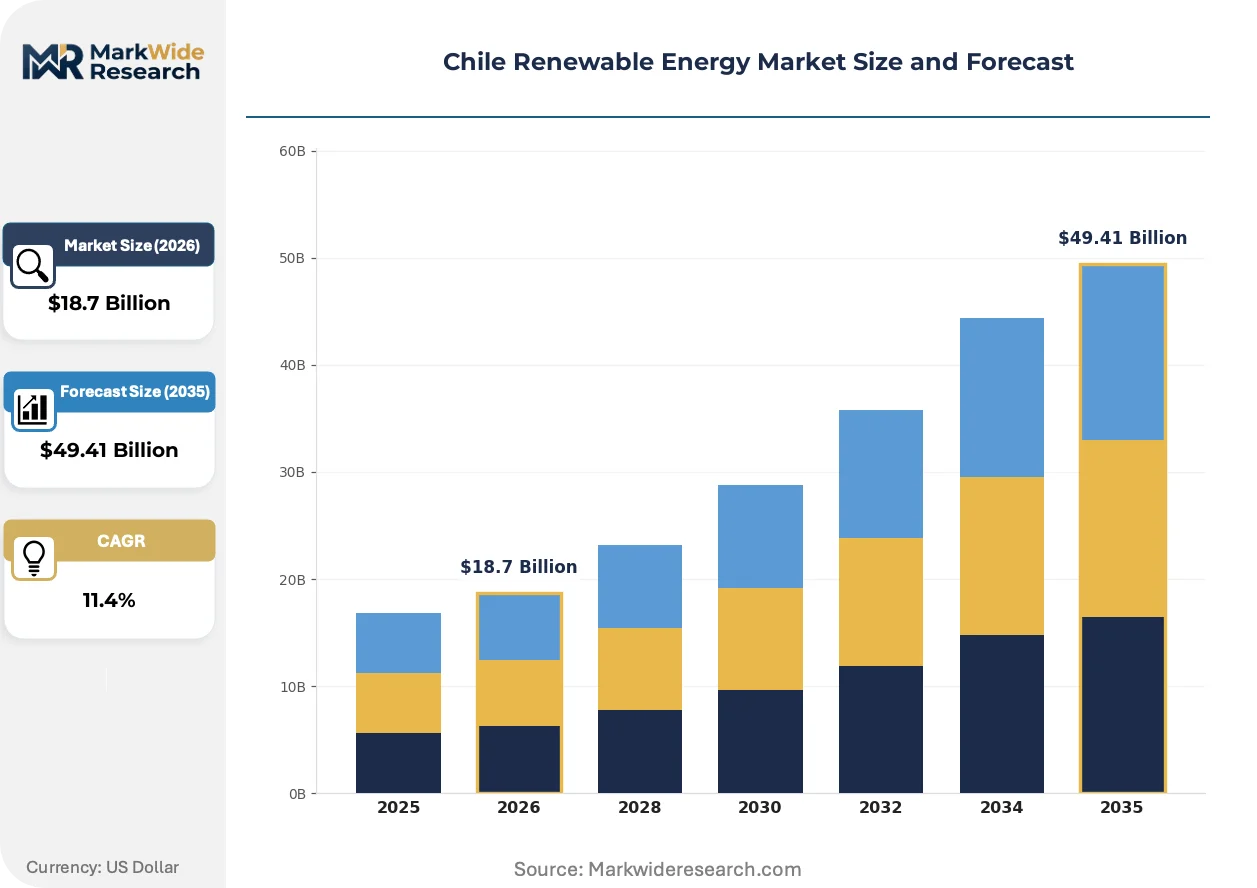
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Geothermal, Biomass End User: Residential, Commercial, Industrial, Government Technology: Photovoltaic, Concentrated Solar Power, Wind Turbines, Hybrid Systems Installation Type: Utility-Scale, Distributed Generation, Off-Grid, On-Grid |
| Companies Covered | Colbún S.A., Mainstream Renewable Power, Enel Green Power Chile SpA, Atlas Renewable Energy, Statkraft Chile, AES Andes S.A., Acciona Energía, Grenergy Renovables, Engie Energía Chile S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Renewable Energy Market Emerging Trajectories
Hybrid renewable configurations are displacing single-technology project designs as developers seek to optimize capacity factors and reduce curtailment exposure across Chile's diverse geography.
Bifacial photovoltaic modules paired with single-axis tracking systems are capturing reflected irradiance from Atacama Desert surfaces, boosting yield by 8-12% over monofacial equivalents. Mining offtakers in Calama and María Elena are specifying these configurations in tender documents. This technology is decentralizing project siting decisions away from the highest-irradiance core zones toward marginal lands with superior grid access.
Chile's Ministry of Energy is tightening grid code requirements for frequency response and reactive power support from inverter-based resources, mimicking European Network Codes. Developer engineering teams are resizing power plant components to meet these standards. Utility-scale solar in the northern SING grid faces the steepest compliance cost increases.
Corporate buyers are abandoning annual volume contracts in favor of 24/7 carbon-free energy matching, requiring developers to bundle solar, wind, and storage. Data center operators in Santiago are driving this specification change. Southern Biobío wind farms are capturing premium pricing by filling evening gaps left by Atacama solar output.
Chile Renewable Energy Market Segmentation
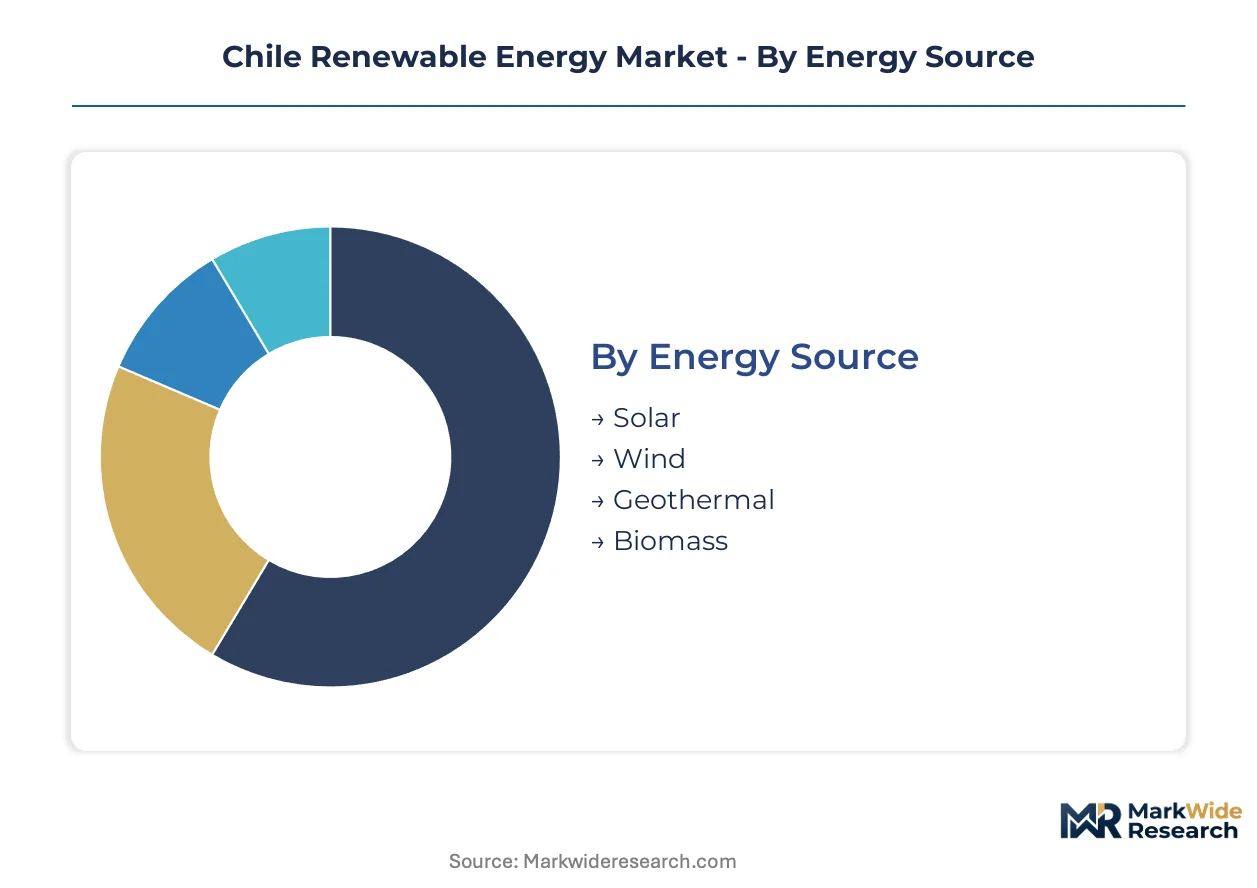
Chile's renewable energy market fragments across four structural dimensions that determine project economics, financing structures, and regulatory exposure. Each segmentation axis reveals distinct capital deployment patterns and offtake contracting strategies among developers active in the SIC and SING grids.
Energy Source:
Standardized resource assessment frameworks dominate solar and wind development, while geothermal and biomass require customized exploration and feedstock agreements.
- Solar:Photovoltaic arrays and concentrated solar power systems exploit Atacama Desert irradiance exceeding 2,700 kWh/m² annually. Mining offtakers in Antofagasta and Tarapacá regions anchor procurement under 15-20 year power purchase agreements, though transmission saturation in these zones forces developers toward hybrid configurations with storage.
- Wind:Onshore turbines in Los Lagos and Magallanes regions achieve capacity factors above 45% from sustained Patagonian gusts. Mainstream Renewable Power and Enel Green Power compete for grid connection rights in these southern corridors where absorption limits remain less constraining than northern solar zones.
- Geothermal:High-temperature resources in the Andean volcanic belt require bespoke reservoir characterization and extended drilling programs.
- Biomass:Agricultural residue combustion and biogas recovery serve localized industrial heat demand in central valley agricultural zones.
Most installed capacity flows through Solar. Expansion is steepest in Wind.
End User:
Contract duration and creditworthiness vary sharply across customer types, with industrial offtakers demanding 24/7 carbon-free matching while residential segments accept intermittent supply.
- Industrial:Copper and lithium producers under Scope 3 emission pressure from European automotive buyers negotiate firm renewable supply with penalty clauses for curtailment. Codelco and Albemarle procurement teams specify bifacial tracking systems and bundled storage in northern Chile tender documents.
- Commercial:Santiago data center operators and retail chains pursue behind-the-meter solar to hedge regulated tariff volatility, accelerating distributed generation permitting queues at the Environmental Evaluation Service.
- Residential:Net metering programs in middle-income Santiago and Valparaíso municipalities drive small-scale rooftop deployment.
- Government:Ministry of Energy direct procurement supports rural electrification and public building retrofits.
Industrial offtakers concentrate developer origination efforts. Commercial self-generation is climbing the fastest.
Technology:
Cost curves and dispatchability profiles separate mature photovoltaic deployment from emerging hybrid architectures requiring integrated control systems.
- Photovoltaic:Crystalline silicon modules with single-axis tracking capture 8-12% yield premiums over fixed-tilt equivalents through reflected irradiance on Atacama Desert surfaces. Project finance terms from Santander and Banco de Chile favor these standardized configurations with proven operation and maintenance protocols.
- Concentrated Solar Power:Molten salt thermal storage enables evening dispatch to mining loads, commanding premium tariffs but requiring specialized EPC contractors with tower and trough experience.
- Wind Turbines:Hub heights above 120 meters access steadier Patagonian wind layers.
- Hybrid Systems:Co-located solar, wind, and lithium-ion storage optimize capacity factors and reduce curtailment exposure.
Photovoltaic dominates megawatt-hour additions. Hybrid Systems show the steepest expansion trajectory as grid codes tighten frequency response requirements.
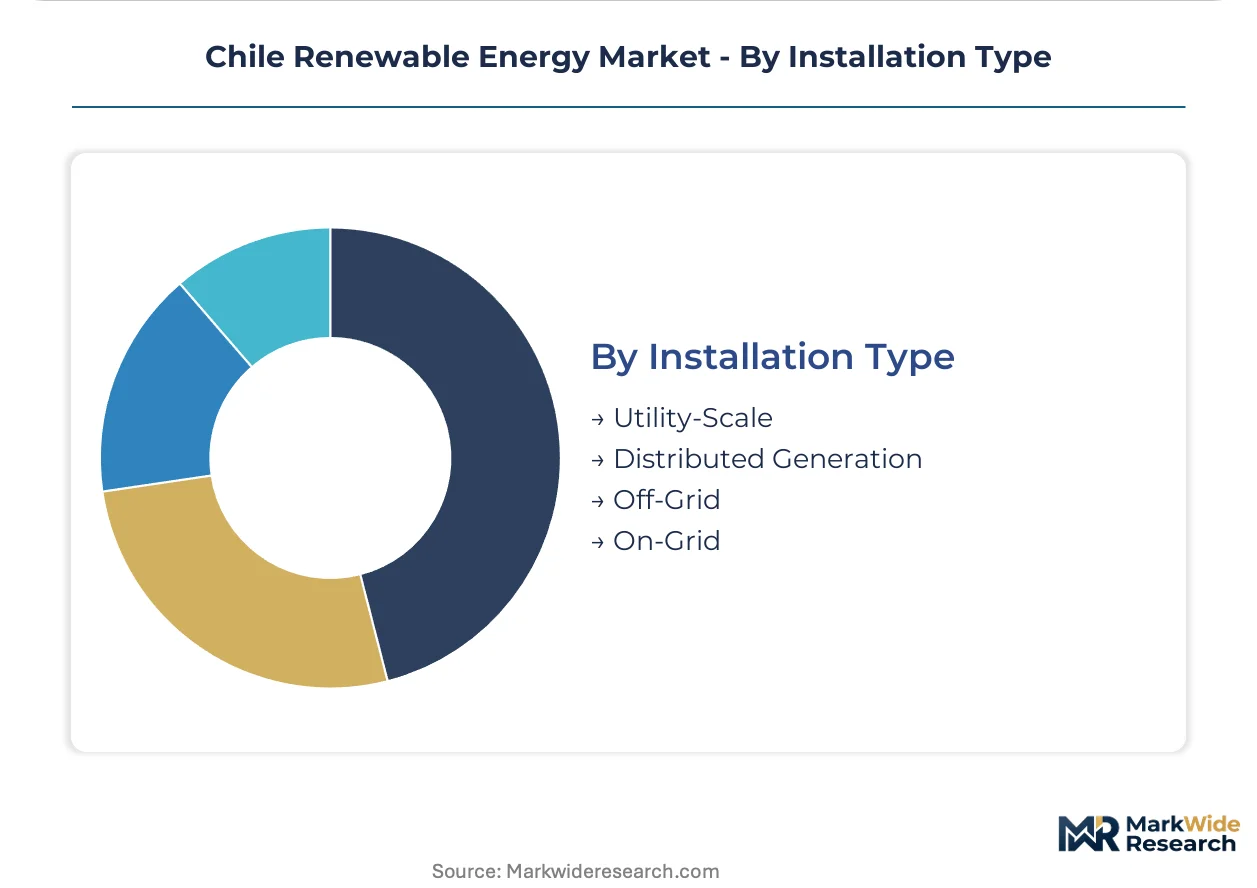
Installation Type:
Scale economies and permitting complexity create divergent capital structures between utility-scale auctions and distributed commercial projects.
- Utility-Scale:Installations exceeding 5 MW capacity feed into high-voltage transmission infrastructure and qualify for long-term auction contracts under the Ministry of Energy's supply tender mechanisms. These projects concentrate international project finance and sovereign guarantee structures.
- Distributed Generation:Behind-the-meter systems under 5 MW bypass transmission access queues and regulated tariff exposure, appealing to commercial users in Santiago metropolitan zone.
- Off-Grid:Remote mining camps and agricultural operations in Atacama and Magallanes regions deploy diesel-hybrid microgrids transitioning to renewable dominance.
- On-Grid:Standardized interconnection protocols apply to residential and commercial rooftop systems.
Utility-Scale captures institutional capital flows. Distributed Generation is expanding most quickly as net metering regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antofagasta anchors Chile's renewable energy investment flows through its mining-industrial corridor connecting Calama, María Elena, and the port city itself. The region's exceptional solar irradiance attracts concentrated developer capital. Grid saturation risks now redirect new projects toward hybrid configurations with storage.
Antofagasta Region
Copper mining operations at Escondida and Collahuasi drive firm renewable procurement under 15-20 year power purchase agreements. The Ministry of Energy's transmission expansion plans target absorption limits in this zone. Calama's industrial cluster hosts bifacial tracking solar installations serving Codelco's electrification targets.
Tarapacá Region
Iquique's free trade zone operators and Arica port facilities create anchor demand for clean hydrogen electrolyzer projects. The Environmental Evaluation Service processes concentrated solar permits under Law 19.300. Pampa del Tamarugal hosts utility-scale photovoltaic arrays facing curtailment during peak irradiance hours.
Biobío Region
Concepción's industrial base and forestry sector sustain biomass co-generation and biogas recovery installations. Grid code tightening for frequency response applies uniformly across central zone generators. Coronel and Lota municipalities attract wind-solar hybrid development to fill evening supply gaps.
Los Lagos Region
Salmon aquaculture processing and pulp mills in Puerto Montt and Osorno negotiate behind-the-meter renewable supply. The Superintendency of Electricity and Fuels monitors compliance with NCRE law quotas in this hydro-dominated grid zone. Patagonian wind corridors above 45% capacity factor remain underdeveloped relative to northern solar concentration.
Magallanes Region
Punta Arenas port infrastructure and remote mining camps transition diesel-hybrid microgrids toward renewable dominance. Indigenous consultation requirements under ILO Convention 169 shape land access procedures for wind projects. Río Turbio and Porvenir clusters test extreme climate turbine designs for export to Antarctic logistics operations.
Chile Renewable Energy Market Vendor Landscape
Global majors compete with regional champions across transmission access and mining offtake contracting. The vendor base concentrates around three tiers: integrated utilities with diversified generation portfolios, pure-play renewable developers with project pipelines, and international IPPs leveraging parent balance sheets. Strategic moves center on securing long-term power purchase agreements and acquiring grid connection rights in absorption-constrained zones.
Within the integrated utility tier, Colbún S.A. and AES Andes S.A. occupy positions spanning conventional and renewable assets across multiple grid zones. Among international pure-play developers, Mainstream Renewable Power and Enel Green Power Chile SpA exemplify contrasting geographic strategies—one concentrating Patagonian wind development, the other dominating Atacama solar deployment through extensive transmission access.
| Leading Market Players |
|---|
| Colbún S.A. |
| Mainstream Renewable Power |
| Enel Green Power Chile SpA |
| Atlas Renewable Energy |
| Statkraft Chile |
| AES Andes S.A. |
| Acciona Energía |
| Grenergy Renovables |
| Engie Energía Chile S.A. |
| Others |
Supply Flow & Price Mechanics
Captive integration into lithium carbonate processing and electrolyzer manufacturing anchors both supply security and pricing power for Chilean developers bidding into mining offtake tenders. This vertical control over battery storage components buffers project returns against commodity volatility while enabling competitive positioning in 24/7 carbon-free energy contracts.
Pricing Analysis
Input-cost pass-through from lithium carbonate and polysilicon fluctuations dominates tariff negotiations between developers and mining offtakers. Project-based long-term offtake contracts with 15-20 year tenors predominate, with price differentiation resting on dispatchability guarantees and storage bundling rather than technology alone. Cost compression in standardized photovoltaic configurations is intensifying because bifacial module supply gluts from Chinese manufacturers are pressuring EPC margins. Industrial copper producers exhibit lowest price sensitivity, accepting premium tariffs for firm evening supply, while commercial distributed generation buyers in Santiago negotiate aggressively on upfront capital costs.
Supply Chain Analysis
Workforce availability constraints in Chinese polysilicon ingot manufacturing and Vietnamese module assembly are extending delivery timelines for Atacama project developers. Geographic supply concentration centers on China for crystalline silicon cells, South Korea for lithium-ion battery cells, and Germany for power electronics inverters. Raw material dependencies span high-purity quartz, cobalt-free cathode chemistries, and rare-earth permanent magnets for turbine generators. Single-source vulnerability in inverter semiconductor components poses acute risk given grid code tightening for frequency response. Distribution runs through specialized EPC contractors with Atacama Desert construction experience rather than generalist logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's renewable energy market functions as a geographic-arbitrage play where exceptional Atacama irradiance and Patagonian wind capacity factors offset higher transmission and permitting costs relative to competing jurisdictions.
For Market Incumbents: Hedge exposure to northern grid saturation by accelerating hybrid storage deployments and securing incremental transmission rights in Magallanes wind corridors before connection queues lengthen. Defensive consolidation of project development pipelines in Biobío and Los Lagos regions counters emerging pure-play developers targeting southern zone grid access. Priority lever: backward integration into battery storage system integration capabilities to capture margin otherwise flowing to Korean cell suppliers. For New Entrants and Emerging Players: Chile's updated NCRE law escalating clean electricity quotas opens a window for specialized geothermal developers targeting Andean volcanic belt resources with bespoke reservoir characterization capabilities. White-space targets concentrate in distributed generation commercial rooftop segments in Valparaíso and Concepción metropolitan zones, plus green hydrogen electrolyzer integration at Arica and Iquique port facilities. Go-to-market angle: 24/7 carbon-free energy matching contracts for Santiago data center operators requiring evening wind fill from southern zones. For Investors and Strategic Acquirers: Consolidation pressure builds where transmission connection rights in absorption-constrained northern zones concentrate among fragmented project development shops with stalled permitting timelines. Long-term viability framing favors developers with diversified technology portfolios spanning solar, wind, and storage rather than single-technology pure-plays vulnerable to curtailment risk. Acquisition target archetype: mid-cap developers with secured grid access in Magallanes and Biobío regions. Signal to watch as inflection indicator: Ministry of Energy announcements on southern transmission expansion timelines and green hydrogen offtake auction structures.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Storage Integration | Co-located lithium-ion systems at Atacama solar sites reduce curtailment exposure and meet mining offtaker firm supply requirements. |
| Patagonian Wind Capacity Buildout | Magallanes and Los Lagos projects capture premium 24/7 pricing by filling evening gaps left by northern solar output. |
| Green Hydrogen Electrolyzer Partnership | Port facility deployments at Arica and Punta Arenas create anchor demand for otherwise curtailed renewable generation. |
| Behind-the-Meter Distributed Generation | Commercial rooftop installations in Santiago and Valparaíso bypass regulated tariff volatility and transmission access queues. |
| Grid Code Compliance Certification | Frequency response and reactive power capabilities satisfy Superintendency of Electricity and Fuels tightening standards for inverter-based resources. |
Methodological Framework
Bottom-up mining offtake and industrial load modeling reconciled against top-down transmission expansion and generation capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators at Chile's Coordinador Eléctrico Nacional were combined with secondary validation from Ministry of Energy auction disclosures, Superintendency of Electricity and Fuels compliance databases, Environmental Evaluation Service permitting records, and IEA renewable investment flow reports.
Historical trendline analysis of installed capacity additions, curtailment rates, and power purchase agreement pricing across the analysis window established baseline growth trajectories. Segmentation dimensions modeled include energy source, end-user category, technology configuration, and installation scale, with CAGRs derived from regression analysis of project finance commitment timelines and offtake contract execution rates. Industry-specific forecast inputs incorporate lithium carbonate price volatility assumptions and grid absorption limit scenarios from transmission expansion schedules.
Revisions become necessary when Ministry of Energy quota escalations accelerate, Environmental Evaluation Service permitting timelines extend beyond modeled ranges, or lithium-ion battery supply disruptions from Chilean export policy shifts materialize. Material deviation in these named triggers warrants pause and re-evaluation of project return assumptions and competitive positioning forecasts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
US Solar Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar Microgrid Market