
 Solar Cell Films Market | 2026-2036
Solar Cell Films Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cell Films Market Analysis
Multi-source procurement for ethylene-vinyl acetate encapsulants is pivoting toward vertically integrated resin-to-film operations as module makers seek supply security. First Solar anchors North American thin-film production through captive cadmium telluride semiconductor deposition. Hanwha Qcells leverages integrated cell-and-module capacity across Korea and Malaysia to control encapsulant quality. Kuraray Co., Ltd specializes in polyvinyl butyral interlayer supply for building-integrated photovoltaic glass laminates.
Solar cell films are multilayer polymer or inorganic coatings, typically 0.4–0.8 mm in thickness, that encapsulate photovoltaic cells to provide electrical insulation, moisture barrier protection, and mechanical support against environmental degradation. These films enable module durability exceeding 25 years in field deployment while maintaining optical transmission above 91% in the visible spectrum. Thin film technology dominates manufacturing scale due to established gigawatt-scale CIGS and CdTe production lines, though perovskite formulations are attracting R&D investment for next-generation tandem cell architectures. Polymer films sustain the largest volume share across residential and utility applications where flexible encapsulation reduces module weight and installation cost.
The EPA regulates hazardous material content in photovoltaic manufacturing under TSCA, while the EU F-Gas Regulation and REACH restrict fluorinated polymer use in backsheet films, forcing reformulation toward polyolefin alternatives. India's BIS certification mandates and PLI scheme domestic-content rules are reshaping supplier qualification criteria for film vendors targeting project developers. Stakeholders must monitor perovskite stability certification protocols and evolving country-of-origin compliance thresholds before committing to regional manufacturing footprints.
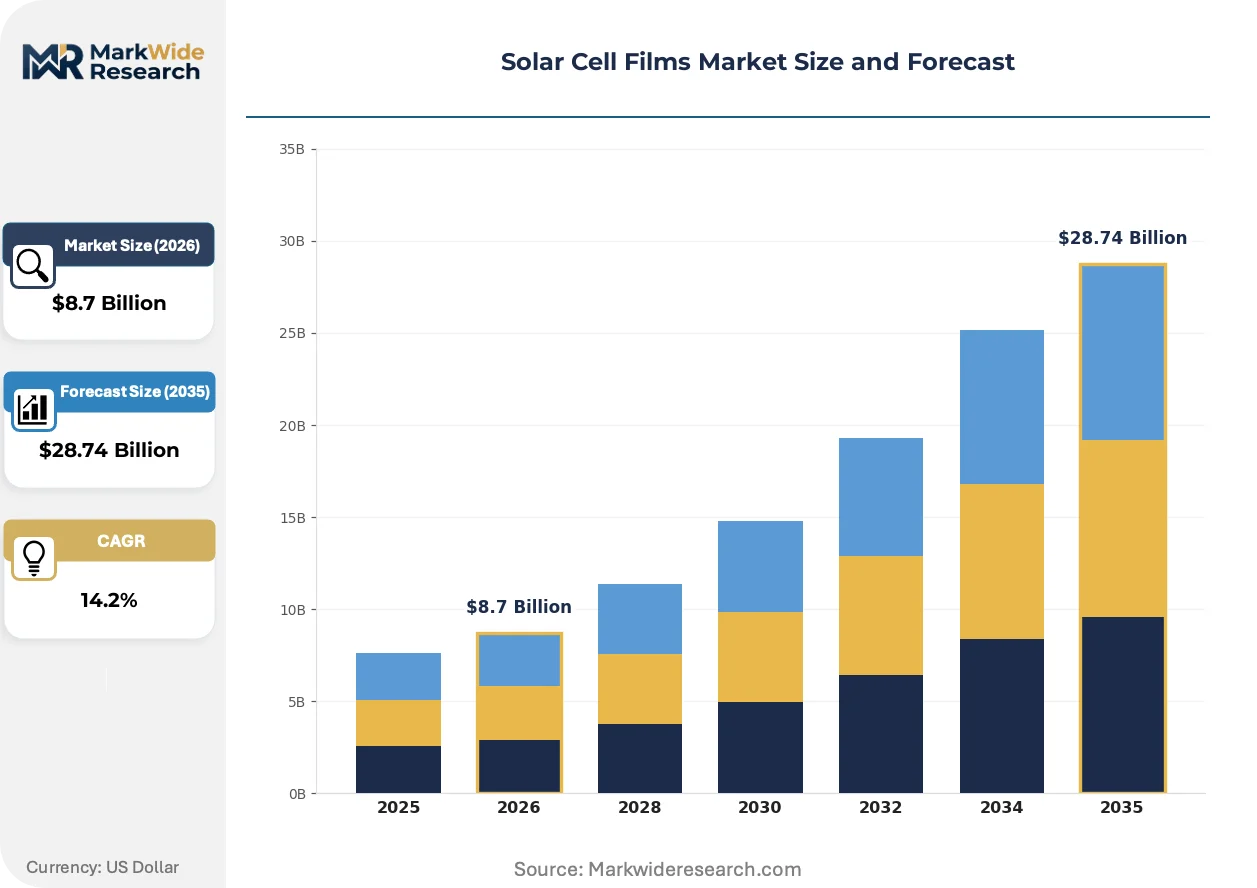
Market Dynamics
Utility-scale developers are consolidating procurement around vertically integrated resin-to-film suppliers to secure encapsulant supply chains against raw material volatility and regulatory compliance tightening. This structural concentration is compressing margins for merchant film producers while rewarding backward-integrated chemical conglomerates.
Growth Catalysts
- India PLI scheme:Domestic-content rules for solar manufacturing are accelerating local film production capacity and creating captive demand for ethylene-vinyl acetate and polyolefin encapsulant formulations.
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is forcing module manufacturers toward fluorine-free backsheet films, opening substitution demand for polyolefin and co-extruded alternatives.
- Building-integrated photovoltaics:Architectural glass laminates requiring polyvinyl butyral interlayers are penetrating commercial facades and residential skylight segments.
Market Restraints
- Ethylene-vinyl acetate resin concentration:Three petrochemical hubs control over two-thirds of global EVA supply, exposing film manufacturers to feedstock allocation risk and price volatility.
- Perovskite stability limitations:Moisture sensitivity and ion migration in unencapsulated perovskite active layers remain unresolved barriers to tandem cell commercialization.
- REACH compliance costs:Registration, evaluation and authorization of novel polymer chemistries imposes six-figure euro burdens on reformulation cycles for backsheet suppliers.
Strategic Opportunities
- Agrivoltaics deployment:Lightweight, flexible polymer encapsulants are enabling elevated solar arrays above active farmland without soil compaction or heavy mounting infrastructure.
- US Inflation Reduction Act:Domestic content bonus credits for utility-scale projects are incentivizing North American film manufacturing investments and local supply qualification.
- Perovskite-silicon tandems:Multi-junction architectures requiring specialized barrier films with water vapor transmission rates below 0.01 g/m²/day are creating premium encapsulant tiers.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing optical clarity, adhesion, and UV stability across 25-year service life projections command premium compensation and limited talent pools.
- IEC 61215 certification timelines:Extended damp-heat and thermal cycling test protocols delay new encapsulant qualification by 12-18 months, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cell Films Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polymer, Glass, Thin Film, BIPV Application: Residential, Commercial, Industrial, Utility Technology: CIGS, CdTe, Organic, Perovskite End User: Developers, Installers, OEMs, Energy Providers |
| Companies Covered | First Solar, KANEKA CORPORATION, 3M, JA Solar Technology Co., Ltd., Ascent Solar Technologies, Inc., Hanwha Qcells, SHARP CORPORATION, Oxford Photovoltaics Ltd., Kuraray Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cell Films Market Emerging Trajectories
Film suppliers are racing to develop next-generation encapsulants that satisfy simultaneously tightening optical performance standards, extended durability warranties, and evolving chemical compliance regimes across multiple jurisdictions.
Polyolefin elastomer formulations are expanding into utility-scale module manufacturing as direct replacements for conventional ethylene-vinyl acetate. Hanwha Qcells and First Solar have qualified co-extruded polyolefin encapsulants for their respective CdTe and silicon product lines. This material transition is expanding into premium module tiers where manufacturers seek to eliminate acetic acid generation and delamination risk over multi-decade deployment horizons.
The EU F-Gas Regulation and accompanying REACH restrictions on per- and polyfluoroalkyl substances are compelling backsheet suppliers to abandon fluorinated polymer architectures entirely. Manufacturers are reformulating toward polyethylene-based barrier films with vapor-deposited aluminum oxide coatings. European module assemblers are qualifying these alternatives ahead of 2025 compliance deadlines to avoid import detention at customs.
Long-term power purchase agreements are reshaping buyer specifications toward performance-guaranteed encapsulant supply contracts rather than spot market procurement. Indian and Southeast Asian project developers are signing five-year offtake agreements with resin-to-film integrated suppliers. This contracting pattern is most visible in Gujarat and Rajasthan solar parks where domestic content requirements intersect with developer financing covenants.
Solar Cell Films Market Segmentation
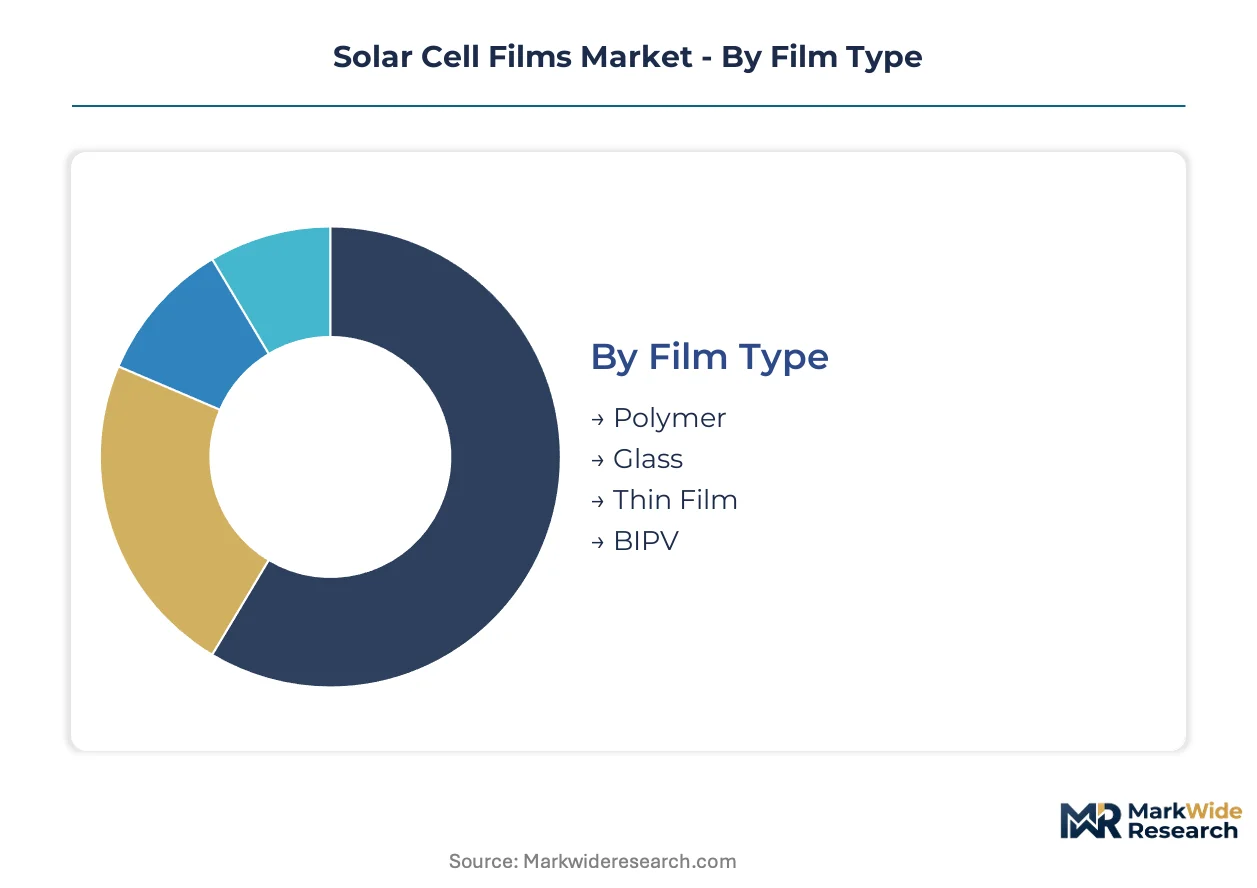
Solar cell film procurement patterns diverge sharply across integration contexts, with standalone encapsulant films commanding premium qualification cycles while embedded thin-film architectures reshape manufacturing economics. Understanding these structural divisions reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Film Type:
Standalone polymer films operate in modular replacement markets and aftermarket refurbishment, while glass and thin-film formats embed directly into integrated cell manufacturing lines.
- Polymer:Ethylene-vinyl acetate and polyolefin elastomer formulations provide flexible encapsulation for crystalline silicon modules. Indian PLI scheme incentives are accelerating domestic compounding capacity in Gujarat and Tamil Nadu to serve utility-scale developers facing domestic-content rules.
- Thin Film:Cadmium telluride and CIGS semiconductor layers deposit directly onto rigid substrates, eliminating separate encapsulant procurement. First Solar's Ohio and Malaysia manufacturing lines anchor this segment's production scale through captive semiconductor deposition.
- Glass:Tempered frontsheet and backsheet laminates serve dual-glass module architectures requiring enhanced mechanical load tolerance. Bifacial module penetration in Chinese and Southeast Asian manufacturing is sustaining demand.
- BIPV:Polyvinyl butyral interlayers integrate photovoltaic cells into architectural glazing for commercial facades. Kuraray's specialized interlayer supply supports building-integrated installations across Japanese and European commercial construction.
Polymer films lead volumes today; BIPV is gaining share fastest through commercial facade retrofits and green building mandates.
Application:
Cost tier differentiation separates high-volume utility procurement from premium commercial installations where performance guarantees justify encapsulant upgrades.
- Utility:Gigawatt-scale solar parks specify standardized encapsulant formulations under long-term power purchase agreements. Rajasthan and Gujarat developers are consolidating procurement around five-year offtake contracts with resin-integrated suppliers to satisfy financing covenants.
- Commercial:Rooftop and carport installations prioritize lightweight polymer films to reduce structural loading. Building-integrated photovoltaic penetration in European commercial construction is expanding polyvinyl butyral interlayer demand.
- Residential:Distributed solar deployments favor flexible encapsulants enabling rapid installation and module weight reduction. Southeast Asian markets are scaling residential capacity through financing programs in Vietnam and the Philippines.
- Industrial:On-site generation for manufacturing facilities combines durability requirements with space constraints. Agrivoltaic deployments above active farmland are creating specialized demand for elevated, lightweight array configurations.
Utility applications dominate current procurement volumes; agrivoltaic configurations within industrial are climbing the fastest as land-use constraints intensify.
Technology:
Technology maturity separates established thin-film production lines from emerging perovskite architectures requiring specialized barrier specifications.
- CdTe:Cadmium telluride deposition achieves lowest manufacturing cost per watt among commercial thin-film technologies. First Solar's vertically integrated manufacturing in Ohio and Malaysia controls semiconductor and encapsulant quality through captive production.
- CIGS:Copper indium gallium selenide offers higher conversion efficiency than CdTe with flexible substrate compatibility. Japanese and South Korean manufacturers are qualifying CIGS for building-integrated applications requiring curvature tolerance.
- Perovskite:Hybrid organic-inorganic active layers promise tandem cell efficiencies exceeding single-junction limits. Moisture sensitivity and ion migration barriers remain unresolved, delaying commercial encapsulant qualification.
- Organic:Solution-processed photovoltaic films target niche applications in portable and indoor energy harvesting. Limited efficiency and stability constrain deployment to consumer electronics and IoT sensor markets.
CdTe maintains the steepest production scale; perovskite-silicon tandems represent the most watched expansion trajectory pending stability certification.
End User:
Customer type determines procurement sophistication, with energy providers and OEMs driving specification standardization while developers and installers focus on installation economics.
- Developers:Project finance requirements mandate encapsulant traceability and 25-year performance warranties. Indian developers in Rajasthan and Gujarat are qualifying domestic film suppliers under PLI scheme domestic-content thresholds.
- OEMs:Module manufacturers specify encapsulant formulations during cell integration, controlling quality through backward integration into resin production. Hanwha Qcells leverages Korean and Malaysian integrated capacity to manage encapsulant specifications.
- Installers:Field deployment teams prioritize rapid installation and compatibility with existing mounting systems. Residential and commercial rooftop specialists in Southeast Asia are scaling training programs for polymer film handling.
- Energy Providers:Utility-scale power purchasers specify performance-guaranteed supply contracts rather than spot market procurement. European energy majors are qualifying fluorine-free backsheet alternatives ahead of F-Gas Regulation compliance deadlines.
OEMs control the largest specification influence today; energy providers are consolidating procurement authority fastest through long-term offtake structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ohio's cadmium telluride manufacturing corridor anchors North American thin-film production capacity. Module assembly clusters in Gujarat and Rajasthan are reshaping procurement patterns under India's PLI scheme. European reformulation cycles are accelerating ahead of F-Gas Regulation compliance deadlines.
United States
Utility-scale developers in Texas and California are consolidating procurement around domestic-content qualified suppliers. The Inflation Reduction Act's manufacturing tax credits are incentivizing resin-to-film capacity investments in Ohio and the Southeast. First Solar's Perrysburg operations anchor captive cadmium telluride semiconductor deposition for utility-scale deployment.
India
Rajasthan and Gujarat solar parks are driving demand for ethylene-vinyl acetate and polyolefin encapsulant formulations. The PLI scheme's domestic-content rules are accelerating local compounding capacity in Mundra and Chennai. BIS certification mandates are reshaping supplier qualification criteria for film vendors targeting project developers.
Germany
Building-integrated photovoltaic installations across commercial facades are sustaining polyvinyl butyral interlayer demand. REACH authorization requirements are imposing reformulation costs on backsheet suppliers targeting European module assemblers. Saxony-Anhalt's chemical corridor hosts fluorine-free barrier film development for 2025 compliance deadlines.
Japan
Copper indium gallium selenide manufacturers are qualifying flexible substrates for architectural curvature applications. METI's renewable energy targets are sustaining R&D investment in next-generation tandem cell architectures. Kyushu's industrial base concentrates CIGS production for building-integrated and residential segments.
South Korea
Hanwha Qcells leverages integrated cell-and-module capacity across Gumi and Malaysia to control encapsulant specifications. The country's petrochemical hub supplies ethylene-vinyl acetate resin to regional film compounders. Domestic module manufacturers are backward-integrating into resin production to secure supply chains against feedstock volatility.
Solar Cell Films Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue perovskite-silicon tandem architectures and fluorine-free backsheet reformulations. The market structure concentrates around resin-to-film integrated chemical conglomerates and captive semiconductor manufacturers. Three strategic archetypes dominate: backward-integrated petrochemical suppliers, thin-film module makers with captive deposition capacity, and specialized interlayer formulators for architectural applications. Competitive moves center on five-year offtake contracting and qualification of polyolefin alternatives to conventional encapsulants.
Among North American thin-film specialists, First Solar exemplifies captive semiconductor manufacturing with integrated cadmium telluride deposition. Hanwha Qcells represents the integrated cell-and-module archetype across Korean and Malaysian manufacturing bases. Kuraray Co., Ltd occupies the specialized interlayer position for building-integrated photovoltaic glass laminates.
| Leading Market Players |
|---|
| First Solar |
| KANEKA CORPORATION |
| 3M |
| JA Solar Technology Co., Ltd. |
| Ascent Solar Technologies, Inc. |
| Hanwha Qcells |
| SHARP CORPORATION |
| Oxford Photovoltaics Ltd. |
| Kuraray Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Captive resin-to-film integration anchors supply positioning and pricing power for module manufacturers seeking insulation from petrochemical volatility. This structural choice concentrates margin capture among backward-integrated chemical conglomerates while compressing returns for merchant compounders exposed to ethylene-vinyl acetate allocation risk.
Pricing Analysis
Ethylene-vinyl acetate resin pass-through dominates pricing mechanics, with three Asian petrochemical hubs controlling feedstock supply. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in standard-grade formulations is intensifying because Indian PLI scheme domestic-content rules are forcing price competition among local compounders. Utility-scale developers exhibit lowest price sensitivity due to long-term power purchase agreement structures, while residential installers face acute margin pressure.
Supply Chain Analysis
Ethylene-vinyl acetate resin supply rests on South Korean, Saudi, and Singaporean petrochemical complexes. Polyolefin elastomer formulations and fluorine-free backsheet alternatives draw from German and Japanese specialty chemical producers. Single-source vulnerability concentrates in high-purity EVA copolymer grades required for optical clarity. Distribution runs through resin-integrated film compounders direct to module OEMs, bypassing merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phasedown deadlines are forcing immediate backsheet reformulation investment and opening substitution windows for polyolefin alternatives.
For Market Incumbents: Anticipate accelerated fluorine-free qualification cycles by securing BIS certification for Indian PLI scheme eligibility ahead of competitor entry. Prioritize captive ethylene-vinyl acetate compounding capacity in Gujarat or Tamil Nadu to defend margin position against resin price volatility. Lock five-year offtake agreements with Rajasthan and Gujarat utility developers before domestic-content thresholds tighten supplier pools. For New Entrants and Emerging Players: Launch via specialized barrier film supply for perovskite-silicon tandem architectures requiring water vapor transmission rates below 0.01 g/m²/day. Target agrivoltaic deployment configurations in Southeast Asian markets where lightweight polymer encapsulant specifications remain underspecified. Pursue direct qualification with European module assemblers racing to meet F-Gas Regulation compliance deadlines. For Investors and Strategic Acquirers: Roll-up economics work for regional film compounders because domestic-content rules in India and US Inflation Reduction Act incentives are fragmenting supply qualification across jurisdictional lines. Five-to-ten year viability favors resin-integrated operations with established IEC 61215 certification histories. Watch perovskite stability certification protocol finalization as the inflection signal for premium encapsulant tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive EVA supply secures margin capture against petrochemical allocation risk from Korean hubs. |
| Fluorine-Free Backsheet Qualification | Polyolefin barrier films with aluminum oxide coatings satisfy EU F-Gas Regulation ahead of customs deadlines. |
| Domestic Content Certification Investment | BIS and PLI scheme alignment unlocks procurement from Indian utility developers in Rajasthan solar parks. |
| Perovskite Barrier Film Development | Specialized encapsulants with ultra-low moisture transmission target tandem cell commercialization timelines. |
| Long-Term Offtake Contracting | Five-year supply agreements with resin-integrated suppliers satisfy project finance covenants for gigawatt-scale deployment. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured formulation chemists at encapsulant compounders, procurement leads at module OEMs, project finance officers at Indian utility developers, and regulatory affairs specialists tracking EU F-Gas and REACH evolution. Secondary validation drew from IEC certification databases, BIS registration filings, SEC 10-K disclosures from listed petrochemical suppliers, and EU regulatory impact assessments. Bottom-up resin demand modeling and top-down module production forecasts were triangulated against trade flow data.
Segment-weighting approaches distributed value across polymer film type, thin-film technology maturity, and application scale tier. The analytical framework modeled film procurement patterns across the projection horizon by integration context, regulatory jurisdiction, and end-user sophistication. CAGRs were derived from compounding annual shipment trajectories adjusted for capacity utilization rates and qualification timeline delays. Key inputs included ethylene-vinyl acetate resin pricing indices and domestic-content threshold implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under perovskite commercialization acceleration or abrupt REACH authorization scope expansion. Forecasts reflect documented assumptions regarding IEC 61215 certification timeline stability and PLI scheme continuity. A small set of named triggers warrants ongoing watch: perovskite stability protocol finalization, EVA feedstock allocation disruptions, and F-Gas Regulation enforcement intensity at European customs points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
GCC Solar Microinverter Market