
 Gas Water Heater Market | 2026-2036
Gas Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Water Heater Market Analysis
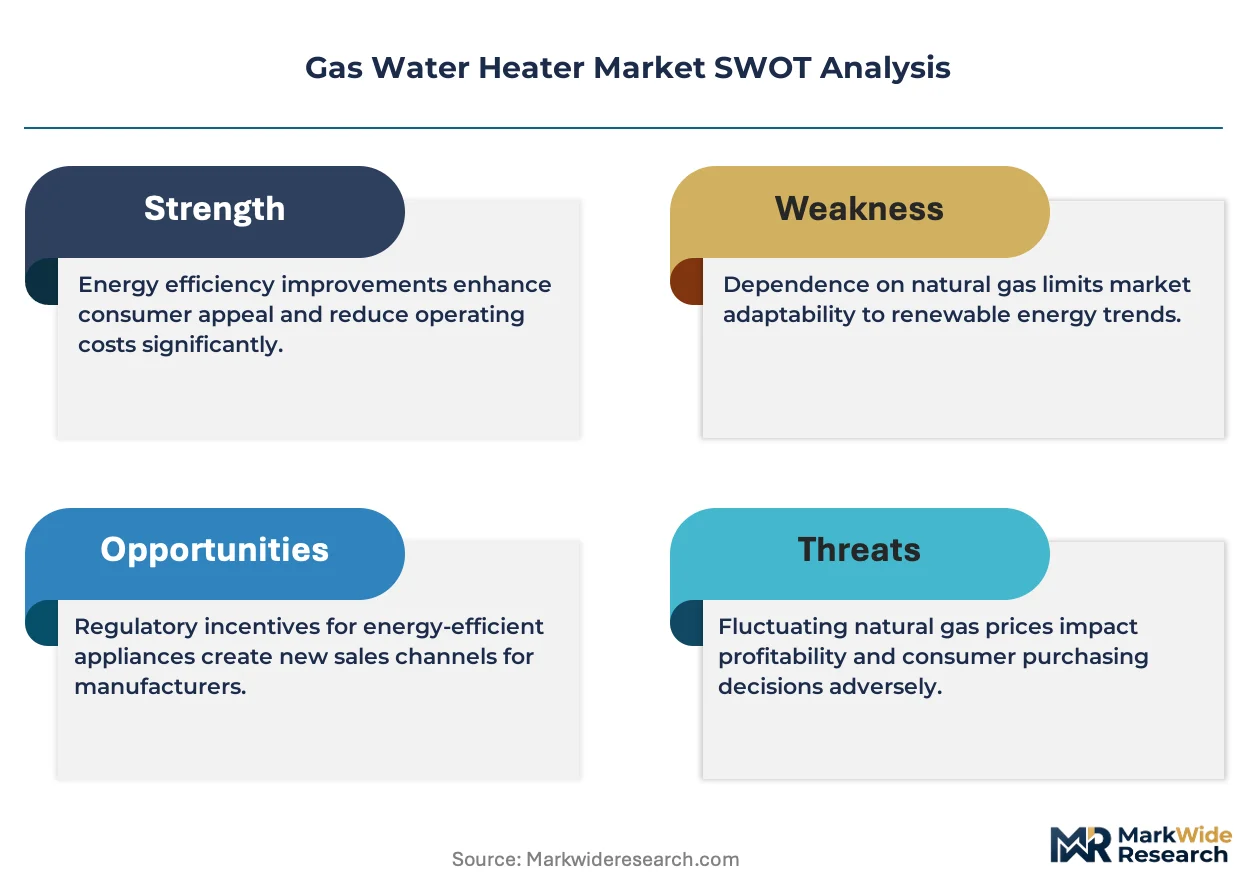
Project finance and green leasing structures for building energy retrofits is reshaping competitive access across the gas water heater value chain. Rinnai Corp. leverages its tankless manufacturing scale to capture premium commercial installations. A. O. Smith Corporation anchors North American distribution through contractor channel control. Bosch Thermotechnology competes on condensing technology leadership in European specification markets.
Gas water heaters are pressurized vessels that combust natural gas, propane, or biogas to heat potable water via submerged heat exchangers or direct-fired tubes, operating at thermal efficiencies between 80% and 98% depending on condensing architecture. These systems serve residential, commercial, and industrial facilities requiring continuous or peak hot water delivery. Tankless configurations now lead value generation due to higher unit economics and installation premiums, while condensing variants represent the fastest-growing technology segment as efficiency regulations tighten across multiple jurisdictions. Storage tanks remain the volume base in retrofit markets where infrastructure compatibility constrains instantaneous system adoption.
EPA rules under the Clean Air Act limit NOx emissions from residential gas appliances, while DOE minimum efficiency standards mandate uniform energy factor thresholds that reshape product development budgets. ISO 9001 quality certification and ASME pressure vessel codes govern market access for imported units in developed economies. Stakeholders must monitor hydrogen-blend gas infrastructure trials, as fuel composition shifts will determine burner design compatibility and warranty exposure across installed bases.
Market Dynamics
The EPA's tightening NOx emission thresholds under the Clean Air Act are forcing manufacturers to redesign burner architectures and catalytic systems, compressing margins while accelerating condensing technology adoption across residential and commercial segments.
Growth Catalysts
- Condensing Technology Mandates:DOE minimum efficiency standards are mandating uniform energy factor thresholds that elevate condensing gas water heater penetration in new construction and replacement cycles.
- Southeast Asia Urbanization:Residential construction acceleration across Vietnam's urban corridor from Ho Chi Minh City to Da Nang is concentrating tankless unit procurement among high-rise developers.
- Hydrogen-Blend Infrastructure Trials:Utility-led hydrogen injection pilots in European and Asia-Pacific markets are creating demand for burner retrofits compatible with variable fuel composition.
Market Restraints
- Copper and Stainless Steel Volatility:Heat exchanger material costs fluctuate with commodity markets, pressuring manufacturing margins on tankless units where metal intensity runs highest.
- Installation Skill Concentration:Certified technician availability clusters in metropolitan markets, constraining rural and secondary city penetration where gas line infrastructure already exists.
- Electric Heat Pump Substitution:Cold-climate heat pump water heaters are capturing share in jurisdictions with aggressive electrification mandates and carbon pricing mechanisms.
Strategic Opportunities
- Green Leasing Structures:Project finance vehicles for building energy retrofits are opening specification access for premium condensing systems in commercial real estate portfolios.
- Biogas Compatibility:Landfill and agricultural digester gas networks in Germany and the Netherlands create addressable markets for modified burner systems with widened fuel tolerance.
- Service Contract Unbundling:Aftermarket maintenance and predictive monitoring subscriptions represent recurring revenue expansion beyond one-time equipment sales in institutional buyer segments.
Industry Challenges
- ASME Pressure Vessel Certification Timelines:Third-party validation for imported units creates 4-6 month market entry delays, favoring domestic manufacturers with established code compliance pathways.
- Legacy Venting Infrastructure Mismatch:Existing flue configurations in replacement markets often require costly modifications to accommodate condensing unit sidewall venting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Water Heater Market |
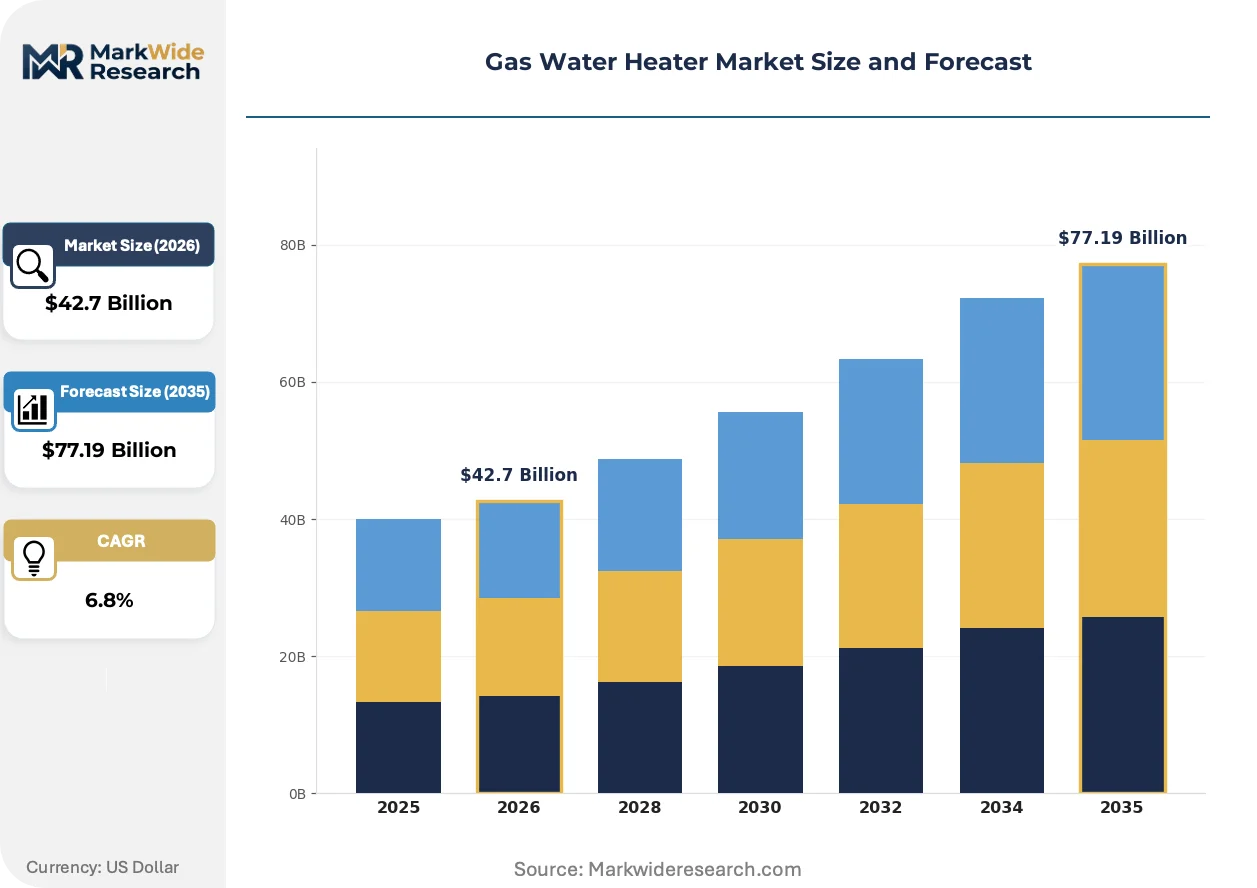
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage, Point-of-Use, Condensing Installation Type: Indoor, Outdoor, Semi-Outdoor, Wall-Mounted Fuel Type: Natural Gas, Propane, Butane, Biogas End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Rinnai Corp., Noritz Corporation, A. O. Smith Corporation, State Water Heaters, Bosch Thermotechnology, Rheem Manufacturing, Navien Inc., Ruud, Bradford White, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Water Heater Market Emerging Trajectories
Connected diagnostics and predictive maintenance capabilities are digitizing equipment lifecycle management, while regulatory pressure on combustion emissions accelerates hardware architecture shifts. These forces are compressing product development cycles and reshaping channel economics.
Smart valve and sensor networks embedded in tankless systems enable real-time flow optimization and fault detection. Multi-family housing developers in Japan and South Korea are specifying these configurations for centralized hot water plants. The technology stack is digitizing service dispatch and warranty claim processing, compressing response times from days to hours.
The EPA's Clean Air Act NOx regulations are tightening emission thresholds for residential gas-fired appliances. Manufacturers must redesign burner heads and add catalytic reduction stages, adding cost but creating specification advantage for early compliant portfolios. The commercial segment faces the steepest compliance burden as continuous-duty cycles amplify emission exposure.
Energy-as-a-service contracting is displacing capital purchase models in hospitality and healthcare verticals. Facility operators in Vietnam and Thailand are adopting fixed-rate hot water agreements that bundle equipment, maintenance, and fuel management. This restructuring concentrates buying authority with energy service companies and away from traditional mechanical contractors.
Gas Water Heater Market Segmentation
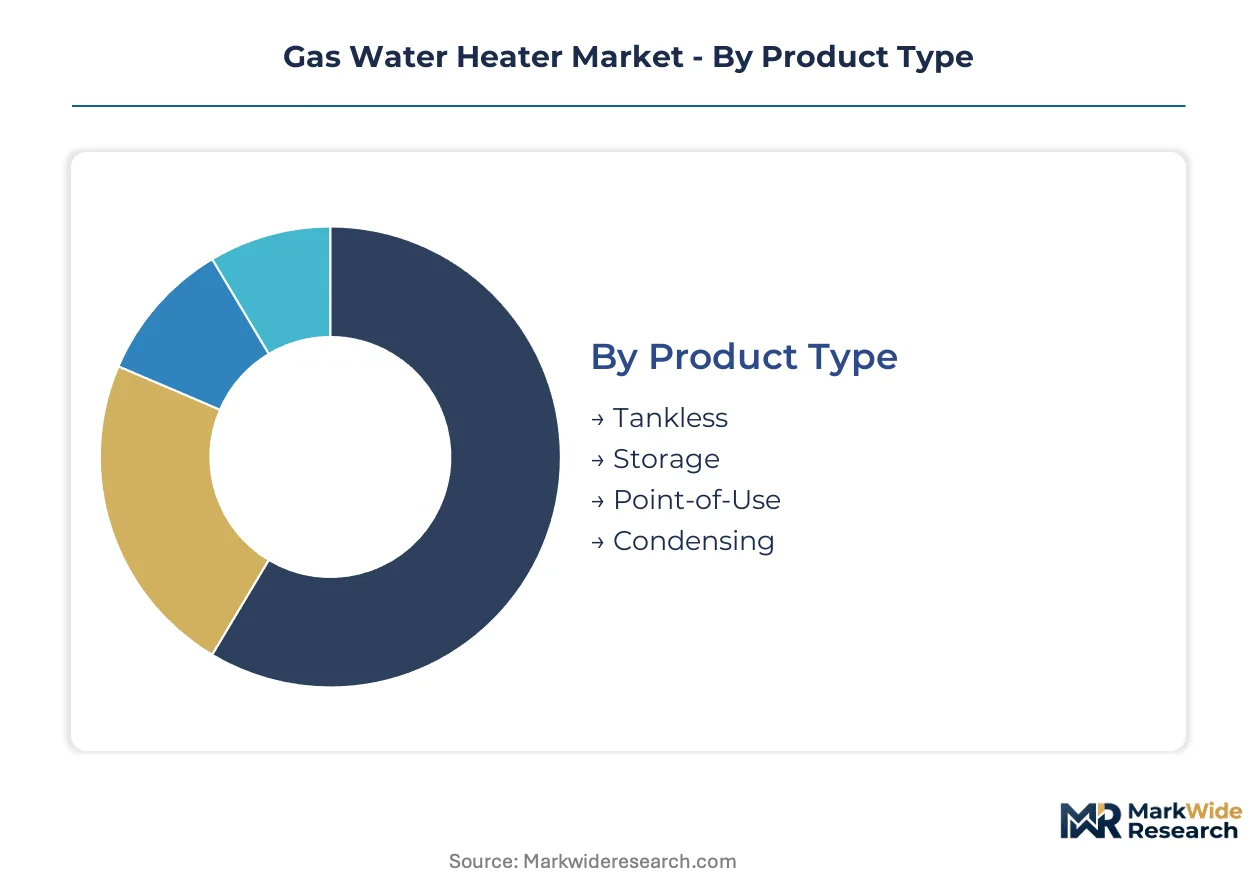
Gas water heater segmentation reveals how thermal efficiency mandates, fuel infrastructure availability, and installation constraints fragment procurement patterns across building types and geographies. Understanding these divisions exposes where technology transitions concentrate and where legacy architectures retain defensive positions.
Product Type:
Mature storage architectures coexist with emerging tankless configurations as efficiency regulations force hardware evolution across residential and commercial applications.
- Tankless:Instantaneous heating via high-BTU burners and compact heat exchangers eliminates standby thermal losses. Demand clusters in Vietnam's high-rise residential corridor from Ho Chi Minh City to Da Nang, where developers prioritize space optimization and continuous-flow capacity for multi-unit buildings. Installation premiums and gas line upgrades constrain retrofit adoption.
- Condensing:Secondary heat exchangers extract latent energy from exhaust gases, pushing thermal efficiency toward 98% while requiring corrosion-resistant materials. EPA Clean Air Act NOx thresholds are accelerating specification in new US construction and replacement cycles where venting modifications prove feasible. The technology commands price premiums that compress payback periods in high-utilization commercial settings.
- Storage:Insulated tanks with submerged burners dominate replacement markets where infrastructure compatibility limits instantaneous system adoption.
- Point-of-Use:Compact units serve isolated fixtures in commercial kitchens and remote facility wings with minimal hot water demand.
Storage handles the majority of throughput; condensing is climbing the fastest on specification share.
Installation Type:
Cost tier separation between infrastructure-light outdoor configurations and climate-controlled indoor systems shapes regional penetration patterns.
- Indoor:Sealed combustion chambers with dedicated air intake and power-vented exhaust suit cold-climate markets and strict building envelope standards. Demand concentrates in northern US states and European markets where freeze protection and emissions containment drive code requirements. Installation complexity elevates contractor dependency and extends project timelines.
- Outdoor:Weatherized housings eliminate venting costs and free interior floor space, suiting mild-climate Southeast Asian markets and utility-adjacent commercial installations. Thailand and Vietnam developers specify these for centralized hot water plants in hospitality portfolios where equipment accessibility simplifies maintenance.
- Semi-Outdoor:Partial enclosures balance weather protection with ventilation in transitional climate zones and covered mechanical areas.
- Wall-Mounted:Vertical orientation maximizes footprint efficiency in dense urban construction and compact mechanical rooms.
Outdoor systems dominate volume in warm-climate geographies; indoor configurations retain premium positioning in regulated northern markets.
Fuel Type:
Customer type stratification separates utility-connected residential bases from distributed fuel users in rural and off-grid commercial applications.
- Natural Gas:Pipeline distribution enables lowest operating costs and highest burner efficiency in connected urban corridors. Germany and the Netherlands utility-led hydrogen injection pilots are creating demand for retrofitted burner compatibility as fuel composition shifts. Infrastructure availability gates market access—rural and secondary city penetration lags where line extension economics fail.
- Biogas:Landfill and agricultural digester methane requires widened fuel tolerance and corrosion-resistant components. Addressable markets concentrate in German and Dutch circular economy zones where waste-to-energy networks achieve scale. Modified burner systems capture carbon-negative positioning for sustainability-mandated institutional buyers.
- Propane:Tank storage serves rural residential and commercial properties beyond natural gas grid boundaries.
- Butane:Portable cylinder supply dominates Southeast Asian residential markets with limited pipeline infrastructure.
Natural gas commands the installed base; biogas is expanding most quickly in European sustainability-driven procurement.
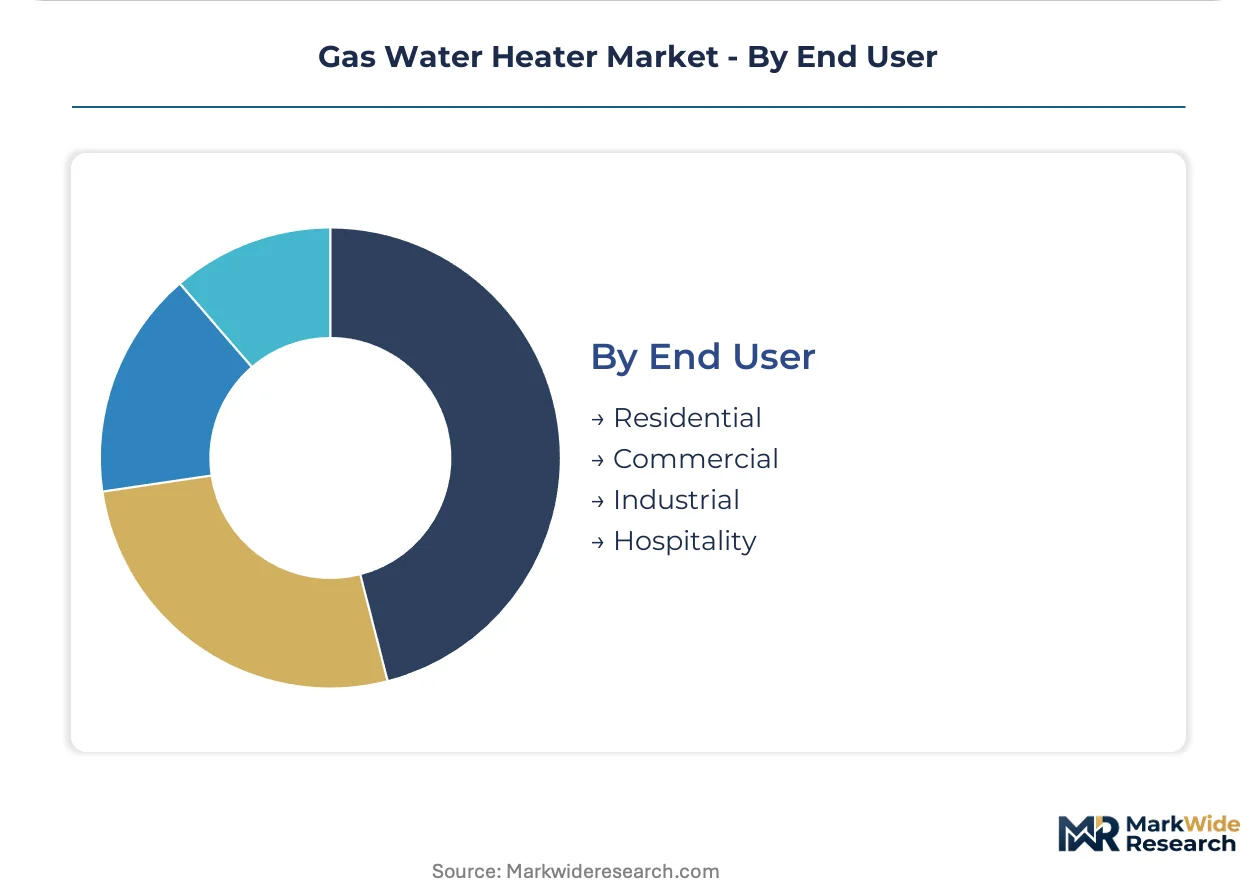
End User:
Application-driven specification separates continuous-duty commercial requirements from intermittent residential demand patterns.
- Residential:Single-family and multi-family installations prioritize first-hour recovery rates and footprint minimization. Tankless configurations gain share in new Southeast Asian high-rise construction while storage tanks defend retrofit markets. Energy-as-a-service contracting is displacing capital purchases in Vietnam and Thailand through fixed-rate hot water agreements.
- Hospitality:Hotels and resorts require redundant capacity and 24/7 reliability with minimal downtime tolerance. Centralized plants in Japan and South Korea specify smart valve networks for predictive maintenance and rapid fault response. Procurement authority is shifting from mechanical contractors to energy service companies under bundled service structures.
- Commercial:Office buildings and retail facilities balance capital constraints with efficiency compliance.
- Industrial:Process heating and wash-down applications demand heavy-duty construction and high recovery rates.
Residential absorbs the highest unit volume; hospitality is gaining share fastest through service-contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-rise developers in Vietnam and Thailand drive tankless procurement through energy-as-a-service contracts. Commercial hospitality operators in Japan specify smart valve networks for predictive maintenance. German utilities test hydrogen-blend compatibility in burner retrofits.
United States
EPA Clean Air Act NOx thresholds force condensing technology adoption in residential replacement cycles. DOE minimum efficiency standards mandate uniform energy factor compliance across new construction. Demand clusters in northern states where sealed combustion indoor systems meet strict building envelope codes.
Germany
Utility-led hydrogen injection pilots create demand for widened fuel tolerance in burner architectures. REACH compliance and CE marking govern imported unit market access. The Rhine-Ruhr corridor concentrates biogas-compatible system specification for institutional sustainability mandates.
Vietnam
Residential construction acceleration along the Ho Chi Minh City to Da Nang urban corridor concentrates tankless unit procurement. Energy-as-a-service contracting displaces capital purchases among high-rise developers. Outdoor weatherized configurations dominate hospitality portfolio installations for maintenance accessibility.
Japan
Multi-family housing developers specify smart valve and sensor networks for centralized hot water plants. METI efficiency guidelines shape product development budgets for connected diagnostics integration. The Kanto region anchors specification demand for predictive maintenance capabilities in commercial facilities.
Netherlands
Agricultural digester gas networks create addressable markets for modified burner systems with corrosion-resistant components. Circular economy zones drive biogas-compatible procurement among carbon-negative positioning buyers. Randstad urban construction favors compact wall-mounted configurations for space optimization.
Gas Water Heater Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. The vendor base separates into contractor-dependent incumbents, specification-driven technology leaders, and scale-focused tankless manufacturers. Three archetypes dominate: North American distribution anchors, Asian manufacturing specialists, and European condensing technology developers. Competitive moves concentrate on M&A for regional channel access and strategic partnerships for hydrogen-blend burner compatibility.
Among Japanese manufacturing specialists, Rinnai Corp. and Noritz Corporation occupy positions exemplifying tankless scale advantages. A. O. Smith Corporation anchors North American contractor channel control. Bosch Thermotechnology represents European condensing technology leadership in specification-driven markets. These three sit within distinct competitive vectors—manufacturing scale, distribution depth, and technology differentiation—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Rinnai Corp. |
| Noritz Corporation |
| A. O. Smith Corporation |
| State Water Heaters |
| Bosch Thermotechnology |
| Rheem Manufacturing |
| Navien Inc. |
| Ruud |
| Bradford White |
| Others |
Supply Flow & Price Mechanics
China's concentration in stainless steel and copper heat exchanger manufacturing anchors cost structures for tankless units, pushing margin pools toward burner technology specialists and certification-holding assemblers in Japan and Germany who capture value through EPA and CE compliance premiums.
Pricing Analysis
Certification level creates the primary spread across the value chain, with ASME pressure vessel and ISO 9001 compliance commanding substantial premiums over non-certified imports. Three-tier pricing structure separates condensing systems with catalytic reduction from standard efficiency units and basic storage configurations. Cost compression in the standard tier is intensifying because copper and stainless steel commodity volatility transfers directly to heat exchanger costs. Residential retrofit buyers exhibit highest price sensitivity due to infrastructure upgrade burdens, while hospitality energy-as-a-service contracts show lowest sensitivity through bundled fuel and maintenance structures.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for heat exchanger sourcing. Manufacturing draws from China for metal fabrication, Japan for precision burner components, and Germany for condensing system engineering. Raw material dependencies center on copper coil stock, stainless steel sheet, and catalytic reduction substrates. Distribution runs through contractor channels in North America, specification engineers in Europe, and energy service companies in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas water heater market is entering a cyclical recovery phase as residential construction rebounds across Vietnam's urban corridor and EPA-mandated replacement cycles accelerate in the United States.
For Market Incumbents: Build certification moats around ASME and EPA NOx compliance to defend against low-cost Asian imports. Deepen backward integration into heat exchanger manufacturing to offset copper volatility exposure. Anchor contractor channel control in North American replacement markets where installation skill concentration creates switching costs. Prioritize hydrogen-blend burner R&D to capture European utility pilot programs before compatibility standards harden. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, particularly centralized hot water plants in Thailand hospitality portfolios where energy-as-a-service contracting is displacing traditional procurement. Biogas-compatible burner retrofits in German and Dutch circular economy zones offer second-mover advantage with lower certification barriers than natural gas baseline systems. Partner with local energy service companies rather than mechanical contractors to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European condensing technology developers holding REACH compliance portfolios but lacking Asia-Pacific manufacturing scale. Long-term viability hinges on hydrogen infrastructure transition timing and electrification mandate intensity across core markets. Monitor German and Dutch hydrogen injection pilot conversion rates as the critical signal for burner retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Blend Burner Retrofit Program | Positions manufacturers for German and Dutch utility pilot conversions before compatibility standards lock in. |
| Energy-as-a-Service Contracting Expansion | Captures recurring revenue from Vietnam and Thailand hospitality developers shifting from capital purchases. |
| Condensing Technology Licensing | Monetizes EPA NOx compliance IP for North American manufacturers facing compressed development timelines. |
| Biogas Compatibility Certification | Unlocks German and Dutch institutional procurement mandating carbon-negative fuel sourcing. |
| Predictive Maintenance Platform Integration | Enables Japanese and South Korean multi-family developers to specify smart valve networks for fault response. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including plant engineers at tankless manufacturing facilities, HVAC contractors in the United States and Vietnam, energy service company procurement directors, and regulatory compliance officers at import certification bodies. Secondary validation drew from EPA Clean Air Act filings, DOE efficiency standard notices, ASME pressure vessel code updates, and customs trade data for heat exchanger component flows. Bottom-up unit shipment estimates from country-level construction permits were triangulated against top-down manufacturer revenue disclosures.
Calibration against historical efficiency mandate adoption curves and commodity price cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, installation configuration, fuel compatibility, and end-use application intensity. CAGRs were derived from regression analysis of regulatory phase-in schedules and replacement cycle elasticity. Industry-specific inputs incorporated hydrogen infrastructure trial timelines and Southeast Asian high-rise construction permit trajectories.
Practitioners should monitor EPA NOx threshold enforcement intensity and German hydrogen injection pilot conversion rates for early signals of technology transition acceleration. Forecasts reflect assumptions around regulatory compliance timelines and commodity price stabilization that could shift with trade policy changes or electrification mandate expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Copper Ground Rod Market