
 Biohybrid Solar Cell Market | 2026-2036
Biohybrid Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Biohybrid Solar Cell Market Insights
Germany is narrowing its focus on applied photovoltaics research through Fraunhofer ISE and Helmholtz-Zentrum Berlin, creating a dense corridor of biohybrid cell development. Greatcell leverages its perovskite specialization to anchor European supply chains for next-generation photovoltaics. Merck KGaA sustains its position through advanced materials and chemical precursors for dye-sensitized architectures. Oxford PV competes on tandem cell efficiency, translating laboratory breakthroughs toward manufacturable formats.
Biohybrid solar cells integrate biological photosynthetic components—such as reaction center proteins or light-harvesting complexes—with synthetic semiconductors, typically achieving power conversion efficiencies between one and four percent in operational prototypes while offering tunable absorption across visible spectra. The primary industrial purpose centers on enabling energy harvesting in form-factor-constrained environments where silicon rigidity fails. Dye-sensitized solar cells occupy the most mature segment, with established manufacturing protocols and lower capital barriers to entry. Perovskite cells represent the fastest-growing technology category, though stability and lead-content concerns concentrate margin pools in encapsulation and barrier-layer suppliers. Building-integrated photovoltaics sits as the highest-value application channel, commanding premium positioning through architectural dual-function requirements.
Europe's ECHA enforces REACH compliance on organic photovoltaic materials, restricting certain solvents and heavy-metal precursors while the EU Green Deal mandates circularity provisions for solar panel end-of-life management. The EU AI Act indirectly shapes automated manufacturing inspection protocols for quality assurance in thin-film deposition. Japan's METI maintains JIS standards for photovoltaic reliability testing, creating a secondary compliance threshold for export-oriented producers. Stakeholders must monitor how evolving material restrictions intersect with scale-up timelines for biological component integration.
Market Dynamics
Biological component integration with synthetic semiconductors is compressing development timelines while forcing manufacturers to navigate novel material compliance frameworks that lack precedent in conventional photovoltaics.
Growth Catalysts
- Wearable technology demand:Form-factor-constrained devices in medical monitoring and fitness tracking require flexible power solutions that silicon cannot deliver.
- EU Green Deal circularity mandates:End-of-life management provisions for solar panels are accelerating investment in biodegradable and recoverable biohybrid architectures.
- Perovskite stability advances:Encapsulation breakthroughs are extending operational lifespans sufficiently to attract commercial manufacturing interest.
Market Restraints
- Reaction center protein supply concentration:Isolation and purification capabilities cluster within specialized biotechnology facilities in Germany and the Netherlands.
- REACH solvent restrictions:ECHA limitations on organic photovoltaic processing chemicals constrain formulation flexibility and increase compliance overhead.
- Solid-state silicon substitution:Thin-film alternatives and emerging tandem architectures compete for building-integrated and portable power applications.
Strategic Opportunities
- Building-integrated photovoltaics premium channel:Architectural dual-function requirements in commercial construction reward aesthetic and form-factor flexibility over raw efficiency.
- Japan METI reliability standards:JIS certification alignment creates export pathway for European and North American manufacturers targeting Japanese industrial buyers.
- Photosynthetic protein-synthetic semiconductor convergence:Hybrid architectures combining reaction centers with perovskite absorbers enable spectral tuning unavailable to either technology alone.
Industry Challenges
- Biophotonic engineering talent scarcity:Cross-disciplinary expertise spanning molecular biology, semiconductor physics, and thin-film manufacturing concentrates in Fraunhofer-adjacent research clusters.
- Encapsulation capex intensity:Barrier-layer deposition equipment for moisture-sensitive biological components demands specialized capital allocation beyond conventional photovoltaic tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biohybrid Solar Cell Market |
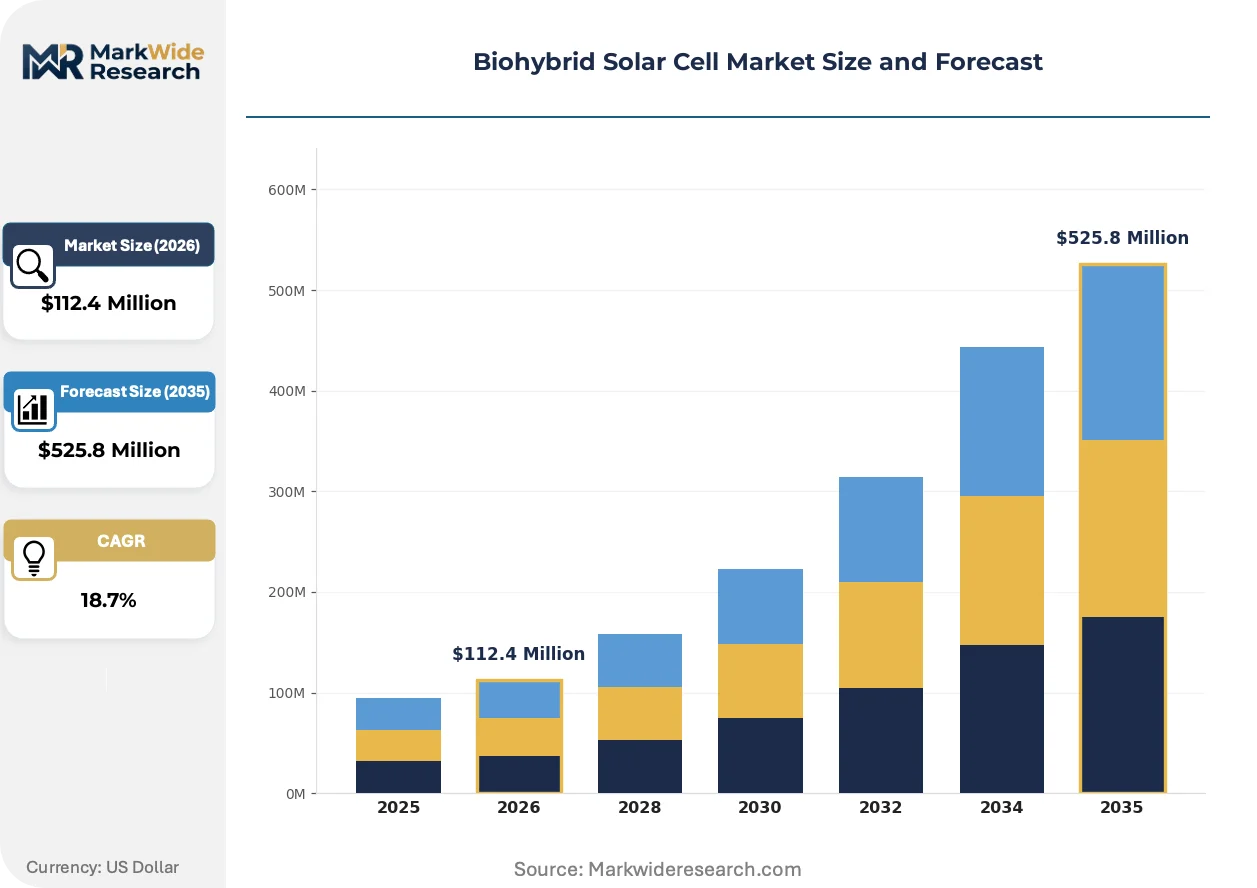
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $525.8 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Photovoltaics, Dye-Sensitized Solar Cells, Perovskite Cells, Hybrid Organic-Inorganic Cells Technology: Thin-Film Technology, Multi-Junction Technology, Concentrated Solar Power, Nanostructured Technology End User: Residential, Commercial, Industrial, Agricultural Application: Power Generation, Building-Integrated Photovoltaics, Wearable Technology, Portable Electronics |
| Companies Covered | Greatcell, Exeger Operations AB, Solaronix SA, Oxford PV, G24 Power Ltd., Merck KGaA, Peccell Technologies, Inc., Sharp Corporation, First Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biohybrid Solar Cell Market Trends and Innovations
Computational design tools are compressing protein engineering cycles while regulatory frameworks mature around novel biological-material interfaces, and buyer expectations shift toward embedded energy harvesting in everyday objects.
Protein engineering platforms are digitizing the optimization of reaction center variants for specific spectral environments. Synthetic biology startups and materials science divisions within industrial conglomerates are adopting these tools at twelve-to-eighteen-month refresh cycles. This capability is digitizing what previously required exhaustive laboratory screening, collapsing development timelines from years to months.
REACH authorization requirements for novel chemical substances are tightening pre-market scrutiny for organic photovoltaic precursors. ECHA's evolving substance evaluation protocols are extending registration timelines for dye-sensitized cell electrolytes and perovskite additives. European manufacturers are responding by front-loading toxicology and environmental fate studies, while non-EU exporters are establishing dedicated compliance subsidiaries in Germany and the Netherlands.
Specification-driven procurement is displacing commodity purchasing in building-integrated and wearable segments. Architects and product designers are issuing performance briefs that prioritize form-factor, weight, and aesthetic integration over standardized efficiency metrics. This pattern is most pronounced in German commercial construction and Japanese consumer electronics supply chains, where tier-one buyers now require vendor participation in early-stage design collaboration rather than late-stage component supply.
Biohybrid Solar Cell Market Segmentation
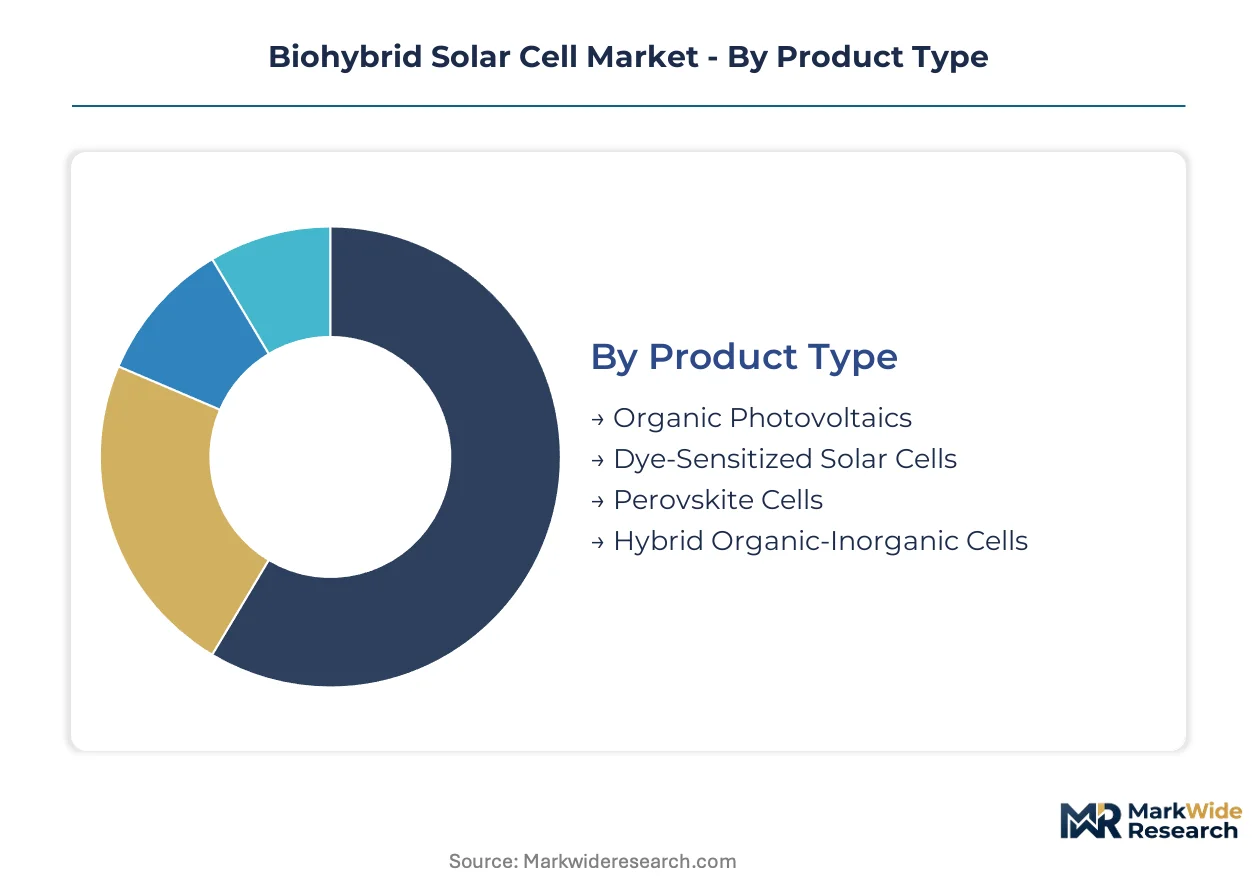
Biohybrid solar cell architectures diverge sharply across product chemistry, fabrication technology, and deployment environment. Each segmentation dimension carries distinct margin profiles, compliance burdens, and capital intensity requirements that reshape competitive positioning.
Product Type:
Cost tier stratification separates mature manufacturing platforms from emerging architectures demanding specialized equipment and material supply chains.
- Organic Photovoltaics:Carbon-based donor-acceptor heterojunctions enable solution-processed manufacturing at ambient temperatures. Demand concentrates in German building-integrated installations where REACH solvent restrictions favor aqueous processing routes over halogenated alternatives.
- Dye-Sensitized Solar Cells:Liquid electrolyte or solid-state hole-transport media combined with ruthenium or organic sensitizer dyes achieve operational stability exceeding a decade in commercial deployments. Japanese consumer electronics manufacturers specify these cells for indoor energy harvesting where silicon efficiency collapses under artificial illumination.
- Perovskite Cells:Metal halide absorber layers deliver the highest power conversion efficiencies among biohybrid architectures, though moisture sensitivity and lead-content concerns concentrate value capture in encapsulation specialists.
- Hybrid Organic-Inorganic Cells:Quantum dot or plasmonic nanostructure integration with organic semiconductors enables spectral tuning for agricultural greenhouse applications requiring selective wavelength transmission.
Dye-sensitized solar cells command the established base. The steepest expansion runs through perovskite cells.
Technology:
Application requirements dictate fabrication approach, with form-factor flexibility and spectral management driving technology selection across end-use segments.
- Thin-Film Technology:Vacuum deposition or solution coating of absorber layers onto flexible substrates enables roll-to-roll manufacturing at reduced capital intensity. Wearable technology buyers in Japan's medical device sector specify thin-film biohybrid cells for conformal integration with skin-contact sensors.
- Multi-Junction Technology:Stacked sub-cells with complementary absorption spectra maximize photon utilization, though lattice-matching constraints and complex interconnect fabrication limit deployment to concentrated solar installations and space-qualified applications.
- Concentrated Solar Power:Optical concentration ratios above 500x reduce absorber area requirements while demanding precise tracking systems and thermal management, restricting viable deployment to utility-scale installations in high-direct-normal-irradiance locations.
- Nanostructured Technology:Plasmonic or photonic crystal architectures manipulate light-matter interaction at sub-wavelength scales, enhancing absorption in ultrathin active layers for portable electronics weight-constrained designs.
Thin-film technology commands the established base. The steepest expansion runs through nanostructured technology.
End User:
Customer type determines performance specifications, procurement scale, and regulatory exposure across the value chain.
- Residential:Distributed rooftop and facade installations prioritize aesthetic integration and simplified permitting over maximum efficiency, with German homeowners driving demand for building-integrated systems under federal renovation subsidies.
- Commercial:Corporate procurement teams negotiate long-term power purchase agreements and sustainability certifications, with Japanese retail chains specifying biohybrid cells for storefront canopy applications combining shading with energy generation.
- Industrial:Process heat and on-site generation requirements favor durability and predictable output over conversion efficiency, limiting biohybrid penetration to auxiliary power and sensor networks.
- Agricultural:Greenhouse-integrated photovoltaics and livestock monitoring devices create demand for semi-transparent cells with tunable spectral transmission, with Dutch horticultural operations piloting organic photovoltaic canopies.
Commercial end users command the established base. The steepest expansion runs through agricultural deployments.
Application:
Deployment environment constrains form factor, encapsulation requirements, and power management architecture.
- Power Generation:Grid-connected or off-grid installations prioritize levelized cost of energy and operational lifespan, with German utility-scale pilots testing perovskite-silicon tandems under Fraunhofer ISE supervision.
- Building-Integrated Photovoltaics:Architectural dual-function requirements reward aesthetic flexibility and customized dimensions over standardized efficiency metrics, with German commercial construction specifications driving premium pricing.
- Wearable Technology:Medical monitoring and fitness tracking devices demand conformal, lightweight power sources with biocompatibility certification, with Japanese electronics conglomerates integrating dye-sensitized cells into wrist-worn health sensors.
- Portable Electronics:Consumer devices and industrial sensors require rapid charge cycles and mechanical durability under cyclic flexing, limiting biohybrid adoption to niche outdoor and emergency applications.
Power generation commands the established base. The steepest expansion runs through wearable technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European regulatory gravity for biohybrid solar cell materials, while Fraunhofer institutes concentrate applied research capabilities in Germany. Japanese METI standards create a secondary compliance threshold for export-oriented manufacturers. Chinese dual carbon goals accelerate domestic perovskite commercialization timelines.
Germany
Wearable medical sensors and building-integrated facade systems drive procurement from Munich-based device manufacturers. The EU Green Deal mandates circularity provisions for solar panel end-of-life management, compelling manufacturers to design recoverable biohybrid architectures. Fraunhofer ISE in Freiburg and Helmholtz-Zentrum Berlin anchor a dense corridor of reaction center protein integration research with industrial partners.
Japan
Consumer electronics conglomerates specify dye-sensitized cells for indoor energy harvesting in wrist-worn health monitors and IoT sensors. METI maintains JIS standards for photovoltaic reliability testing that European exporters must satisfy for market access. Osaka-based electronics supply chains integrate conformal thin-film biohybrid cells into skin-contact medical devices requiring biocompatibility certification.
United States
Research universities and national laboratories concentrate federal funding on photosynthetic protein-synthetic semiconductor convergence for space-constrained applications. EPA oversees chemical precursor registration under TSCA for organic photovoltaic materials entering commercial supply chains. Boston-Cambridge biotech clusters collaborate with Arizona-based concentrated solar pilot facilities on multi-junction architectures.
China
Domestic perovskite manufacturers scale barrier-layer deposition capacity to address moisture sensitivity in metal halide absorber layers. MIIT coordinates national standards development for emerging photovoltaic technologies under dual carbon neutrality targets. Yangtze River Delta industrial parks host integrated production lines combining synthetic biology facilities with thin-film semiconductor foundries.
Netherlands
Dutch horticultural operations pilot semi-transparent organic photovoltaic canopies for greenhouse-integrated spectral management. ECHA substance evaluation protocols extend registration timelines for novel electrolyte formulations, front-loading toxicology studies for Dutch manufacturers. Eindhoven's high-tech campus concentrates protein purification capabilities alongside ASML-adjacent precision coating equipment suppliers.
Biohybrid Solar Cell Market Competitive Landscape
Capability concentration sits with specialized research-intensive players; scale advantage sits with diversified materials conglomerates and established thin-film manufacturers. The competitive structure fragments across three tiers: Fraunhofer-adjacent biotechnology spinouts mastering reaction center isolation; chemical precursors suppliers controlling dye-sensitized electrolyte formulations; and tandem cell developers bridging laboratory efficiency records toward manufacturable formats. Dominant competitive moves include strategic partnerships between synthetic biology platforms and semiconductor foundries, plus geographic expansion through dedicated compliance subsidiaries in Germany and the Netherlands to satisfy REACH authorization requirements.
Within the research-commercialization bridge tier, Greatcell and Oxford PV exemplify divergent strategic positioning. Greatcell occupies a position representing European perovskite specialization anchored to supply chain security objectives. Oxford PV exemplifies the laboratory-to-fab translation archetype, occupying a position where tandem cell efficiency breakthroughs must negotiate manufacturable scale-up constraints. Merck KGaA, a German diversified chemicals AG, anchors the precursor materials tier through established positions in dye-sensitized and organic photovoltaic chemical supply. These three entities collectively illustrate how value capture distributes across reaction center biotechnology, metal halide absorber engineering, and formulation chemistry in biohybrid solar cell commercialization.
| Leading Market Players |
|---|
| Greatcell |
| Exeger Operations AB |
| Solaronix SA |
| Oxford PV |
| G24 Power Ltd. |
| Merck KGaA |
| Peccell Technologies, Inc. |
| Sharp Corporation |
| First Solar |
| Others |
Pricing and Supply Chain Analysis
Fraunhofer ISE's applied photovoltaics corridor in Freiburg concentrates reaction center protein isolation capabilities, compressing downstream pricing power for dye-sensitized cell manufacturers dependent on German biotechnology clusters. REACH solvent restrictions and ECHA authorization timelines further tighten formulation flexibility, forcing cost absorption through specialized compliance subsidiaries.
Pricing Analysis
Price spreads between German-manufactured biohybrid cells and Asian-imported alternatives reflect REACH compliance overhead and protein purification facility proximity. Three-tier pricing structure across premium, standard, and economy levels separates Fraunhofer-adjacent research-grade suppliers from volume-scale thin-film producers. Cost compression in standard-tier perovskite cells is intensifying because barrier-layer deposition equipment demands specialized capital allocation. Agricultural greenhouse operators in the Netherlands exhibit highest price sensitivity due to spectral-tuning customization requirements, while Japanese medical device manufacturers demonstrate lowest sensitivity given biocompatibility certification premiums.
Supply Chain Analysis
Upstream feedstock for photosynthetic proteins draws from biotechnology facilities concentrated in Germany, the Netherlands, and Japan. Metal halide precursors for perovskite absorbers rest on chemical suppliers in China and Germany, while ruthenium-based sensitizers hinge on South African and Russian mining operations. Single-source vulnerability concentrates in reaction center protein purification capabilities clustered around Eindhoven and Freiburg research parks. Distribution runs through semiconductor foundry partnerships for thin-film deposition, with final integration occurring at OEM facilities in Japan's Osaka electronics corridor and Germany's medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary expertise spanning molecular biology, semiconductor physics, and thin-film manufacturing concentrates in Fraunhofer-adjacent research clusters, creating persistent capability gaps for competitors lacking proximity to these ecosystems.
For Market Incumbents: Harden supply chain resilience through captive protein purification capacity in the Netherlands or backward integration into barrier-layer deposition equipment. Solid-state silicon tandem architectures threaten building-integrated market share, necessitating accelerated R&D in photosynthetic protein-perovskite convergence. Certification investment in JIS reliability standards opens Japanese medical device procurement channels. For New Entrants and Emerging Players: Mid-market commercial building-integrated installations in German secondary cities represent the most penetrable entry point, as federal renovation subsidies sustain demand without Fraunhofer research proximity requirements. Dutch agricultural greenhouse operations seeking spectral-tuning canopies offer second-tier opportunity with lower certification barriers. Go-to-market positioning should emphasize early-stage architect collaboration rather than component supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among encapsulation specialists serving moisture-sensitive perovskite architectures with long-term service agreements. Five-to-ten-year viability favors acquisition targets with established REACH authorization track records and existing JIS certification pathways. Monitor ECHA substance evaluation protocol expansions as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reaction Center Protein Supply Agreement | Long-term contracts with Fraunhofer-adjacent biotechnology spinouts secure isolation capacity ahead of competitor lock-up. |
| Barrier-Layer Deposition Capacity Buildout | In-house encapsulation equipment addresses perovskite moisture sensitivity while capturing margin pools from outsourced specialists. |
| JIS Reliability Certification Program | Japanese METI standards alignment enables export pathway to Osaka-based medical device and consumer electronics manufacturers. |
| Greenhouse-Integrated Photovoltaic Partnership | Collaboration with Dutch horticultural operations pilots semi-transparent organic photovoltaic canopies for spectral management. |
| REACH Authorization Subsidiary Establishment | Dedicated German or Dutch compliance entities front-load toxicology studies for dye-sensitized electrolyte market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance registration databases, Fraunhofer ISE technical publications, and METI JIS standard documentation. Primary interviews engaged thin-film manufacturing directors, biotechnology procurement leads at reaction center protein suppliers, regulatory affairs specialists navigating REACH authorization, and building-integrated photovoltaic specification architects. Secondary validation incorporated trade customs data for organic photovoltaic precursor chemicals, patent filings for perovskite encapsulation architectures, and hospital procurement databases for wearable medical sensor integrations. Bottom-up segment sizing triangulated against top-down market construction across product chemistry, fabrication technology, and deployment environment dimensions.
Forecast inputs considered technology maturation curves for protein-synthetic semiconductor integration, regulatory timeline probabilities for ECHA authorization expansions, and substitution elasticity from solid-state silicon alternatives. Segmentation modeling captured product type stratification, thin-film versus multi-junction fabrication approaches, end-user procurement scale differentials, and application-specific form-factor constraints. CAGRs derived from segment-level growth rate blending weighted by current revenue composition. Industry-specific inputs included perovskite stability improvement trajectories and EU Green Deal circularity mandate implementation schedules.
Practitioners should monitor ECHA substance evaluation protocol revisions, Japanese METI standard updates, and perovskite encapsulation breakthrough announcements for early signals of forecast deviation. Cross-checking against IEA photovoltaic technology roadmaps and Fraunhofer ISE annual technology reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Denmark Solar Energy Market