
 Solar PV Inverter Market | 2026-2036
Solar PV Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Inverter Market Intelligence
Utility-scale solar deployment is recalibrating inverter procurement priorities worldwide. Sungrow Power Supply Co., Ltd. leverages its manufacturing scale to dominate utility-scale string inverter supply across Asia-Pacific markets. SMA Solar Technology AG anchors European demand through specialized grid-tied central inverter platforms engineered for high-voltage transmission integration. Huawei Technologies Co., Ltd. competes aggressively on digital power electronics and smart PV management systems that reduce levelized cost of energy for large developers.
A solar PV inverter converts direct current generated by photovoltaic modules into alternating current synchronized with grid frequency and voltage parameters, typically operating at efficiency thresholds above 98% in modern silicon carbide-based designs. Its primary commercial purpose centers on enabling safe, code-compliant interconnection between solar arrays and electrical distribution infrastructure. String inverters occupy the dominant revenue position across residential and commercial installations due to favorable balance-of-system economics. Microinverters represent the fastest-expanding technology segment as module-level power electronics gain traction in rooftop applications where shading and orientation variability degrade centralized inverter performance. Utility-scale deployments sustain concentrated margin pools for central and hybrid inverter architectures capable of megawatt-scale output with integrated storage readiness.
Grid codes issued by FERC in the United States and CE marking requirements under EU directives mandate specific ride-through capabilities, harmonic limits, and reactive power support functions that determine market access for inverter suppliers. India's CEA technical standards for solar grid connectivity and China's GB standards for distributed PV interconnection impose additional certification burdens that filter participant eligibility. Stakeholders must monitor evolving storage-integration mandates and cybersecurity requirements for networked inverter fleets as distributed energy resource management systems proliferate.
Market Dynamics
Silicon carbide power semiconductors are compressing inverter form factors while tightening grid code mandates across Germany, India, and the United States force simultaneous upgrades to ride-through and reactive power capabilities. These dual pressures are restructuring supplier qualification criteria and procurement timelines for utility-scale developers.
Growth Catalysts
- CEA Technical Standards:India's Central Electricity Authority mandates stringent fault ride-through and voltage regulation requirements for solar grid connectivity, filtering inverter eligibility toward certified suppliers with proven utility-scale deployment records.
- Distributed Generation Incentives:Germany's EEG framework and net metering policies across multiple US states accelerate residential string inverter replacements and commercial rooftop expansion.
- Silicon Carbide MOSFETs:Wide-bandgap semiconductor adoption reduces switching losses and thermal management requirements, enabling higher power density designs that shrink balance-of-system footprints for large solar farms.
Market Restraints
- IGBT Supply Concentration:Power semiconductor fabrication concentrates among East Asian foundries, exposing inverter manufacturers to capacity allocation volatility and extended lead times for high-voltage switching components.
- GB Standard Certification Burden:China's distributed PV interconnection requirements impose lengthy type-testing protocols that delay market entry for non-domestic suppliers lacking established in-country testing partnerships.
- Electrolytic Capacitor Lifespan:Thermal cycling degradation in traditional DC-link capacitors limits inverter design lifespans to 10-12 years, creating replacement cost uncertainty for long-term power purchase agreement financiers.
Strategic Opportunities
- EU Green Deal Storage Mandates:Emerging requirements for grid-forming inverters with integrated battery readiness create specification white space for hybrid architectures in Spanish and Italian utility pipelines.
- Agricultural PV Applications:Agrivoltaic installations across France and Japan demand specialized string inverters with enhanced environmental sealing and flexible mounting configurations for dual-use land applications.
- Virtual Power Plant Aggregation:Distributed energy resource management platforms in California and Texas create new revenue streams for inverter-embedded communication and control capabilities.
Industry Challenges
- Power Electronics Talent Scarcity:Specialized expertise in electromagnetic compatibility design and thermal management engineering concentrates among veteran practitioners, constraining product development velocity for emerging suppliers.
- Multi-Standard Certification Parallelism:Simultaneous pursuit of UL 1741-SA, IEC 62109, and GB/T 37408 approvals fragments engineering resources and extends time-to-revenue for globally ambitious manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Inverter Market |
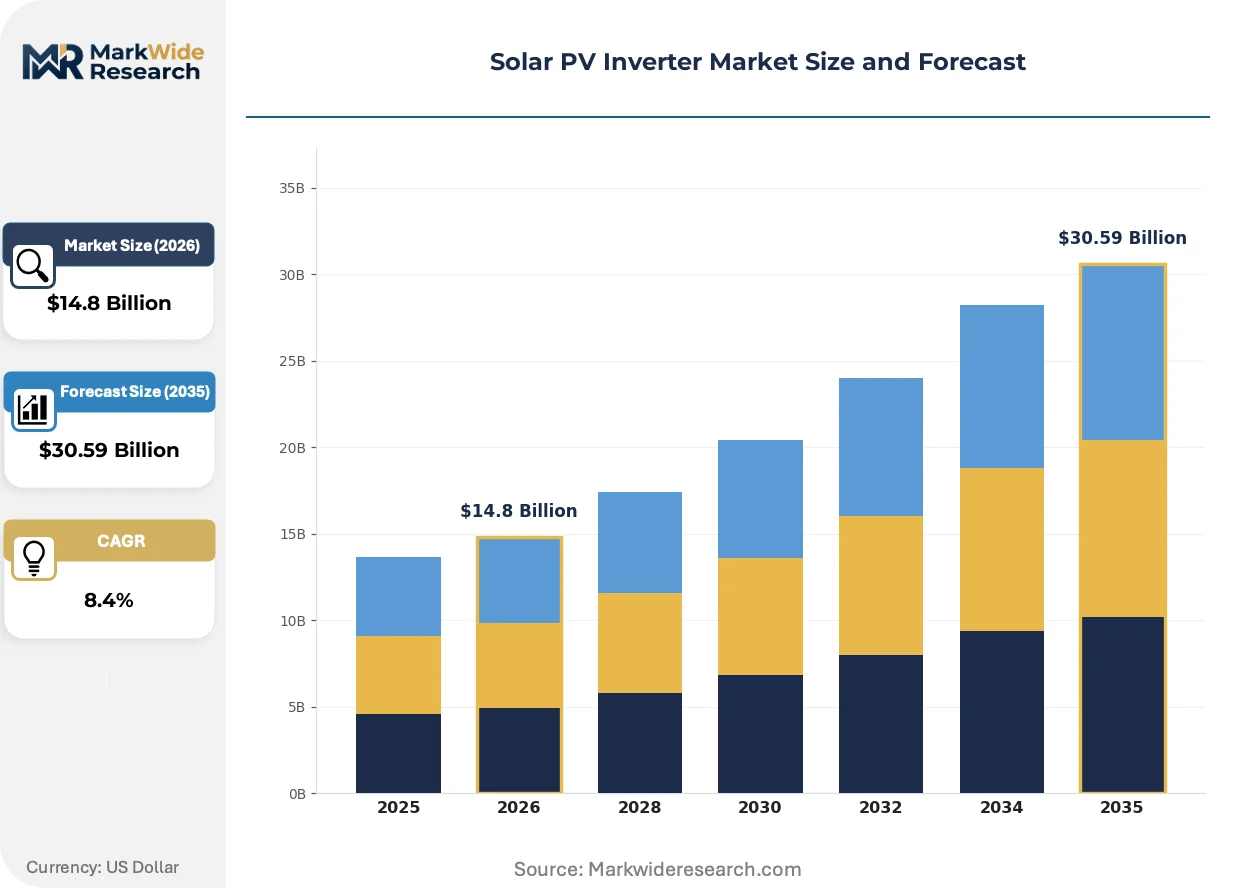
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Power Optimizers, Battery Inverters Technology: Grid-Tied, Off-Grid, Hybrid, Centralized End User: Residential, Commercial, Industrial, Utility-Scale Installation: Roof-Top, Ground-Mounted, Portable, Carport |
| Companies Covered | Huawei Technologies Co., Ltd., Sungrow Power Supply Co., Ltd., SMA Solar Technology AG, SolarEdge Technologies Inc., Enphase Energy Inc., Ginlong Technologies, Growatt New Energy, Delta Electronics, Inc., Power Electronics S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Inverter Market Strategic Shifts & Innovations
Power semiconductor material transitions and grid code harmonization efforts are compressing inverter development cycles while expanding the functional boundary between power conversion and grid management systems. These forces are redefining supplier value propositions beyond raw efficiency metrics.
Silicon carbide-based inverter platforms are absorbing switching frequency limitations that previously constrained transformerless designs in high-voltage utility applications. Developers in Arizona and Rajasthan are specifying these architectures for 1500V DC systems to reduce copper and magnetic material content. The technology is absorbing margin pressure from commodity silicon IGBT competition by enabling 20-year operational lifespan guarantees that secure project finance.
FERC Order 2023 interconnection reforms and the EU's Network Code on Requirements for Generators are synchronizing grid support function mandates across Atlantic markets. These frameworks mandate ride-through capabilities down to zero voltage and specified reactive power injection patterns during frequency excursions. Utility-scale procurement specifications in Texas and Bavaria now prioritize grid-forming inverter modes that can operate without synchronous generation reference.
Aggregator-led procurement is consolidating buyer power among virtual power plant operators and independent power producers with multi-gigawatt pipelines. Traditional equipment distributors in the US Southwest and North India are losing volume to direct manufacturer relationships and long-term service agreements. This concentration is most visible in California, where three developer groups now account for the majority of string inverter procurement for community solar portfolios.
Solar PV Inverter Market Segmentation
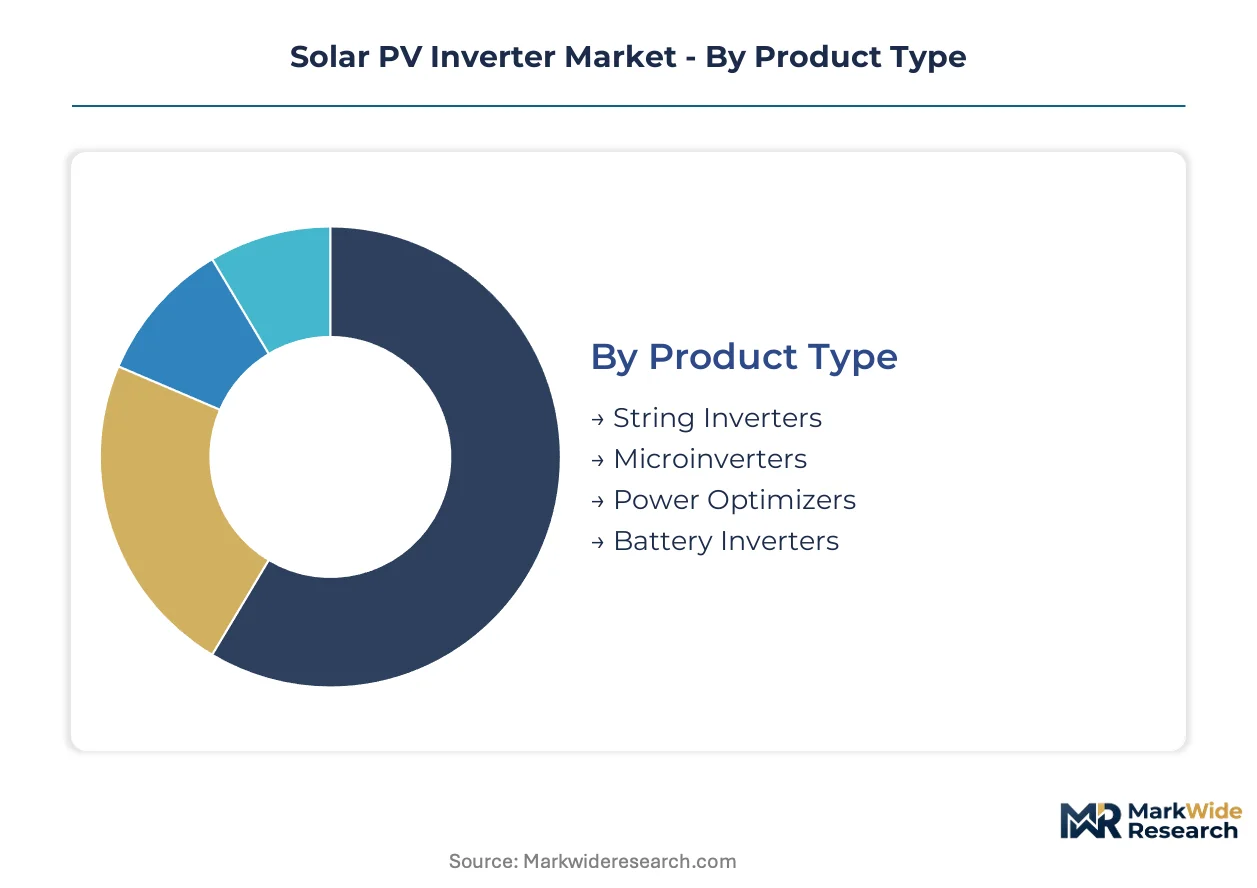
Segmentation in solar PV inverters reveals how power electronics architectures align with distinct grid interconnection requirements and project scale economics. Procurement specifications diverge sharply across residential rooftop systems, commercial installations, and utility-scale solar farms.
Product Type:
Power conversion topology determines balance-of-system costs, maintenance accessibility, and module-level optimization capabilities across installation scales.
- String Inverters:These centralized DC-to-AC conversion units aggregate photovoltaic strings into single conversion points, typically rated 3-150 kW. Utility-scale developers in Rajasthan and Arizona specify 1500V string architectures to reduce combiner box count and DC cabling runs. FERC interconnection reforms and India's CEA technical standards are tightening fault ride-through requirements that filter supplier eligibility toward established manufacturers with utility-scale deployment records.
- Microinverters:Module-level power electronics attach directly to individual photovoltaic panels, enabling per-panel maximum power point tracking and eliminating single points of failure. Residential markets in Germany and California are absorbing these units where shading from trees or adjacent structures degrades centralized inverter performance. The technology commands premium pricing that compresses adoption in price-sensitive emerging markets.
- Power Optimizers:DC-to-DC conditioning devices paired with string inverters deliver module-level monitoring and shutdown compliance without full AC conversion at each panel.
- Battery Inverters:Bidirectional power electronics manage charge-discharge cycles for lithium-ion storage systems, integrating with solar arrays under evolving EU Green Deal storage mandates.
Mature deployment sits with String Inverters. Newer deployment is concentrated in Microinverters.
Technology:
Grid integration architecture determines market access eligibility under divergent national interconnection codes and storage readiness requirements.
- Grid-Tied:Synchronization-dependent inverters operate exclusively when utility voltage and frequency references are present, representing the dominant installation base across established solar markets. Germany's EEG framework and US state-level net metering policies sustain replacement demand for these units in residential and commercial segments. Silicon carbide MOSFET adoption is compressing form factors while maintaining efficiency thresholds above 98%.
- Hybrid:Dual-mode architectures manage simultaneous solar generation and battery storage with grid-forming capabilities that enable islanded operation. Spanish and Italian utility pipelines are specifying these systems under emerging EU requirements for storage-integrated renewable assets. The technology captures margin premiums from developers securing long-term power purchase agreements with capacity firming guarantees.
- Off-Grid:Standalone power electronics operate without utility reference, serving remote industrial sites and rural electrification projects.
- Centralized:Megawatt-scale single-unit designs serve utility solar farms with integrated transformer and switchgear functions.
Grid-Tied systems anchor current installed capacity. Hybrid configurations are expanding most quickly under storage integration mandates.
End User:
Customer scale determines inverter specification priorities across efficiency targets, communication protocols, and service agreement structures.
- Residential:Single-phase and small three-phase units serve rooftop installations under 20 kW, where module-level electronics address shading and orientation variability. Germany's EEG feed-in tariffs and California's net metering reforms are accelerating string inverter replacements in aging rooftop fleets. Procurement concentrates through installer networks and direct-to-consumer channels.
- Utility-Scale:Central and string inverter architectures serve solar farms exceeding 5 MW, where procurement specifications prioritize grid support functions and 20-year operational lifespan guarantees. Independent power producers in Texas and Bavaria are consolidating buyer power through direct manufacturer relationships and long-term service agreements.
- Commercial:Three-phase string and small central inverters serve 20 kW to 5 MW rooftop and ground-mounted systems.
- Industrial:Behind-the-meter installations serve manufacturing facilities with demand charge management and power quality objectives.
Utility-Scale procurement commands concentrated engineering resources. Residential volumes are climbing fastest under distributed generation incentive expansions.
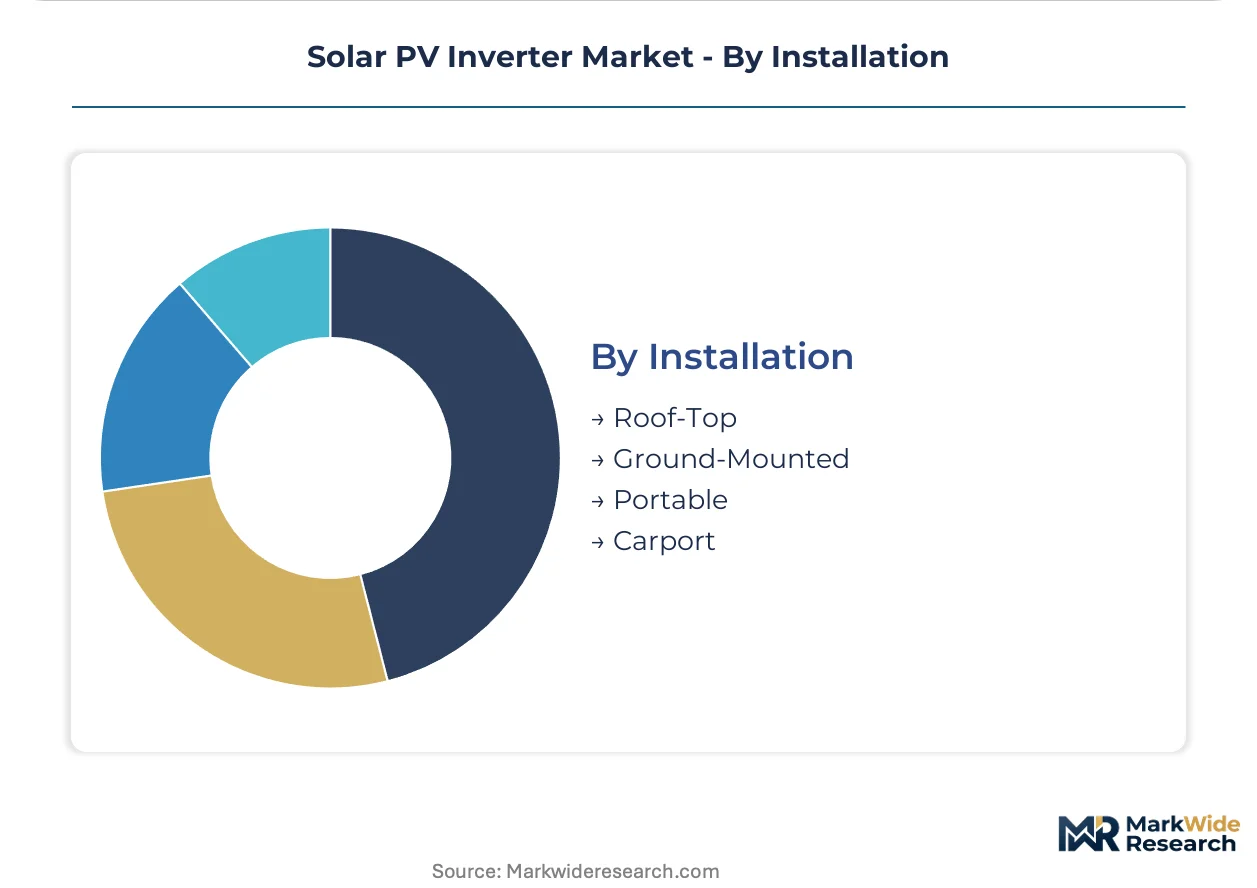
Installation:
Physical mounting configuration shapes environmental sealing requirements, thermal management design, and structural integration approaches.
- Roof-Top:Residential and commercial building-integrated systems demand compact form factors, enhanced ingress protection, and rapid shutdown compliance. India's distributed PV interconnection requirements under CEA technical standards and China's GB standards are filtering supplier eligibility based on certification status.
- Ground-Mounted:Utility-scale solar farms accommodate larger inverter enclosures with active cooling systems and direct transformer coupling. Installations in Arizona and Rajasthan specify these configurations for 1500V DC system architectures.
- Carport:Solar canopy structures integrate generation with vehicle shelter, requiring specialized mounting and cable management.
- Portable:Mobile power electronics serve temporary construction, emergency response, and recreational applications.
Ground-Mounted systems absorb utility-scale deployment. Roof-Top installations are gaining share fastest under distributed generation policy support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's solar parks and special economic zones are concentrating utility-scale inverter procurement under accelerated depreciation schemes and generation-based incentives. Rajasthan's Bhadla and Pavagada solar parks anchor multi-gigawatt deployment pipelines.
United States
Texas and California utility-scale developers are consolidating procurement through independent power producers with direct manufacturer relationships. FERC interconnection reforms mandate grid-forming capabilities for new solar assets. The ERCOT grid in Texas and CAISO territory in California absorb the majority of string inverter volumes for community solar portfolios.
China
Dual carbon goals and distributed PV expansion under GB standards are filtering supplier eligibility toward domestic manufacturers with established certification partnerships. The Yangtze River Delta and Shandong Province host concentrated manufacturing clusters for silicon carbide-based designs serving both domestic and export markets.
Germany
EEG feed-in tariff reforms and residential replacement cycles are accelerating string inverter turnover in aging rooftop fleets. Bavaria and North Rhine-Westphalia anchor commercial deployment under tightening grid code harmonization with EU Network Code requirements for ride-through capabilities.
India
CEA technical standards for fault ride-through and voltage regulation are filtering inverter eligibility toward certified suppliers with proven utility-scale records. Rajasthan and Gujarat solar parks specify 1500V string architectures to reduce balance-of-system costs under national renewable purchase obligations.
Solar PV Inverter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with utility-scale procurement consolidating around established players with certification depth while residential channels fragment across installer-network brands. The vendor base organizes into three archetypes: integrated power electronics conglomerates with captive semiconductor sourcing, pure-play inverter specialists with regional certification depth, and contract manufacturers serving private-label distributors. Capacity expansion and strategic partnerships dominate competitive moves as suppliers secure silicon carbide supply agreements and utility-scale service contracts.
Within the integrated conglomerate tier, Huawei Technologies Co., Ltd. and Sungrow Power Supply Co., Ltd. occupy positions defined by manufacturing scale and Asia-Pacific market presence. SMA Solar Technology AG exemplifies the European specialist archetype with concentrated certification depth under EU grid codes. These three entities represent divergent strategic postures: scale-driven vertical integration versus regional regulatory specialization versus platform-agnostic power electronics breadth.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Sungrow Power Supply Co., Ltd. |
| SMA Solar Technology AG |
| SolarEdge Technologies Inc. |
| Enphase Energy Inc. |
| Ginlong Technologies |
| Growatt New Energy |
| Delta Electronics, Inc. |
| Power Electronics S.L. |
| Others |
Cost & Logistics Intelligence
Silicon carbide MOSFET adoption is compressing inverter cost curves while simultaneously concentrating power semiconductor sourcing among East Asian foundries, creating asymmetric pricing power between integrated manufacturers and component-dependent assemblers. This technology shift rewards suppliers with captive wafer supply or long-term foundry agreements while squeezing margins for buyers exposed to spot-market semiconductor volatility.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from scheduled volume commitments, with utility-scale developers paying premiums for sub-quarter delivery windows amid silicon carbide allocation constraints. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade tiers reflects UL 1741-SA certification depth and after-sales service bundling. Cost compression in economy string inverters is intensifying because Chinese domestic suppliers are absorbing margin to secure utility-scale service contracts. Residential installers show highest price sensitivity, while independent power producers with multi-gigawatt pipelines prioritize grid-forming capability premiums over unit cost.
Supply Chain Analysis
IGBT and silicon carbide wafer supply rests on Taiwanese, South Korean, and Chinese specialty semiconductor foundries with limited alternative sourcing. Inverter assembly draws from electrolytic capacitors sourced from Japanese component houses, magnetic cores from Chinese powder metallurgy specialists, and thermal interface materials from German chemical formulators. Single-source vulnerability concentrates in 1500V-rated silicon carbide MOSFETs where only three foundries maintain qualified production lines. Distribution runs through direct manufacturer relationships for utility-scale procurement and installer-network channels for residential volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's CEA technical standards and FERC interconnection reforms erect certification barriers that filter participation toward established suppliers with proven utility-scale deployment records.
For Market Incumbents: Cement grid-forming inverter certification depth under EU Network Code and FERC Order 2023 mandates to defend against emerging Chinese suppliers with cost-advantaged silicon carbide platforms. Prioritize backward integration into silicon carbide wafer supply through foundry partnerships or captive sourcing to secure allocation priority during semiconductor capacity crunches. Extend long-term service agreements with independent power producers in Texas and Bavaria to lock out competitor access to multi-gigawatt procurement pipelines.
For New Entrants and Emerging Players: Enter via agricultural PV inverter specialization for French and Japanese agrivoltaic installations, where dual-use land requirements demand enhanced environmental sealing that incumbent suppliers have not optimized. Target hybrid inverter white space in Spanish and Italian utility pipelines under emerging EU Green Deal storage mandates. Pursue white-label manufacturing partnerships with established distributors in North India to bypass lengthy CEA certification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to power electronics conglomerates seeking silicon carbide inverter platforms and utility-scale service capabilities. Long-term viability favors suppliers with demonstrated FERC and CEA certification depth, captive semiconductor sourcing, and contracted pipeline visibility across multiple regulatory jurisdictions. Watch silicon carbide foundry capacity expansion announcements as the inflection signal for margin normalization versus sustained allocation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures wafer allocation priority from Taiwanese foundries amid capacity constraints. |
| Grid-Forming Certification Investment | Unlocks FERC-compliant procurement in Texas ERCOT and California CAISO territories. |
| Agrivoltaic Inverter Development | Captures French and Japanese dual-use land installation specifications ahead of incumbents. |
| Virtual Power Plant Platform Integration | Enables California and Texas aggregator revenue streams through embedded control capabilities. |
| Long-Term Service Contract Expansion | Locks multi-gigawatt pipeline access with independent power producers in Bavaria and Rajasthan. |
Research Approach
Multi-period observation of inverter procurement volumes, certification timelines, and silicon carbide allocation patterns anchored the trend analysis, supplemented by interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators. Secondary validation drew from FERC interconnection filings, EIA generation capacity data, IEA renewable technology reports, and CEA technical standard documentation. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment were triangulated against supplier shipment disclosures.
Input-output matrices mapped silicon carbide wafer supply to inverter production capacity across technology tiers, with segmentation modeled by product topology, grid integration architecture, end-user scale, and physical mounting configuration. CAGRs were derived from regression analysis of historical deployment against policy incentive trajectories and grid code evolution timelines. Forecast inputs included foundry capacity expansion schedules, renewable portfolio standard mandates across US states, and EU Green Deal implementation pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silicon carbide supply disruption or accelerated grid code harmonization scenarios. Projections reflect assumptions regarding semiconductor allocation continuity, certification timeline stability, and policy incentive durability. A small set of triggers—foundry fire or earthquake, sudden FERC rulemaking revision, or Chinese GB standard expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Solar Power Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Residential Solar Panels Market