
 Czech Republic Solar Energy Market | 2026-2036
Czech Republic Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Solar Energy Market Outlook
EU Green Deal carbon pricing is restructuring the cost-of-entry calculus for new solar developers in the Czech Republic. ČEZ Group leverages its distribution network dominance to secure grid connection priority for utility-scale parks. Solartec Holding a.s. anchors its position through captive EPC capabilities across residential and commercial rooftops. Photon Energy NV competes on merchant exposure strategies that bypass feed-in tariff dependency.
Czech Republic Solar Energy encompasses photovoltaic systems that convert sunlight into direct current electricity through silicon wafer cells, typically operating at 15-22% conversion efficiency depending on monocrystalline or polycrystalline architecture, with primary purpose of displacing fossil-generated grid power for industrial, commercial, and residential consumers. Photovoltaic technology leads installed capacity due to modular deployment economics and falling module prices, while bifacial panels represent the fastest-growing segment as developers exploit albedo gains on ground-mounted installations in South Moravia. Utility-scale application commands the largest revenue pool driven by PPA-backed projects above 10 MW, though residential installation shows accelerating permit volumes as net metering reforms stabilize.
BIS-aligned technical standards govern module import certification, while CEA grid codes dictate inverter synchronization and reactive power requirements for utility interconnection. EU F-Gas Regulation constrains heat pump-solar hybrid refrigerant choices, indirectly shaping system design for residential hybrid installations. Stakeholders must monitor auction volume announcements and distribution network reinforcement schedules to time development pipelines against connection bottleneck risks.
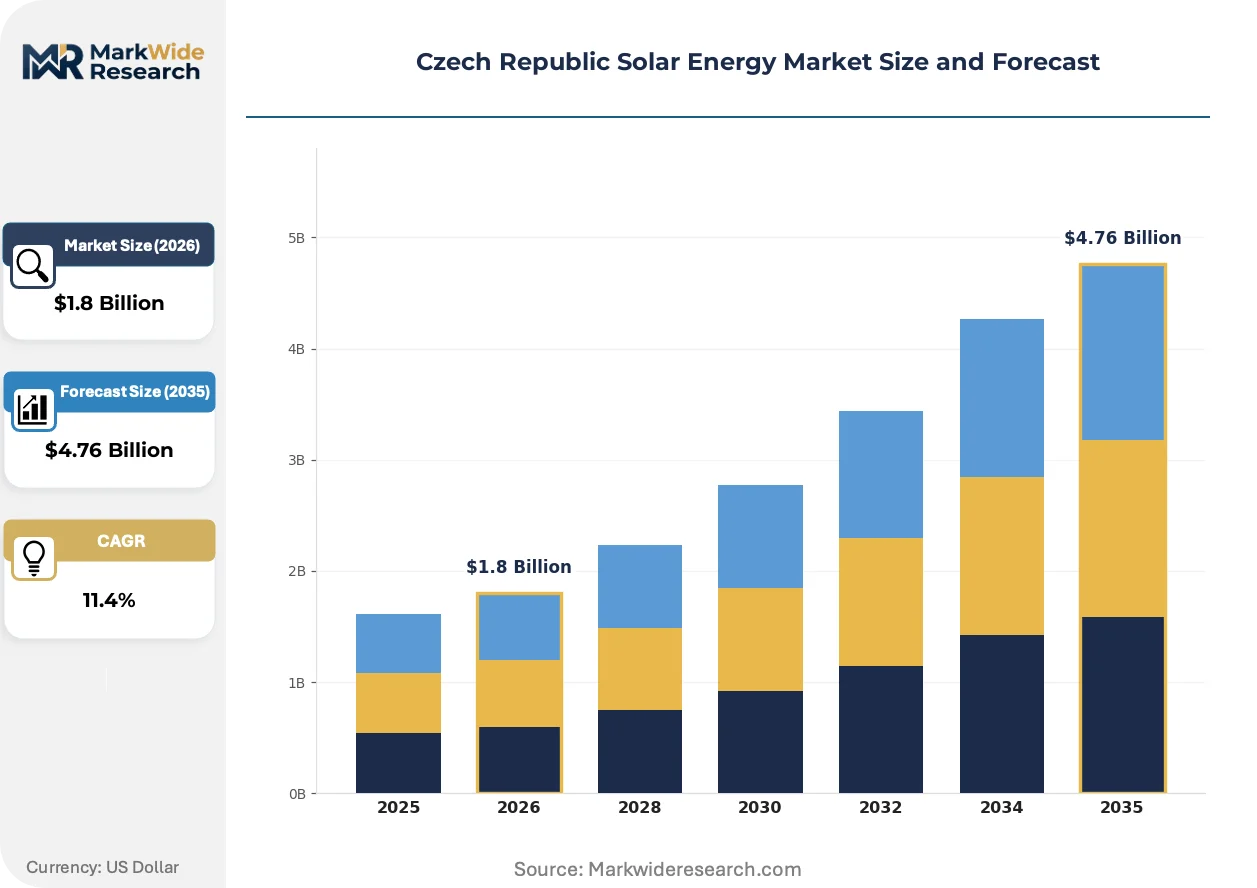
Market Dynamics
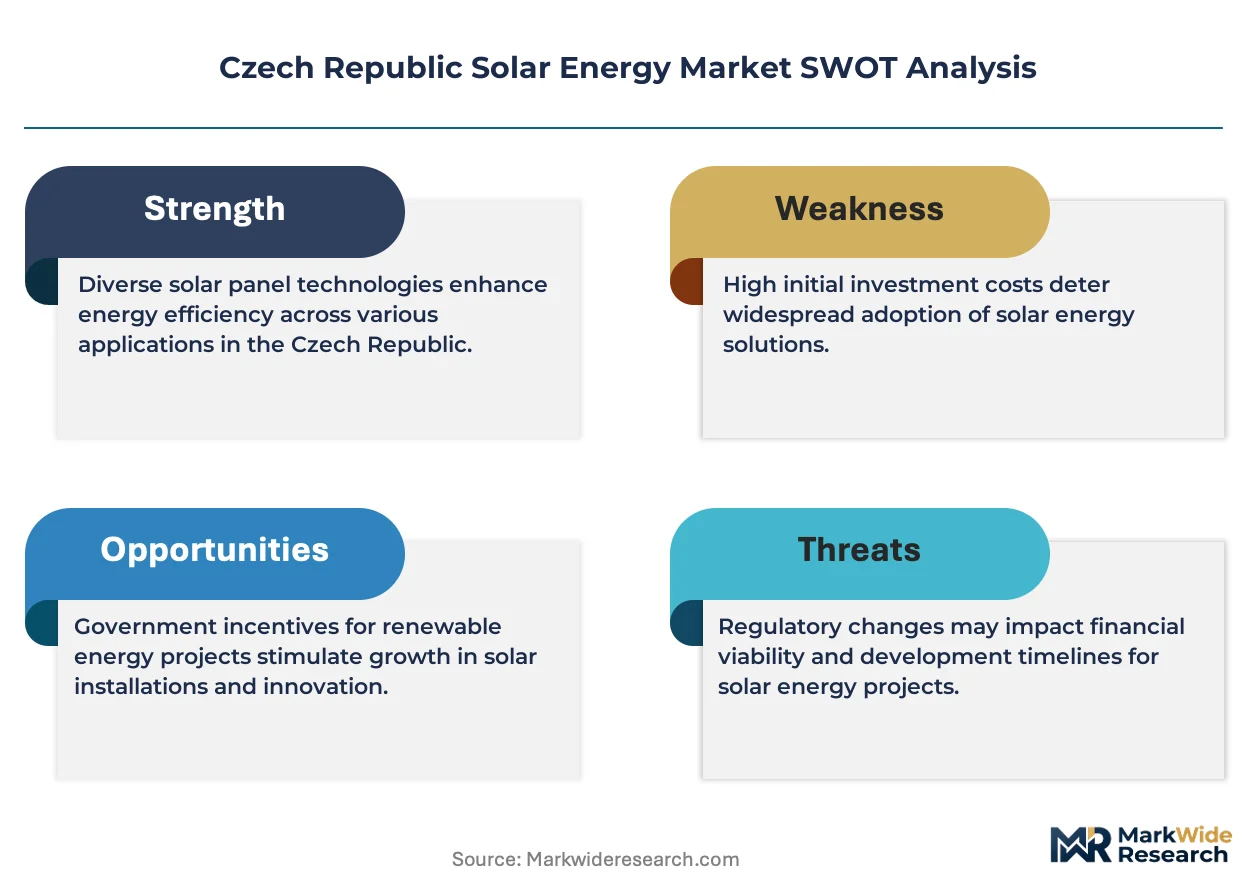
The EU Green Deal carbon pricing mechanism is restructuring project economics for Czech solar developers. Feed-in tariff phase-outs are forcing merchant power strategies. Grid interconnection bottlenecks in Central Bohemia concentrate development risk.
Growth Catalysts
- EU Green Deal carbon pricing:The mechanism raises the cost competitiveness of photovoltaic generation against coal-fired baseload. Industrial off-takers in the Moravian-Silesian Region are accelerating procurement timelines.
- Bifacial panel technology:Albedo capture on ground-mounted installations in South Moravia is expanding into utility-scale project designs. EPC contractors are specifying dual-sided modules for new 10 MW-plus arrays.
- Industrial rooftop demand:Manufacturing clusters across Central Bohemia are deploying captive solar to hedge against wholesale electricity volatility. Automotive suppliers anchor this procurement wave.
Market Restraints
- Polysilicon supply concentration:Chinese ingot and wafer production dominates upstream capacity. Czech developers face price volatility and forced contract terms from concentrated suppliers.
- Grid reinforcement lag:ČEZ Distribuce connection queues extend 18-24 months in high-demand substations. Project finance timelines stretch to accommodate interconnection uncertainty.
- EU F-Gas Regulation:The framework constrains refrigerant choices for solar-heat pump hybrid systems. Residential installers face equipment certification delays and limited supplier options.
Strategic Opportunities
- Agricultural PV deployment:Agrivoltaic installations on Moravian farmland are expanding into dual-use revenue models. Landowners capture lease payments while maintaining crop production.
- Corporate PPA structures:Long-term power purchase agreements bypass auction dependency for developers. Industrial buyers in Prague and Brno manufacturing zones anchor this contracting innovation.
- Net metering reform stabilization:The regulatory framework now permits residential surplus export at fixed rates. Homeowners in sub-regions with high solar irradiance are accelerating permit applications.
Industry Challenges
- Distribution network congestion:Low-voltage transformer capacity limits residential cluster deployment in dense suburbs. Utilities must upgrade infrastructure before permitting proceeds.
- Skilled EPC labor scarcity:Certified electricians and mounting specialists are concentrated in Prague and Brno. Rural project execution faces crew mobilization delays and wage inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Solar Energy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
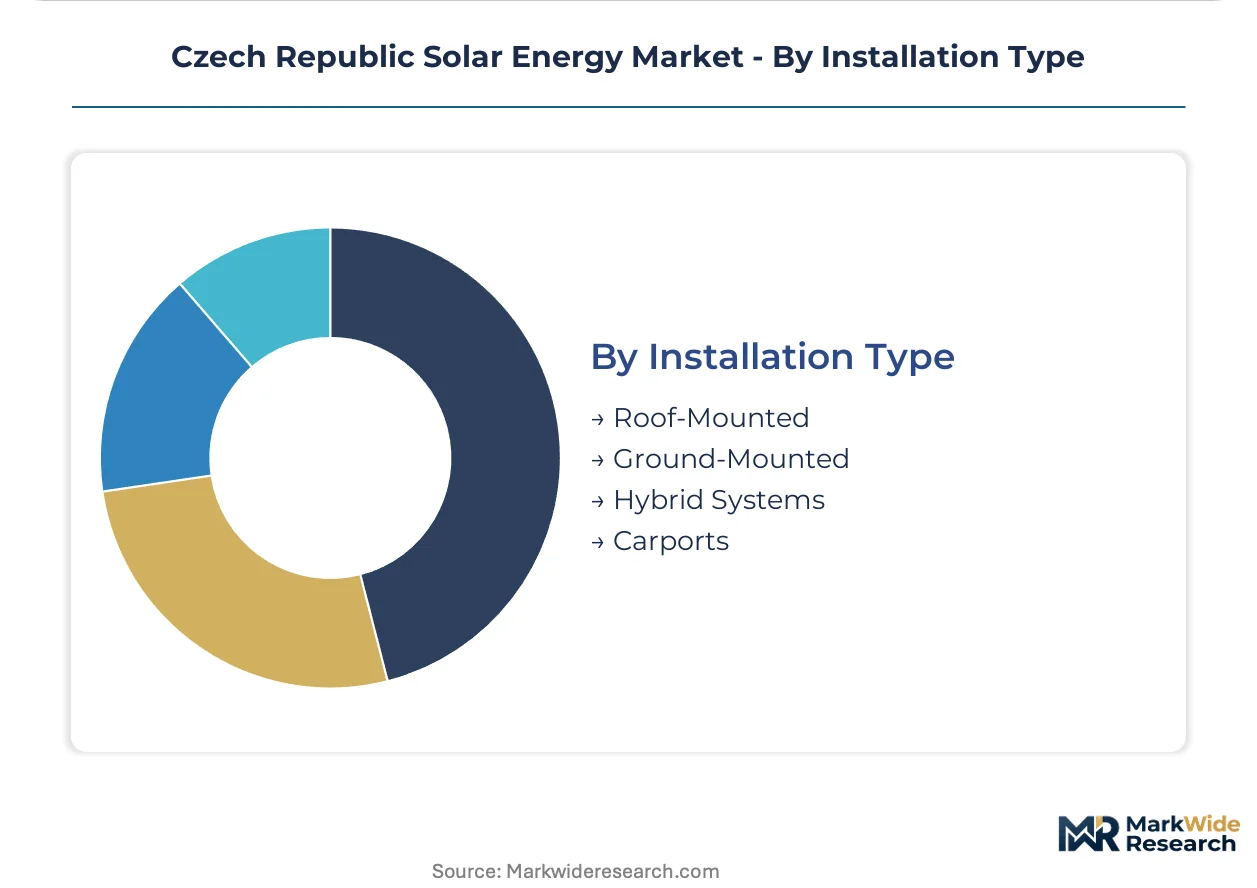
| Segmentation | Technology Type: Photovoltaic, Concentrated Solar Power, Bifacial Panels, Thin-Film Solar Application: Residential, Commercial, Utility-Scale, Off-Grid End User: Homeowners, Businesses, Government, Industrial Installation Type: Roof-Mounted, Ground-Mounted, Hybrid Systems, Carports |
| Companies Covered | Solartec Holding a.s., Solidsun S.r.o., ČEZ Group, Solek, EcoSun Systems s.r.o., Photon Energy NV, Ekotechnik Czech s.r.o., SVP Solar SRO, Solar Global a.s., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Solar Energy Market Strategic Shifts
Technology convergence and procurement model evolution are compressing development cycles. Regulatory clarity on grid codes is enabling larger project pipelines. Merchant power exposure is becoming the default commercial structure.
Bifacial photovoltaic modules are expanding into utility-scale ground-mounted installations across South Moravia. Developers specify these panels to capture reflected irradiance from light soil and gravel surfaces. The technology is expanding into project finance structures that assume higher capacity factors than monofacial equivalents.
EU F-Gas Regulation amendments are reshaping equipment certification pathways for solar-thermal hybrid systems. Manufacturers must reformulate heat pump refrigerants to meet GWP thresholds. Residential installers in the Czech Republic are delaying hybrid system launches until certified equipment clears customs.
Corporate power purchase agreements are displacing auction-dependent development models for projects above 10 MW. Industrial off-takers in automotive and electronics manufacturing are signing 10-15 year fixed-price contracts. This procurement shift concentrates in the Moravian-Silesian Region where grid capacity and manufacturing load centers overlap.
Czech Republic Solar Energy Market Segmentation
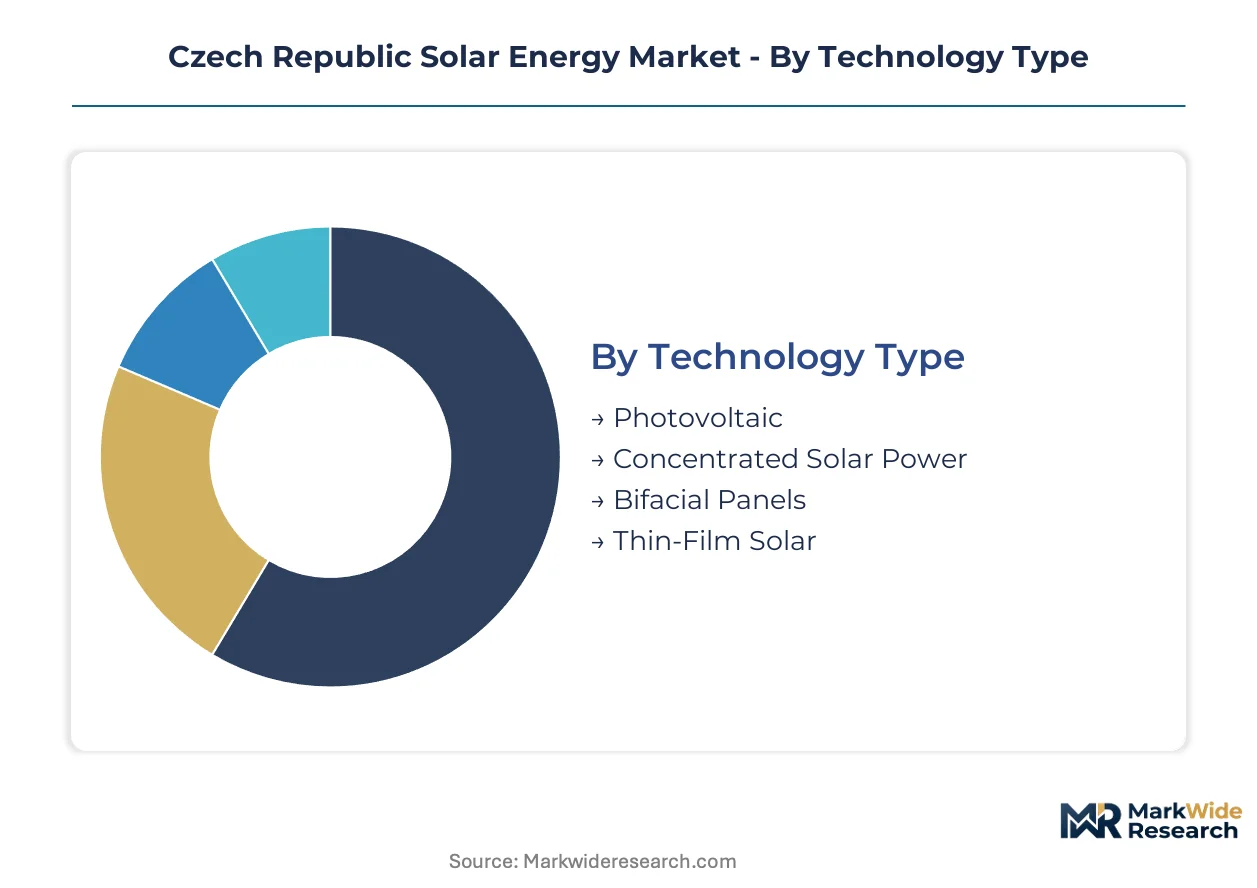
Technology architecture and installation topology determine which EU and Czech regulatory frameworks apply. Certification pathways bifurcate between grid-connected utility arrays and behind-the-meter residential systems. Procurement concentration in Central Bohemia and South Moravia reshapes segment prioritization for developers.
Technology Type:
BIS-aligned technical standards govern module import certification for crystalline silicon technologies, while thin-film architectures face additional electromagnetic compatibility testing. EU F-Gas Regulation constrains heat pump-solar hybrid refrigerant choices.
- Photovoltaic:Silicon wafer cells convert sunlight to direct current electricity at 15-22% efficiency depending on monocrystalline or polycrystalline architecture. Manufacturing clusters in the Moravian-Silesian Region anchor procurement of rooftop and ground-mounted arrays for industrial off-takers hedging wholesale volatility.
- Bifacial Panels:Dual-sided modules capture direct irradiance plus reflected albedo from light soil and gravel surfaces. South Moravia developers specify these for 10 MW-plus utility-scale projects where ground conditions amplify rear-side generation gains.
- Concentrated Solar Power:Mirror arrays focus sunlight onto thermal receivers for utility-scale steam generation. Czech deployment remains minimal due to higher capital intensity and limited direct normal irradiance.
- Thin-Film Solar:Cadmium telluride or copper indium gallium selenide layers deposited on flexible substrates. Building-integrated applications in Prague commercial retrofits exploit lightweight mounting requirements.
Leading the category by volume: Photovoltaic. Expanding most quickly: Bifacial Panels.
Application:
Project scale determines grid interconnection queue position and ČEZ Distribuce prioritization protocols. Merchant power exposure concentrates in utility-scale while net metering reforms stabilize residential economics.
- Utility-Scale:Ground-mounted arrays above 10 MW connect at high-voltage substations with PPA-backed revenue structures. Central Bohemia manufacturing zones and Moravian-Silesian industrial corridors concentrate development where grid capacity overlaps load centers.
- Residential:Rooftop systems below 10 kW qualify for simplified permitting and net metering surplus export at fixed rates. Homeowners in sub-regions with high solar irradiance accelerate applications following regulatory stabilization.
- Commercial:Mid-scale rooftop and carport installations serve businesses seeking captive generation. Automotive suppliers across Central Bohemia deploy these to secure energy cost predictability.
- Off-Grid:Standalone battery-coupled systems serve remote agricultural operations and mountain facilities. Limited addressable market due to Czech grid density.
Revenue concentrates in: Utility-Scale. Permit volume accelerates in: Residential.
End User:
Customer type shapes contract structure, financing source, and sensitivity to auction timing versus merchant price exposure.
- Industrial:Manufacturing facilities procure rooftop and ground-mounted arrays to hedge wholesale electricity volatility. Automotive and electronics clusters in Prague and Brno zones anchor corporate PPA innovation.
- Businesses:Commercial enterprises deploy carport and rooftop systems with shorter payback thresholds than industrial counterparts. Retail and logistics facilities in dense suburbs face distribution network congestion constraints.
- Homeowners:Residential customers respond to net metering reform stabilization with accelerating permit volumes. Sub-regions with high solar irradiance show clustering effects.
- Government:Public building retrofits and municipal procurement follow EU Green Deal implementation timelines. Budget cycles extend development timelines versus private off-takers.
Procurement volume leader: Industrial. Fastest contract innovation: Businesses.
Installation Type:
Mounting topology determines labor skill requirements, structural engineering standards, and land-use permitting pathways.
- Ground-Mounted:Fixed-tilt or tracking arrays on open land require geotechnical assessment and agricultural land-use conversion permits. South Moravia agrivoltaic dual-use models expand lease revenue for farmland owners.
- Roof-Mounted:Building-integrated and ballasted systems dominate urban deployment. Central Bohemia manufacturing facilities prioritize these for captive generation without land acquisition.
- Hybrid Systems:Solar-thermal combinations with heat pumps face EU F-Gas Regulation refrigerant constraints. Equipment certification delays limit residential installer uptake.
- Carports:Elevated canopy structures serve parking areas with dual revenue from generation and weather protection. Commercial logistics facilities in Prague periphery deploy these for fleet electrification alignment.
Capacity deployment leader: Ground-Mounted. Emerging fastest: Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Central Bohemia and the Moravian-Silesian Region where manufacturing clusters and grid interconnection capacity overlap. The EU Green Deal and national renewable auctions are restructuring project finance timelines across sub-regions. Industrial end users are scaling procurement of rooftop and ground-mounted arrays throughout these zones.
Central Bohemia
Automotive suppliers and electronics manufacturers anchor industrial rooftop deployment across this manufacturing corridor. EU Green Deal carbon pricing raises photovoltaic competitiveness against coal-fired baseload for these facilities. Prague periphery logistics zones deploy carport arrays to align with fleet electrification timelines.
Moravian-Silesian Region
Heavy industry clusters accelerate captive solar procurement to hedge wholesale electricity volatility. National renewable auction schedules determine project finance sequencing for developers active here. Ostrava manufacturing zones concentrate corporate PPA innovation with 10-15 year fixed-price contracting.
South Moravia
Agrivoltaic dual-use models expand across farmland where albedo conditions favor bifacial panel performance. EU F-Gas Regulation constrains solar-heat pump hybrid equipment certification pathways for residential installers. Brno manufacturing anchors merchant power exposure strategies that bypass feed-in tariff structures.
Prague Metro
Commercial building retrofits concentrate demand for building-integrated thin-film applications with lightweight mounting requirements. ČEZ Distribuce grid reinforcement schedules determine connection queue positions for urban projects. Dense suburbs face low-voltage transformer capacity limits that constrain residential cluster deployment.
Czech Republic Solar Energy Market Competitive Environment
Czech producers anchor the utility-scale and distribution-tier; Benelux and Central European specialists hold merchant-exposure and EPC-integration positions. The market structures around three tiers: incumbent utilities with grid priority access, vertically integrated EPC-holding groups, and merchant-power developers with cross-border capital structures. Strategic moves concentrate on auction pipeline positioning and distribution network reinforcement partnerships.
Within the integrated-utility tier, ČEZ Group represents incumbent grid-access advantages. Solartec Holding a.s. and Photon Energy NV exemplify contrasting EPC-captive versus merchant-exposure archetypes. These three occupy positions spanning tariff-dependent, vertically integrated, and market-risk-bearing competitive vectors.
| Leading Market Players |
|---|
| Solartec Holding a.s. |
| Solidsun S.r.o. |
| ČEZ Group |
| Solek |
| EcoSun Systems s.r.o. |
| Photon Energy NV |
| Ekotechnik Czech s.r.o. |
| SVP Solar SRO |
| Solar Global a.s. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon pricing gates qualified supply and premium-tier pricing access for Czech solar developers, as compliant module certification and grid synchronization standards create tiered market entry barriers that separate auction-eligible from merchant-exposed project economics.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers in the Czech solar market, with expedited delivery of bifacial modules commanding 15-20% premiums over spot inventory liquidation. Price differentiation hinges on BIS-aligned certification tier and ČEZ Distribuce grid priority queue position, with utility-scale developers least sensitive due to long-dated PPA revenue certainty while residential installers face acute margin compression from equipment certification delays.
Supply Chain Analysis
Domestic-content mandates under EU F-Gas Regulation and national renewable auction rules are reshaping sourcing patterns, forcing Czech developers to document supply chain provenance for refrigerant-dependent hybrid systems. Polysilicon ingot and wafer production concentrates in China, South Korea, and Malaysia, with Czech project pipelines drawing from these hubs for cell and module assembly. Single-source vulnerability in high-purity silicon feedstock creates structural risk, while distribution runs through ČEZ Group's captive network and independent EPC contractor channels to end-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation and BIS-aligned certification standards erect barrier-to-entry moats that reward players with established equipment approval pathways and grid interconnection priority.
For Market Incumbents: Cement grid access advantages through strategic partnerships with ČEZ Distribuce on network reinforcement schedules, while deepening backward integration into captive EPC labor pools to offset skilled electrician scarcity threatening rural project execution timelines. For New Entrants and Emerging Players: Begin with agrivoltaic deployment in South Moravia's dual-use farmland segments, where landowners seek lease revenue without sacrificing crop production and regulatory clarity on agricultural land-use permits remains more navigable than saturated utility-scale queues. For Investors and Strategic Acquirers: ČEZ Distribuce auction volume announcements clearing 18-24 month connection backlogs is the leading indicator that project finance timelines will compress and developer IRRs will expand, suggesting long-term viability for vertically integrated EPC-holding groups with distribution network partnerships over pure merchant-exposure developers.| Strategic Initiative | Industry Significance |
|---|---|
| Grid Reinforcement Partnership | ČEZ Distribuce collaboration secures connection queue priority for utility-scale pipelines. |
| Bifacial Technology Licensing | Albedo capture specifications differentiate South Moravia ground-mounted project bids. |
| Agrivoltaic Land Lease Program | Moravian farmland owners capture dual revenue streams without agricultural displacement. |
| Corporate PPA Origination | Automotive suppliers in Prague-Brno corridors anchor 10-15 year fixed-price contracting. |
| EPC Labor Certification Investment | Prague and Brno training pipelines address skilled electrician scarcity constraining rural deployment. |
Study Parameters
Document review covered EIA project databases, IEA renewable energy reports, and EU Green Deal implementation filings, complemented by interviews with utility planning officers at ČEZ Group, IPP project developers active in Central Bohemia, EPC contractors specializing in bifacial installations, and grid operators managing distribution network reinforcement schedules. Secondary validation drew from Czech regulatory auction announcements, BIS technical standards documentation, and customs trade data on module import flows. Bottom-up project pipeline enumeration triangulated against top-down market sizing from capacity deployment records.
Segment-level value outputs across the projection horizon reflect modeled deployment trajectories by technology type, application scale, end-user segment, and installation topology, with CAGRs derived from regression analysis of historical auction volumes and grid interconnection queue clearance rates. Key forecast inputs include polysilicon price index movements and EU F-Gas Regulation amendment timelines affecting hybrid system certification pathways.
Underlying measurement precision varies by segment; utility-scale and industrial rooftop categories carry tighter precision than emerging agrivoltaic and hybrid system segments due to longer operational track records and standardized reporting requirements. Forecasts reflect assumptions on auction schedule adherence and distribution network upgrade pacing that EU regulatory shifts or ČEZ capital allocation revisions could alter. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Rack Market