
 Solar-Powered EV Charging Stations Market | 2026-2036
Solar-Powered EV Charging Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Solar-Powered EV Charging Stations Market Analytics
Commercial fleet operators are rotating into the dominant buyer archetype for solar-powered EV charging stations as logistics electrification accelerates. ABB E-mobility leverages its grid-interconnection expertise to anchor large-scale fleet deployments across European and North American markets. Tesla dominates integrated hardware-software ecosystems with proprietary Supercharger architecture and in-house solar panel production. Beam Global differentiates through fully transportable, off-grid units that occupy niche applications for emergency response and remote fleet staging.
Solar-powered EV charging stations combine photovoltaic generation, battery energy storage, and electric vehicle supply equipment into unified systems typically rated from 7 kW residential Level 2 outputs to 350 kW DC fast-charging configurations. These installations serve commercial and public infrastructure by eliminating grid-dependency during peak demand periods and reducing operational carbon intensity. Fast chargers command premium positioning within product type segments due to fleet-operator requirements for rapid turnaround times. Networked stations extract recurring revenue through software subscriptions and demand-response participation, while standalone units retain appeal for rural and backup-power applications where grid connectivity remains unreliable or costly.
The US Inflation Reduction Act directs investment tax credits toward solar-plus-storage configurations, while the EU Green Deal and F-Gas Regulation constrain refrigerant-based cooling alternatives for high-power electronics. California's Title 24 building standards mandate solar readiness for new commercial construction, effectively preconditioning site infrastructure for EV charging integration. Stakeholders must monitor evolving interconnection standards and net-metering reforms that determine whether behind-the-meter solar configurations retain economic viability against time-of-use utility rates.
Market Dynamics
Fleet electrification timelines are compressing procurement cycles for solar-powered EV charging infrastructure as logistics operators seek to decouple from volatile utility rate structures and interconnection queue delays.
Growth Catalysts
- US Inflation Reduction Act Investment Tax Credits:Solar-plus-storage configurations qualify for accelerated capital recovery, shortening payback periods for commercial deployments.
- California Title 24 Building Standards:New commercial construction must incorporate solar readiness, preconditioning electrical infrastructure for integrated EV charging systems.
- Fleet Electrification Mandates:Last-mile delivery and municipal transport operators face binding decarbonization targets that favor on-site renewable generation.
Market Restraints
- Interconnection Queue Congestion:Utility approval timelines for grid-tied solar installations in Texas and Florida extend 18-24 months, delaying revenue commencement.
- Lithium-Ion Battery Cost Volatility:Energy storage represents 35-40% of system capex, with cell price fluctuations transmitted directly to project economics.
- EU F-Gas Regulation Constraints:High-power charging electronics require alternative cooling architectures as refrigerant-based thermal management faces phase-down schedules.
Strategic Opportunities
- Emergency Response Applications:Transportable off-grid units serve disaster relief and remote staging where grid infrastructure is non-existent or compromised.
- India PLI Scheme for Solar Manufacturing:Domestic module production incentives reduce import dependency and soften landed costs for charging station integrators.
- Vehicle-to-Grid Integration:Bidirectional charging protocols enable fleet operators to monetize battery assets through frequency regulation and peak shaving services.
Industry Challenges
- Electrical Engineering Talent Scarcity:System integrators struggle to staff projects requiring combined expertise in photovoltaic design, battery management, and DC fast-charging protocols.
- Multi-Standard Certification Complexity:UL 2743 for portable power, SAE J1772 for connectors, and IEC 61851 for charging systems create overlapping compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar-Powered EV Charging Stations Market |
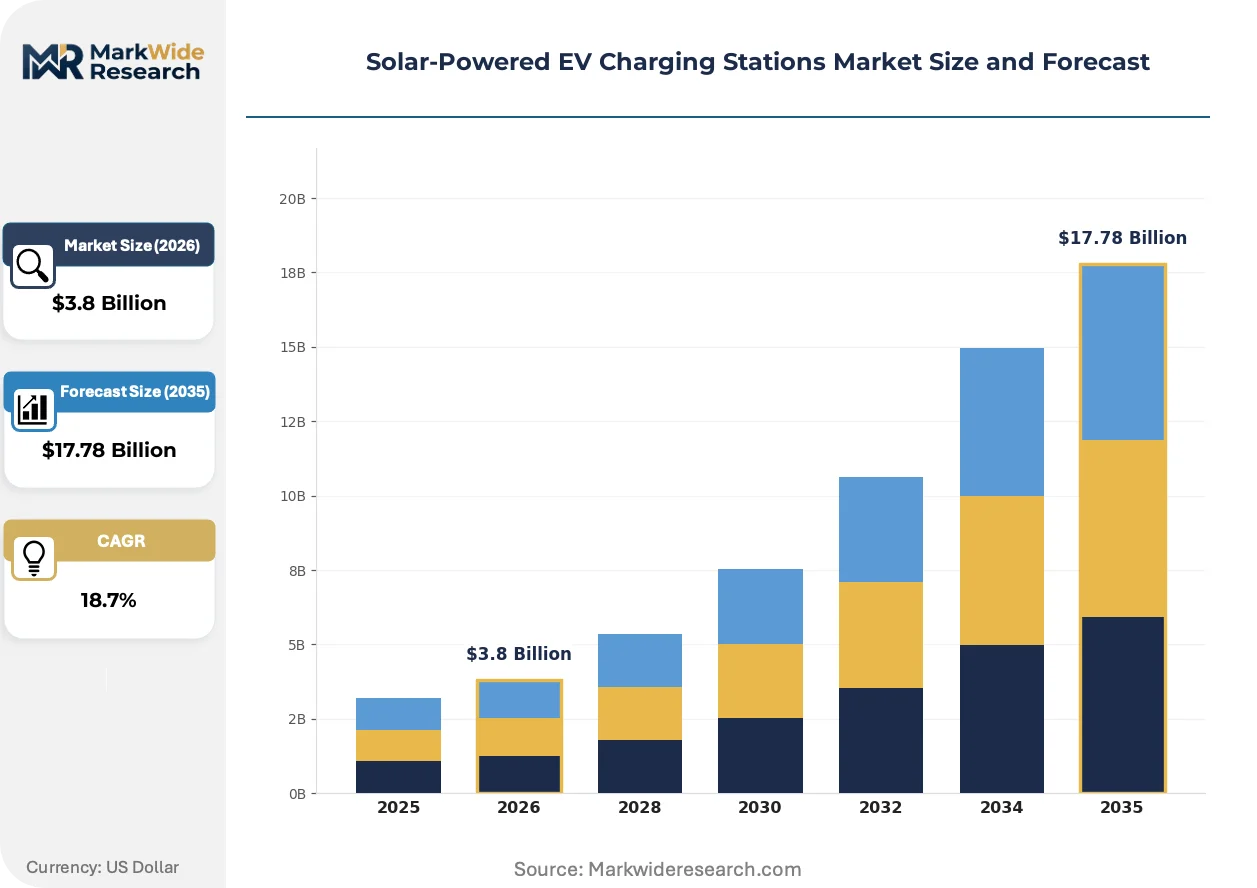
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, Fast Chargers, Superchargers Installation Type: Public Infrastructure, Residential Installations, Commercial Installations, Fleet Charging Charging Network: Standalone Stations, Networked Stations, Mobile Charging Units, Integrated Solutions End User: Private Users, Fleets, Commercial Entities, Government Facilities |
| Companies Covered | ROA Energy, ABB E-mobility, Beam Global, Electrify America, Tesla, Enphase Energy, Emporia Corp., EVgo, Suryatech EV Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar-Powered EV Charging Stations Market Evolving Landscape
Silicon carbide power electronics and solid-state battery architectures are compressing system footprints while elevating thermal efficiency, enabling deployment in space-constrained urban environments previously unsuitable for solar charging infrastructure.
Silicon carbide MOSFETs are displacing traditional IGBT modules in DC fast-charging inverters, cutting switching losses by half. Tier 1 automotive suppliers and charging network operators are adopting 800V architectures for fleet hubs. This semiconductor transition is displacing incumbent thermal management approaches and enabling 350kW outputs from enclosures one-third the size of legacy systems.
The EU Green Deal's Fit for 55 package tightens embodied carbon thresholds for infrastructure projects receiving public funding. Member states are incorporating lifecycle assessment requirements into concession agreements for highway charging corridors. Fast-charging equipment manufacturers serving the Trans-European Transport Network must now document supply chain emissions or face procurement disqualification.
Fleet operators are consolidating vendor relationships around integrated hardware-software-service bundles rather than procuring components separately. Large logistics companies now specify charging-as-a-service contracts with guaranteed uptime SLAs, transferring operational risk to infrastructure providers. This purchasing pattern is most pronounced in California and Texas, where fleet electrification targets are binding and capital allocation favors opex models over balance-sheet ownership.
Solar-Powered EV Charging Stations Market Segmentation
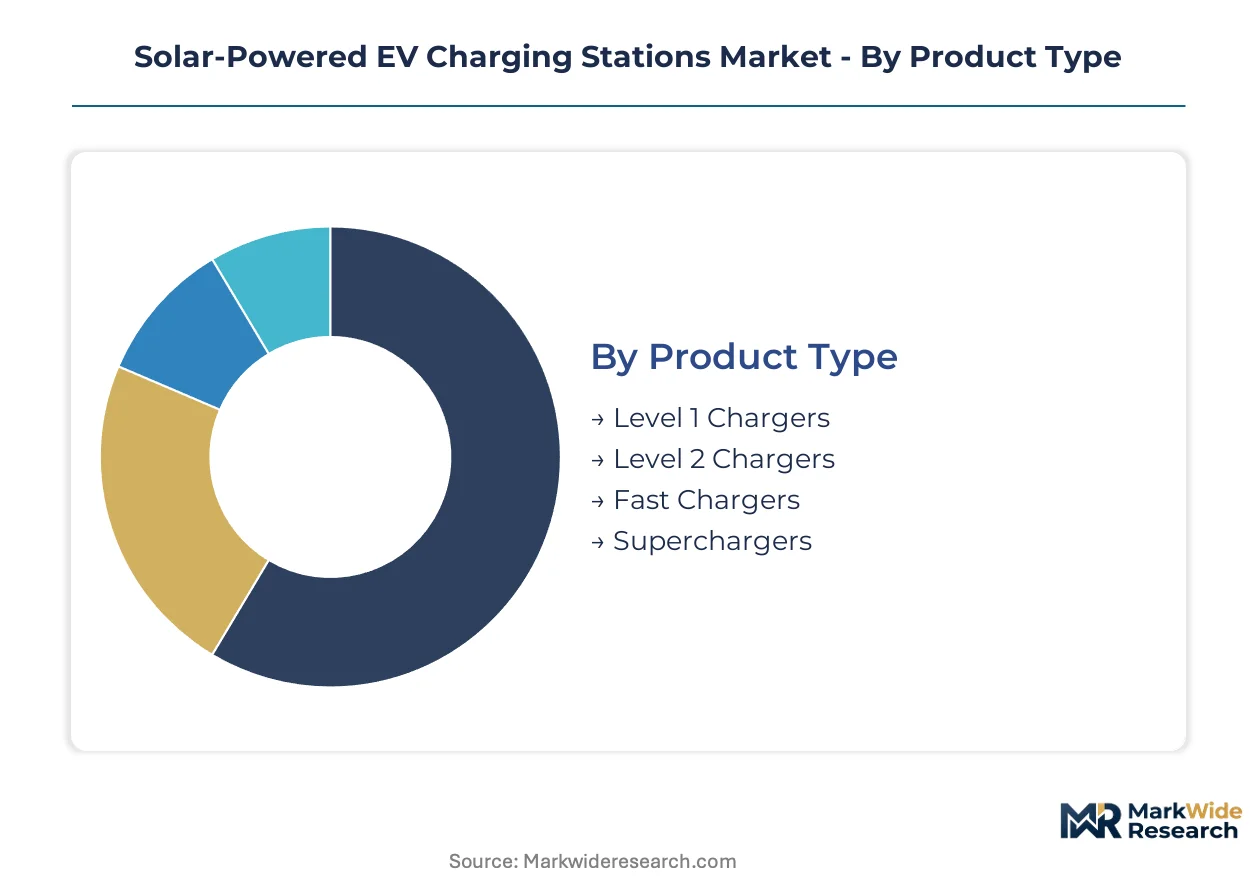
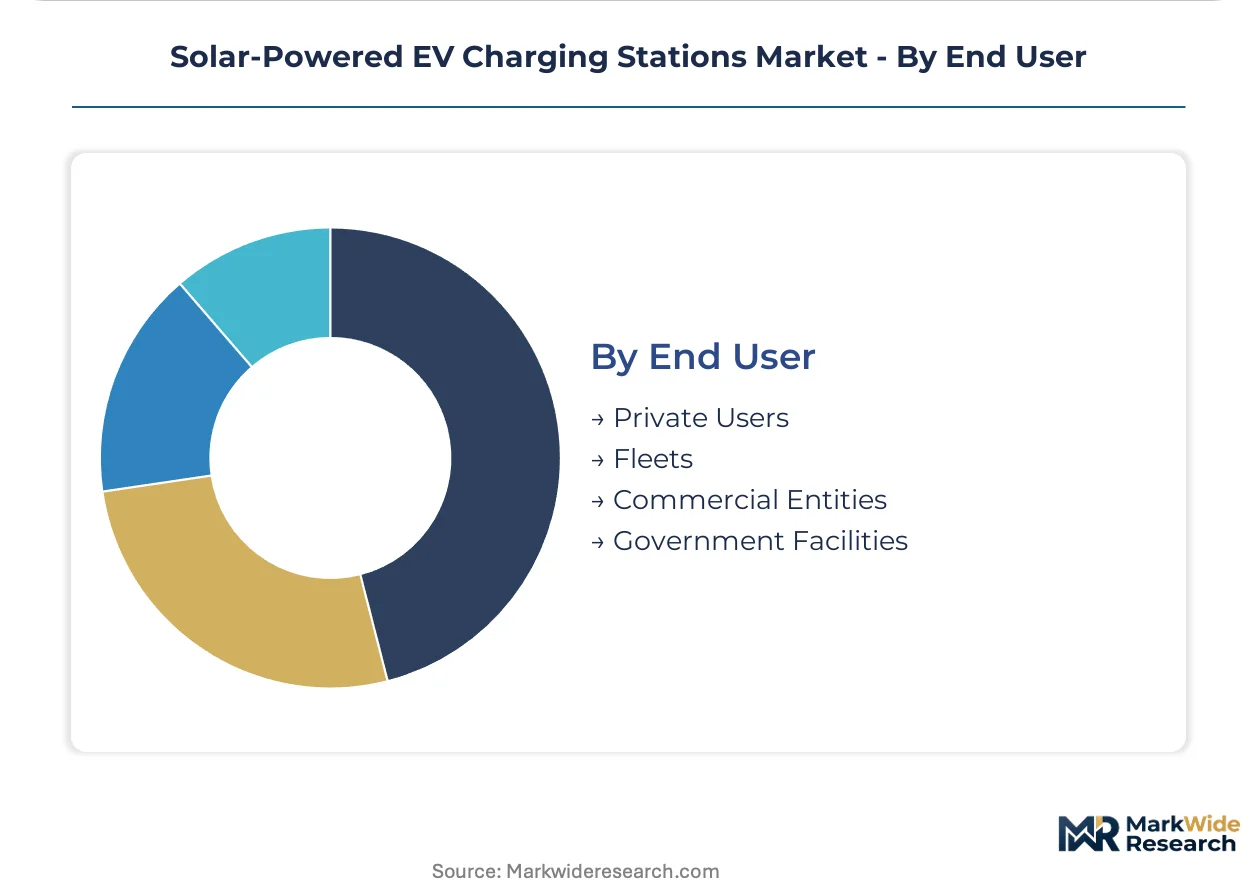
Segmentation in solar-powered EV charging stations reveals how procurement patterns diverge between fleet operators seeking rapid turnaround and residential users prioritizing cost recovery. Technical specifications, installation environments, and network connectivity each create distinct competitive arenas with varying margin profiles and capital intensity requirements.
Product Type:
Fast charging architectures face the strongest substitution pressure from grid-tied alternatives when solar generation and battery storage costs exceed utility time-of-use arbitrage value.
- Level 1 Chargers:These 1.4 kW residential units rely on standard 120V outlets and require minimal electrical infrastructure. Demand concentrates in single-family homes across California and Texas where overnight charging aligns with solar battery discharge cycles and IRA tax credits offset hardware costs.
- Level 2 Chargers:Rated 7-19 kW, these systems dominate workplace and multi-unit dwelling installations. Procurement volumes in Florida cluster around commercial real estate developments seeking LEED certification and Title 24 compliance, with solar integration reducing operational carbon intensity for ESG reporting.
- Fast Chargers:50-350 kW DC configurations serve fleet hubs and highway corridors where vehicle utilization rates demand sub-30-minute charging cycles.
- Superchargers:Proprietary high-power architectures above 250 kW with integrated thermal management and vehicle communication protocols.
Level 2 chargers anchor the volume base while fast chargers gain share at the steepest rate.
Installation Type:
Cost tier stratification separates capital-intensive public infrastructure from distributed residential deployments with divergent payback horizons and financing structures.
- Public Infrastructure:Highway corridors and municipal parking facilities requiring utility interconnection and ADA compliance. Texas and California transportation authorities prioritize these for transit electrification corridors.
- Residential Installations:Single-family and multi-unit dwelling systems typically paired with rooftop solar and home energy management. Florida's net-metering reforms and hurricane resilience requirements shape procurement specifications.
- Commercial Installations:Retail, hospitality, and workplace charging with customer dwell-time optimization. These systems expand most quickly as employers compete for talent through sustainability amenities and EV-ready parking.
- Fleet Charging:Dedicated depot infrastructure for logistics, municipal transit, and last-mile delivery operators. California Air Resources Board mandates and Texas fleet electrification targets compress procurement timelines for this segment.
Fleet charging commands the highest capital deployment per site while commercial installations expand across the greatest number of new locations.
Charging Network:
Application maturity separates established networked architectures from emerging mobile and integrated configurations with unproven revenue models.
- Standalone Stations:Off-grid units with no external connectivity, serving rural backup power and emergency response. Beam Global's transportable deployments in remote Texas and Florida staging areas illustrate this niche.
- Networked Stations:Cloud-connected systems with payment processing, remote monitoring, and demand-response participation. These dominate California's highway corridor concessions where uptime SLAs determine vendor selection.
- Mobile Charging Units:Trailer-mounted solar-battery systems for temporary events, construction sites, and disaster relief. FEMA procurement and municipal resilience budgets in hurricane-prone states drive specification requirements.
- Integrated Solutions:Combined solar generation, storage, and charging with building energy management. These climb the fastest as California Title 24 mandates precondition new commercial construction for full electrification.
Networked stations generate the most recurring software revenue while integrated solutions capture the steepest expansion trajectory in new construction.
End User:
Customer type concentration reveals how fleet procurement centralization contrasts with fragmented private demand and institutional purchasing cycles.
- Private Users:Individual vehicle owners purchasing residential systems or accessing public networks. California's high EV penetration rates and time-of-use rate structures concentrate demand here.
- Fleets:Logistics operators, ride-hail services, and municipal transit authorities with binding electrification targets. Texas last-mile delivery operators and California drayage truck fleets represent the largest procurement volumes.
- Commercial Entities:Retail chains, hospitality groups, and employers offering charging as an amenity. These users prioritize opex-based charging-as-a-service contracts over capital ownership.
- Government Facilities:Federal, state, and municipal installations with procurement governed by Buy America requirements and federal sustainability mandates. Florida state agencies and California municipal governments lead deployment timelines.
Fleets anchor the volume base for high-power infrastructure while commercial entities gain share fastest through service-based procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 5 corridor's electrification backbone underwrites California's primacy in solar-powered EV charging deployment, while Texas's ERCOT grid independence accelerates behind-the-meter solar adoption for fleet operators seeking rate arbitrage.
United States
California's Title 24 building standards mandate solar-ready commercial construction, preconditioning electrical infrastructure for integrated charging systems. The Inflation Reduction Act directs investment tax credits toward solar-plus-storage configurations, shortening capital recovery timelines for depot operators. Fleet electrification mandates from the California Air Resources Board compress procurement cycles for drayage and last-mile logistics operators across the Los Angeles-Long Beach port complex.
Germany
The Trans-European Transport Network's charging corridor concessions require lifecycle emissions documentation under the EU Green Deal's Fit for 55 package. The KBA enforces type-approval standards for high-power charging hardware, while the F-Gas Regulation phases down refrigerant-based thermal management for DC fast-charging electronics. Industrial clusters in Baden-Württemberg anchor manufacturing of silicon carbide power electronics for next-generation charging inverters.
China
Dual carbon goals from the State Council accelerate distributed solar generation for EV infrastructure across the Yangtze River Delta manufacturing belt. The MIIT issues GB standards for vehicle-to-grid interoperability, enabling bidirectional charging protocols for fleet battery asset monetization. Shenzhen's municipal government mandates 100% electric bus procurement with on-site solar generation for depot charging.
India
The PLI scheme for solar manufacturing reduces module import dependency for charging station integrators serving the Delhi-Mumbai Industrial Corridor. The CEA issues technical standards for grid-interconnected solar-plus-storage installations, while state-level electric vehicle policies in Maharashtra and Gujarat mandate renewable energy procurement for public charging networks. Bangalore's technology corridor concentrates software development for charging network management platforms.
Australia
The Australian Renewable Energy Agency funds solar-powered fast-charging corridors along the Hume Highway linking Sydney and Melbourne. State-level net-metering reforms in New South Wales and Victoria determine behind-the-meter solar economics for commercial fleet depots. The mining sector's electrification drives demand for off-grid charging units in Western Australia's Pilbara region.
Solar-Powered EV Charging Stations Market Competitive Landscape
Concentration sits with integrated hardware-software providers and specialized off-grid fabricators. The vendor base stratifies across three tiers: automotive-aligned charging networks with captive vehicle ecosystems, industrial electrical conglomerates leveraging grid-interconnection expertise, and transportable unit specialists serving emergency response niches. Dominant competitive moves include strategic partnerships between charging network operators and fleet management platforms, plus backward integration into solar module and battery cell production to secure supply chain control.
Among the named participants, ABB E-mobility and Tesla occupy positions as scale-driven integrators with established network footprints, while Beam Global exemplifies the transportable off-grid archetype for remote and resilient applications. ROA Energy, Enphase Energy, and Emporia Corp. sit within the distributed energy resource segment, representing residential and small-commercial system configurations. EVgo and Electrify America anchor the public charging network tier with highway corridor presence. Suryatech EV Power represents India-based manufacturing participation in the solar charging value chain.
| Leading Market Players |
|---|
| ROA Energy |
| ABB E-mobility |
| Beam Global |
| Electrify America |
| Tesla |
| Enphase Energy |
| Emporia Corp. |
| EVgo |
| Suryatech EV Power |
| Others |
Value Network & Pricing Analysis
Silicon carbide MOSFETs displacing legacy IGBT modules in DC fast-charging inverters simultaneously redraws procurement geography toward Baden-Württemberg manufacturing clusters and compresses pricing premiums for high-power configurations. This semiconductor transition concentrates value capture with tier 1 automotive suppliers while eroding margins for thermal management incumbents locked into refrigerant-based architectures.
Pricing Analysis
Volume-discount tiering structures separate fleet operators commanding charging-as-a-service contracts with guaranteed uptime SLAs from residential users purchasing standalone hardware. Three-tier pricing stratifies across premium fast-charging hubs with integrated solar-plus-storage, standard Level 2 workplace installations, and economy residential units. Cost compression in the economy tier intensifies because IRA tax credit arbitrage attracts price-sensitive entrants. Fleet procurement teams exhibit lowest price sensitivity due to binding electrification mandates and operational risk transfer preferences.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes constrain module integrators dependent on polysilicon and lithium carbonate feedstocks. Manufacturing concentrates in China for photovoltaic cells, South Korea for battery management systems, and Germany for silicon carbide power electronics. Cell price volatility represents the dominant structural risk, with energy storage comprising 35-40% of system capex. Distribution runs through EPC contractors and direct fleet procurement channels rather than traditional electrical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where software subscriptions and demand-response participation layers expand faster than hardware unit sales. Recurring revenue from networked station management and vehicle-to-grid integration protocols outpaces margin capture from standalone equipment.
For Market Incumbents: Shield installed base relationships by embedding charging-as-a-service contracts with guaranteed uptime SLAs before fleet operators consolidate vendor panels. Accelerate backward integration into solar module and battery cell production to secure supply chain control against lithium-ion cost volatility. Prioritize certification investment in UL 2743 and SAE J1772 standards to maintain procurement eligibility for government facilities. For New Entrants and Emerging Players: Certification fast-tracks through California's Title 24 pre-approval pathways open white-space penetration in commercial new construction where electrical infrastructure is preconditioned for integration. Target emergency response applications in hurricane-prone Florida and remote Texas staging areas where transportable off-grid units face minimal incumbent competition. Lead with mobile charging units for FEMA procurement cycles and municipal resilience budgets. For Investors and Strategic Acquirers: Capital is best deployed toward integrated hardware-software-service providers with demonstrated fleet operator relationships and recurring revenue traction. Long-term viability hinges on opex model adoption compressing capital ownership preferences among logistics operators. Monitor interconnection queue reform legislation as the inflection signal determining whether behind-the-meter solar configurations retain economic viability against time-of-use utility rates.| Strategic Initiative | Industry Significance |
|---|---|
| Charging-as-a-Service Contracting | Transferring operational risk to infrastructure providers locks in fleet procurement volumes across California and Texas. |
| Backward Integration into Battery Cells | Captive lithium-ion supply insulates project economics from cell price volatility transmitted through spot markets. |
| Vehicle-to-Grid Protocol Development | Bidirectional charging enablement allows fleet operators to monetize battery assets through frequency regulation services. |
| Solid-State Battery Architecture Transition | Next-generation thermal management displaces refrigerant-dependent cooling systems facing EU F-Gas phase-down schedules. |
| Title 24 Pre-Approved System Certification | California building code compliance accelerates commercial new construction penetration before competitors secure electrical contractor relationships. |
Research Methodology
Operator-level perspectives from fleet electrification managers, EPC contractors, utility interconnection planners, and charging network software engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FERC interconnection filings, EIA distributed generation databases, California Air Resources Board enforcement records, and IRA tax credit implementation guidance. Bottom-up unit economics modeling triangulated against top-down market sizing from solar-plus-storage deployment tracking.
Sensitivity analysis across battery cost trajectories, interconnection timeline scenarios, and fleet electrification mandate compliance schedules informed projection boundaries. Segmentation dimensions modeled include charger power tier, installation environment, network connectivity architecture, and end-user procurement centralization. CAGRs derived from logistic diffusion curves fitted to fleet operator adoption patterns and utility rate structure evolution across the analysis window. Silicon carbide adoption curves and solid-state battery commercialization timelines served as technology-specific forecast inputs.
Underlying assumptions cover IRA tax credit continuity, lithium-ion supply expansion, and interconnection queue processing rates, with deviation risk concentrated in federal policy reversal, raw material export restrictions, and net-metering reform timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Solar Power Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Residential Solar Shading System Market