
 Romania Oil and Gas Downstream Market | 2026-2036
Romania Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Oil and Gas Downstream Market Analytics
ISO 50001 energy management certification is rotating as a de facto gatekeeper for refinery operators seeking EU carbon border adjustment compliance. OMV Petrom leverages its integrated upstream-downstream footprint to secure feedstock flexibility across the Black Sea corridor. Rompetrol Rafinare anchors its position through heavy crude processing capability at the Vega refinery. MOL Romania competes via cross-border pipeline logistics linking Hungarian and Romanian distribution networks.
Romania oil and gas downstream operations encompass crude oil refining, natural gas processing, and the manufacture of petroleum derivatives including gasoline with maximum sulfur content, diesel meeting Euro 6 standards, and petrochemical feedstocks such as naphtha and propylene. These facilities serve industrial heat, vehicle propulsion, and polymer manufacturing across Southeast European supply chains. Refined Fuels commands the largest revenue pool given Romania's vehicle fleet density and transit corridor role, while Petrochemicals represents the fastest-expanding margin segment as regional polymer demand outpaces local supply. Lubricants occupies a mature, brand-loyal niche where direct sales to industrial accounts sustain premium pricing power against retail channel competition.
Romania's National Regulatory Authority for Energy (ANRE) governs wholesale fuel pricing transparency and storage obligation levels, while EU REACH and F-Gas Regulation constrain petrochemical process emissions and fluorinated gas use in refrigeration units at LNG terminals. ANRE's storage mandates create strategic inventory requirements that shape working capital intensity for all licensed distributors. Stakeholders must monitor how EU carbon border adjustment implementation affects import parity for Russian-origin crude substitutes versus Black Sea domestic production economics.
Market Dynamics
Romania's downstream oil and gas sector confronts a structural pivot as EU methane emissions rules force capital reallocation toward emission-abatement infrastructure at Black Sea processing facilities. This regulatory pressure compounds with the maturation of domestic offshore gas production, reshaping feedstock economics for Ploiești and Constanța refining complexes.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated refrigerants at LNG terminals are accelerating equipment replacement cycles across Romanian gas processing infrastructure, creating captive demand for low-GWP alternatives and retrofit services.
- Polymer manufacturing:Southeast European supply chains are pulling naphtha and propylene volumes northward from Constanța petrochemical integration projects as regional packaging and automotive component demand tightens local feedstock balances.
- Transit corridor expansion:Romania's position as a Black Sea-to-Central Europe fuel logistics hub is amplifying diesel and gasoline offtake from refineries serving Hungarian and Bulgarian distribution networks.
Market Restraints
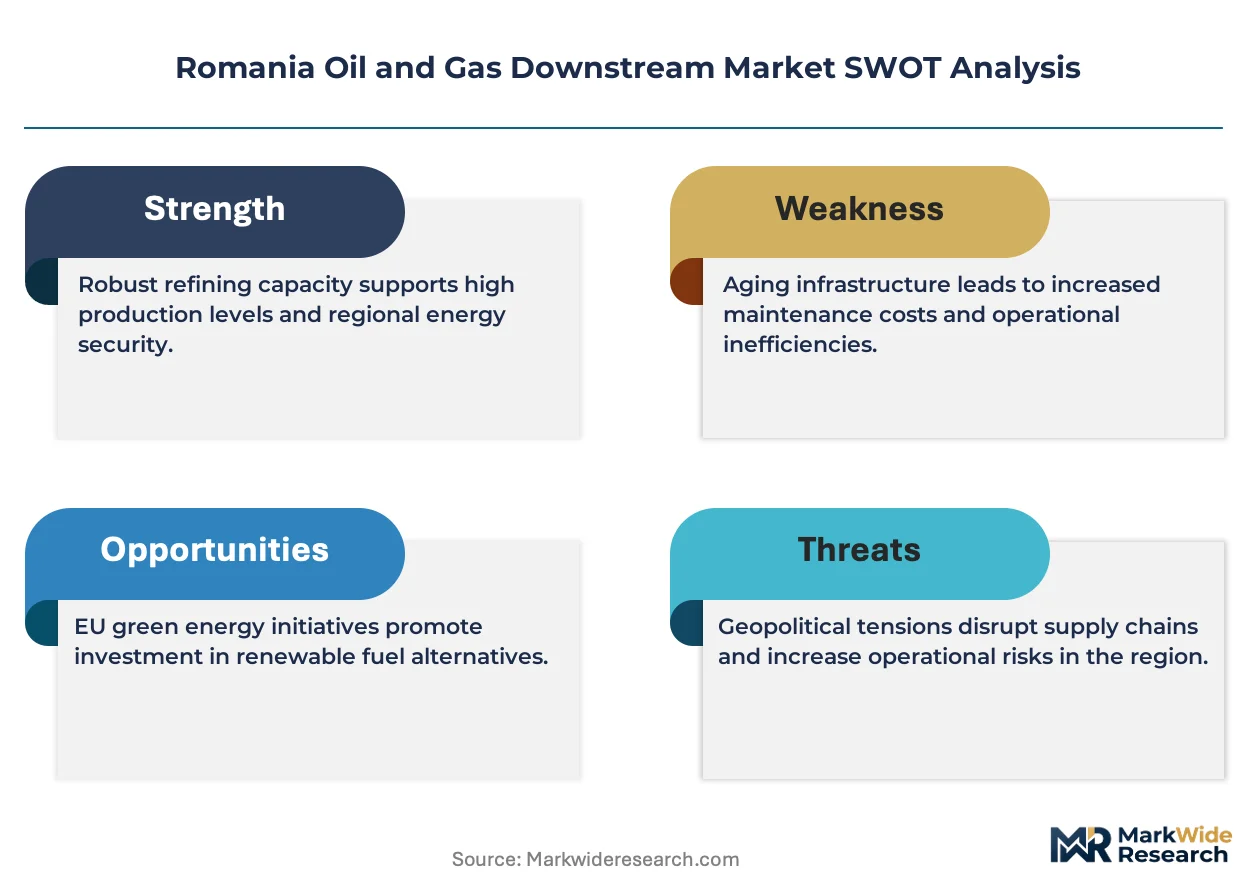
- Crude import dependency:Romanian refineries remain exposed to seaborne crude price volatility and quality variation as domestic Black Sea production volumes insufficiently cover Ploiești processing capacity.
- Carbon border adjustment mechanics:EU CBAM implementation is compressing import parity for Russian-origin crude substitutes, forcing working capital intensity adjustments at storage facilities governed by ANRE mandates.
- Electrification substitution:Battery-electric vehicle penetration in Romania's urban fleet is eroding long-term gasoline demand trajectories despite current transit corridor volumes.
Strategic Opportunities
- ANRE storage obligation arbitrage:Licensed distributors can monetize strategic inventory requirements through forward contracting structures as wholesale fuel pricing transparency rules tighten margin capture mechanics.
- Hydrogen blending infrastructure:Natural gas pipeline networks linking Romanian and Hungarian systems offer retrofit pathways for hydrogen carrier integration into existing downstream distribution assets.
- ISO 50001 certification differentiation:Energy management system accreditation is emerging as a procurement gatekeeper for industrial heat buyers seeking supply chain carbon accounting compliance.
Industry Challenges
- REACH compliance timeline:Petrochemical process emissions documentation under EU chemical registration protocols is stretching technical staff capacity at mid-sized refineries lacking dedicated regulatory affairs functions.
- Legacy SCADA integration:Cybersecurity hardening of decades-old process control systems at Vega and Petromidia facilities requires capital deployment without immediate throughput returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Oil and Gas Downstream Market |
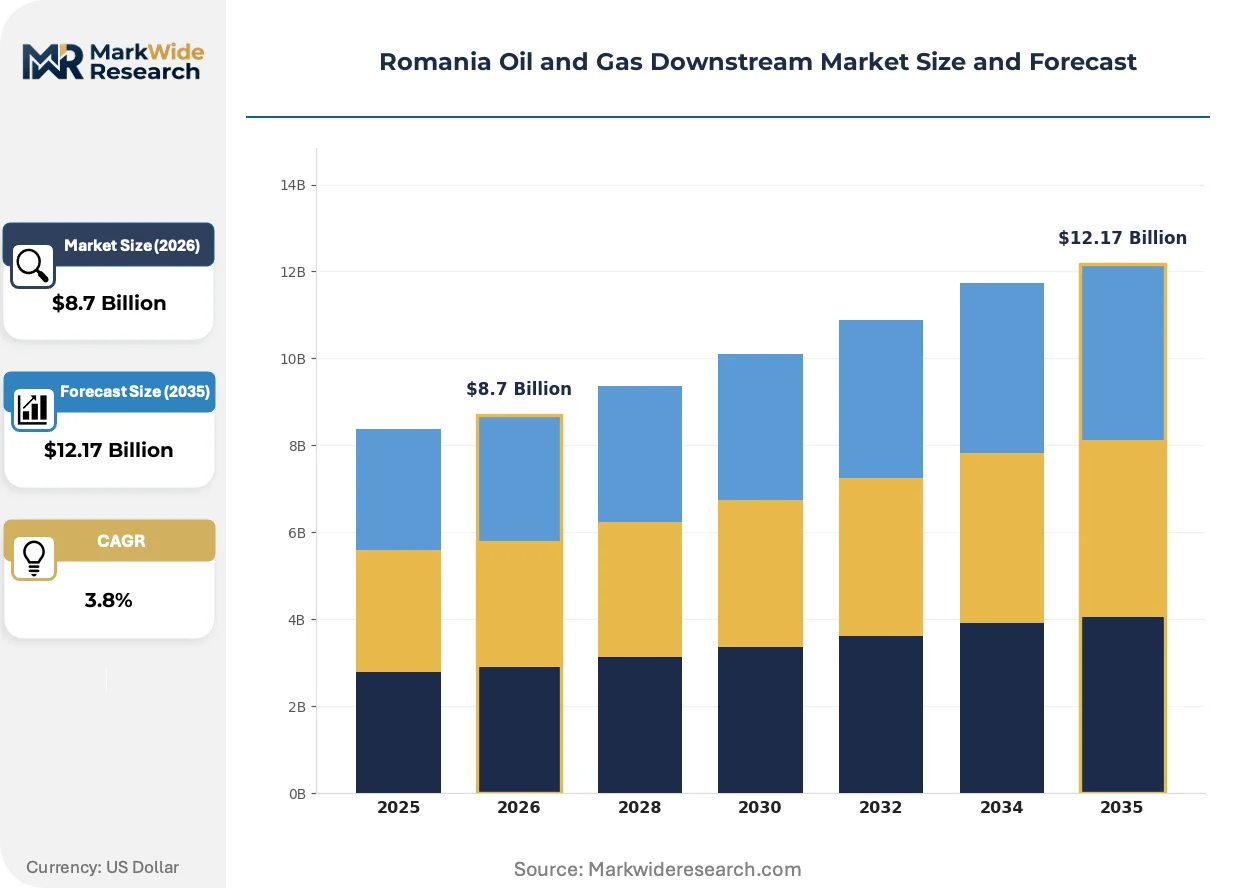
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalt End User: Transportation, Manufacturing, Retail, Power Generation Distribution Channel: Direct Sales, Wholesalers, Retail Outlets, Online Platforms Service Type: Logistics, Storage, Refining, Maintenance |
| Companies Covered | Total SA, MOL Romania, OMV Petrom, NIS Petrol, Black Sea Oil & Gas, Rompetrol Rafinare, Serinus Energy Company, Eni, Lukoil Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Oil and Gas Downstream Market Evolving Landscape
Digital instrumentation and process intensification are reshaping Romanian refining economics as operators balance emission abatement mandates against margin compression in middle distillate markets. Three developments are altering competitive positioning.
Advanced process control systems incorporating machine learning for crude unit optimization are bifurcating operational performance between early adopters and conventional operators. Ploiești refining complexes deploying predictive maintenance analytics are capturing 8-12 month payback periods on sensor infrastructure. This capability gap is compressing margin capture for facilities relying on scheduled turnaround cycles rather than condition-based intervention.
EU methane emissions regulations are mandating optical gas imaging and continuous monitoring installations at Black Sea offshore production tie-ins. Romanian downstream operators must now integrate leak detection data into ANRE reporting frameworks or face storage license penalties. Petrochemical feedstock producers are responding by contracting third-party verification services to maintain offtake eligibility with German and Austrian polymer manufacturers.
Industrial heat buyers are consolidating procurement around certified low-carbon fuel suppliers as Scope 3 accounting requirements propagate through automotive and packaging value chains. Direct sales contracts with ANRE-licensed distributors are displacing spot market purchasing for large manufacturing accounts in Argeș and Prahova counties. This concentration is most visible among cement and ceramics producers facing EU ETS compliance cost pass-through pressures.
Romania Oil and Gas Downstream Market Segmentation
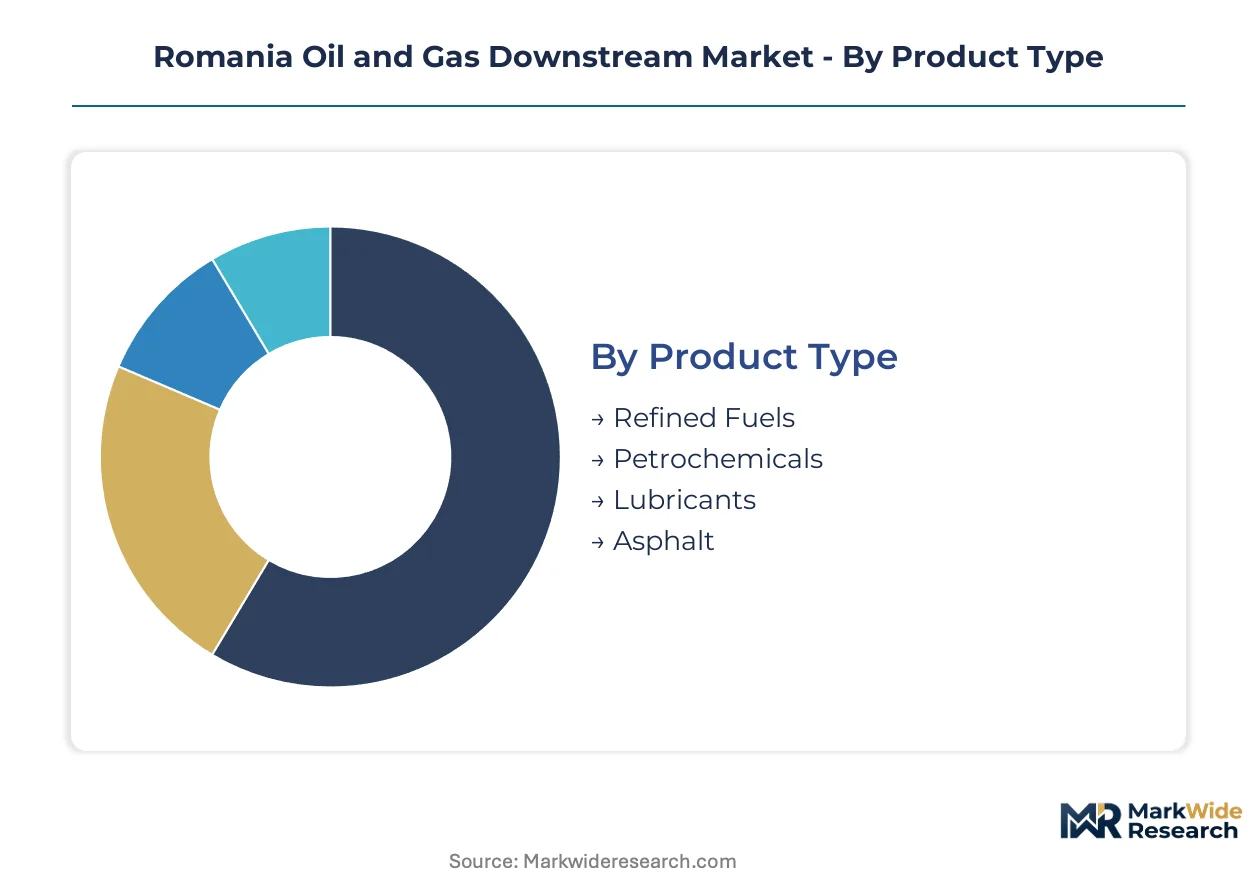
Downstream segmentation in Romania reveals how capital allocation priorities differ across product categories, end-use applications, and service delivery models. Margin capture mechanics vary substantially between refining operations governed by ANRE storage mandates and petrochemical integration projects serving Southeast European polymer demand.
Product Type:
Margin pools concentrate in refined fuels given Romania's vehicle fleet density and transit corridor role, while petrochemical integration offers the steepest expansion trajectory as regional feedstock balances tighten.
- Refined Fuels:Gasoline, diesel, and middle distillates meeting Euro 6 sulfur specifications dominate revenue generation. Transportation sector buyers in Bucharest and Ploiești counties sustain volume offtake, though battery-electric vehicle penetration in urban fleets is compressing long-term gasoline demand trajectories.
- Petrochemicals:Naphtha, propylene, and polymer feedstocks represent the fastest-climbing margin segment. Packaging and automotive component manufacturers across Argeș and Prahova counties are pulling volumes northward from Constanța integration projects as local supply falls short of regional demand.
- Lubricants:Brand-loyal industrial accounts in manufacturing clusters sustain premium pricing power through direct sales contracts.
- Asphalt:Road construction seasonality drives procurement patterns, with ANRE-licensed distributors managing inventory cycles for infrastructure contractors.
The dominant share belongs to Refined Fuels, while Petrochemicals is closing the gap fastest.
End User:
Application concentration determines working capital intensity, with transportation and manufacturing exhibiting divergent procurement behaviors.
- Transportation:Fleet operators and logistics companies across the Black Sea-to-Central Europe corridor generate the largest volume demand. Diesel offtake from refineries serving Hungarian and Bulgarian distribution networks amplifies throughput at Ploiești and Constanța facilities.
- Manufacturing:Cement and ceramics producers in Argeș and Prahova counties face EU ETS compliance cost pass-through pressures. These industrial heat buyers are consolidating procurement around certified low-carbon fuel suppliers as Scope 3 accounting requirements propagate through value chains.
- Retail:Consumer fuel purchasing through service station networks operates under ANRE wholesale pricing transparency rules.
- Power Generation:Natural gas-fired facilities integrate with Black Sea offshore production maturation under EU methane emissions regulations.
Transportation commands the largest volume position, though Manufacturing is gaining procurement sophistication fastest.
Distribution Channel:
Channel economics reflect customer scale and regulatory compliance burden, with direct sales offering margin protection against spot market volatility.
- Direct Sales:Large manufacturing accounts negotiate long-term contracts with ANRE-licensed distributors, displacing spot market purchasing. ISO 50001 certification requirements from industrial buyers favor established supplier relationships over transactional procurement.
- Wholesalers:Intermediate distributors manage strategic inventory requirements under ANRE storage mandates, creating working capital intensity that shapes margin capture mechanics.
- Retail Outlets:Service station networks serve consumer and light commercial demand with transparent pricing regulation.
- Online Platforms:Digital procurement channels are emerging for lubricant and specialty product segments.
Direct Sales holds the premium margin position, while Online Platforms are expanding access fastest.
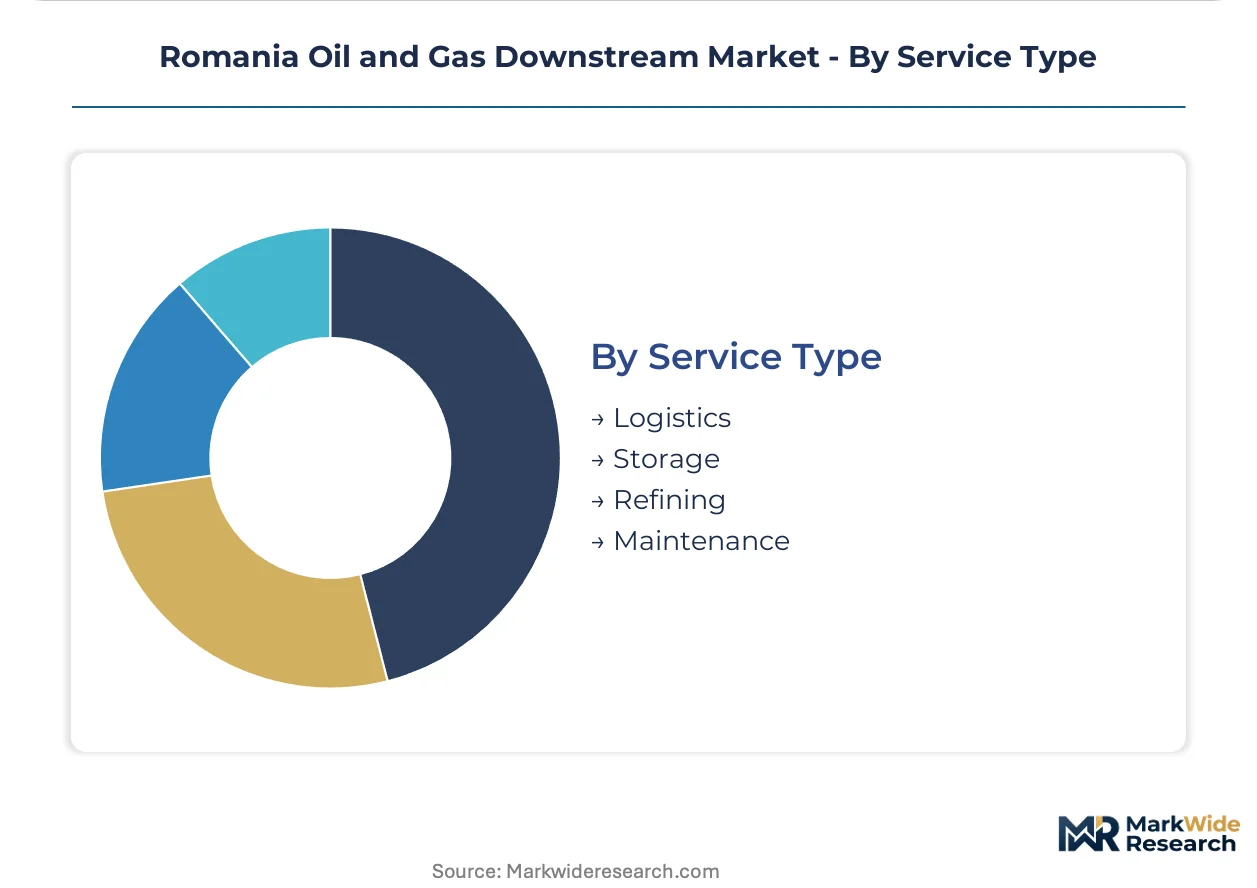
Service Type:
Service differentiation centers on asset control and regulatory compliance capabilities, with storage and logistics offering distinct competitive moats.
- Logistics:Cross-border pipeline networks linking Romanian and Hungarian systems enable MOL Romania to compete via integrated distribution assets. Hydrogen blending retrofit pathways are emerging as a future service extension.
- Storage:ANRE-mandated strategic inventory requirements create captive demand for licensed facility operators. Forward contracting structures allow distributors to monetize working capital intensity as wholesale fuel pricing transparency rules tighten.
- Refining:Heavy crude processing capability at Vega and Petromidia facilities anchors competitive positioning for complex feedstock economics.
- Maintenance:Predictive maintenance analytics deployment at Ploiești complexes is capturing payback periods that compress margin capture for facilities relying on scheduled turnaround cycles.
Storage commands the most defensible revenue stream, while Maintenance is digitizing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania's downstream oil and gas sector attracts concentrated investment from integrated energy buyers seeking Black Sea corridor feedstock security. These procurement-heavy archetypes cluster around Ploiești refining complexes and Constanța petrochemical integration projects.
Prahova County
Industrial heat buyers in Ploiești's refining corridor sustain diesel and naphtha offtake from Vega and Petromidia facilities. ANRE storage mandates govern working capital intensity for distributors serving manufacturing accounts across the county. Cement and ceramics producers in Câmpina and Ploiești are consolidating procurement around ISO 50001-certified fuel suppliers.
Constanța County
Petrochemical feedstock demand from Southeast European polymer manufacturers pulls propylene volumes northward from Constanța integration projects. EU F-Gas Regulation compliance drives equipment replacement cycles at LNG terminals along the Black Sea coast. The Port of Constanța anchors cross-border logistics linking Romanian and Bulgarian distribution networks.
Bucharest-Ilfov
Fleet operators and logistics companies in the capital region generate the largest refined fuels volume demand for gasoline and Euro 6 diesel. Battery-electric vehicle penetration in urban fleets is compressing long-term gasoline demand trajectories despite current transit corridor volumes. ANRE wholesale pricing transparency rules shape retail margin capture mechanics across service station networks.
Argeș County
Automotive component manufacturers in Pitești and surrounding industrial zones pull polymer feedstocks from Constanța petrochemical projects. Scope 3 accounting requirements propagate through packaging value chains, favoring direct sales contracts with ANRE-licensed distributors. EU ETS compliance cost pass-through pressures are cementing procurement consolidation among large manufacturing accounts.
Romania Oil and Gas Downstream Market Competitive Landscape
Player mix skews toward integrated upstream-downstream operators with captive Black Sea feedstock access. Market structure concentrates around three refining complexes with heavy crude processing capability and cross-border pipeline logistics. Strategic archetypes include integrated majors leveraging upstream-downstream footprints, regional midstream specialists optimizing storage and distribution assets, and petrochemical integrators capturing polymer demand pull from Southeast Europe. Dominant competitive moves center on refining capacity upgrades for petrochemical integration and hydrogen blending infrastructure retrofits on existing pipeline networks.
Within the integrated major tier, OMV Petrom and Rompetrol Rafinare anchor competitive positioning through control of Ploiești refining complexes and Black Sea corridor logistics. MOL Romania occupies a distinct position linking Hungarian and Romanian distribution networks via cross-border pipeline assets. These three entities exemplify how feedstock flexibility and storage license control under ANRE mandates create defensible margin capture mechanics in a market confronting EU methane emissions compliance and carbon border adjustment pressures.
| Leading Market Players |
|---|
| Total SA |
| MOL Romania |
| OMV Petrom |
| NIS Petrol |
| Black Sea Oil & Gas |
| Rompetrol Rafinare |
| Serinus Energy Company |
| Eni |
| Lukoil Oil Company |
| Others |
Value Network & Pricing Analysis
Russian-origin crude substitution by Black Sea domestic production simultaneously redraws supply geography toward Constanța and Ploiești corridors and compresses import parity economics under EU carbon border adjustment mechanics. This feedstock pivot forces ANRE-licensed distributors to reprice strategic inventory holdings as working capital intensity rises with storage mandate compliance.
Pricing Analysis
Cost-plus contracts indexed to Platts Black Sea crude assessments dominate refined fuels procurement, with ANRE wholesale transparency rules capping margin capture for licensed distributors. Price differentiation separates ISO 50001-certified industrial suppliers from spot-market wholesalers serving retail channels. Cost compression in middle distillates is intensifying because EU methane emissions compliance adds processing overhead at Black Sea facilities. Fleet operators across the Bucharest-Ilfov corridor exhibit highest price sensitivity, while cement and ceramics manufacturers in Argeș and Prahova counties prioritize carbon-accounting certification over unit cost.
Supply Chain Analysis
Strategic stockpiling mandated by ANRE storage obligations overrides just-in-time preferences across Romanian downstream operations, creating captive demand for licensed facility operators. Feedstock draws from Kazakhstan, Azerbaijan, and domestic Black Sea offshore fields, with naphtha, propylene, and heavy sour crude anchoring input dependencies. Single-source vulnerability concentrates in cross-border pipeline segments linking Hungarian and Romanian distribution networks. Distribution runs through ANRE-licensed wholesaler networks into direct sales contracts with large manufacturing accounts and retail service station channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's downstream oil and gas sector tracks a cyclical recovery as Black Sea offshore production maturation restores domestic feedstock security after years of import dependency. Capital allocation now favors operators with integrated storage and processing assets.
For Market Incumbents: Shield margin capture by securing ISO 50001 certification ahead of EU carbon border adjustment full implementation, locking in industrial heat buyer procurement consolidation. Prioritize backward integration into Black Sea offshore production tie-ins to reduce seaborne crude price exposure. Defend against hydrogen blending infrastructure retrofits by MOL Romania through early pipeline network upgrade commitments. For New Entrants and Emerging Players: Differentiate on low-GWP refrigerant retrofit services at Constanța LNG terminals, exploiting EU F-Gas Regulation phase-down mandates as entry wedge. Target ANRE storage obligation arbitrage through forward contracting structures with mid-sized distributors lacking working capital scale. Penetrate polymer feedstock supply gaps in Argeș County automotive component manufacturing through direct sales relationships. For Investors and Strategic Acquirers: EU carbon border adjustment implementation reshapes the acquisition landscape toward heavy crude processing capability and cross-border pipeline control. Five-to-ten year viability favors integrated upstream-downstream footprints with ANRE license portfolios over pure-play distribution assets. Watch for hydrogen carrier integration announcements on Romanian-Hungarian pipeline networks as inflection signal for infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Petrochemical Integration Project | Captures regional polymer demand pull from Southeast European packaging manufacturers into Constanța facilities. |
| ISO 50001 Certification Program | Secures procurement eligibility with EU ETS-facing cement and ceramics producers in Prahova County. |
| Hydrogen Blending Infrastructure Retrofit | Extends asset life of cross-border pipelines linking Romanian and Hungarian distribution networks. |
| Heavy Crude Processing Upgrade | Preserves feedstock flexibility as Kazakh and Azerbaijani crude quality variation intensifies. |
| Long-term Supply Agreement | Locks in offtake from Black Sea offshore production maturation under EU methane emissions rules. |
Research Methodology
Operator-level perspectives from refinery operations managers, ANRE regulatory affairs leads, petrochemical procurement directors, and cross-border logistics coordinators anchored the qualitative base. These primary interviews combined with customs and trade data, ANRE storage license disclosures, EU ETS compliance filings, and Black Sea crude import statistics. Bottom-up segment sizing triangulated against top-down macroeconomic energy demand projections.
Sensitivity analysis tested forecast robustness across crude price volatility bands, EU carbon border adjustment implementation timelines, and Black Sea production ramp scenarios. Segmentation modeling spanned product type, end-user application, distribution channel, and service delivery mode throughout the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure commissioning schedules. Forecast inputs incorporated ANRE mandate compliance costs and EU methane emissions monitoring technology adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory tightening and Black Sea production maturation; material deviation would warrant model refresh. Revision becomes warranted when battery-electric vehicle penetration in Romanian urban fleets crosses threshold levels that structurally compress gasoline demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Gold Mining Market
Oil & Gas
Crown Block Market
Oil & Gas
Mud Balance Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Well Cementing Market
Oil & Gas
US Sand Control Systems Market