
 Geothermal Drilling Market | 2026-2036
Geothermal Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Drilling Market Intelligence
Kenya's Rift Valley is rewriting East African geothermal development timelines with aggressive capacity additions at Olkaria and Menengai fields. Fervo Energy leverages horizontal drilling techniques adapted from shale basins to unlock enhanced geothermal systems in Nevada's Great Basin. Sage Geosystems sustains a differentiated position through closed-loop reservoir engineering that eliminates subsurface water consumption. AltaRock Energy anchors its competitive stance on deep drilling capabilities targeting supercritical geothermal resources below conventional accessible depths.
Geothermal drilling encompasses the mechanical penetration of subterranean formations to access hydrothermal or petrothermal heat resources, typically achieving depths between 1,500 and 4,000 meters depending on reservoir temperature gradients and geological complexity. The process employs rotary drilling with specialized mud systems to maintain borehole stability while circulating heat-resistant drilling fluids rated for temperatures exceeding 300°C. Rotary drilling methods dominate installed capacity due to proven reliability in volcanic and sedimentary formations, though air drilling variants are gaining traction in hard-rock crystalline environments where lost circulation presents operational risks. Production drilling services capture the largest revenue share as developers transition from exploratory phases to multi-well field development, while downhole tools represent a concentrated margin pool given thermal durability requirements and limited supplier bases.
The U.S. Department of Energy and Kenya's Energy Regulatory Commission shape project economics through drilling cost-share mechanisms and feed-in tariff structures respectively, while ISO standards govern equipment thermal ratings and safety protocols. EPA underground injection control permits and local aquifer protection statutes constrain drilling fluid disposal and well completion practices across American projects. Stakeholders must monitor regulatory treatment of induced seismicity protocols and water use permitting, as these approval timelines increasingly determine project finance viability and development sequencing.
Market Dynamics
Enhanced geothermal systems are compressing development timelines through millimeter-wave drilling breakthroughs that vaporize rock without mechanical abrasion, fundamentally altering cost structures for deep resource access.
Growth Catalysts
- US Department of Energy Funding:Cost-share mechanisms for demonstration projects de-risk capital deployment for supercritical resource targeting.
- Grid Stabilization Mandates:Utility-scale power producers in California and Hawaii prioritize baseload geothermal over battery-backed solar for frequency regulation.
- Horizontal Drilling Transfer:Techniques adapted from Permian Basin shale operations unlock low-permeability formations previously classified as non-commercial.
Market Restraints
- Tungsten Carbide Supply Concentration:China controls 80% of global hardmetal production for drill bit manufacturing, creating input vulnerability.
- Induced Seismicity Protocols:EPA Class VI underground injection control permits impose 18-24 month approval cycles in seismically sensitive zones.
- Shallow Geothermal Substitution:Ground-source heat pumps for commercial buildings capture building-level thermal demand without reservoir drilling.
Strategic Opportunities
- Indonesia's Ring of Fire:Untapped high-enthalpy resources in Sumatra and Sulawesi offer 3,000 MW of undeveloped potential with existing transmission corridors.
- Closed-Loop Systems:Engineered reservoirs eliminate aquifer contamination risks and expand viable geology to dry hot rock formations.
- EU Green Deal Taxonomy:Classification of geothermal as sustainable finance-eligible lowers weighted average cost of capital for European developers.
Industry Challenges
- Directional Drilling Expertise Gap:Shortage of petrothermal reservoir engineers with combined geological and drilling optimization skills extends project staffing cycles.
- High-Temperature Electronics Certification:Downhole measurement tools rated above 250°C require extended validation timelines under ISO 17025 thermal testing protocols.
- Legacy Well Recompletion Complexity:Converting abandoned oil and gas boreholes to geothermal production demands casing integrity assessments that delay field development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Drilling Market |
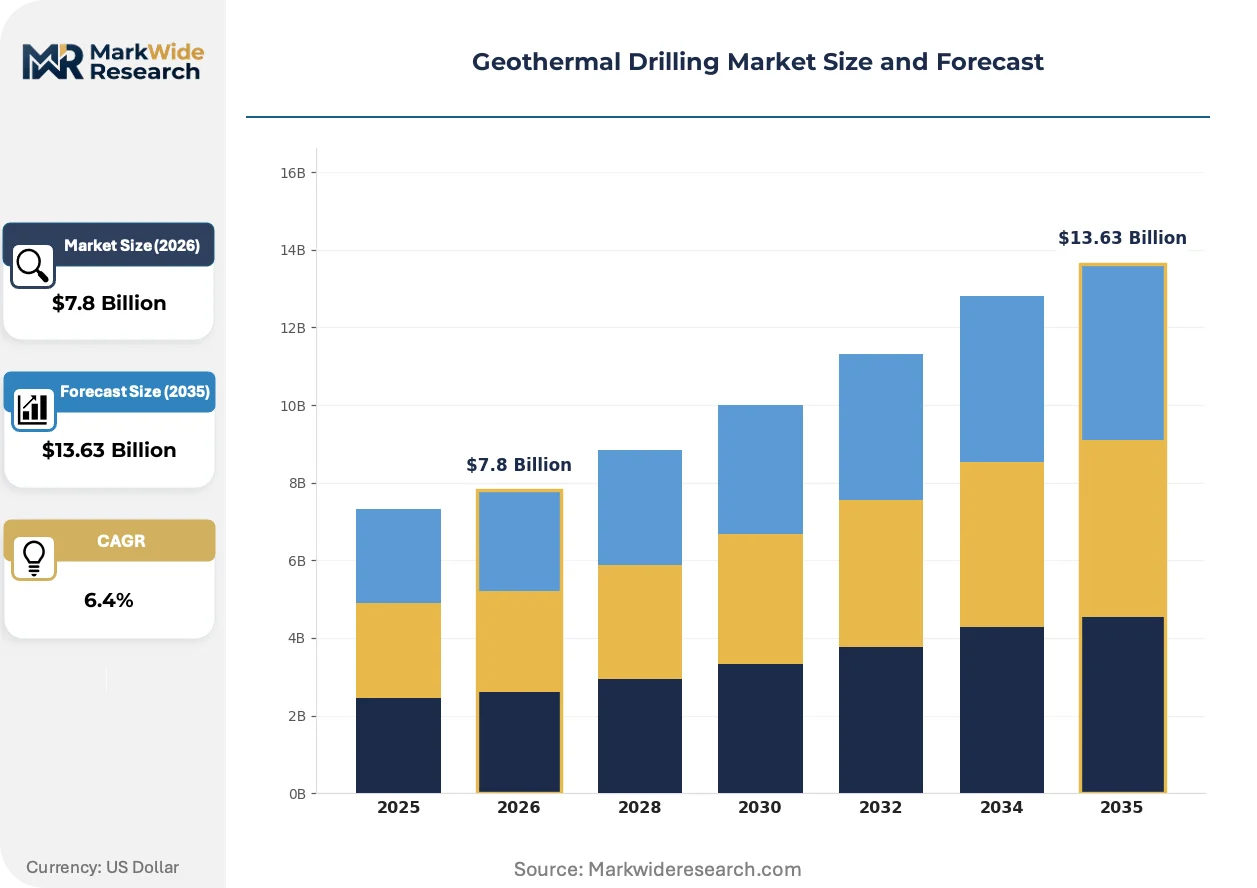
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drilling Method: Rotary Drilling, Dual Mud System, Continuous Circulation, Air Drilling Service Type: Exploratory Drilling, Production Drilling, Well Maintenance, Site Assessment Equipment Type: Drill Rigs, Mud Pumps, Downhole Tools, Wellheads End User: Geothermal Power Plants, Research Institutions, Government Agencies, Private Developers |
| Companies Covered | AltaRock Energy, Sage Geosystems, Fervo Energy, Cyrq Energy, Zanskar, Quaise Energy, XGS Energy, Bedrock Energy, GA Drilling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Drilling Market Strategic Shifts & Innovations
Digital twin integration and advanced subsurface imaging are compressing exploration risk profiles while automated rig systems reshape labor economics across drilling operations.
Millimeter-wave directed energy drilling is virtualizing mechanical rock removal by using gyrotron-generated electromagnetic radiation to fracture crystalline basement formations without bit wear. Nevada-based demonstration projects are validating this approach for 10+ kilometer depths. The technology is virtualizing traditional rotary rig deployment schedules and eliminating tripping operations that consume 40% of conventional drilling time.
EU F-Gas Regulation phase-down mandates are accelerating adoption of carbon dioxide as a working fluid in closed-loop geothermal systems, displacing hydrofluorocarbons with high global warming potential. German and Dutch project developers now specify CO2-based designs for direct-use heating networks. District heating operators in Copenhagen and Rotterdam are retrofitting existing geothermal wells for CO2 circulation to maintain regulatory compliance.
Integrated service contracting is consolidating exploration, drilling, and reservoir management under single-vendor accountability structures that transfer geological risk from developers to drilling contractors. European utilities now favor full-wrap EPC arrangements over segmented procurement. This consolidation is most advanced in Kenya's Rift Valley corridor, where KenGen has moved to performance-based drilling contracts with guaranteed flow rate minimums.
Geothermal Drilling Market Segmentation
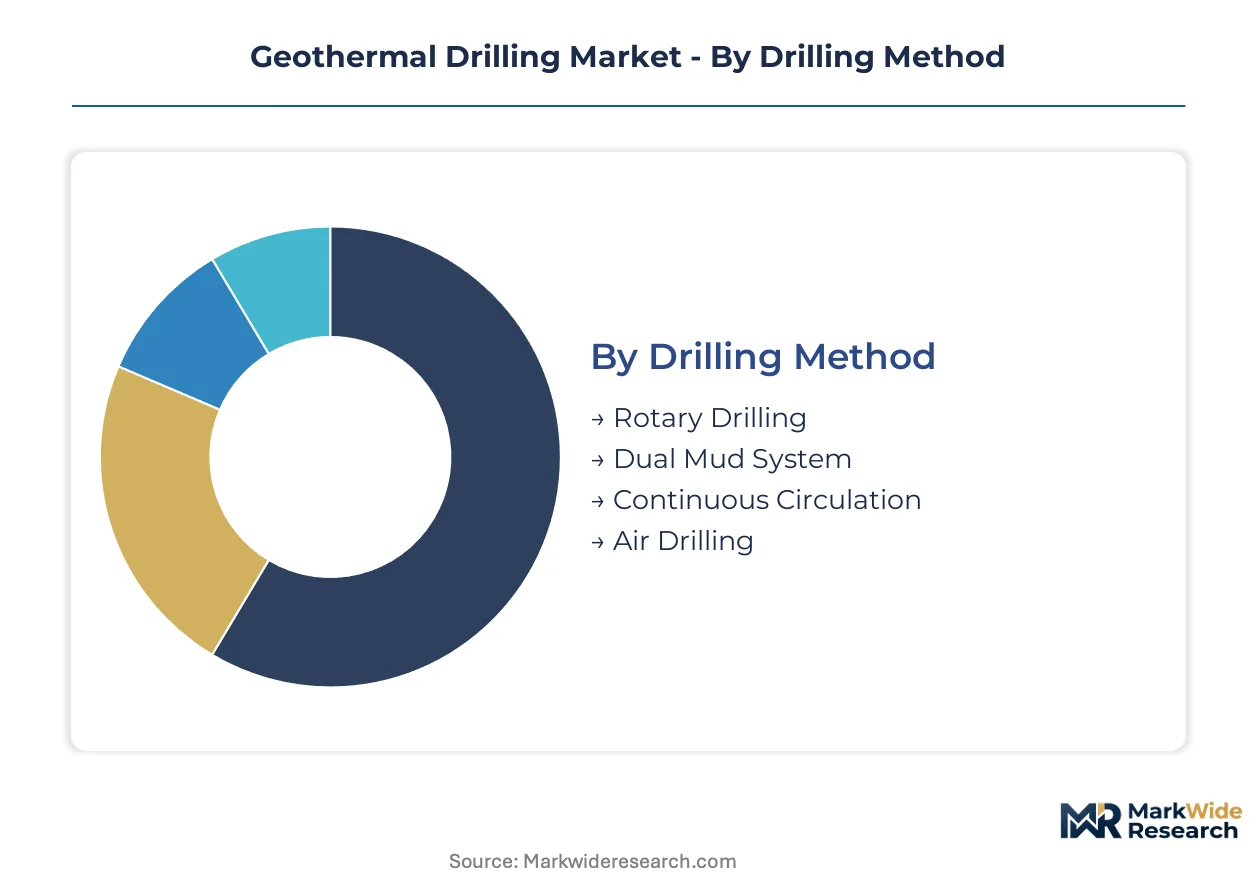
Geothermal drilling segmentation reveals distinct equipment lifecycle patterns and service intensity profiles across development phases. Each category carries implications for capital deployment timing, technical competency requirements, and aftermarket revenue capture.
Drilling Method:
Aftermarket service intensity varies dramatically by drilling method, with hard-rock crystalline formations demanding more frequent bit replacement and mud system rehabilitation than sedimentary targets.
- Rotary Drilling:Conventional rotary methods employ tricone or PDC bits with weighted drilling fluids to maintain borehole stability in volcanic and sedimentary formations. Utility-scale developers in Nevada's Great Basin and Kenya's Rift Valley corridor specify rotary rigs for production well campaigns where proven reliability outweighs speed advantages.
- Dual Mud System:This configuration circulates separate fluid formulations through concentric drill strings, enabling precise pressure management in high-temperature fractured zones. Enhanced geothermal system developers targeting supercritical resources below 4,000 meters specify dual mud architectures to mitigate lost circulation events that stall conventional operations.
- Continuous Circulation:Maintains uninterrupted fluid flow during pipe connections, reducing pressure spikes that destabilize fractured formations in Indonesia's Sumatra high-enthalpy fields.
- Air Drilling:Compressed air or mist systems eliminate formation damage in hard-rock crystalline basement where water-based fluids trigger clay swelling and permeability reduction.
Rotary Drilling holds the largest share; momentum sits with Dual Mud System.
Service Type:
Contracting structures increasingly bundle services across the development cycle, with performance guarantees shifting geological risk from developers to drilling contractors.
- Production Drilling:Multi-well field development campaigns require sustained rig deployment over 12-24 month cycles with guaranteed flow rate minimums. KenGen's performance-based contracts in Kenya's Olkaria fields exemplify this model, where contractors assume reservoir productivity risk in exchange for premium day rates.
- Exploratory Drilling:Slim-hole characterization programs reduce upfront capital exposure before full-field commitment. Iceland's National Energy Authority funds exploratory campaigns through cost-share mechanisms that de-risk private developer entry into untapped volcanic systems.
- Well Maintenance:Workover rigs restore productivity in mature fields through scale removal, casing repair, and pump replacement.
- Site Assessment:Geophysical surveying and temperature gradient drilling precedes formal exploration permitting.
Production Drilling dominates revenue capture; exploratory activity is climbing the fastest in frontier provinces.
Equipment Type:
Capital equipment procurement concentrates in integrated packages, though downhole tools command disproportionate margin pools due to thermal durability requirements.
- Downhole Tools:Measurement-while-drilling assemblies, logging tools, and steering systems rated above 250°C require extended ISO 17025 thermal validation timelines. Limited supplier bases for high-temperature electronics create pricing power for certified vendors serving supercritical resource developers.
- Drill Rigs:Automated mast systems and iron roughnecks reshape labor economics across extended-reach drilling campaigns. Quaise Energy's millimeter-wave demonstrations in Nevada are virtualizing conventional rig deployment for deep basement penetration.
- Mud Pumps:High-pressure positive displacement units circulate specialized formulations resistant to thermal degradation above 300°C.
- Wellheads:Pressure-containing assemblies must accommodate thermal expansion cycles and corrosive brine chemistry across 30-year operational lifespans.
Drill Rigs represent the largest capital category; downhole tools carry the steepest expansion trajectory as depth targets intensify.
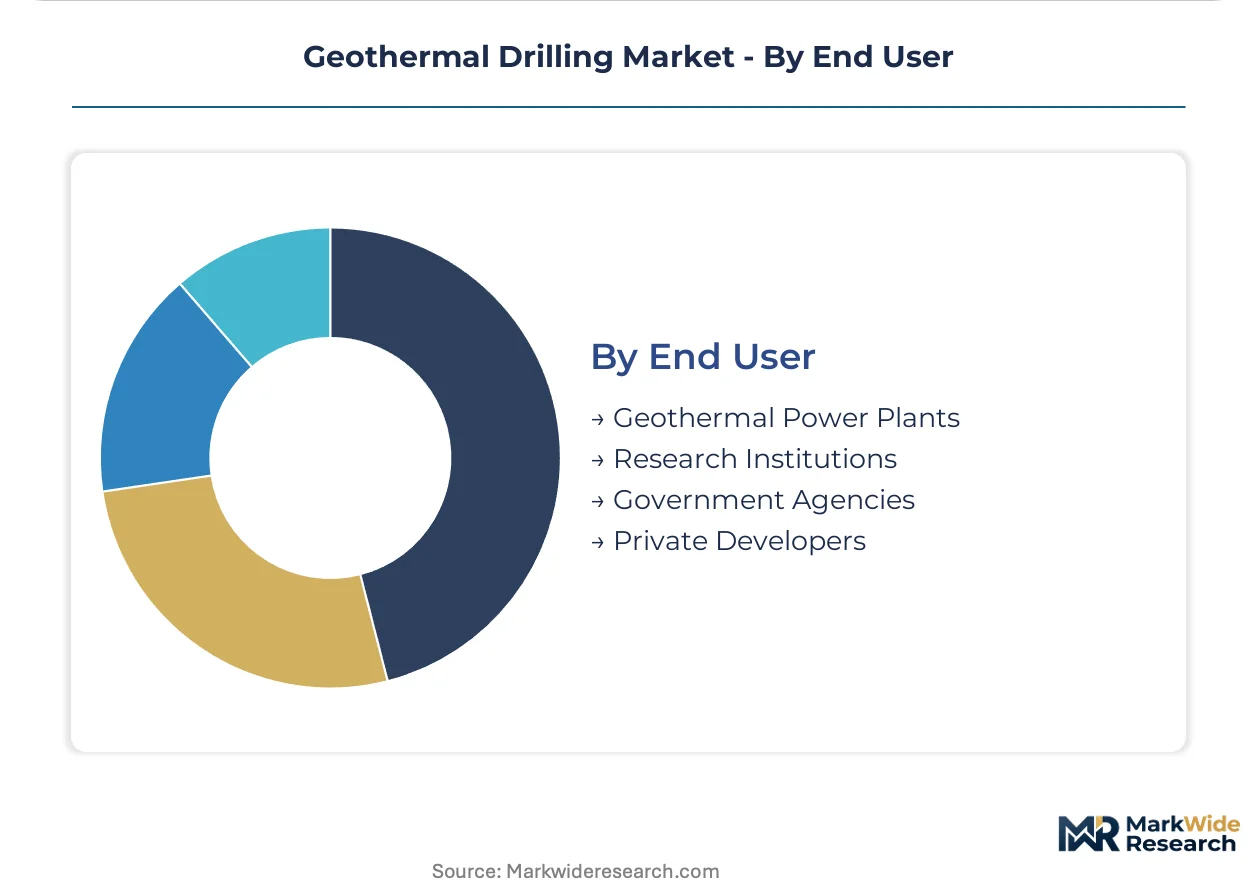
End User:
Customer sophistication and procurement scale separate utility-scale developers from institutional and governmental counterparts.
- Geothermal Power Plants:Utility-scale operators in California, Hawaii, and Kenya's Rift Valley corridor prioritize baseload capacity additions with multi-decade power purchase agreements. Grid stabilization mandates from California ISO drive preference for geothermal frequency regulation over battery-backed solar alternatives.
- Private Developers:Independent power producers leverage horizontal drilling transfers from Permian Basin shale operations to unlock low-permeability formations. Fervo Energy's Nevada deployments demonstrate commercial viability of enhanced geothermal systems through oilfield technique adaptation.
- Government Agencies:National energy authorities in Iceland and Kenya fund exploratory infrastructure and resource characterization.
- Research Institutions:University consortia and national laboratories validate novel drilling technologies and reservoir engineering approaches.
Geothermal Power Plants command the largest procurement volumes; private developers are gaining share fastest as project finance structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy anchors project economics through cost-share mechanisms and supercritical resource demonstration programs. Kenya's Energy Regulatory Commission and Iceland's National Energy Authority shape parallel development corridors through feed-in tariff structures and exploratory infrastructure funding.
United States
California ISO grid stabilization mandates and Hawaii's renewable portfolio standards drive utility-scale baseload procurement. EPA Class VI underground injection control permits impose 18-24 month approval cycles for seismically sensitive zones. Nevada's Great Basin hosts Fervo Energy's horizontal drilling deployments and Quaise Energy's millimeter-wave demonstrations targeting deep basement formations.
Kenya
KenGen's performance-based drilling contracts with guaranteed flow rate minimums attract international rig operators to the Rift Valley corridor. The Energy Regulatory Commission's feed-in tariff structures de-risk capital deployment for independent power producers. Olkaria and Menengai fields concentrate aggressive capacity additions with existing transmission infrastructure.
Iceland
The National Energy Authority funds exploratory campaigns through cost-share mechanisms that reduce upfront private developer exposure. EU Green Deal Taxonomy classification of geothermal as sustainable finance-eligible lowers weighted average cost of capital. Volcanic systems in the Reykjanes Peninsula and Krafla region host high-enthalpy resource characterization programs.
Indonesia
Untapped high-enthalpy resources in Sumatra and Sulawesi offer substantial undeveloped potential with existing transmission corridors. The country's national energy regulator oversees resource licensing frameworks for foreign developer entry. Continuous circulation drilling specifications dominate procurement for fractured formation stability in the Ring of Fire volcanic arc.
Germany
EU F-Gas Regulation phase-down mandates accelerate carbon dioxide working fluid adoption in closed-loop district heating networks. German project developers now specify CO2-based designs for direct-use heating applications. The Upper Rhine Graben and North German Basin host deep drilling campaigns targeting sedimentary reservoir targets.
Geothermal Drilling Market Key Industry Players
Integrated technology developers and specialized drilling contractors split the market based on depth targeting capabilities and reservoir engineering competencies. The competitive terrain concentrates around three strategic archetypes: millimeter-wave directed energy specialists, horizontal drilling adapters from oilfield service backgrounds, and closed-loop reservoir engineers. Dominant competitive moves include strategic partnerships with utility-scale power producers and technology licensing arrangements for geothermal-specific intellectual property.
Among US-based technology developers, AltaRock Energy, Fervo Energy, and Quaise Energy occupy distinct positions within the competitive matrix. AltaRock Energy exemplifies the deep drilling archetype targeting supercritical resources below conventional accessible depths. Fervo Energy represents the horizontal drilling transfer model adapted from Permian Basin shale operations to unlock low-permeability formations. Quaise Energy anchors the directed energy tier through millimeter-wave demonstrations that virtualize mechanical rock removal for 10+ kilometer depth targets.
| Leading Market Players |
|---|
| AltaRock Energy |
| Sage Geosystems |
| Fervo Energy |
| Cyrq Energy |
| Zanskar |
| Quaise Energy |
| XGS Energy |
| Bedrock Energy |
| GA Drilling |
| Others |
Cost & Logistics Intelligence
Rig utilization rates below 70% in North American onshore markets are compressing day-rate premiums for conventional rotary drilling, forcing contractors to bundle reservoir engineering services and accept performance-based contract structures that transfer productivity risk from developers.
Pricing Analysis
Day-rate spreads between Nevada's Great Basin and Indonesia's Sumatra high-enthalpy fields exceed 40% for equivalent rig specifications, reflecting mobilization costs and regulatory compliance burdens. Project-based long-term offtake structures dominate utility-scale procurement, with price differentiation anchored in certification tier (ISO 17025 thermal validation) and guaranteed flow rate minimums. Cost compression in standard rotary drilling services is intensifying because horizontal drilling transfers from oilfield operators are expanding qualified contractor pools. Independent power producers exhibit highest price sensitivity due to limited project finance track records, while KenGen and California utilities prioritize reservoir productivity guarantees over rate minimization.
Supply Chain Analysis
US export controls on high-temperature electronics and gyrotron components are constraining millimeter-wave drilling technology flows to non-allied markets, fragmenting equipment availability across development corridors. Manufacturing concentration for tungsten carbide drill bits rests on China, Germany, and Sweden, with rare earth magnet supply for downhole motors drawing from Chinese and Vietnamese processing facilities. Single-source vulnerability in superalloy forging capacity for wellhead assemblies creates procurement bottlenecks for supercritical resource developers. Distribution runs through integrated service contractors who consolidate exploration, drilling, and reservoir management under single-vendor accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards combined geological and drilling optimization competencies that remain scarce across both incumbent oilfield service firms and emerging geothermal specialists, creating persistent staffing cycle extensions for enhanced geothermal system developers.
For Market Incumbents: Entrench competitive position through backward integration into high-temperature electronics certification and captive supply of tungsten carbide hardmetal components, insulating against China supply concentration while building proprietary drilling optimization IP. Prioritize performance-based contract structures that transfer reservoir productivity risk from utility offtakers, defending margin position against horizontal drilling specialists entering from Permian Basin shale operations. For New Entrants and Emerging Players: Build out closed-loop reservoir engineering capabilities targeting Germany's Upper Rhine Graben and the Netherlands' North German Basin, where EU F-Gas Regulation phase-down mandates are accelerating carbon dioxide working fluid adoption. Indonesia's untapped Sumatra and Sulawesi high-enthalpy corridors offer the most penetrable geography given existing transmission infrastructure and limited incumbent saturation. Lead with district heating network integration expertise rather than power generation optimization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical resource targeting below 4,000 meters, as millimeter-wave drilling demonstrations validate deep basement penetration economics. Long-term viability over the next decade hinges on technology licensing arrangements that monetize horizontal drilling and directed energy IP across multiple development corridors. Target acquisition archetypes: integrated service contractors with guaranteed flow rate contract experience in Kenya's Rift Valley or Iceland's volcanic systems. The signal to watch is EPA Class VI permit approval velocity in seismically sensitive zones, as regulatory timeline compression would unlock stranded project finance commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Arrangement | Millimeter-wave drilling IP from Quaise Energy accelerates deep resource access for utility-scale developers. |
| Performance-Based Drilling Contract | KenGen's guaranteed flow rate minimums transfer reservoir productivity risk to contractors and attract international rig operators. |
| Backward Integration into Hardmetals | Captive tungsten carbide supply mitigates China concentration vulnerability for drill bit manufacturing. |
| Closed-Loop System Specification | CO2-based designs in German district heating networks eliminate aquifer contamination risks and maintain EU F-Gas regulatory compliance. |
| Horizontal Drilling Capability Transfer | Permian Basin technique adaptation unlocks low-permeability formations previously classified as non-commercial in Nevada's Great Basin. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, independent power producer project developers, EPC contractors, geothermal reservoir engineers, and drilling rig operators, cross-referenced against EIA geothermal project databases, IEA renewable energy technology roadmaps, FERC interconnection filings, and national energy authority exploratory campaign disclosures, with bottom-up well count and capacity addition estimates triangulated against top-down market value reconstructions.
Calibration against historical deployment trajectories in Kenya's Rift Valley and Nevada's Great Basin anchored the analytical framework across the projection horizon, with segmentation dimensions spanning drilling method, service type, equipment category, and end-user archetype. CAGRs were derived from installed capacity buildout curves and capital intensity benchmarks for supercritical versus conventional hydrothermal resources, incorporating millimeter-wave technology maturation timelines and EPA Class VI permit approval velocity as industry-specific inflection inputs.
Stress conditions across tungsten carbide supply disruption, induced seismicity protocol tightening, and shallow geothermal substitution by ground-source heat pumps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology cost reduction curves and regulatory treatment evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Underreamers Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Mud Balance Market
Oil & Gas
India AI in Oil and Gas Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Corrosion Protection Market