
 LAMEA Oilfield Auxiliary Rental Equipment Market | 2026-2036
LAMEA Oilfield Auxiliary Rental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Oilfield Auxiliary Rental Equipment Market Analytics
The EU Green Deal's methane emissions reduction framework is pivoting offshore operators toward rental equipment with certified leak-detection systems. Schlumberger Limited leverages its integrated drilling technology portfolio to bundle auxiliary rentals with digital monitoring platforms. Weatherford International plc anchors its LAMEA position through specialized wellhead rental services in Brazilian deepwater fields. Halliburton Company differentiates via localized maintenance hubs that reduce equipment mobilization times across West African offshore blocks.
Oilfield auxiliary rental equipment encompasses mobile, modular assets—including drilling rigs, pumps, generators, and compressors—deployed on temporary contracts to support hydrocarbon extraction operations, typically rated for pressure ranges exceeding 10,000 psi and designed for rapid rig-up in remote locations. Short-term rentals command premium pricing in exploration phases where equipment utilization cycles remain unpredictable, while long-term rentals generate stable revenue streams tied to production maintenance contracts. Well intervention applications exhibit the fastest structural expansion as aging LAMEA fields require more frequent workovers, with maintenance services capturing margin pools through bundled service-level agreements.
ANP, Brazil's national petroleum regulator, enforces strict equipment certification standards for offshore operations, while Nigeria's Department of Petroleum Resources mandates local content participation that reshapes supplier qualification criteria. Angola's petroleum ministry imposes fleet modernization requirements that accelerate replacement of legacy auxiliary equipment. Stakeholders must monitor how evolving local content thresholds and decarbonization mandates reshape competitive access across the LAMEA rental equipment value chain.
Market Dynamics
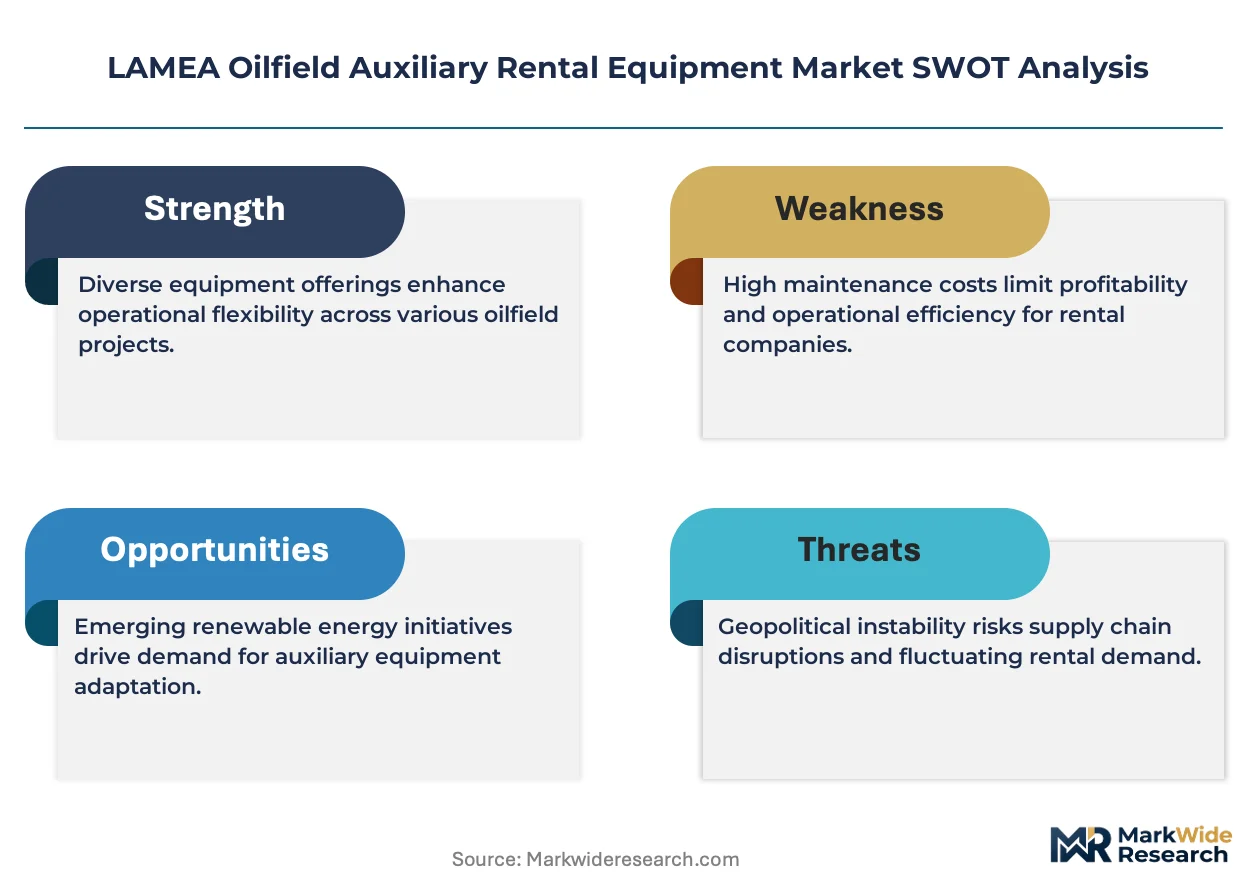
The LAMEA oilfield auxiliary rental equipment sector is being fundamentally restructured by local content mandates that force international operators to redirect procurement toward domestic rental providers, compressing traditional supply relationships while creating protected market segments for regional fleet owners.
Growth Catalysts
- ANP Certification Standards:Brazil's national petroleum regulator enforces rigorous offshore equipment certification that accelerates fleet replacement cycles and sustains continuous demand for compliant rental assets.
- Pre-salt Basin Development:Petrobras-led exploration programs in Brazil's deepwater pre-salt formations require sustained auxiliary equipment rotation for drilling and completion operations.
- Subsea Tieback Projects:Offshore drilling contractors across West Africa are expanding rental fleets to service subsea tieback installations connecting marginal fields to existing infrastructure.
Market Restraints
- Steel Price Volatility:Fluctuations in high-grade alloy steel prices directly pressure rental rate margins for pressure-rated equipment exceeding 10,000 psi specifications.
- Single-source Component Dependency:Specialized wellhead control systems concentrate with limited North American and European suppliers, exposing LAMEA rental operators to extended lead times.
- Nigerian Local Content Thresholds:The Department of Petroleum Resources mandates escalating domestic participation requirements that foreign rental providers struggle to meet without joint venture structures.
Strategic Opportunities
- Angolan Fleet Modernization:The petroleum ministry's mandatory replacement of legacy auxiliary equipment creates immediate demand for certified rental assets compliant with updated safety protocols.
- EU Green Deal Methane Framework:The emissions reduction mandate pivots offshore operators toward rental equipment with certified leak-detection systems, differentiating premium fleet providers.
- Digital Monitoring Convergence:Integration of IoT sensor networks with auxiliary rental assets enables predictive maintenance offerings and remote performance verification.
Industry Challenges
- Subsea Systems Integration:Auxiliary equipment must interface with proprietary wellhead architectures from multiple OEMs, requiring costly adapter engineering and extended commissioning timelines.
- Certification Backlog Compression:ANP and Angola's petroleum ministry face inspection queue bottlenecks that delay equipment deployment and compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Oilfield Auxiliary Rental Equipment Market |
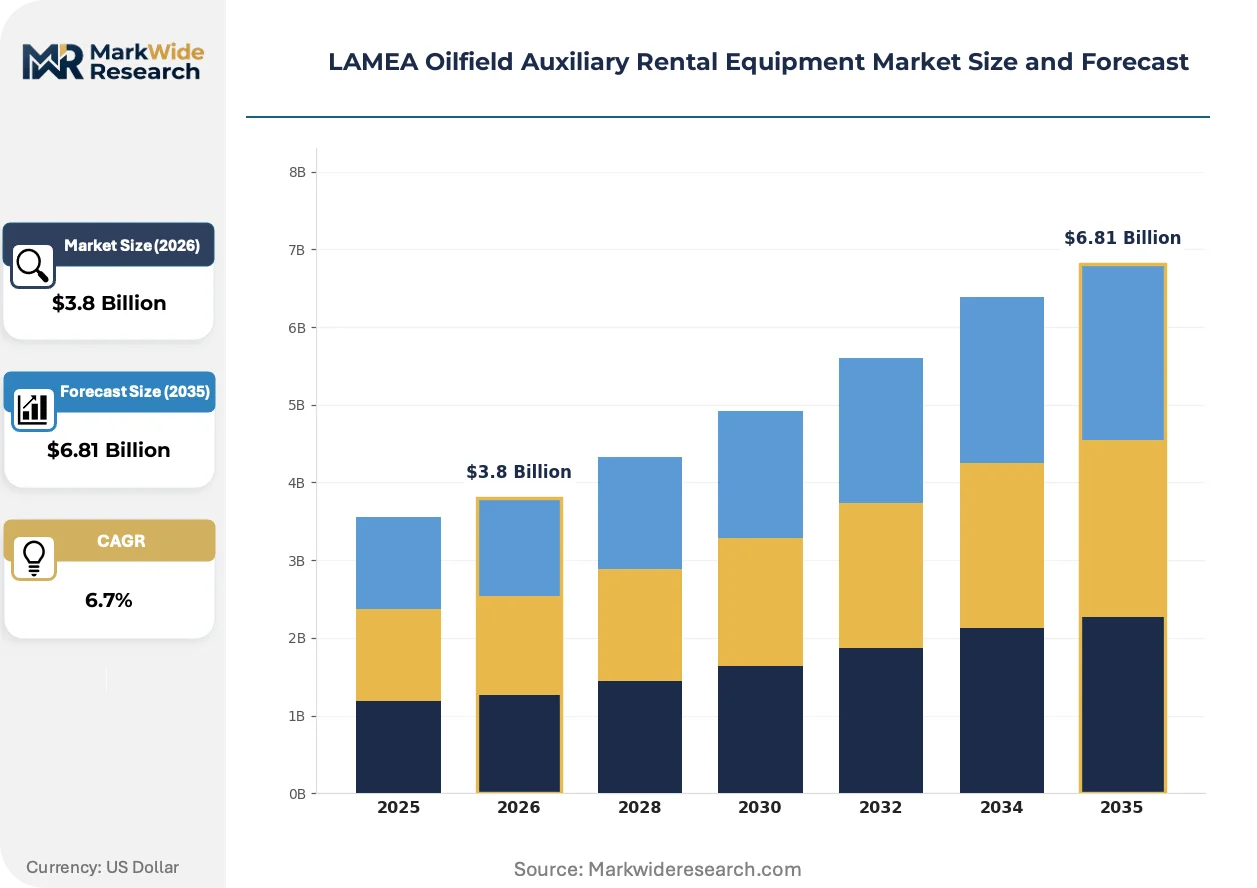
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Drilling Rigs, Pumps, Generators, Compressors Service Type: Short-term Rentals, Long-term Rentals, Maintenance Services, Logistics Support End User: Oil Producers, Service Companies, Contractors, Government Agencies Application: Exploration, Drilling, Production, Well Intervention |
| Companies Covered | Schlumberger Limited, Weatherford International plc, Halliburton Company, Oil States Industries, Superior Energy Services, NOV Inc., Baker Hughes Company, TechnipFMC, Key Energy Services, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Oilfield Auxiliary Rental Equipment Market Evolving Landscape
Digitalization and decarbonization mandates are converging to reshape equipment specifications and service delivery models across LAMEA offshore operations. Fleet operators must now bundle hardware with data-enabled compliance verification.
Modular electric-powered auxiliary skids is expanding into Brazilian deepwater pre-salt operations. Petrobras and its drilling contractors are specifying these systems for new floating production units to meet methane intensity targets. The technology is expanding into pressure pumping and power generation segments previously dominated by diesel-mechanical units.
Angola's petroleum ministry has imposed fleet modernization requirements that accelerate replacement of legacy auxiliary equipment. The regulation mandates retirement timelines for assets exceeding twenty years of service. Deepwater drilling contractors are responding by restructuring long-term rental agreements to align with forced replacement schedules.
Integrated service bundling is displacing standalone equipment rentals in West African offshore blocks. Operators now require maintenance, logistics, and digital monitoring wrapped into single contractual frameworks. Nigeria's Department of Petroleum Resources local content enforcement has intensified this shift, as domestic providers compete through service scope rather than asset scale alone.
LAMEA Oilfield Auxiliary Rental Equipment Market Segmentation
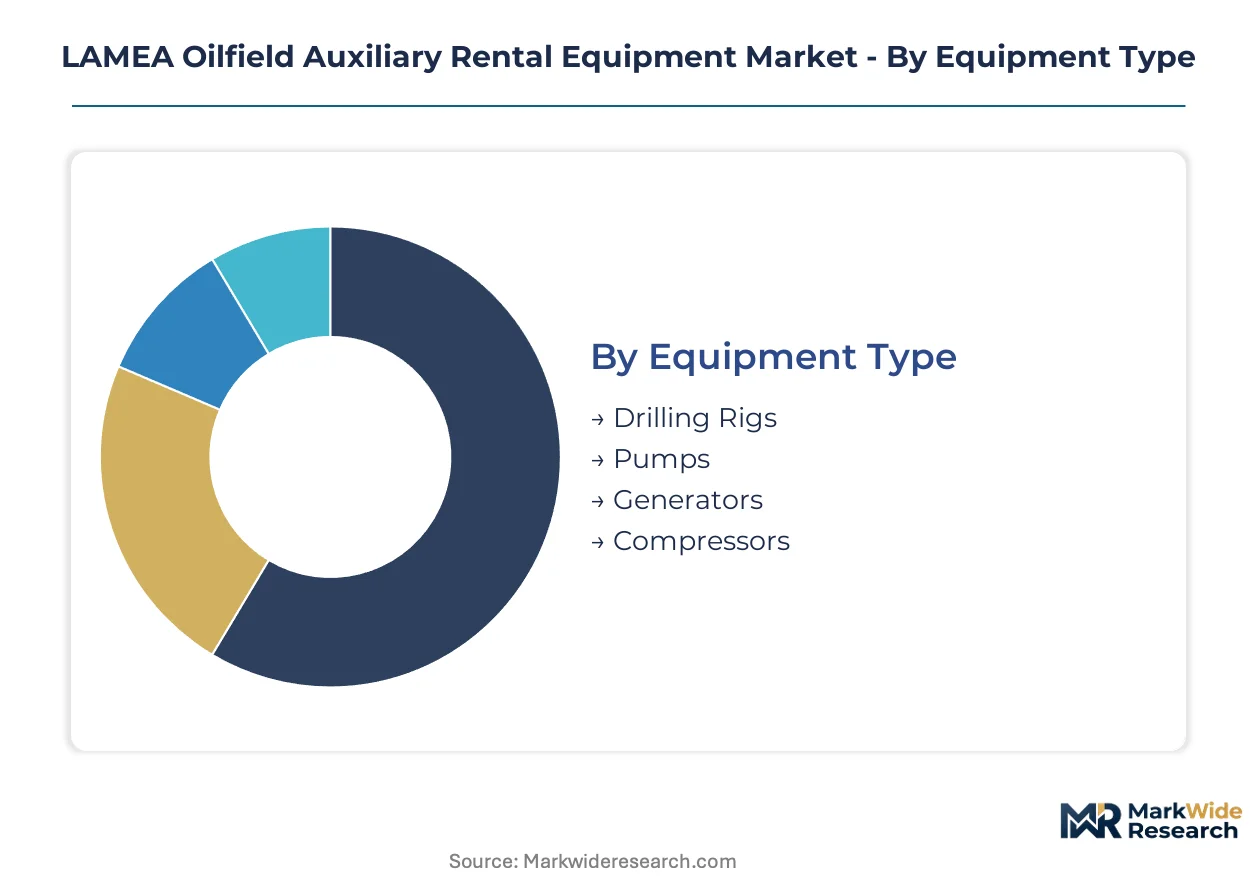
Equipment categorization in LAMEA oilfield auxiliary rentals determines procurement patterns, certification requirements, and margin structures across Brazilian pre-salt and West African deepwater blocks. Segment boundaries shift as local content mandates force international operators to restructure supplier relationships and fleet deployment strategies.
Equipment Type:
Upgrade cycles and replacement timelines vary dramatically by equipment category, with pressure-rated assets facing accelerated retirement under ANP and Angolan petroleum ministry protocols.
- Drilling Rigs:Mobile modular units rated for 10,000+ psi operations dominate Brazilian pre-salt deployment. Petrobras-led programs sustain continuous rotation demand as contractors cycle assets between exploration and development phases to meet ANP certification windows.
- Pumps:High-pressure pumping skids command premium rental rates in well intervention applications. West African subsea tieback projects concentrate demand for units compatible with proprietary wellhead architectures from multiple OEMs.
- Generators:Power generation assets face replacement pressure from Angola's twenty-year service limit mandates. Deepwater drilling contractors restructure long-term agreements to align with forced retirement schedules.
- Compressors:Gas compression equipment supports production maintenance across aging LAMEA fields. Nigerian local content thresholds redirect procurement toward domestic rental providers with joint venture structures.
Drilling Rigs sits at the top of the volume ranking, with Pumps climbing the fastest.
Service Type:
Contract duration and pricing structures stratify across exploration unpredictability versus production stability, with bundled offerings displacing standalone rentals in Nigerian and Angolan offshore blocks.
- Short-term Rentals:Exploration-phase contracts command premium pricing where utilization cycles remain unpredictable. Brazilian pre-salt drilling programs generate concentrated demand for rapid rig-up assets with certified leak-detection systems.
- Long-term Rentals:Production maintenance contracts generate stable revenue streams tied to field life extensions. Angolan fleet modernization requirements accelerate replacement of legacy auxiliary equipment under petroleum ministry timelines.
- Maintenance Services:Bundled service-level agreements capture margin pools through predictive maintenance offerings. Nigerian Department of Petroleum Resources enforcement intensifies competition through service scope rather than asset scale.
- Logistics Support:Equipment mobilization and demobilization services reduce downtime across remote West African offshore blocks. Local content mandates compress traditional supply relationships while creating protected segments for regional fleet owners.
Long-term Rentals anchors revenue stability, with Maintenance Services expanding most quickly through integrated contractual frameworks.
End User:
Procurement authority and technical specifications diverge sharply between national oil companies, international operators, and domestic service providers navigating local content enforcement.
- Oil Producers:National and international oil companies set equipment specifications for offshore development programs. Petrobras drives pre-salt basin demand with continuous auxiliary equipment rotation requirements.
- Service Companies:Schlumberger, Weatherford, and Halliburton bundle auxiliary rentals with digital monitoring platforms and localized maintenance hubs. Their integrated drilling technology portfolios reshape competitive access across LAMEA blocks.
- Contractors:Offshore drilling contractors expand rental fleets to service subsea tieback installations connecting marginal fields to existing infrastructure. West African projects concentrate demand for certified assets.
- Government Agencies:Regulatory bodies including ANP and Nigeria's Department of Petroleum Resources enforce equipment certification standards and local content participation that reshape supplier qualification criteria.
Oil Producers dominate procurement volume, with Service Companies gaining share fastest through technology bundling and digital platform integration.
Application:
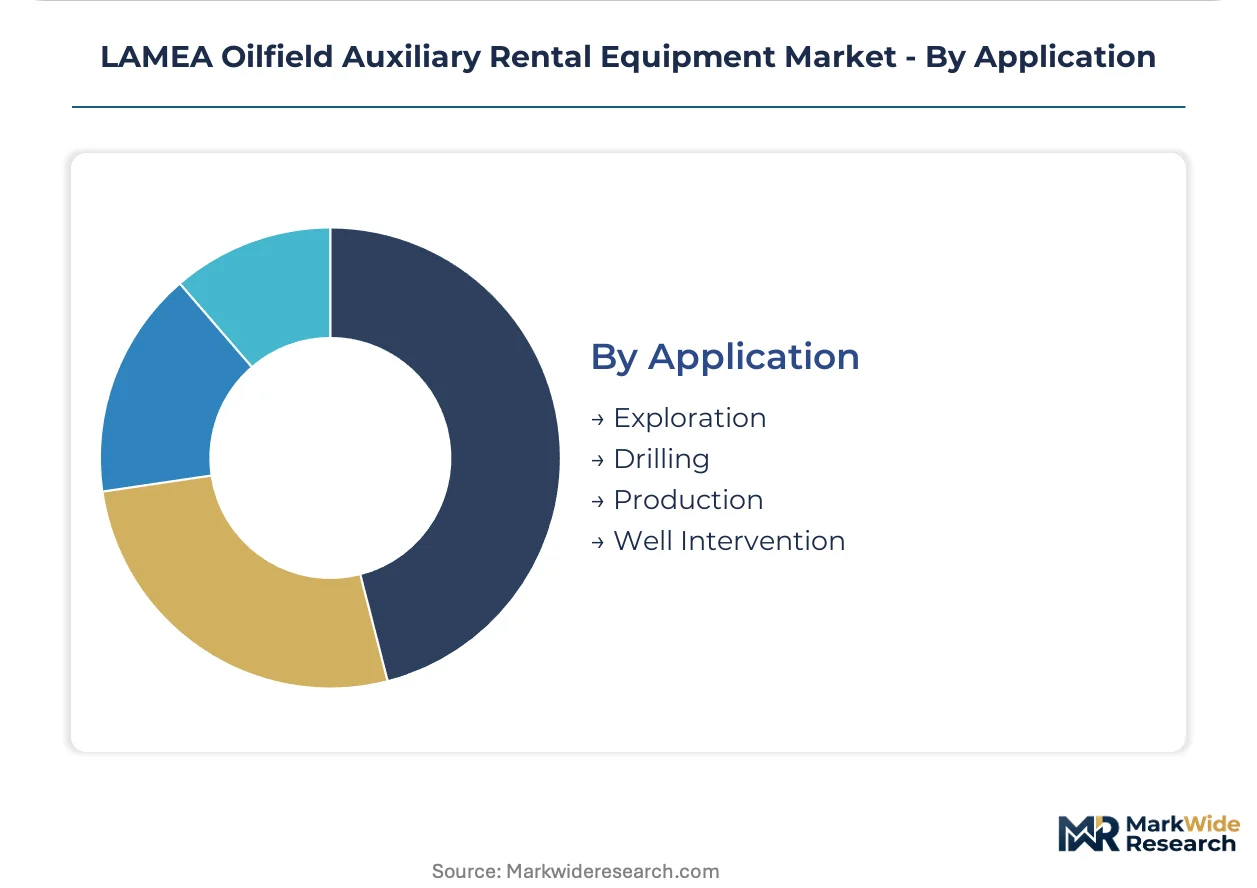
Field maturity and operational intensity determine equipment specification requirements, with aging LAMEA reservoirs driving structural expansion in intervention-intensive segments.
- Exploration:Wildcat drilling programs require rapid-deployment auxiliary assets with unpredictable utilization cycles. Brazilian pre-salt frontier blocks sustain demand for certified rental equipment under ANP offshore standards.
- Drilling:Development drilling operations utilize sustained equipment deployment with longer rental horizons. West African deepwater contractors face subsea systems integration challenges requiring costly adapter engineering.
- Production:Sustained hydrocarbon extraction relies on auxiliary equipment for power generation and gas compression. Angola's petroleum ministry imposes fleet modernization requirements that accelerate legacy asset replacement.
- Well Intervention:Workover and maintenance operations exhibit the fastest structural expansion as aging LAMEA fields require more frequent intervention. EU Green Deal methane frameworks pivot operators toward rental equipment with certified leak-detection systems.
Production holds the largest installed base, with Well Intervention showing the steepest expansion trajectory amid reservoir maturity across Brazilian and West African fields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LAMEA oilfield auxiliary rental equipment sector traces its operational scale to Brazil's 2007 pre-salt discoveries, which established deepwater drilling as the region's defining technical frontier and created sustained demand for certified mobile assets.
Brazil
Petrobras-led pre-salt development programs drive continuous auxiliary equipment rotation between exploration and production phases. ANP certification standards enforce rigorous offshore equipment protocols that accelerate fleet replacement cycles. The Santos Basin cluster anchors deepwater drilling activity, with contractors cycling pressure-rated assets to meet regulatory inspection windows.
Nigeria
Subsea tieback installations connecting marginal fields to existing infrastructure concentrate demand for compatible pumping and wellhead systems. The Department of Petroleum Resources mandates escalating domestic participation thresholds that foreign rental providers address through joint venture structures. The Niger Delta offshore blocks host integrated service bundling as domestic providers compete through expanded contractual scope.
Angola
Petroleum ministry fleet modernization requirements force retirement of auxiliary assets exceeding twenty-year service limits. Deepwater drilling contractors restructure long-term rental agreements to align with mandated replacement schedules. The Kwanza Basin deepwater concessions absorb certified rental equipment as operators comply with updated safety protocols.
Mexico
Energy reform liberalization opened offshore blocks to international operators, expanding demand for rapid-deployment drilling rigs and power generation assets. The National Hydrocarbons Commission enforces equipment certification standards for deepwater operations. The Gulf of Mexico's Perdido Fold Belt attracts auxiliary rental deployment for frontier exploration programs.
Saudi Arabia
Aramco's offshore field development programs sustain demand for high-pressure pumping skids and gas compression equipment in the Arabian Gulf. The Saudi Standards, Metrology and Quality Organization mandates conformity assessment for imported oilfield equipment. The Safaniya and Zuluf offshore fields anchor production maintenance contracts requiring continuous auxiliary asset rotation.
LAMEA Oilfield Auxiliary Rental Equipment Market Competitive Landscape
Capital-heavy integrated service companies compete with specialized rental fleet operators for contract positioning across LAMEA offshore blocks. The market structure concentrates around technology-bundled offerings from full-service providers and asset-scale plays from regional fleet owners. Three archetypes dominate: integrated drilling technology bundlers, localized maintenance hub operators, and pure-play equipment lessors with joint venture local content structures. Competitive positioning hardens through strategic partnerships with national oil companies and selective capacity expansion in pre-salt and West African deepwater corridors.
Among the integrated service tier, Schlumberger Limited and Halliburton Company exemplify technology-bundled market presence, while Weatherford International plc occupies a specialized position within wellhead rental services. These entities represent contrasting strategic postures: full-service integration against focused technical specialization. Their competitive interaction shapes procurement patterns as national oil companies increasingly specify bundled digital monitoring and maintenance services alongside core equipment provision.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Weatherford International plc |
| Halliburton Company |
| Oil States Industries |
| Superior Energy Services |
| NOV Inc. |
| Baker Hughes Company |
| TechnipFMC |
| Key Energy Services |
| Others |
Value Network & Pricing Analysis
ANP certification standards for offshore equipment are forcing Brazilian drilling contractors toward premium-tier rental assets with certified leak-detection systems, compressing procurement flexibility and elevating rate floors for compliant fleet providers across the LAMEA basin complex.
Pricing Analysis
Contract-based long-term offtake with maintenance bundling dominates Brazilian pre-salt and West African deepwater blocks. Price differentiation hinges on ANP certification grade and after-sales service scope, with standard-tier assets facing margin compression from Angolan fleet modernization mandates. Premium-tier providers capture widening spreads as Nigerian local content enforcement redirects procurement toward joint-venture structures with elevated compliance costs. National oil companies exhibit lowest price sensitivity; independent offshore contractors in marginal field development show highest.
Supply Chain Analysis
Nigerian and Angolan domestic-content mandates are reshaping sourcing patterns for pressure-rated components and wellhead control systems. Manufacturing concentration rests on the United States, Germany, and Singapore for specialized subsea electronics and high-grade alloy steel. Raw material feeds draw from chromium-molybdenum alloy suppliers and North American wellhead OEMs. Single-source vulnerability concentrates in proprietary control system architectures. Distribution runs through integrated service company hubs with localized maintenance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on fleet modernization premiums and digital monitoring bundling that captures recurring revenue streams above base equipment rental rates.
For Market Incumbents: Hedge against Nigerian local content threshold escalation by restructuring joint venture equity with domestic fleet owners before mandatory participation tiers harden. Accelerate backward integration into certified maintenance hub networks across West African offshore corridors to compress mobilization timelines and defend rate premiums against pure-play lessors.
For New Entrants and Emerging Players: Remote equipment monitoring platforms offer the most penetrable entry vector for mid-tier contractors seeking predictive maintenance capabilities without captive fleet investment. Target Angolan deepwater blocks undergoing forced asset replacement under petroleum ministry timelines. Lead with IoT-enabled compliance verification bundled with third-party logistics support.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional fleet owners holding ANP-certified assets and established joint venture structures in Nigeria. The five-to-ten year viability window favors operators with pre-salt deployment track records and digital platform integration capabilities. Monitor Angolan petroleum ministry inspection queue compression as an inflection signal for certified asset scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Structuring | Nigerian DPR local content mandates force equity partnerships with domestic rental providers. |
| Digital Platform Integration | IoT sensor networks enable predictive maintenance offerings that differentiate premium fleet tiers. |
| Certification Investment | ANP offshore standards accelerate compliant asset replacement cycles in Brazilian pre-salt basins. |
| Maintenance Hub Localization | Regional service infrastructure reduces equipment mobilization times across West African blocks. |
| Fleet Modernization Alignment | Angolan petroleum ministry timelines create immediate demand for certified replacement assets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured drilling contractor procurement directors, ANP certification specialists, Nigerian DPR local content officers, and Halliburton regional maintenance hub managers. Secondary validation drew from ANP regulatory filings, Angolan petroleum ministry fleet modernization directives, Petrobras procurement disclosures, and SEC 10-K equipment rental revenue segmentations. Bottom-up equipment deployment counts and top-down regional capex estimates were triangulated to anchor volume projections.
Historical reference periods spanning pre-salt discovery through recent local content enforcement waves anchored the projection horizon. Segmentation modeling spanned equipment type, service contract duration, end-user procurement authority, and application intensity across exploration through well intervention. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate acceleration effects. Forecast inputs incorporated ANP inspection queue dynamics and Angolan forced retirement schedules.
The model assumes a particular technology adoption path; alternative pathways for modular electric-powered auxiliary skids would alter the outlook if Petrobras methane intensity targets accelerate faster than baseline assumptions. Forecasts reflect documented certification backlog risks and steel price volatility thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Casing Centralizer Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Japan AI in Oil and Gas Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market