
 Coal Liquefaction Market | 2026-2036
Coal Liquefaction Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Liquefaction Market Outlook
Project finance tied to state-backed energy security programs is tilting competitive access toward national oil companies and state-linked chemical conglomerates. Sasol Ltd. leverages its decades of Fischer-Tropsch operational expertise in South Africa to sustain a benchmark position in indirect liquefaction. China Shenhua Energy Co. Ltd. anchors the world's largest direct coal liquefaction complex in Inner Mongolia, controlling domestic supply chains for synthetic fuels.
Coal liquefaction converts solid coal into liquid hydrocarbons through direct hydrogenation or indirect gasification-synthesis routes, typically yielding synthetic crude, diesel, or chemical feedstocks at operating pressures above 150 bar and temperatures exceeding 400°C. The primary commercial purpose is to produce transport fuels and chemical precursors in coal-rich, oil-scarce economies. Indirect liquefaction via Fischer-Tropsch synthesis leads in installed capacity due to superior product quality and environmental compliance, while direct liquefaction occupies niche applications where hydrogen supply and catalyst stability have improved. Bituminous coal dominates feedstock consumption because of its favorable hydrogen-to-carbon ratio and established gasification infrastructure.
China's Ministry of Ecology and Environment enforces dual carbon goals that restrict new direct liquefaction approvals unless paired with carbon capture, while South Africa's Department of Mineral Resources and Energy regulates Sasol's emissions under national air quality standards. India's Central Electricity Authority and Ministry of Coal coordinate liquefaction pilot programs tied to strategic petroleum reserve policy. Stakeholders must monitor how carbon border adjustments and synthetic fuel certification schemes reshape project economics and offtake agreements.
Market Dynamics
China's dual carbon goals are compressing project timelines for direct liquefaction while redirecting capital toward carbon-captured indirect pathways, fundamentally restructuring how synthetic fuel capacity gets financed and permitted.
Growth Catalysts
- Indirect Liquefaction Technology Maturation:Fischer-Tropsch synthesis improvements are lowering capital intensity per barrel of synthetic crude output. South Africa's operational track record validates process reliability at commercial scale.
- Strategic Petroleum Reserve Policy:India's Ministry of Coal coordinates pilot programs linking domestic coal conversion to national fuel security mandates. State-backed offtake agreements de-risk project finance.
- Carbon Capture Integration:China's MEE approves new direct liquefaction only when paired with operational carbon capture systems. This regulatory gate is accelerating technology deployment and project restructuring.
Market Restraints
- Capital Intensity Barriers:Front-end engineering for coal-to-liquids facilities requires multi-billion dollar commitments before first synthetic fuel output. This cost structure limits private participation outside state-linked conglomerates.
- Feedstock Concentration Risk:Bituminous coal supply chains concentrate in specific mining basins, exposing project economics to geological variability and domestic transport bottlenecks.
- Renewable Diesel Substitution:Hydrotreated vegetable oil and biomass-to-liquid pathways compete for the same transport fuel offtake contracts without coal's carbon intensity burden.
Strategic Opportunities
- Underpenetrated Indian Market:India's coal reserves remain largely unconverted to liquid fuels despite import dependency. Central Electricity Authority coordination creates regulatory runway for first-mover projects.
- Blue Hydrogen Convergence:Coal gasification paired with carbon capture yields hydrogen for ammonia and refining applications. This technology convergence opens chemical feedstock markets beyond transport fuels.
- Synthetic Fuel Certification Schemes:Emerging lifecycle carbon accounting standards for aviation and marine fuels create compliance-driven demand for certified low-carbon coal-to-liquids output.
Industry Challenges
- Specialized Catalyst Deactivation:Direct liquefaction requires cobalt-molybdenum and iron-based catalysts that foul rapidly under high-sulfur coal conditions. Catalyst regeneration cycles compress plant availability factors.
- Integration Complexity with Legacy Refining:Synthetic crude from Fischer-Tropsch units carries unique paraffin content requiring dedicated hydrocracking or blending infrastructure. Existing refineries need material modification to process significant coal-derived volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Liquefaction Market |
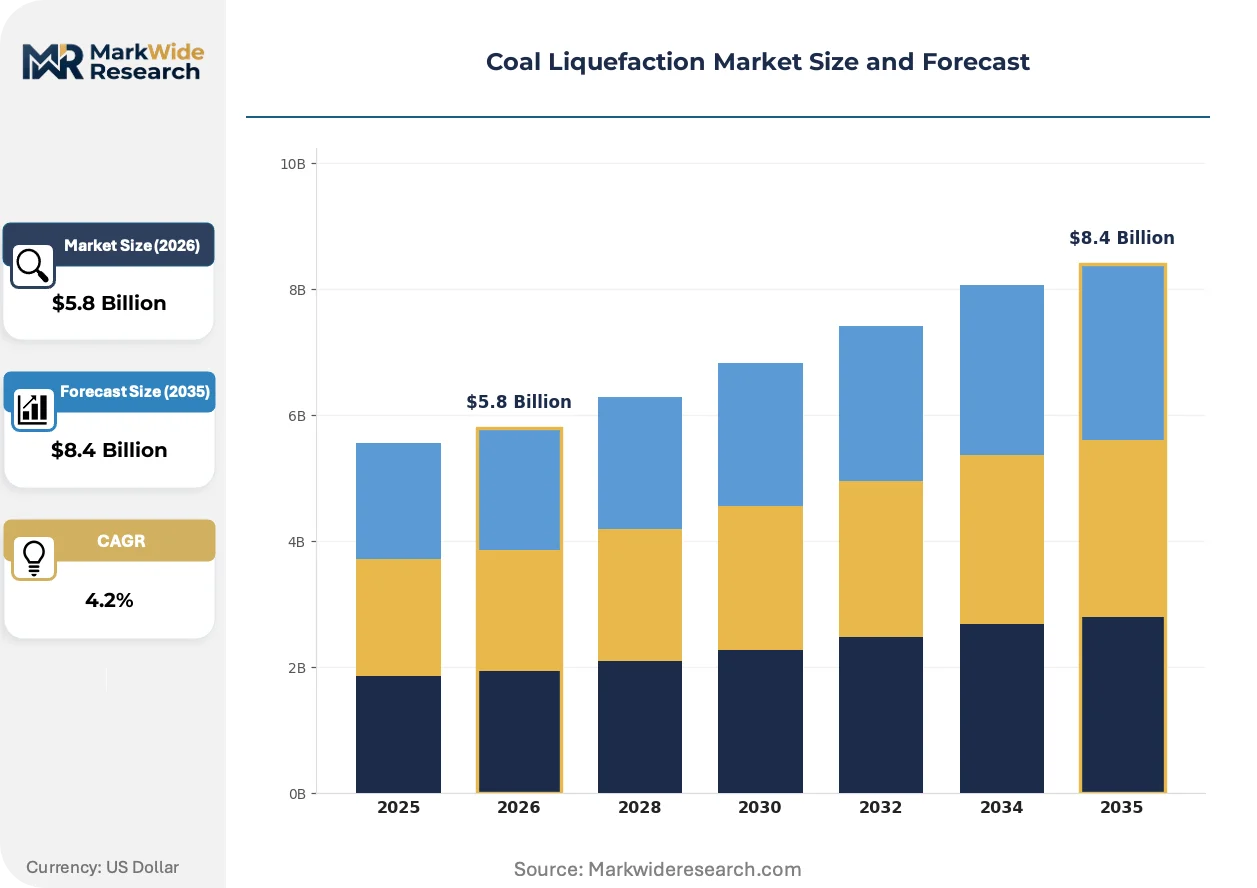
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Bituminous Coal, Lignite, Anthracite, Sub-Bituminous Coal Process Technology: Direct Liquefaction, Indirect Liquefaction, Hydrocracking, Fischer-Tropsch Synthesis End User Industry: Transportation, Chemicals, Power Generation, Natural Gas Substitution Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Synfuels China Technology Co., Celanese Corp., China Shenhua Energy Co. Ltd., Yitai Yili Energy Co., Thyssenkrupp Uhde GmbH, Sasol Ltd., Air Products and Chemicals Inc., Shenhua Group, Shandong Energy Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Liquefaction Market Strategic Shifts
Process intensification and digital control systems are compressing the gap between laboratory catalyst performance and commercial reactor output, while carbon accounting standardization reshapes which conversion pathways attract capital.
Advanced process control systems are digitizing reactor temperature and pressure management across Fischer-Tropsch trains. Sasol's South African operations deploy these platforms to sustain catalyst life and optimize wax-to-diesel selectivity. The structural consequence is digitizing maintenance scheduling from calendar-based to condition-based protocols, reducing unplanned shutdown frequency.
China's MEE enforcement of dual carbon goals restricts direct liquefaction permits to projects with operational carbon capture. This policy compression forces developers to front-load capture engineering or pivot entirely to indirect gasification-synthesis routes. Domestic synthetic fuel producers are responding by integrating pre-combustion capture into new facility designs.
Aviation sector buyers are consolidating offtake contracting around certified synthetic paraffinic kerosene with documented lifecycle carbon intensity. Airlines in Asia-Pacific and Europe now specify fuel provenance requirements that favor indirect liquefaction with carbon capture over conventional refining. This procurement concentration is most visible in Singapore and Rotterdam hub markets where bunker fuel blending operates under emerging maritime decarbonization rules.
Coal Liquefaction Market Segmentation
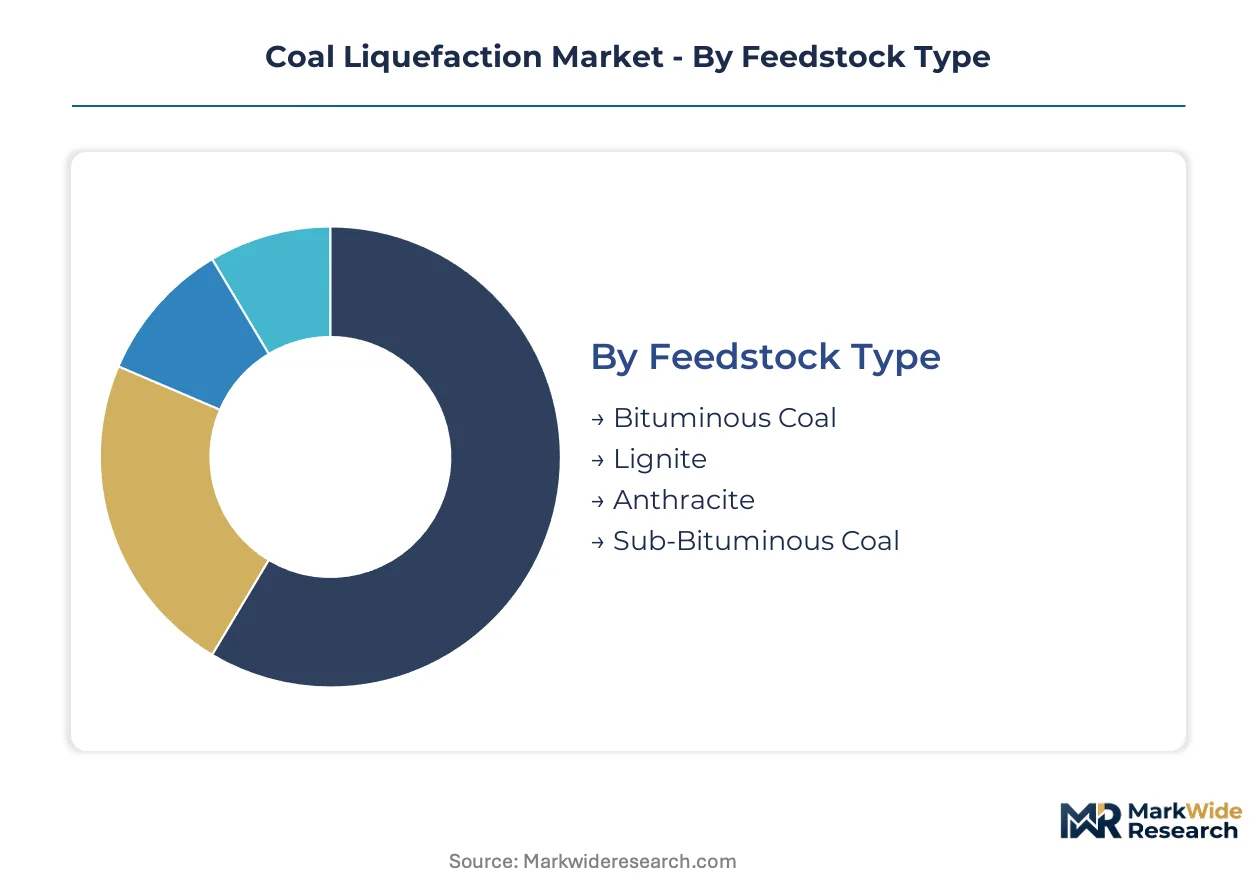
Segmentation in coal liquefaction reveals how feedstock quality, conversion chemistry, and offtake contracting shape project returns. Each dimension carries distinct capital requirements and regulatory exposure that determine which technology pathways attract state-backed financing.
Feedstock Type:
After-sales service intensity concentrates around bituminous coal gasification trains where catalyst replacement cycles and gasifier refractory maintenance dominate operational expenditure.
- Bituminous Coal:Higher hydrogen-to-carbon ratio enables efficient Fischer-Tropsch synthesis with lower hydrogen import requirements. Demand concentrates in China's Inner Mongolia complexes and Sasol's Secunda operations where established mining infrastructure reduces feedstock transport costs.
- Lignite:Lower energy density requires larger gasification trains per barrel of synthetic output, elevating capital intensity. India's pilot programs in Odisha and Jharkhand target lignite reserves for domestic fuel security despite higher moisture handling costs.
- Anthracite:Premium carbon content suits direct hydrogenation routes but limited global reserves constrain scale. Small-scale units in China Shaanxi province process anthracite for chemical feedstocks.
- Sub-Bituminous Coal:Intermediate characteristics drive blending strategies with bituminous feedstocks. Wyoming Powder River Basin supply chains feed experimental gasification units seeking lower sulfur input.
Bituminous Coal holds the largest share; momentum sits with Lignite as Indian state enterprises advance domestic reserve conversion.
Process Technology:
Cost tier stratification separates billion-dollar integrated complexes from modular pilot units, with financing access determining which developers can deploy at commercial scale.
- Direct Liquefaction:Hydrogenation at 400°C and 150 bar yields synthetic crude without intermediate gasification. China's Shenhua Ordos facility anchors global capacity; new approvals require operational carbon capture per MEE dual carbon enforcement.
- Indirect Liquefaction:Gasification-synthesis route dominates installed capacity through superior product quality and environmental compliance. Sasol's Fischer-Tropsch expertise in South Africa validates process reliability for aviation fuel certification schemes.
- Hydrocracking:Secondary upgrading of heavy Fischer-Tropsch waxes into diesel and kerosene cuts. Refinery integration complexity limits standalone deployment outside petrochemical complexes.
- Fischer-Tropsch Synthesis:Catalytic conversion of syngas to liquid hydrocarbons represents the core indirect liquefaction step. Cobalt-based catalyst advances from Sasol and Chinese research institutes are extending catalyst life cycles.
Indirect Liquefaction commands current capacity; Direct Liquefaction gains policy attention where carbon capture integration satisfies permitting requirements.
End User Industry:
Application-specific offtake contracting varies sharply, with aviation and marine fuel buyers now demanding certified lifecycle carbon documentation that favors certain conversion pathways.
- Transportation:Synthetic diesel and jet fuel production anchors commercial viability for coal-to-liquids projects. Singapore and Rotterdam bunker fuel markets are consolidating procurement around certified synthetic paraffinic kerosene specifications.
- Chemicals:Olefins and aromatics from coal-derived syngas feed polyethylene and polyester value chains. China's Ningxia coal chemical cluster integrates liquefaction with downstream polymer production.
- Power Generation:Direct combustion of coal-derived liquids occupies niche applications in remote mining operations. Diesel replacement for off-grid generators motivates small-scale South African deployments.
- Natural Gas Substitution:Synthetic natural gas from coal gasification serves city gas networks in northern China. Substitute natural gas projects in Inner Mongolia and Xinjiang redirect syngas from liquid fuels to pipeline injection.
Transportation holds the largest share; Chemicals represents the steepest expansion trajectory as coal-to-olefins economics improve against naphtha cracking.
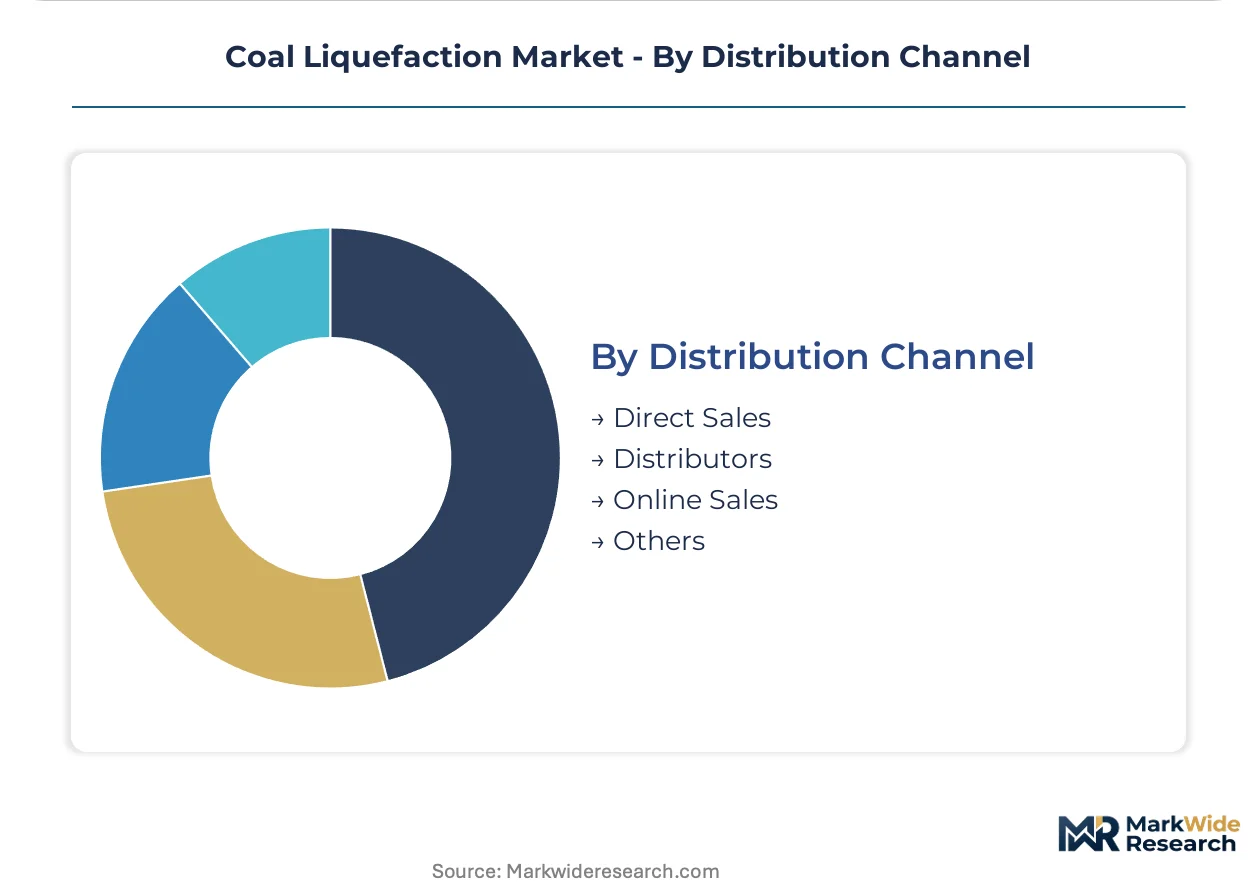
Distribution Channel:
Customer type segmentation separates state-backed offtake agreements from merchant sales, with project finance structures dictating channel selection for synthetic fuel output.
- Direct Sales:Long-term offtake contracts with national oil companies and strategic petroleum reserve programs de-risk capital-intensive projects. India's Ministry of Petroleum coordinates direct procurement for blending mandates.
- Distributors:Intermediate handling of synthetic diesel and naphtha serves smaller industrial buyers lacking dedicated storage. South African fuel wholesalers manage Sasol product distribution to mining and agricultural sectors.
- Online Sales:Digital platforms for specialty chemical intermediates and laboratory-grade solvents. Limited penetration given bulk commodity nature of primary coal liquefaction output.
- Others:Barter arrangements and countertrade mechanisms in bilateral energy agreements. Chinese development finance institutions structure synthetic fuel exports as loan repayment vehicles.
Direct Sales holds the largest share; momentum sits with Distributors as merchant market liquidity improves for certified synthetic fuels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed energy security programs are redirecting capital toward coal-to-liquids infrastructure in coal-rich, oil-import dependent economies. Regulatory enforcement of carbon intensity standards is compressing project timelines and favoring indirect liquefaction pathways with integrated capture systems.
China
Dual carbon goals under MEE oversight are restricting new direct liquefaction approvals to projects with operational carbon capture. Shenhua Ordos in Inner Mongolia anchors the world's largest direct liquefaction complex. The Ningxia coal chemical cluster integrates liquefaction with downstream polymer production for domestic chemical feedstock security.
South Africa
Sasol's Secunda operations sustain decades of Fischer-Tropsch expertise validating indirect liquefaction at commercial scale. The Department of Mineral Resources and Energy regulates emissions under national air quality standards. Mining and agricultural sectors in Mpumalanga province absorb synthetic diesel output through established fuel wholesaler distribution networks.
India
Import dependency and strategic petroleum reserve policy are driving Central Electricity Authority coordination of liquefaction pilot programs. The Ministry of Coal links domestic coal conversion to national fuel security mandates. Odisha and Jharkhand lignite reserves target first-mover projects despite higher moisture handling costs.
United States
Wyoming Powder River Basin sub-bituminous supply chains feed experimental gasification units seeking lower sulfur input pathways. EPA emissions standards and state-level carbon policies shape project feasibility assessments. Gulf Coast refining infrastructure offers potential integration points for Fischer-Tropsch synthetic crude processing.
Coal Liquefaction Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure tilted toward state-linked conglomerates with privileged project finance access. National oil companies and state-backed chemical groups dominate billion-dollar integrated complexes. Three archetypes prevail: technology licensors with process engineering expertise, captive coal miners with integrated conversion assets, and industrial gas suppliers with syngas handling capabilities. Competitive moves center on carbon capture integration partnerships and strategic offtake contracting with aviation fuel certification schemes.
Among Chinese state-linked energy conglomerates, China Shenhua Energy Co. Ltd. and Shenhua Group occupy positions exemplifying captive coal-to-liquids integration. Sasol Ltd. anchors the technology-licensor archetype with South African operational heritage. Thyssenkrupp Uhde GmbH represents the process engineering specialist tier with European project execution capabilities.
| Leading Market Players |
|---|
| Synfuels China Technology Co. |
| Celanese Corp. |
| China Shenhua Energy Co. Ltd. |
| Yitai Yili Energy Co. |
| Thyssenkrupp Uhde GmbH |
| Sasol Ltd. |
| Air Products and Chemicals Inc. |
| Shenhua Group |
| Shandong Energy Group Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Inner Mongolia's Ordos basin anchors global direct liquefaction capacity, with Shenhua's integrated mining-conversion complex translating captive bituminous supply into synthetic crude pricing power that merchant buyers cannot replicate.
Pricing Analysis
Certification level for synthetic paraffinic kerosene creates the primary spread between aviation-grade premiums and industrial diesel benchmarks. Three-tier pricing structure across certified low-carbon, standard Fischer-Tropsch, and unabated direct liquefaction output reflects carbon intensity documentation. Pricing pressure stems from renewable diesel substitution in European bunker fuel markets. State-backed strategic petroleum reserve programs exhibit lowest price sensitivity, while merchant industrial buyers in South Africa's mining sector negotiate hardest on volume discounts.
Supply Chain Analysis
Contract manufacturing concentration rests with state-linked EPC consortia in China and South Africa, with Thyssenkrupp Uhde and domestic Chinese engineering groups holding process technology deployment capacity. Geographic supply concentrates in China, South Africa, and India as regulatory approval gates limit new entrant participation. Raw material dependencies center on bituminous coal from specific mining basins, cobalt-molybdenum catalyst precursors, and hydrogen supply from dedicated gasification trains. Single-source vulnerability concentrates around Fischer-Tropsch catalyst regeneration services. Distribution runs through long-term offtake contracts with national oil companies rather than spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coal liquefaction markets track cyclical energy security investment waves, with import dependency spikes in India and China's dual carbon enforcement resetting capital allocation toward carbon-captured pathways.
For Market Incumbents: Insulate position by deepening backward integration into captive mining assets and accelerating carbon capture certification to satisfy MEE permitting requirements. Sasol's Secunda operational heritage demonstrates how Fischer-Tropsch expertise barriers deter technology licensing competitors. Prioritize aviation fuel offtake contracting before renewable diesel capacity floods Singapore and Rotterdam hub markets. For New Entrants and Emerging Players: Pursue India's underpenetrated lignite conversion segment where Central Electricity Authority coordination creates regulatory runway for first-mover projects. Target modular pilot-scale deployments in Odisha and Jharkhand to demonstrate moisture handling capabilities before scaling. Go-to-market positioning should emphasize strategic petroleum reserve linkage over merchant fuel sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors indirect liquefaction specialists with integrated carbon capture engineering capabilities over direct hydrogenation exposure. Long-term viability hinges on synthetic fuel certification scheme adoption in aviation and marine sectors. Acquisition targets should demonstrate operational Fischer-Tropsch trains with documented catalyst life extension. Monitor carbon border adjustment mechanism enforcement in European bunker fuel markets as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | MEE dual carbon enforcement restricts direct liquefaction permits to capture-ready projects, restructuring project finance access. |
| Aviation Fuel Certification | Singapore and Rotterdam bunker markets consolidate procurement around certified synthetic paraffinic kerosene specifications. |
| Backward Integration into Mining | Captive bituminous supply in Inner Mongolia and Mpumalanga insulates feedstock cost volatility from transport bottlenecks. |
| Catalyst Life Extension R&D | Cobalt-based advances from Sasol and Chinese institutes compress regeneration cycles and sustain plant availability factors. |
| Strategic Petroleum Reserve Linkage | India's Ministry of Petroleum coordinates direct procurement for blending mandates, de-risking capital-intensive project returns. |
Study Parameters
Cross-validation between primary interviews with Fischer-Tropsch plant managers, EPC contractors, and aviation fuel procurement officers and secondary validation through EIA energy data, IEA technology roadmaps, and SEC filings from integrated energy conglomerates anchors the qualitative findings. Bottom-up capacity assessments triangulate against top-down energy security policy expenditure tracking across the analysis window.
Calibration against historical project completion timelines and synthetic fuel offtake contract volumes shapes the projection framework across feedstock type, process technology, and end-use industry segmentation dimensions. CAGRs derive from capacity utilization trends and carbon intensity regulation enforcement patterns. Forecast inputs incorporate Fischer-Tropsch catalyst replacement cycles and carbon capture retrofit capital requirements.
Sensitivities concentrate around carbon border adjustment implementation timing and renewable diesel cost parity achievement in European markets. Forecasts reflect documented assumptions on state-backed financing availability and dual carbon goal enforcement consistency. Quarterly review of MEE permitting decisions and aviation fuel certification scheme adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Germany Bunker Fuel Market
Fuels
North America Wood Pellet Market
Fuels
India Petrol Station Market
Fuels
Fuel Conditioning System Market
Fuels
China Bunker Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Global Gas Cylinder Market
Fuels
CNG Dispenser Market
Fuels
Storage Tank Market
Fuels
India Retail Fuel Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Japan Bunker Fuel Market
Fuels
LNG Filling Station Market
Fuels
Pyrolysis Gas Market
Fuels
Global Turbine Oil Market
Fuels
Asia-Pacific Coal Market