
 Southeast Asia Oil and Gas Midstream Market | 2026-2036
Southeast Asia Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Oil and Gas Midstream Market Analytics
Integrated service bundling is shifting buyer procurement patterns across Southeast Asia's midstream sector. Petronas leverages its captive pipeline and storage infrastructure to offer end-to-end gas processing contracts that lock in long-term offtake agreements. PT Pertamina anchors Indonesia's domestic distribution through its control of Java-Sumatra trunk lines and coastal terminals. PTT Public Company Limited dominates Thailand's eastern seaboard with integrated liquefaction and regasification assets that serve industrial estates.
Southeast Asia oil and gas midstream encompasses the transportation, storage, and processing infrastructure bridging upstream extraction with downstream refining and distribution, typically operating at pressures between 50-150 bar for cross-border pipelines and maintaining cryogenic temperatures below minus 162 degrees Celsius for LNG handling. Pipelines and storage facilities constitute the foundational revenue layer, with natural gas processing and liquefaction technology capturing expanding margin pools as LNG export capacity multiplies across Indonesia, Malaysia, and Myanmar. Control systems represent the fastest-growing technology segment as operators automate remote monitoring across subsea and jungle terrain installations.
Malaysia's PETRONAS and Indonesia's BPH Migas enforce domestic market obligation rules that reserve pipeline capacity for local supply before export authorization, while Thailand's Energy Regulatory Commission governs third-party access to PTT's transmission network. Vietnam's Ministry of Industry and Trade coordinates offshore gas field development licensing with pipeline routing approvals that shape infrastructure sequencing. Stakeholders must track how ASEAN Power Grid interconnection plans redirect gas demand from power generation toward industrial hydrogen feedstock applications.
Market Dynamics
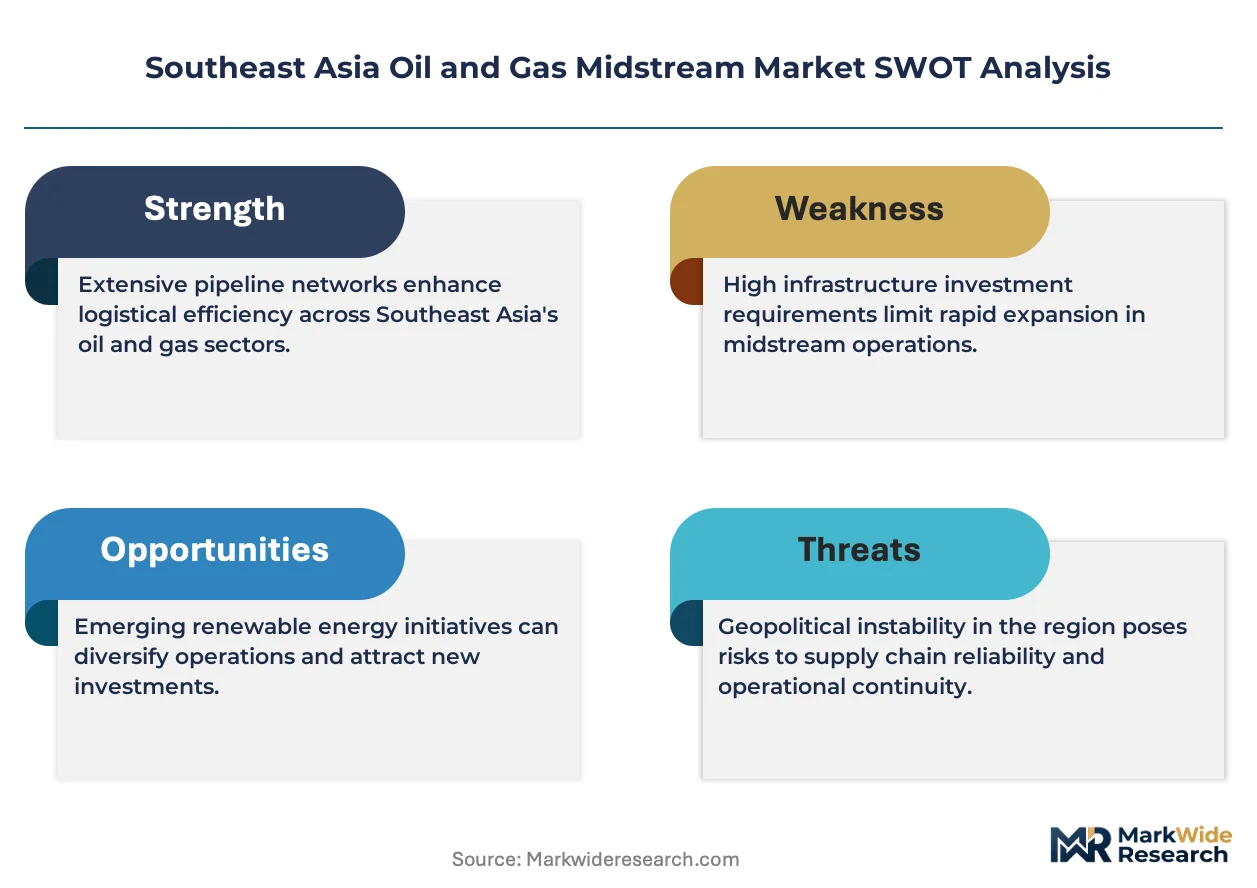
Carbon capture retrofit requirements are forcing midstream operators across Indonesia, Malaysia, and Thailand to reconfigure existing pipeline networks for CO2 co-transport, compressing project timelines and inflating engineering complexity for brownfield expansions.
Growth Catalysts
- Domestic Market Obligation frameworks:Malaysia's PETRONAS and Indonesia's BPH Migas reserve pipeline capacity for local supply before export authorization, guaranteeing baseline throughput for trunk line operators.
- Floating LNG technology adoption:Offshore gas discoveries in the Philippines and Vietnam require dedicated FLNG processing infrastructure, creating demand for subsea tieback systems and cryogenic transfer solutions.
- Industrial estate clustering:Thailand's eastern seaboard concentration of petrochemical facilities generates sustained demand for integrated liquefaction and regasification assets with dedicated pipeline connectivity.
Market Restraints
- Specialized steel alloy cost volatility:X80 and X100 grade linepipe procurement faces price swings tied to nickel and molybdenum commodity markets, squeezing EPC contractor margins on fixed-price contracts.
- Jungle terrain construction limitations:Borneo and Papua New Guinea pipeline routes encounter restricted heavy equipment access during monsoon seasons, extending construction windows by 40-60%.
- Cross-border regulatory friction:ASEAN member states maintain non-harmonized technical standards for pipeline safety and environmental permitting, fragmenting project approval timelines.
Strategic Opportunities
- Myanmar pipeline rehabilitation:Dormant onshore transmission corridors connecting Shwe gas fields to Yunnan province offer brownfield redevelopment potential as regional gas demand recovers.
- Hydrogen blending infrastructure:Singapore and Thailand's industrial hydrogen feedstock pilots create retrofit demand for existing natural gas pipelines rated for H2 admixture up to 20% by volume.
- Digital twin convergence:Integration of IoT sensor networks with predictive maintenance platforms enables remote monitoring across subsea and remote terrain installations, reducing physical inspection cycles.
Industry Challenges
- Subsea welding technician scarcity:Saturated diving labor markets in Southeast Asia cannot supply sufficient hyperbaric welders for deepwater pipeline installation schedules, forcing contractor recruitment from West Africa and the Gulf of Mexico.
- Legacy SCADA integration complexity:Brownfield pipeline automation upgrades must interface with 1980s-era control systems, requiring custom protocol gateways that extend commissioning timelines.
- Carbon certification timeline compression:Project developers face overlapping verification requirements from Malaysia's carbon accounting framework and voluntary LNG cargo certification schemes, duplicating documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Oil and Gas Midstream Market |
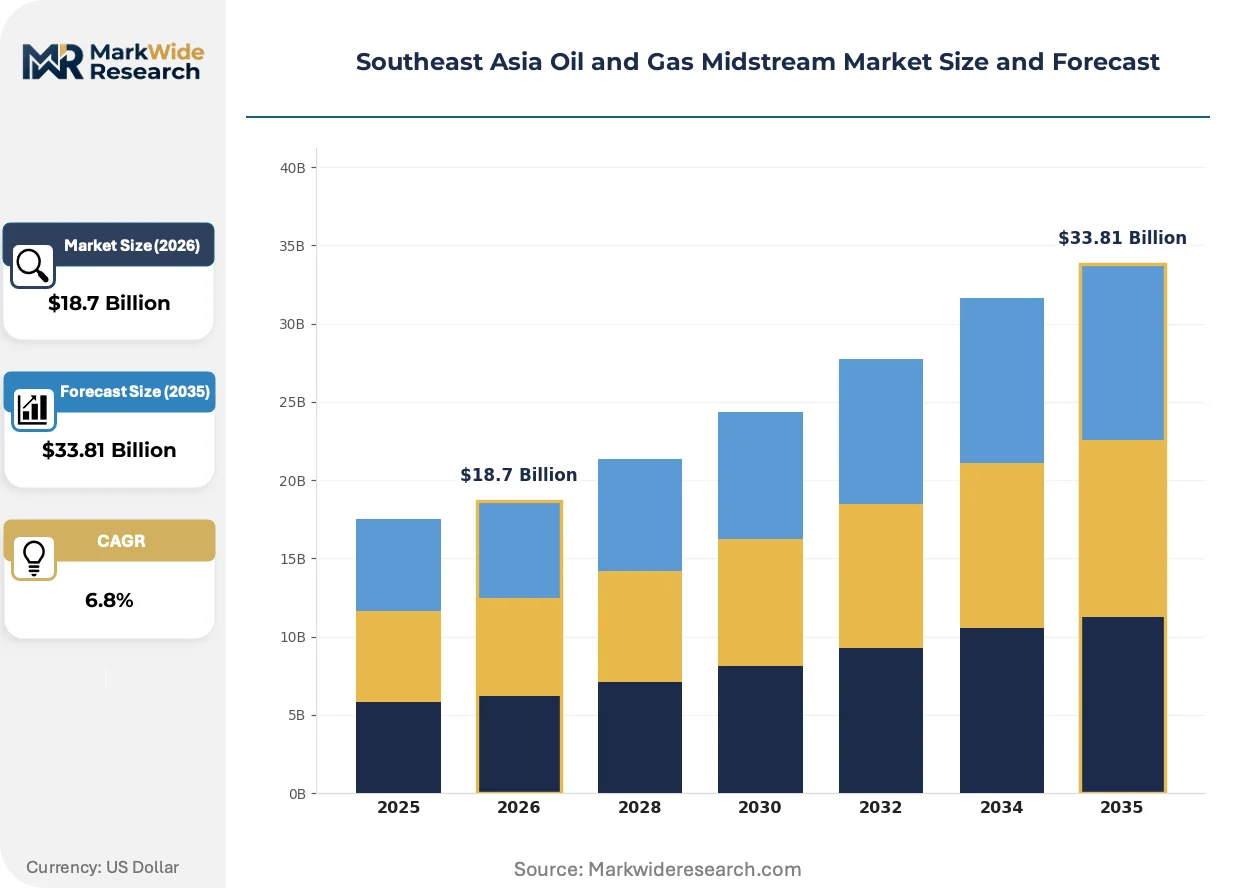
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage Facilities, Transportation, Processing Services Technology: Natural Gas Processing, Liquefaction Technology, Compression Systems, Control Systems End User: Utility Companies, Industrial Users, Government Agencies, Independent Producers Capacity: High Capacity, Medium Capacity, Low Capacity, Expedited Capacity |
| Companies Covered | Petronas, PT Pertamina, PTT Public Company Limited, Vietnam Oil and Gas Group, Petronas Gas Berhad, PT Perusahaan Gas Negara, Gas Malaysia Berhad, TechnipFMC plc, PT Connusa Energindo, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Oil and Gas Midstream Market Evolving Landscape
Digital automation and modular processing architectures are compressing project delivery timelines while regulatory carbon accounting mandates reshape infrastructure investment criteria across Southeast Asian gas corridors.
Subsea processing technology is modularizing field development economics for marginal offshore discoveries. Compact separation and compression units installed on the seabed eliminate platform construction costs for fields below 500 million cubic feet per day. PETRONAS and PTTEP are deploying these systems in Sarawak and the Gulf of Thailand, enabling production from reservoirs previously classified as sub-commercial. This architecture is modularizing project sanctioning decisions, allowing phased investment against reserve confirmation rather than committing full capex upfront.
Malaysia's carbon capture and storage regulatory framework now mandates CO2 monitoring and verification for pipeline operators transporting associated gas from offshore fields. The Petroleum Management Unit requires baseline emissions reporting and third-party audit protocols for new trunk line approvals. Midstream developers are responding by embedding fiber-optic sensing for leak detection and commissioning dedicated metering stations for CO2 content measurement, particularly on routes serving Bintulu LNG and Pengerang complexes.
Integrated service contracting is displacing fragmented procurement for gas processing infrastructure. End-users in Vietnam's power sector and Indonesia's fertilizer industry now specify lump-sum turnkey agreements spanning pipeline connection, dehydration, and custody transfer metering. This consolidation compresses vendor management overhead but concentrates risk with EPC contractors. The shift is most visible in Vietnam's Block B and Ca Voi Xanh developments, where power utilities negotiate single-point responsibility for gas delivery to plant battery limits.
Southeast Asia Oil and Gas Midstream Market Segmentation
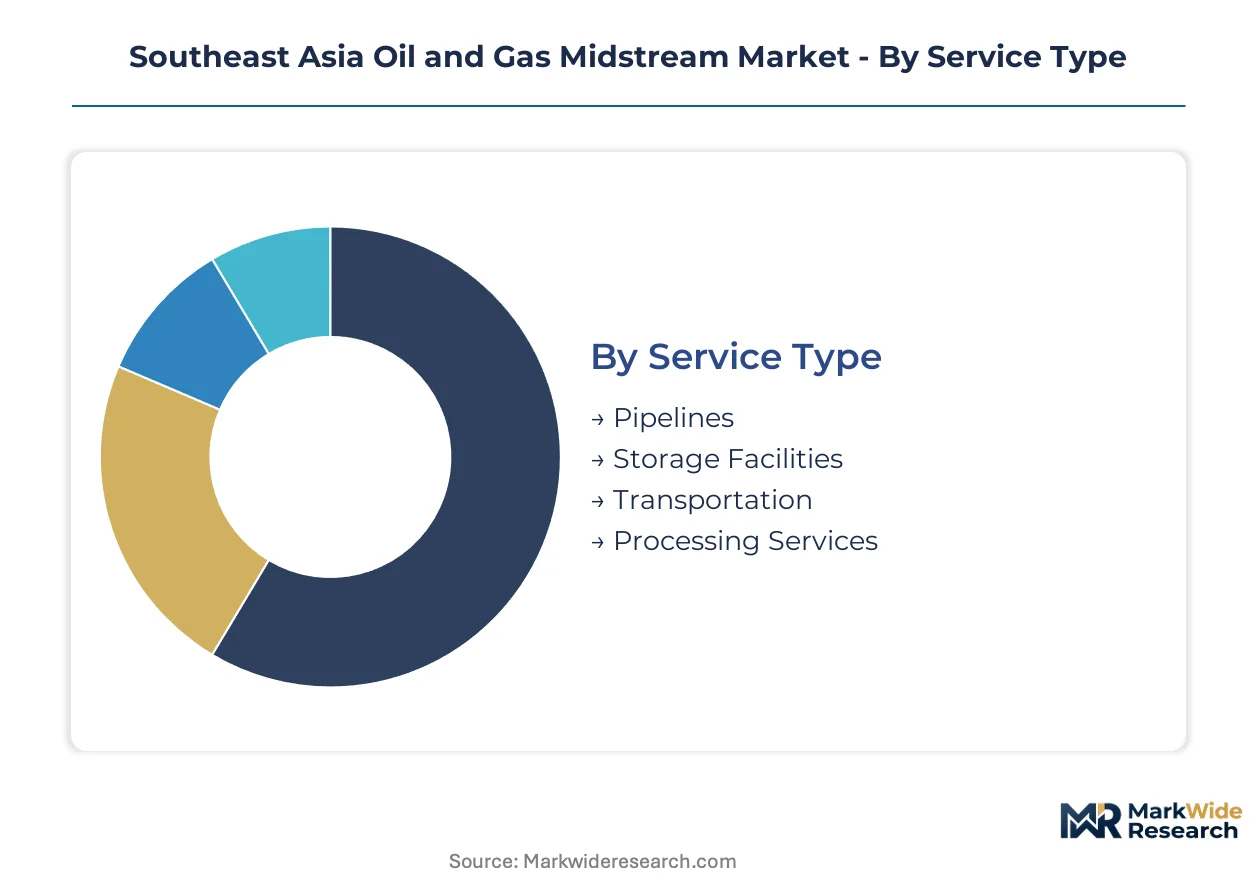
Midstream infrastructure investment decisions diverge sharply across service configurations, technology maturity, and offtake scale. Procurement patterns in Southeast Asia cluster around integrated bundled contracts that compress vendor management overhead while shifting execution risk to EPC contractors.
Service Type:
Buyers differentiate by whether they seek single-point accountability or fragmented specialist procurement across the value chain.
- Pipelines:Cross-border trunk lines operating at 50-150 bar pressure ratings constitute the foundational revenue layer. Indonesia's Java-Sumatra corridor and Malaysia's Peninsular Gas Utilization network anchor regional throughput, though carbon capture retrofit requirements now compress brownfield expansion timelines.
- Storage Facilities:Underground salt caverns and above-ground tank farms provide buffer capacity for seasonal demand swings. Thailand's eastern seaboard petrochemical clusters drive sustained demand for dedicated crude and product storage with integrated pipeline connectivity.
- Transportation:Marine vessel chartering and rail tanker movements handle inter-island logistics where pipeline economics fail. Archipelagic geography across Indonesia and the Philippines necessitates multimodal solutions for feedstock delivery to remote industrial zones.
- Processing Services:Dehydration, sweetening, and fractionation units bridge upstream production with downstream specifications. Vietnam's Block B and Ca Voi Xanh developments exemplify lump-sum turnkey procurement spanning pipeline connection through custody transfer metering.
Volume sits with Pipelines; growth tilts toward Processing Services as integrated contracting displaces fragmented procurement.
Technology:
Technology selection tracks reserve characteristics, with marginal field economics favoring modular architectures over centralized processing hubs.
- Natural Gas Processing:Acid gas removal and NGL recovery units condition raw production for pipeline specifications. Malaysia's PETRONAS advances carbon capture integration into existing networks, embedding fiber-optic sensing and dedicated CO2 metering stations on routes serving Bintulu LNG.
- Liquefaction Technology:Cryogenic trains and FLNG vessels convert stranded gas into exportable LNG at temperatures below minus 162 degrees Celsius. Offshore discoveries in the Philippines and Vietnam require subsea tieback systems and cryogenic transfer solutions for sub-commercial reservoirs.
- Compression Systems:Centrifugal and reciprocating units maintain pipeline pressure across extended tie-in distances. Aging infrastructure across Myanmar's dormant Shwe field corridors creates brownfield rehabilitation demand as regional gas volumes recover.
- Control Systems:SCADA automation and IoT sensor networks enable remote monitoring across jungle terrain and subsea installations. Legacy system integration complexity extends commissioning timelines where 1980s-era protocols require custom gateway solutions.
Revenue concentrates in Natural Gas Processing; automation hardware expands most quickly as operators reduce physical inspection cycles.
End User:
Offtake patterns split between regulated utilities with domestic market obligations and merchant industrial buyers seeking flexible term structures.
- Utility Companies:Power generation firms across Indonesia and Thailand anchor baseload gas demand through long-term offtake agreements. BPH Migas and PETRONAS enforcement of domestic market obligation rules reserves pipeline capacity for local supply before export authorization.
- Industrial Users:Petrochemical and fertilizer producers require dedicated pipeline connectivity with interruptible supply options. Singapore and Thailand's hydrogen feedstock pilots create retrofit demand for existing natural gas infrastructure rated for H2 admixture.
- Government Agencies:State-owned midstream operators control trunk line access and terminal capacity allocation. Vietnam's Ministry of Industry and Trade coordinates offshore licensing with pipeline routing approvals that shape infrastructure sequencing.
- Independent Producers:Small-scale upstream developers seek processing and transportation access without captive infrastructure. Third-party access frameworks governed by Thailand's Energy Regulatory Commission determine tariff structures for non-affiliated shippers.
Contract value pools with Utility Companies; margin expansion favors Independent Producers as regulatory access frameworks mature.
Capacity:
Scale thresholds determine whether projects qualify for standardized EPC pricing or require bespoke engineering with cost-plus contracting.
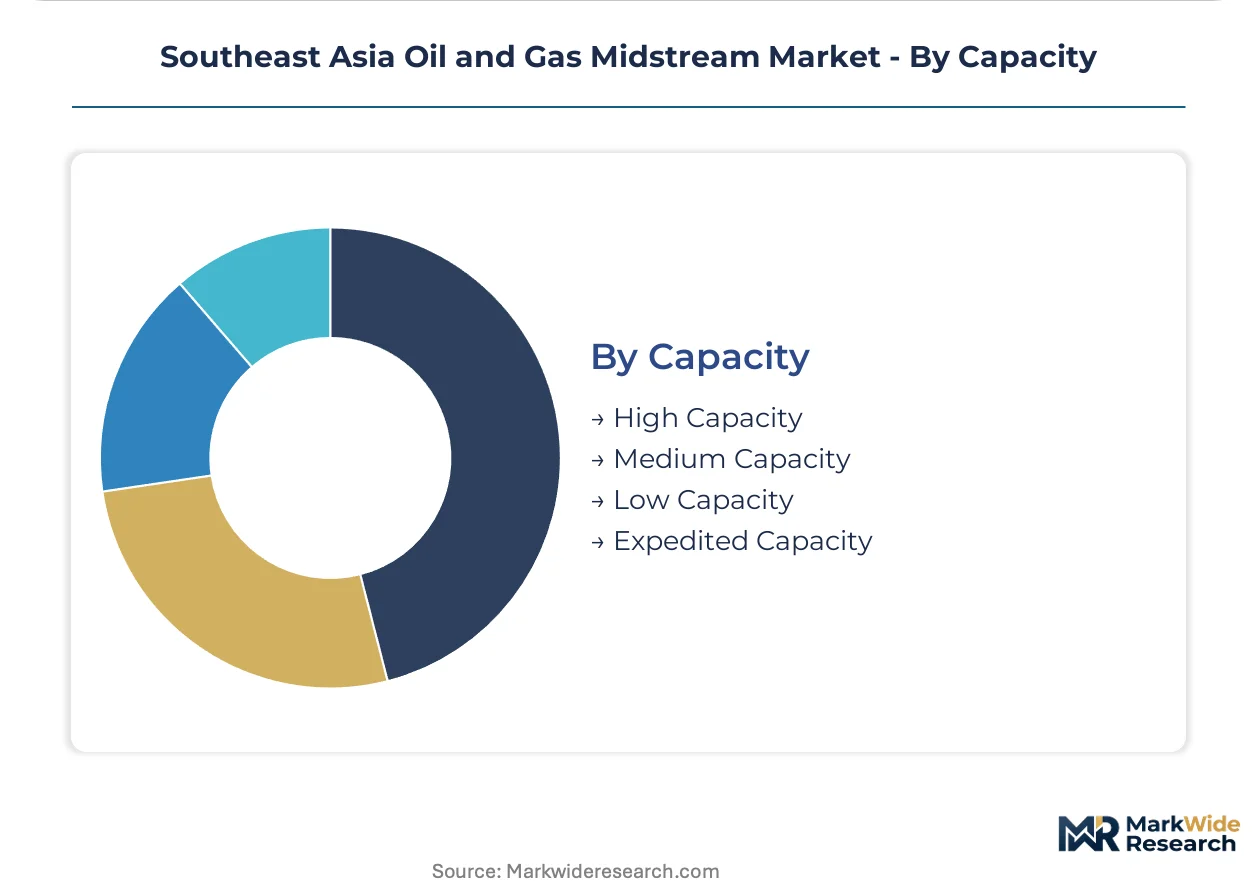
- High Capacity:Trunk lines and export terminals exceeding 500 million cubic feet per day throughput attract integrated contractor consortia. These projects command dedicated project finance structures with multilateral development bank participation.
- Medium Capacity:Regional gathering systems and distribution networks serve industrial estate clusters with predictable offtake profiles. Thailand's eastern seaboard concentration exemplifies sustained demand at this scale tier.
- Low Capacity:Marginal field tie-ins and satellite processing units deploy modular skids for rapid deployment. Compact subsea separation systems eliminate platform construction costs for reservoirs below commercial thresholds.
- Expedited Capacity:Fast-track installations address supply emergencies or temporary production surges. Jungle terrain construction limitations across Borneo and Papua New Guinea extend delivery windows by 40-60% during monsoon seasons, compressing expedited project feasibility.
Capital deployment concentrates in High Capacity; project velocity favors Low Capacity as modular architectures reduce sanctioning risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia dominate midstream throughput while Thailand anchors demand-side infrastructure; Vietnam and the Philippines emerge as growth frontiers where offshore discoveries require new processing corridors.
Indonesia
Power generation utilities expand gas-fired capacity across Java and Sumatra, driving trunk line utilization on the Java-Sumatra corridor. BPH Migas enforces domestic market obligation rules that reserve pipeline capacity for local supply before export authorization. The coastal terminal network around Jakarta and Surabaya anchors PT Pertamina's distribution control.
Malaysia
PETRONAS advances carbon capture integration into existing Peninsular Gas Utilization network infrastructure. The Petroleum Management Unit mandates baseline emissions reporting and third-party audit protocols for new trunk line approvals. Bintulu LNG and Pengerang complexes drive embedded fiber-optic sensing deployment for CO2 monitoring.
Thailand
Industrial estate clustering along the eastern seaboard sustains demand for integrated liquefaction and regasification assets. The Energy Regulatory Commission governs third-party access to PTT's transmission network, shaping tariff structures for non-affiliated shippers. Rayong and Map Ta Phut petrochemical corridors concentrate dedicated pipeline connectivity investment.
Vietnam
Offshore gas discoveries at Block B and Ca Voi Xanh require subsea tieback systems and dedicated processing infrastructure. The Ministry of Industry and Trade coordinates offshore licensing with pipeline routing approvals that shape infrastructure sequencing. Power utilities negotiate lump-sum turnkey agreements spanning pipeline connection through custody transfer metering.
Philippines
Marginal offshore fields drive floating LNG technology adoption and cryogenic transfer solution demand. Malampaya field depletion pressures regulators to accelerate new pipeline corridor approvals for replacement supply. Subsea processing modularization enables production from reservoirs previously classified as sub-commercial.
Southeast Asia Oil and Gas Midstream Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Southeast Asia's midstream infrastructure layer. National oil companies anchor trunk line ownership and terminal capacity allocation, while international engineering contractors capture technology-intensive subsea and processing segments. Two strategic archetypes dominate: state-integrated operators leveraging captive infrastructure for end-to-end service bundling, and specialized EPC firms deploying modular architectures for marginal field economics. Competitive positioning sharpens through integrated service contracting consolidation and carbon capture retrofit capability differentiation.
Among Malaysia-based operators, Petronas and Petronas Gas Berhad exemplify the state-integrated archetype with control of peninsular transmission networks and LNG export terminals. Thailand's PTT Public Company Limited occupies a parallel position anchoring eastern seaboard infrastructure. Indonesia's PT Pertamina and PT Perusahaan Gas Negara represent the archipelagic variant, managing Java-Sumatra corridor throughput and coastal terminal distribution. Vietnam Oil and Gas Group sits within the emerging frontier tier where offshore licensing coordination shapes infrastructure sequencing. TechnipFMC plc anchors the technology-specialist segment, with subsea processing and FLNG deployment capability.
| Leading Market Players |
|---|
| Petronas |
| PT Pertamina |
| PTT Public Company Limited |
| Vietnam Oil and Gas Group |
| Petronas Gas Berhad |
| PT Perusahaan Gas Negara |
| Gas Malaysia Berhad |
| TechnipFMC plc |
| PT Connusa Energindo |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel futures and molybdenum spot quotations cascade through Southeast Asian midstream procurement, compressing EPC contractor margins on fixed-price linepipe contracts while tiering project economics across premium X100 grades, standard X80 specifications, and economy-grade carbon steel alternatives.
Pricing Analysis
Margin tightening in high-grade linepipe procurement reflects volatile alloy commodity markets, with X80 and X100 grade specifications commanding premium-mid-economy pricing differentiation based on nickel content and sour-service certification tiers. Cost-down pressure on standard-grade carbon steel accelerates because Indonesian and Malaysian domestic market obligation frameworks reserve baseline throughput for local supply, squeezing export-authorized volumes into narrower margin pools. Utility companies anchor long-term offtake agreements with lowest price sensitivity, while independent producers and small-scale upstream developers exhibit highest sensitivity to tariff fluctuations and interruptible supply premiums.
Supply Chain Analysis
Indonesian domestic content mandates under BPH Migas licensing reshape sourcing patterns, requiring minimum local participation thresholds for pipeline construction and terminal fabrication that redirect procurement toward domestic steel mills and fabrication yards. Geographic supply concentration centers on South Korea and Japan for specialized linepipe alloys, with China anchoring standard-grade carbon steel and modular processing skids. Raw material dependencies draw from nickel-molybdenum alloy feedstocks, cryogenic insulation systems, and subsea umbilical components. Single-source vulnerability in hyperbaric welding labor markets creates bottleneck exposure, as saturated Southeast Asian diving pools force contractor recruitment from West Africa and the Gulf of Mexico. Distribution runs through state-integrated operators controlling trunk line access and terminal capacity allocation across Indonesia, Malaysia, and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia's oil and gas midstream sector sits in a technology-transition phase, with digital twin convergence and IoT sensor networks displacing legacy SCADA systems that require custom protocol gateways for brownfield integration.
For Market Incumbents: Anchor carbon capture retrofit capability as the primary defensive moat, embedding fiber-optic sensing and dedicated CO2 metering stations along existing Peninsular Gas Utilization and Java-Sumatra corridors before regulatory mandates compress project timelines. Consolidate subsea processing technology partnerships to neutralize TechnipFMC's modular architecture advantage in marginal field economics. Vertical integration into cryogenic transfer solutions for floating LNG deployments protects against pure-play specialist encroachment in Philippines and Vietnam frontier basins. For New Entrants and Emerging Players: EPC contractors with modular skid fabrication expertise represent the most accessible channel partner type for penetrating Vietnam's Block B and Ca Voi Xanh developments, where lump-sum turnkey procurement patterns concentrate vendor risk and create entry openings for specialized execution teams. Target Myanmar's dormant Shwe field corridor rehabilitation as the most penetrable geography, leveraging brownfield redevelopment demand as regional gas volumes recover. Position through hydrogen blending infrastructure pilots in Singapore and Thailand, offering retrofit engineering for existing natural gas pipelines rated for H2 admixture up to 20 percent by volume. For Investors and Strategic Acquirers: Distressed-cycle entries favor subsea processing technology specialists with proven FLNG deployment track records in Sarawak and Gulf of Thailand marginal fields, where reserve depletion pressures and capital discipline create acquisition windows. Long-term viability hinges on carbon capture integration capability across the analysis window, as Malaysia's Petroleum Management Unit mandates baseline emissions reporting and third-party audit protocols for new trunk line approvals. Monitor ASEAN Power Grid interconnection progress as the critical inflection signal, with accelerated grid integration redirecting gas demand from power generation toward industrial hydrogen feedstock applications and compressing traditional midstream throughput projections.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | Mandatory CO2 monitoring under Malaysia's Petroleum Management Unit reshapes brownfield investment criteria. |
| Floating LNG Technology Adoption | Offshore discoveries in Philippines and Vietnam require subsea tieback systems and cryogenic transfer solutions. |
| Digital Twin Convergence | IoT sensor integration with predictive maintenance platforms reduces physical inspection cycles across jungle terrain installations. |
| Hydrogen Blending Infrastructure | Singapore and Thailand industrial pilots create retrofit demand for existing natural gas pipeline networks. |
| Integrated Service Contracting | Lump-sum turnkey agreements in Vietnam's power sector compress vendor management overhead while concentrating execution risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with pipeline operators, EPC contractors, utility procurement officers, and subsea engineering specialists alongside validation against BPH Migas domestic market obligation reports, PETRONAS sustainability disclosures, and Thailand Energy Regulatory Commission third-party access tariffs. Bottom-up project pipeline tracking and top-down sectoral demand modeling provided triangulation across data sources.
Granularity-level modeling operated at service-type, technology, end-user, and capacity-tier dimensions, with additional segmentation by domestic market obligation status and carbon capture retrofit requirement tiers. CAGRs derived from volume-throughput projections against infrastructure commissioning timelines, incorporating LNG export capacity multipliers, industrial estate clustering density, and subsea field development economics throughout the forecast period. Forecast inputs included pipeline pressure rating specifications, cryogenic temperature handling requirements, and modular processing architecture adoption curves.
Caveats apply where nickel-molybdenum commodity volatility, cross-border regulatory friction, or subsea welding labor scarcity could materially shift the outlook. Forecasts reflect documented assumptions regarding ASEAN Power Grid interconnection pace and hydrogen feedstock pilot commercialization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Canada LNG Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Well Test Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Global Floating LNG Terminal Market