
 GCC Oil and Gas Separation Market | 2026-2036
GCC Oil and Gas Separation Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Oil and Gas Separation Market Intelligence
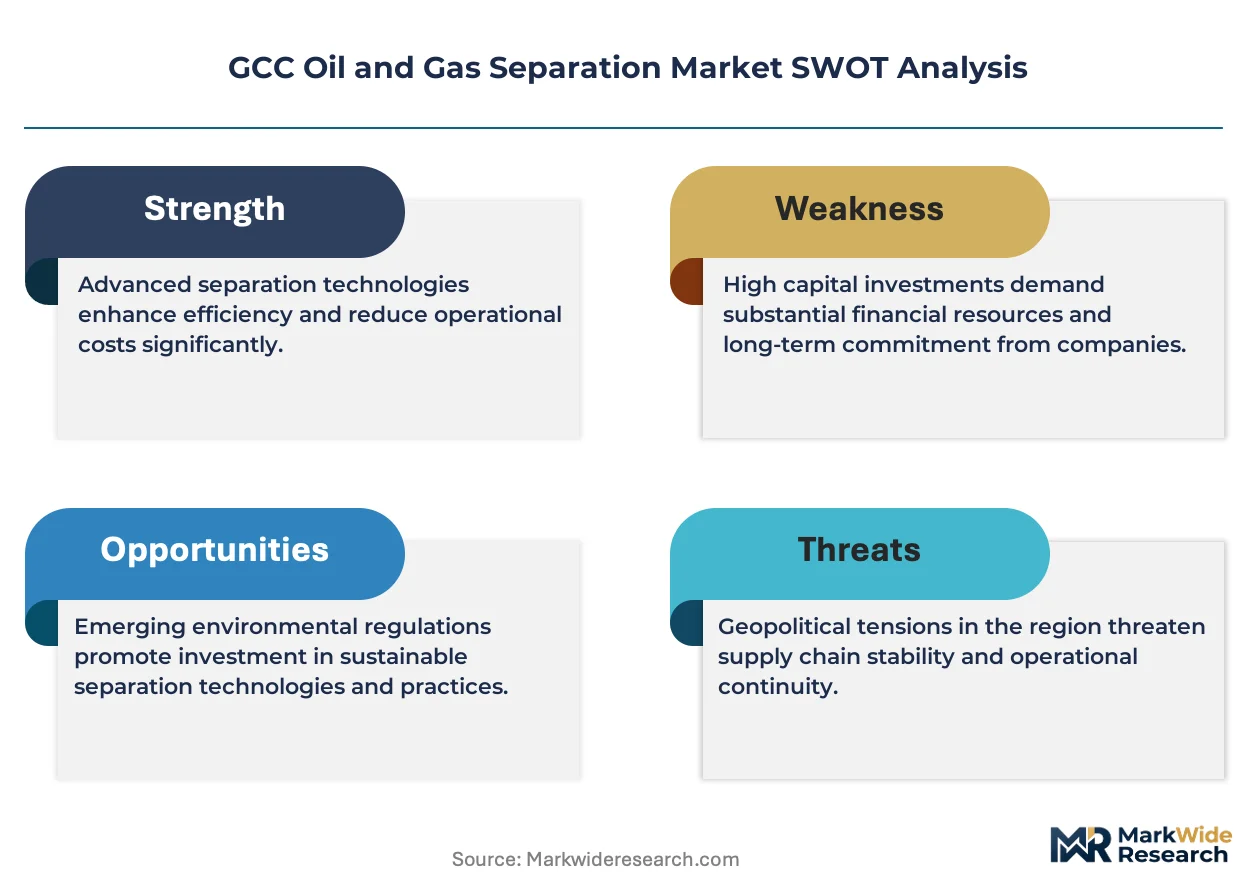
Project finance and leasing structures for offshore separation packages is narrowing the competitive field to firms with balance-sheet depth. Schlumberger Limited leverages integrated project delivery models that bundle separation hardware with long-term service contracts. Baker Hughes Company anchors its position through turbomachinery expertise that extends into high-pressure gas-liquid separation systems. NOV Inc. competes by dominating the subsea separation niche where capital intensity deters smaller entrants.
GCC oil and gas separation encompasses the mechanical and physicochemical processes that isolate crude oil, natural gas, water, and solids at wellhead and processing facilities, typically operating at pressures from 50 to 2,000 psi and temperatures up to 150°C depending on reservoir conditions. Gravity separators remain the workhorse technology across onshore Saudi and Kuwaiti fields, though centrifugal separators are gaining share in offshore UAE developments where footprint constraints command premium pricing. Membrane separators occupy a nascent but strategically significant position for gas dehydration and carbon capture readiness at Qatar's North Field expansion sites.
Saudi Arabia's Presidency of Meteorology and Environment enforces flaring restrictions that mandate closed-loop separation with vapor recovery, while UAE's Federal Authority for Nuclear Regulation and environmental standards bodies impose water discharge limits that drive produced water treatment integration. Kuwait's Environmental Public Authority adds compliance layers for sour gas handling that favor electrostatic separator upgrades. Stakeholders must weigh brownfield retrofit economics against greenfield modular designs as reservoir maturity across the GCC shifts produced fluid compositions toward higher water cuts and lower API gravities.
Market Dynamics
Offshore footprint constraints across UAE and Qatar fields are compressing separator vessel dimensions while demanding higher throughput, forcing modular skidded systems to displace conventional gravity vessels in brownfield retrofits.
Growth Catalysts
- Zero-flare mandates:Saudi Arabia's Presidency of Meteorology and Environment enforces vapor recovery integration that mandates closed-loop separation hardware upgrades at all onshore facilities.
- High-pressure gas-liquid separation:Deepwater developments in Qatar's North Field require compact separators operating above 1,500 psi, driving specialized turbomachinery procurement cycles.
- Eastern Province concentration:Ghawar and Safaniya field maturation generates replacement demand for aging gravity infrastructure across Saudi Aramco's operated assets.
Market Restraints
- Specialized alloy input costs:Duplex stainless steel and Inconel pricing volatility directly pressures vessel fabrication margins for high-sour service applications.
- Subsea supplier concentration:Only three qualified fabricators globally can deliver subsea separation modules, creating bottleneck risk for UAE offshore timelines.
- Membrane technical limitations:Polymeric gas dehydration membranes face temperature ceilings below 120°C that exclude high-temperature reservoir applications in Kuwait.
Strategic Opportunities
- Carbon capture readiness:Qatar's North Field expansion mandates membrane-integrated separation trains that pre-stage CO2 capture infrastructure.
- Produced water treatment convergence:Electrostatic coalescer upgrades in Kuwait's Burgan field enable integrated oil-water-gas separation with discharge compliance.
- Leasing and performance contracting:Schlumberger and Baker Hughes deploy separation-as-a-service models that shift capex burdens to opex for marginal field operators.
Industry Challenges
- Subsea welding certification timelines:DNV-ST-F101 qualification for hyperbaric welders extends project schedules by eight to fourteen months.
- Legacy SCADA integration:Brownfield gravity separator retrofits require protocol bridging between 1980s-era control systems and modern digital twins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Oil and Gas Separation Market |
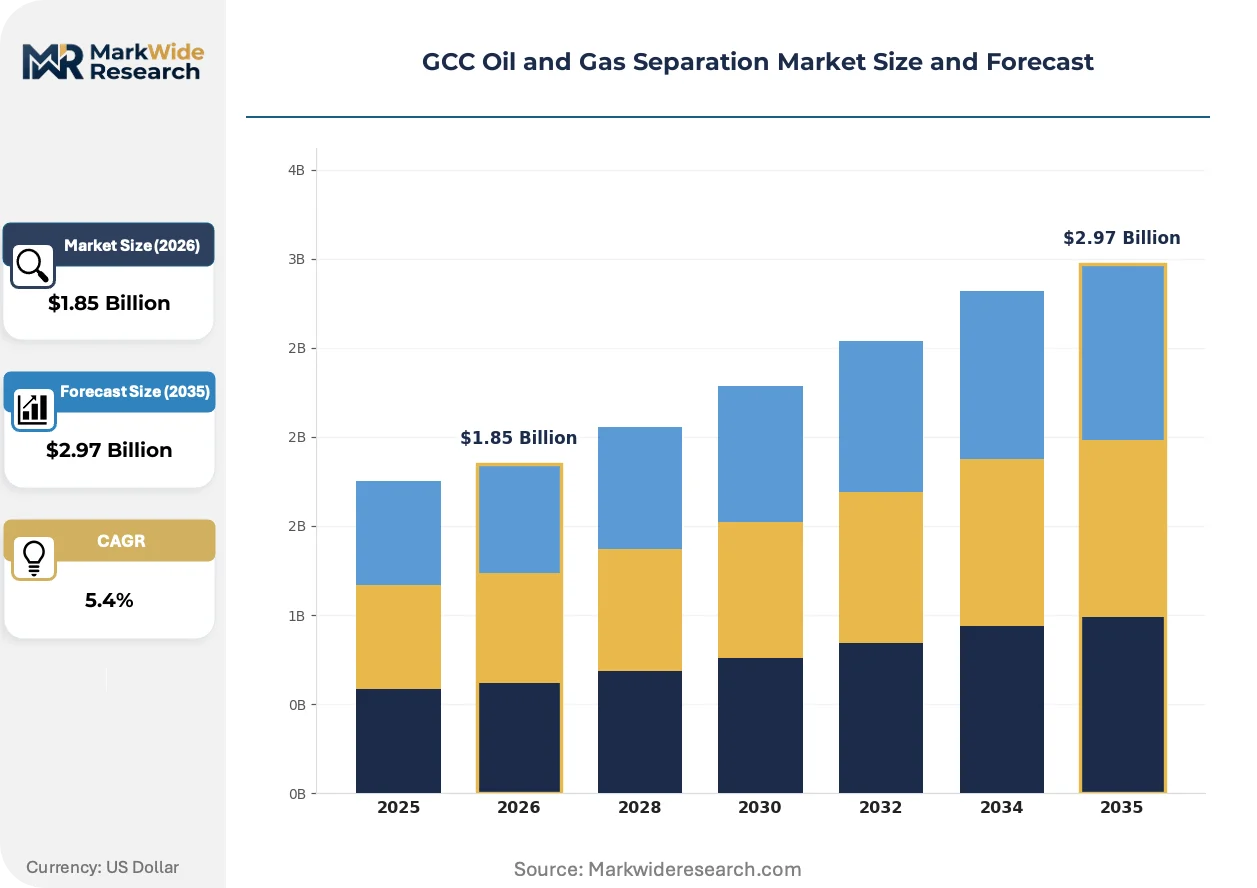
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Separators, Gravity Separators, Centrifugal Separators, Electrostatic Separators Technology: Continuous, Batch, Hybrid, Thermal Application: Crude Oil Processing, Natural Gas Processing, Water Treatment, Sulfur Recovery End User: Refineries, Petrochemical Plants, Exploration Companies, Utility Providers |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, TechnipFMC plc, NOV Inc., Alfa Laval, Sulzer Ltd., Cameron, Air Products and Chemicals, Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Oil and Gas Separation Market Strategic Shifts & Innovations
Digital instrumentation and real-time optimization software are displacing manual separator control across GCC offshore platforms, while regulatory pressure on flaring accelerates closed-loop hardware adoption.
Multiphase flow meters combined with machine learning algorithms are digitizing separator inlet characterization, enabling predictive control of residence times and chemical dosing. ADNOC's offshore operations deploy these systems at fifteen-day commissioning cycles versus ninety days for conventional test separators. The technology is digitizing maintenance scheduling by correlating sand production rates with erosion patterns in real time.
Saudi Arabia's Presidency of Meteorology and Environment tightened flaring restrictions to ninety-eight percent utilization minimums, mandating vapor recovery unit integration at all new wellhead facilities. This policy compresses project timelines by requiring front-end engineering to incorporate closed-loop separation from concept phase. Operators in the Empty Quarter gas fields respond by specifying compact electrostatic separators with integrated compressor packages.
Buyer concentration among national oil companies is compressing vendor qualification timelines and unbundling after-sales service from hardware procurement. Saudi Aramco now requires five-year availability guarantees with penalty clauses, displacing traditional time-and-materials maintenance contracts. This pattern appears most acutely in the Eastern Province, where framework agreements with Schlumberger and Baker Hughes lock out smaller fabricators from major replacement cycles.
GCC Oil and Gas Separation Market Segmentation
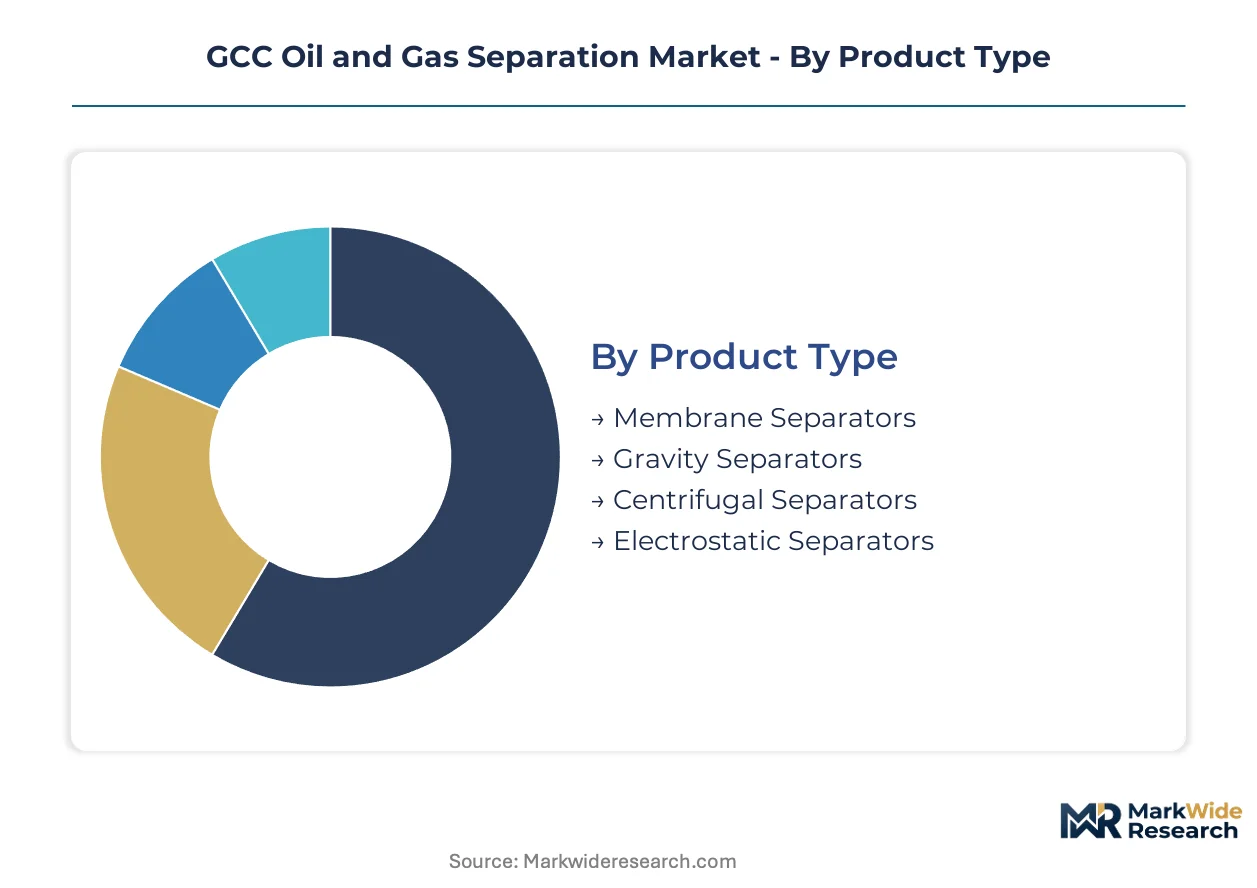
Segmentation in GCC oil and gas separation reflects divergent capital intensity, maintenance burdens, and regulatory compliance requirements across product types and applications. National oil companies structure procurement frameworks around lifecycle service commitments rather than standalone hardware transactions.
Product Type:
After-sales-service intensity varies dramatically across separator categories, with membrane and electrostatic systems demanding specialized technician networks that only integrated service providers can sustain.
- Gravity Separators:These vessels rely on density differential settling at atmospheric to moderate pressures, typically fabricated from carbon steel or duplex stainless for sour service. Demand concentrates in Saudi Arabia's Eastern Province where Ghawar and Safaniya field maturation drives replacement of 1980s-era horizontal separators with corrosion-resistant upgrades.
- Centrifugal Separators:Rotating drum assemblies generate centrifugal forces exceeding 1,000 G for compact footprint applications. UAE offshore developments in Upper Zakum and Satah al Razboot fields specify these units where platform space constraints command premium engineering.
- Membrane Separators:Polymeric or ceramic membranes achieve gas dehydration and selective permeation at Qatar's North Field expansion pre-staging carbon capture infrastructure.
- Electrostatic Separators:High-voltage coalescing grids enhance water-oil separation efficiency for Kuwait's Burgan field produced water treatment integration.
Gravity separators hold the largest share; momentum sits with membrane systems gaining share fastest.
Technology:
Technology selection tracks reservoir fluid characteristics and water cut trajectories, with continuous systems dominating high-volume offshore while batch processing persists in marginal onshore stripper wells.
- Continuous:Uninterrupted flow processing with real-time level control and automated chemical injection dominates Saudi Aramco's Ghawar field central processing facilities handling over five million barrels daily.
- Hybrid:Combined gravity-centrifugal or membrane-adsorption trains optimize for variable feedstock compositions at QatarEnergy's North Field expansion trains.
- Batch:Intermittent processing cycles suit low-rate wells and pilot test facilities requiring flexible turnaround schedules.
- Thermal:Heated separation vessels address high-viscosity crudes and paraffin-heavy production from Kuwait's heavy oil thermal projects.
Continuous technology dominates installed base; hybrid configurations are climbing the fastest as operators retrofit for carbon capture readiness.
Application:
Application segmentation aligns with downstream value chain position, with crude oil processing commanding the highest vessel specification tiers due to entrained solids and corrosive species.
- Crude Oil Processing:Three-phase separation of oil, gas, and produced water at wellhead and central gathering stations requires corrosion-resistant alloys and sand handling capability for Saudi Arabia's high-sour crudes.
- Water Treatment:Produced water polishing for discharge or reinjection integrates hydrocyclones, flotation cells, and membrane bioreactors at UAE's Upper Zakum offshore complex meeting Federal Authority for Nuclear Regulation environmental standards.
- Natural Gas Processing:Dew point control and liquid recovery from gas streams utilizes glycol contactors and Joule-Thomson expansion at Qatar's LNG trains.
- Sulfur Recovery:Acid gas handling and Claus unit feed preparation demands specialized metallurgy for Kuwait's sour gas developments.
Crude oil processing maintains the largest application share; water treatment is expanding most quickly on regulatory discharge mandates.
End User:
End user concentration among national oil companies compresses vendor qualification timelines and unbundles maintenance from hardware procurement.
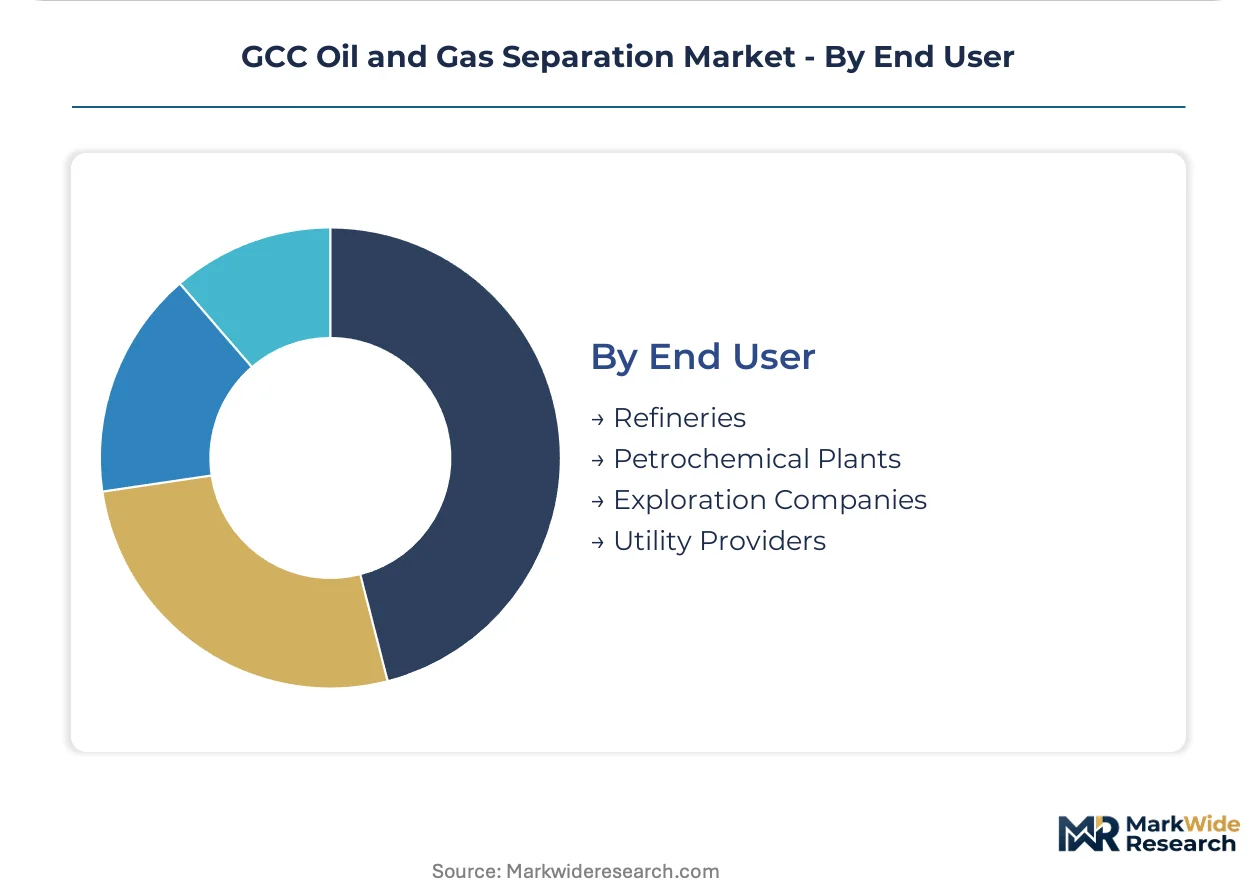
- Exploration Companies:Upstream operators including Saudi Aramco, ADNOC, and QatarEnergy specify separation trains through framework agreements locking in five-year availability guarantees with penalty clauses.
- Refineries:Downstream processing units require desalting and crude stabilization vessels meeting strict product quality specifications for export grades.
- Petrochemical Plants:Feedstock purification for ethylene crackers and aromatics complexes demands high-purity separation with tight contaminant specifications.
- Utility Providers:Power generation and water desalination facilities utilize fuel gas conditioning and steam separation equipment.
Exploration companies command the largest end user position; petrochemical plant retrofits show the steepest expansion trajectory on feedstock flexibility investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National oil companies across the Gulf Cooperation Council concentrate procurement authority, compressing vendor qualification timelines and favoring established service integrators over standalone equipment fabricators. Saudi Aramco, ADNOC, and QatarEnergy collectively account for the dominant share of separation system demand through framework agreements that bundle hardware with long-term service commitments.
Saudi Arabia
Ghawar and Safaniya field maturation drives replacement cycles for 1980s-era gravity separators across the Eastern Province. The Presidency of Meteorology and Environment enforces zero-flare mandates requiring vapor recovery integration at all new wellhead facilities. Dhahran-based engineering clusters coordinate centralized procurement for Saudi Aramco's operated assets.
United Arab Emirates
Offshore developments at Upper Zakum and Satah al Razboot fields specify compact centrifugal separators where platform footprint constraints command premium engineering. The Federal Authority for Nuclear Regulation imposes water discharge limits that drive produced water treatment integration. Abu Dhabi serves as the procurement hub for ADNOC's offshore separation packages.
Qatar
North Field expansion mandates membrane-integrated separation trains that pre-stage carbon capture infrastructure for LNG train feedstock preparation. QatarEnergy's engineering specifications require specialized high-pressure gas-liquid separation above 1,500 psi. Ras Laffan Industrial City hosts the fabrication and integration facilities for these complex trains.
Kuwait
Burgan field produced water treatment upgrades favor electrostatic coalescer integration with three-phase separation systems. The Environmental Public Authority adds compliance layers for sour gas handling that drive metallurgical upgrades to duplex stainless and Inconel. Ahmadi Governorate concentrates Kuwait Oil Company's central engineering functions.
GCC Oil and Gas Separation Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that rewards integrated project delivery over standalone equipment sales. The vendor base stratifies into three tiers: global service companies with balance-sheet depth for project finance, specialized turbomachinery and subsea fabricators with technical moats, and regional maintenance providers serving brownfield retrofit demand. Dominant competitive moves include bundling separation hardware with long-term performance contracts and acquiring specialized welding certifications for subsea module fabrication.
Among the integrated service tier, Schlumberger Limited and Baker Hughes Company exemplify the project-delivery archetype that bundles hardware with availability guarantees. NOV Inc. occupies a distinct position within subsea separation where capital intensity and certification requirements deter smaller entrants. These three anchors represent the competitive standard against which qualification frameworks from Saudi Aramco, ADNOC, and QatarEnergy calibrate vendor selection.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| TechnipFMC plc |
| NOV Inc. |
| Alfa Laval |
| Sulzer Ltd. |
| Cameron |
| Air Products and Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Duplex stainless steel and Inconel price volatility determines both the premium-to-economy tier spreads for high-sour service vessels and the geographic clustering of fabrication capacity around raw material access points. Saudi Aramco's five-year availability guarantee requirements compress margin structures for contractors while favoring balance-sheet-heavy integrators capable of absorbing alloy input cost swings.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate vessel procurement for Saudi Aramco and ADNOC framework agreements. Price differentiation rests on metallurgical grade certification and bundled after-sales service intensity, with Inconel-clad separators commanding substantial premiums over carbon steel equivalents. Cost compression in standard gravity vessel tiers is intensifying as Chinese fabricators qualify for Kuwait Oil Company procurement lists. Marginal field operators exhibit highest price sensitivity, while QatarEnergy's North Field expansion projects prioritize technical specification compliance over unit cost minimization.
Supply Chain Analysis
Upstream feedstock for specialized alloys draws from nickel mines in Indonesia, chromium operations in South Africa, and molybdenum extraction in Chile. Vessel fabrication capacity concentrates in South Korea, Singapore, and the UAE's Jebel Ali corridor, with DNV-ST-F101 certified welding labor acting as the binding constraint. Single-source vulnerability sits with hyperbaric welding certification timelines that extend project schedules by eight to fourteen months. Distribution runs through engineering-procurement-construction contractors holding master service agreements with national oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-flare mandates from Saudi Arabia's Presidency of Meteorology and Environment are accelerating hardware replacement cycles across the GCC, creating a high-growth disruption window for separation technology providers with integrated service capabilities.
For Market Incumbents: Build certification moats around DNV-ST-F101 hyperbaric welding qualifications that lock out smaller fabricators from subsea separation modules. Deepen backward integration into alloy supply through long-term offtake agreements with Indonesian nickel producers to defend margin position against volatile input costs. Counter the threat of Chinese vessel fabricators qualifying for Kuwait Oil Company procurement by embedding five-year availability guarantees with penalty clauses into Saudi Aramco framework renewals. For New Entrants and Emerging Players: Build out membrane separator servicing capabilities targeting Qatar's North Field expansion sites where polymeric gas dehydration systems require specialized technician networks that incumbent turbomachinery providers under-resource. Target Kuwait's Burgan field electrostatic coalescer retrofit segment, the most penetrable white space given Environmental Public Authority discharge compliance deadlines. Pursue leasing and performance contracting models that shift capex burdens to opex for marginal field operators in the Empty Quarter gas fields. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors integrated project delivery specialists with balance-sheet depth for availability guarantee underwriting. Long-term viability over the coming decade hinges on carbon capture readiness positioning as QatarEnergy pre-stages CO2 capture infrastructure. Acquisition targets should display subsea separation module fabrication credentials or membrane-integrated separation train expertise. Monitor Saudi Aramco Eastern Province replacement cycle announcements as the primary inflection signal for sector-wide demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Welding Certification Investment | DNV-ST-F101 qualification creates eight-to-fourteen-month competitive barriers for rival fabricators. |
| Alloy Supply Backward Integration | Long-term nickel and Inconel offtakes from Indonesian and South African sources stabilize fabrication margins. |
| Membrane-Separation Service Network Buildout | Specialized technician deployment for Qatar's North Field polymeric systems captures high-margin aftermarket revenue. |
| Performance Contracting Model Expansion | Separation-as-a-service offerings shift capex to opex for marginal field operators across Saudi Arabia's Empty Quarter. |
| Carbon Capture Readiness Integration | Membrane-train pre-staging for CO2 capture aligns with QatarEnergy's LNG expansion engineering specifications. |
Research Approach
A standing panel of separation technology engineers, national oil company procurement directors, EPC project managers, and aftermarket service heads provided ongoing calibration across the primary research phase. Secondary validation drew from Saudi Aramco supplier qualification databases, ADNOC tender announcements, QatarEnergy engineering specifications, DNV certification registries, and GCC customs import records for specialized alloy vessels. Bottom-up unit economics for gravity, centrifugal, membrane, and electrostatic separator categories were triangulated against top-down national oil company capex disclosure aggregates.
Scenario-bracketing around regulatory enforcement intensity, alloy price volatility bands, and subsea project sanctioning timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology configuration, application stage, and end-user procurement sophistication. CAGRs were derived from replacement cycle analysis for aging infrastructure in Saudi Arabia's Eastern Province and greenfield development schedules for Qatar's North Field expansion. Industry-specific forecast inputs encompassed reservoir maturation water-cut trajectories and Presidency of Meteorology and Environment zero-flare compliance deadlines.
Stress conditions across nickel and Inconel price spikes, DNV certification backlog extensions, and Saudi Aramco framework agreement re-tendering schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding national oil company procurement continuity and regulatory enforcement consistency. Cross-checking against IEA Middle East upstream investment trackers and GCC industrial import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Natural Gas Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Tight Gas Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Oil and Gas Accumulators Market