
 United Arab Emirates Fuel Station Market | 2026-2036
United Arab Emirates Fuel Station Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Fuel Station Market Analytics
Fleet operators is collapsing as the dominant buyer archetype across the UAE fuel station landscape while individual passenger vehicle share stagnates. ADNOC Distribution leverages its nationwide retail footprint to anchor volume throughput across emirate-level corridors. ENOC competes through integrated supply chain control from import terminals to forecourt delivery. CAFU differentiates via mobile refueling applications that bypass traditional station infrastructure entirely.
United Arab Emirates fuel stations comprise fixed retail and commercial dispensing facilities engineered for hydrocarbon and alternative fuel transfer, typically featuring underground storage tanks with 30,000-75,000 liter capacity, vapor recovery systems, and multi-product dispensers calibrated to local metrology standards. These installations serve as critical nodes in the UAE's transportation energy matrix, bridging refined product import terminals with end-use combustion and emerging electric charging demand. Smart pump technology leads capital deployment as operators retrofit legacy forecourts with contactless payment and real-time inventory telemetry. Mobile applications represent the fastest-growing service modality, compressing delivery times for fleet and commercial accounts. Traditional pump infrastructure remains mature across interior emirates where traffic density limits upgrade returns.
MOHAP, the Emirates Authority for Standardization and Metrology (ESMA), and local civil defense departments enforce fuel storage, dispensing accuracy, and environmental compliance across UAE fuel station operations. These frameworks mandate vapor recovery installation, underground tank integrity testing, and product quality verification that elevate capital requirements for new market entrants. Stakeholders must monitor hydrogen blending pilot programs and carbon intensity benchmarking as the regulatory perimeter expands beyond conventional liquid fuels.
Market Dynamics
Fleet procurement consolidation across Dubai's logistics corridor and Abu Dhabi's industrial zones is compressing transaction volumes into fewer high-volume accounts, forcing operators to reconfigure forecourt layouts and payment systems around commercial throughput rather than retail convenience.
Growth Catalysts
- MOHAP Safety Mandates:Emirates Authority for Standardization and Metrology certification requirements for vapor recovery systems and underground tank integrity testing are accelerating infrastructure replacement cycles at older stations.
- Dual Carbon Goals:UAE federal targets for emissions reduction are channeling capital toward hydrogen blending pilot programs and electric charging bay installations at existing retail sites.
- Smart Pump Networks:Contactless payment integration and real-time inventory telemetry are reducing operational downtime and enabling predictive maintenance scheduling across emirate-level distribution networks.
Market Restraints
- Import Terminal Concentration:Refined product supply chains terminate at a limited number of coastal import facilities, creating single-point vulnerability for interior emirate distribution.
- Metrology Compliance Costs:ESMA calibration standards for multi-product dispensers impose recurring certification expenses that elevate break-even thresholds for low-volume rural stations.
- Mobile Refueling Substitution:Application-based fuel delivery services are capturing fleet accounts that previously anchored station revenue, compressing throughput at fixed retail locations.
Strategic Opportunities
- Sharjah and Northern Emirates:Traffic density limitations have delayed smart infrastructure deployment, creating first-mover advantage for operators willing to absorb upfront retrofit costs.
- Hydrogen Infrastructure:Pilot blending programs at Abu Dhabi industrial zones offer regulatory sandbox access for operators positioned to scale alternative fuel dispensing capabilities.
- Integrated Energy Hubs:Convergence of hydrocarbon dispensing, electric charging, and future hydrogen transfer at single locations aligns with MOHAP's consolidated safety framework evolution.
Industry Challenges
- Legacy System Integration:Civil defense department mandates for automated emergency shutdown systems must interface with decades-old underground tank architectures without triggering extended service interruptions.
- Specialized Technician Scarcity:Vapor recovery installation and smart pump maintenance require certified personnel whose training pipelines have not kept pace with deployment timelines across the Emirates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Fuel Station Market |
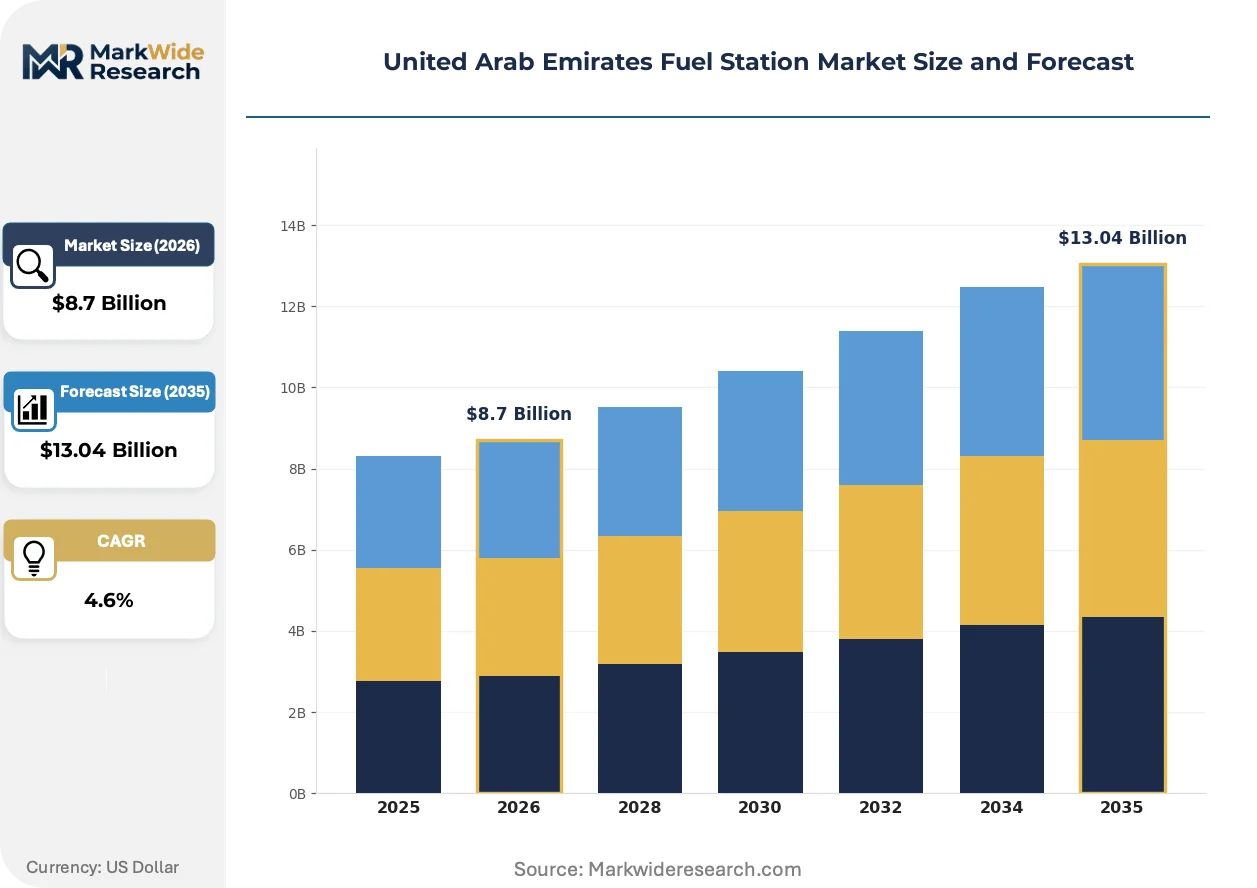
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail, Commercial, Fleet, Marine Fuel Type: Petrol, Diesel, CNG, LPG Technology: Traditional Pumps, Smart Pumps, Self-Service, Mobile Applications End User: Passenger Vehicles, Heavy-Duty Vehicles, Public Transport, Construction |
| Companies Covered | TotalEnergies, CAFU, ADNOC Distribution, Al-Futtaim Blue Fuel, H2GO Power, ENOC, EPCO, Powertech Mobility, Emarat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Fuel Station Market Evolving Landscape
Digital payment architecture and alternative fuel dispensing infrastructure are converging to redefine the functional role of fuel stations from pure hydrocarbon transfer points to multi-modal energy access nodes.
Smart pump technology is miniaturizing sensor arrays and telemetry modules into compact retrofit kits compatible with existing dispenser housings. Fleet operators are demanding these upgrades to enable automated reconciliation with enterprise fuel management systems. The technology is miniaturizing capital deployment barriers, allowing phased infrastructure refresh rather than full forecourt reconstruction.
MOHAP's evolving safety framework now incorporates carbon intensity benchmarking that extends beyond conventional liquid fuels to cover hydrogen blending ratios and electric charging station co-location. Station operators must now document lifecycle emissions across all energy products dispensed. Dubai's logistics corridor stations are responding fastest, submitting consolidated compliance portfolios to preempt enforcement phase-ins.
Commercial buyers are consolidating fuel procurement through centralized fleet management platforms that bypass traditional retail pricing structures. Long-haul trucking operators and municipal vehicle pools are aggregating demand into volume contracts executed through mobile applications or direct terminal access. This concentration is most visible in Abu Dhabi's industrial zones, where integrated energy service contracts now cover fuel, maintenance, and carbon offsetting in single agreements.
United Arab Emirates Fuel Station Market Segmentation
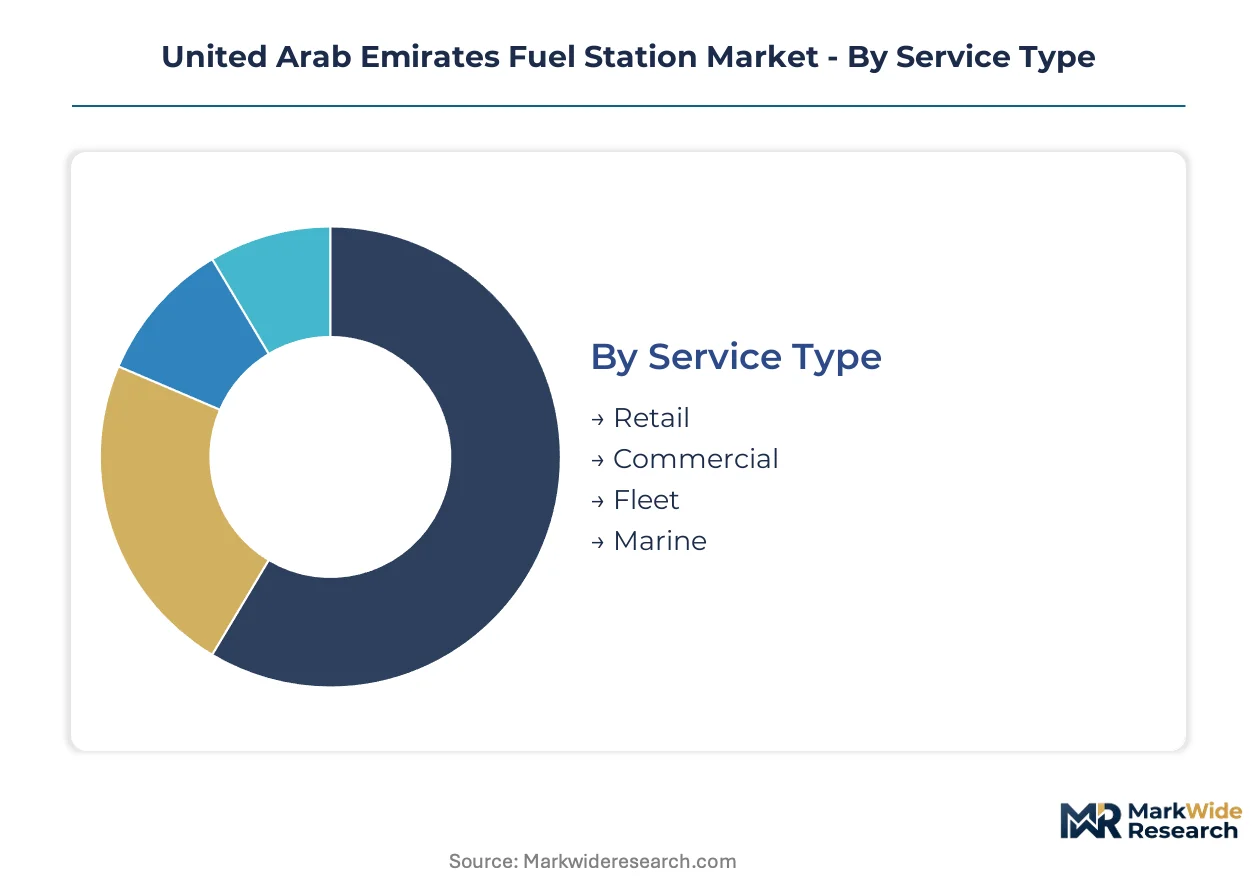
UAE fuel station operators configure infrastructure around distinct demand profiles that diverge sharply between retail convenience and commercial throughput. Segmentation reveals where capital deployment concentrates and which service modalities are displacing legacy formats.
Service Type:
Retail service dominates Dubai's residential corridors and Abu Dhabi's arterial highways, while commercial and fleet accounts anchor volume in industrial zones. Marine bunkering concentrates at Fujairah and Jebel Ali port complexes.
- Retail:Fixed forecourt operations with attended service and convenience retail integration serve individual motorists across all seven emirates. Dubai's logistics corridor stations report the highest transaction frequency per pump as commuter density sustains throughput.
- Commercial:High-volume dispensing for logistics fleets and industrial equipment requires dedicated lanes and automated billing systems. ADNOC Distribution has reconfigured twelve stations across Abu Dhabi's industrial zones for commercial-only access.
- Fleet:Centralized procurement platforms with negotiated terminal access are compressing traditional station margins. CAFU's mobile refueling units now service municipal vehicle pools in Sharjah and Ras Al Khaimah.
- Marine:Coastal bunkering facilities at Fujairah Oil Industry Zone handle heavy fuel oil and marine diesel for international shipping.
Retail commands the established base. The steepest expansion runs through Fleet.
Fuel Type:
Petrol and diesel retain volume leadership, though regulatory pressure on emissions is diversifying the product mix. CNG infrastructure expansion lags despite federal targets.
- Petrol:95-octane and 98-octane grades dispensed through multi-product nozzles constitute the majority of retail transactions. Dubai's passenger vehicle fleet sustains demand concentration.
- Diesel:Ultra-low sulfur formulations for commercial transport and construction equipment dominate Abu Dhabi's industrial zone throughput. ESMA mandates on sulfur content have forced storage tank upgrades at older stations.
- CNG:Compressed natural gas dispensing remains limited to three emirates with pipeline access. ADNOC Distribution operates the only cross-emirate CNG network.
- LPG:Autogas conversions for taxi fleets in Dubai and Sharjah drive specialized dispenser installation.
Diesel anchors commercial revenue. CNG is gaining share fastest where pipeline infrastructure exists.
Technology:
Capital deployment splits between retrofitting legacy infrastructure and greenfield smart installations. Mobile applications are bypassing fixed infrastructure entirely in fleet segments.
- Traditional Pumps:Mechanical metering systems with manual payment processing persist in Northern Emirates where traffic density limits upgrade returns. Ras Al Khaimah and Umm Al Quwain retain the highest concentration.
- Smart Pumps:Contactless payment integration and real-time inventory telemetry enable predictive maintenance scheduling. ENOC has deployed these across Dubai's logistics corridor.
- Self-Service:Unattended dispensing with automated payment verification reduces labor costs at high-volume locations. MOHAP certification requirements for emergency shutdown systems have slowed rollout.
- Mobile Applications:Tanker-based delivery dispatched through smartphone platforms eliminates fixed infrastructure for fleet accounts. CAFU operates the largest fleet in the Emirates.
Traditional pumps hold rural market share. Smart pumps are climbing the fastest in Dubai and Abu Dhabi.
End User:
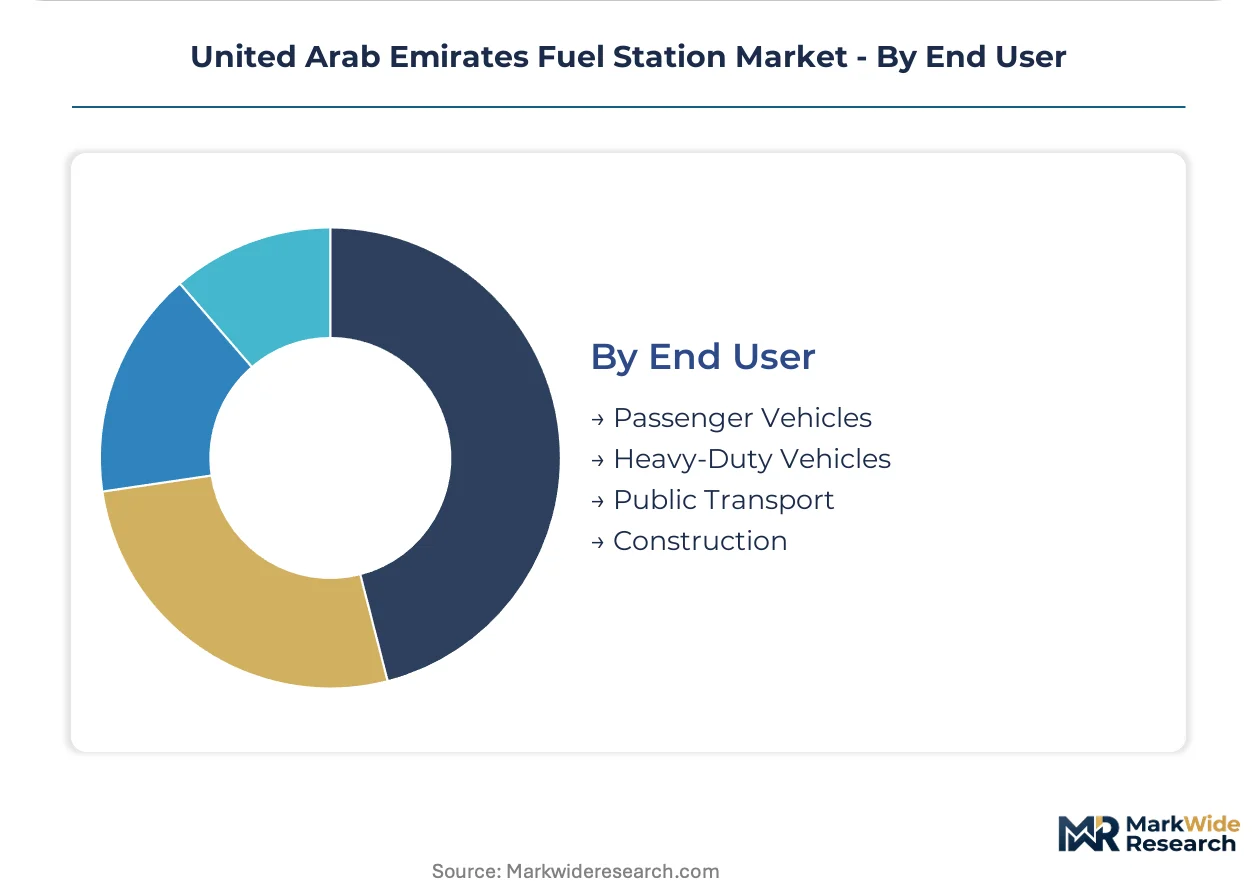
Passenger vehicle demand saturates urban corridors while heavy-duty and construction segments concentrate in industrial zones. Public transport electrification is altering fuel procurement patterns.
- Passenger Vehicles:Individual motorists with variable route patterns require distributed station networks with convenience amenities. Dubai's residential districts sustain the highest pump density per square kilometer.
- Heavy-Duty Vehicles:Long-haul trucking and logistics fleets with predictable routes favor commercial lanes and volume pricing. Abu Dhabi's Khalifa Industrial Zone anchors demand.
- Public Transport:Municipal bus fleets and taxi operators are transitioning procurement to centralized platforms with carbon offset integration. Dubai's Roads and Transport Authority has consolidated fuel buying.
- Construction:Off-road diesel equipment with intermittent refueling needs relies on mobile tanker delivery to active worksites. Sharjah's construction boom has expanded this segment.
Passenger vehicles represent the volume base. Heavy-duty vehicles are expanding most quickly as logistics capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined product import terminals cluster at Jebel Ali and Fujairah, creating distribution radii that shape fuel station density across the seven emirates. Interior stations face elongated supply chains from these coastal nodes. MOHAP and ESMA regulations enforce uniform standards that compress regional operating cost differentials.
Dubai
Logistics fleet procurement dominates commercial throughput along Sheikh Mohammed Bin Zayed Road and Al Khail Road corridors. Dubai's Roads and Transport Authority mandates carbon intensity benchmarking for municipal vehicle fuel contracts. Jebel Ali port anchors marine bunkering operations while Dubai South logistics zone drives high-volume diesel demand from long-haul trucking operators.
Abu Dhabi
Khalifa Industrial Zone and Musaffah industrial district concentrate heavy-duty vehicle refueling for construction and manufacturing equipment. ADNOC Distribution leverages integrated terminal-to-forecourt control under Abu Dhabi National Oil Company ownership. Hydrogen blending pilot programs at industrial zone stations test alternative fuel infrastructure scalability under federal dual carbon targets.
Sharjah
Construction sector diesel demand from active megaproject sites sustains mobile tanker delivery services alongside fixed retail networks. The emirate's civil defense department enforces underground tank integrity testing schedules aligned with MOHAP safety mandates. Sharjah's logistics corridor along Emirates Road experiences delayed smart pump deployment relative to Dubai and Abu Dhabi benchmarks.
Northern Emirates
Ras Al Khaimah and Umm Al Quwain retain traditional mechanical pump infrastructure where traffic density limits smart retrofit returns. CAFU mobile refueling units service municipal vehicle pools across these emirates, bypassing fixed station construction. Federal ESMA calibration standards still apply, elevating compliance costs for low-volume rural operators.
United Arab Emirates Fuel Station Market Competitive Landscape
Concentration sits with state-affiliated distributors holding integrated supply chain control from import terminals through retail forecourts. ADNOC Distribution and ENOC anchor volume leadership through nationwide station networks and direct refined product access. Three archetypes define competitive positioning: integrated national oil company distributors, mobile application-based delivery specialists, and alternative fuel infrastructure pioneers. M&A activity concentrates on terminal asset consolidation and smart technology licensing partnerships.
Within the integrated distributor tier, ADNOC Distribution and ENOC exemplify state-backed vertical control over hydrocarbon supply chains. CAFU occupies the mobile delivery archetype, operating tanker fleets dispatched through smartphone platforms that bypass fixed infrastructure for fleet accounts. TotalEnergies represents the multinational energy major position, leveraging global trading capabilities and alternative fuel technology portfolios. These three anchors illustrate how competitive positioning splits between asset-heavy terminal control, digital service disruption, and international energy transition capital.
| Leading Market Players |
|---|
| TotalEnergies |
| CAFU |
| ADNOC Distribution |
| Al-Futtaim Blue Fuel |
| H2GO Power |
| ENOC |
| EPCO |
| Powertech Mobility |
| Emarat |
| Others |
Value Network & Pricing Analysis
MOHAP vapor recovery certification gates both supplier qualification and price tiering across UAE fuel station operations. ESMA metrology standards for multi-product dispensers create compliance cost stratification that separates high-volume coastal operators from low-throughput interior stations.
Pricing Analysis
ESMA calibration mandates dictate the pricing tier structure across UAE fuel station operations. Pricing stratifies across premium smart-pump installations, standard automated forecourts, and economy-grade mechanical systems in rural emirates. Price differentiation rests on certification grade and volume scale, with fleet procurement platforms extracting steepest discounts through terminal-direct access. Cost compression in the retail tier is intensifying as CAFU mobile delivery captures commuter demand with convenience premiums.
Supply Chain Analysis
Strategic stockpile preferences dominate refined product procurement given UAE import terminal concentration at Jebel Ali and Fujairah. Supply draws from Saudi Aramco term contracts, Kuwait Petroleum spot cargoes, and ADNOC refinery output. Underground storage tank architecture, vapor recovery systems, and smart pump telemetry modules constitute critical component dependencies. Single-source vulnerability concentrates at coastal import facilities where weather disruptions or geopolitical friction could sever interior emirate distribution. Distribution runs through ADNOC Distribution and ENOC integrated networks from terminal to forecourt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile refueling applications threaten fixed infrastructure economics, forcing incumbents to defend throughput through service integration and alternative fuel positioning.
For Market Incumbents: Compound defensive moats by integrating hydrogen dispensing capabilities at industrial zone stations ahead of federal dual carbon enforcement. Deepen backward integration into terminal storage assets to secure supply priority during import disruptions. Anchor fleet relationships through enterprise fuel management system compatibility that CAFU cannot replicate at scale. For New Entrants and Emerging Players: Anchor in Sharjah and Northern Emirates smart pump retrofit demand where traffic density has delayed incumbent capital deployment. Target municipal vehicle pool contracts in Ras Al Khaimah and Umm Al Quwain where CAFU has established mobile delivery presence but fixed infrastructure gaps persist. Pursue white-label smart pump technology licensing to regional petroleum distributors lacking in-house telemetry development. For Investors and Strategic Acquirers: MOHAP's evolving carbon intensity benchmarking reshapes the acquisition landscape toward integrated energy hubs with alternative fuel optionality. Long-term viability favors operators with terminal access, smart infrastructure deployment capability, and regulatory sandbox participation for hydrogen blending. The signal to watch is fleet procurement platform consolidation volume crossing thresholds that trigger incumbent margin compression responses.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Infrastructure Buildout | Positions operators for MOHAP alternative fuel compliance ahead of enforcement phase-ins at Abu Dhabi industrial zones. |
| Smart Pump Retrofit Acceleration | Captures fleet demand for automated reconciliation with enterprise fuel management systems across Dubai logistics corridors. |
| Mobile Application Partnership | Defends retail share against CAFU by embedding delivery scheduling within incumbent loyalty platforms. |
| Terminal Storage Expansion | Reduces single-point vulnerability at Jebel Ali and Fujairah through distributed coastal capacity. |
| Integrated Energy Hub Certification | Aligns with MOHAP consolidated safety framework evolution covering hydrocarbon, electric, and hydrogen co-location. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ESMA regulatory filings, ADNOC Distribution operational disclosures, and ENOC infrastructure investment records. Station operators, fleet procurement managers at Dubai logistics companies, and MOHAP compliance officers provided stakeholder perspective. Customs data on refined product imports and civil defense department inspection schedules supplied secondary validation. Bottom-up station-level throughput estimates triangulated against top-down emirate-level fuel consumption aggregates.
Segmentation dimensions modeled include service type, fuel category, technology tier, and end-user vertical across the projection horizon. CAGRs derived from historical infrastructure deployment rates, regulatory compliance cycle timing, and fleet procurement platform adoption curves. Hydrogen blending pilot program expansion schedules and smart pump retrofit capital allocation patterns informed alternative fuel and technology segment trajectories.
Underlying assumptions cover sustained federal dual carbon commitment, stable refined product import terminal access, and fleet operator platform consolidation trends, with deviation risk concentrated in regulatory enforcement timing and mobile refueling substitution velocity. Revision becomes warranted when mobile delivery volume crosses thresholds that trigger fixed station closure cascades in interior emirates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Europe Bunker Fuel Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Electric Fuel Heater Market
Fuels
CNG Dispenser Market
Fuels
Briquette Market
Fuels
LPG Gas Cylinder Market
Fuels
Fuel Quality Testing Market
Fuels
India Petrol Station Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Storage Tank Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Petroleum Fuel Dyes Sales Market