
 Malaysia Oil and Gas Pipeline Market | 2026-2036
Malaysia Oil and Gas Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Oil and Gas Pipeline Market Foresight
Sarawak's offshore gas infrastructure expansion is reshaping procurement patterns across the Malaysian pipeline sector. Dialog Group Berhad leverages its integrated engineering capabilities to capture maintenance and inspection contracts across PETRONAS-operated fields. MISC Berhad anchors the offshore installation segment with its fleet of specialized pipeline lay vessels operating in deepwater Sabah blocks. Sapura Energy Berhad competes through subsea construction expertise tied to marginal field developments.
Malaysia oil and gas pipelines are high-pressure conduits fabricated from carbon steel or corrosion-resistant alloys, designed to transport crude oil, natural gas, and condensates across onshore processing facilities, offshore platforms, and subsea tiebacks at operating pressures typically exceeding 100 bar. Steel pipelines dominate the product type landscape due to their established welding protocols and compatibility with Malaysia's high-temperature, high-pressure offshore reservoirs. Offshore installation commands premium margins relative to onshore construction, reflecting the technical complexity of subsea tie-ins and the limited availability of specialized marine construction assets. Energy producers represent the most concentrated end-user segment, driven by PETRONAS-led upstream commitments and third-party access regulations under the Malaysian Gas Distribution Act.
Malaysia's Department of Occupational Safety and Health enforces pipeline construction standards under the Petroleum Regulations, while the Energy Commission regulates third-party access to gas transmission networks. The Safety and Health Authority mandates periodic integrity assessments for aging pipelines crossing ecologically sensitive coastal zones and indigenous land reserves. Stakeholders must monitor regulatory shifts around carbon capture readiness requirements for new pipeline approvals, as these standards will determine material specifications and rerouting costs for projects in the Sarawak and Sabah deepwater basins.
Market Dynamics
PETRONAS-led marginal field tiebacks are compressing project timelines and forcing procurement cycles toward modular, pre-fabricated pipeline segments that slash offshore welding hours.
Growth Catalysts
- Third-party access mandates:Malaysia's Gas Distribution Act opens transmission networks to independent power producers and industrial off-takers, expanding addressable demand beyond PETRONAS-operated assets.
- Corrosion-resistant alloy substitution:High-pressure CO2-rich reservoirs in Sarawak's deepwater blocks are accelerating specification upgrades from carbon steel to duplex stainless grades.
- Kertih-Klang Valley corridor saturation:Peninsular Malaysia's industrial gas belt is driving lateral pipeline extensions into southern Johor manufacturing zones.
Market Restraints
- Specialized marine asset scarcity:Southeast Asia's limited fleet of deepwater pipe-lay vessels concentrates installation capacity with Singapore and Malaysian-flagged operators.
- High-grade steel import dependency:Domestic mills lack API 5L X70 and above production capability, exposing project budgets to Korean and Japanese mill pricing volatility.
- Coastal environmental clearance friction:Malaysia's Department of Environment mandates extended impact assessments for pipelines traversing mangrove reserves and turtle nesting zones.
Strategic Opportunities
- Sabah deepwater basin underdevelopment:Unconnected gas discoveries in offshore Sabah await pipeline infrastructure to reach the Bintulu LNG complex.
- Carbon capture readiness retrofit:Pending amendments to Malaysia's Petroleum Regulations will mandate CO2-compatible materials in new pipeline approvals.
- Decommissioning liability transfer:Aging assets in Peninsular Malaysia's mature fields are creating aftermarket inspection and abandonment service contracts.
Industry Challenges
- Welder certification bottlenecks:Malaysia's Department of Occupational Safety and Health enforces ASME Section IX qualification renewals that lag project staffing needs.
- Subsea tie-in integration complexity:Retrofitting new pipelines into live PETRONAS processing platforms demands hot-tap capabilities that few regional contractors possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Oil and Gas Pipeline Market |
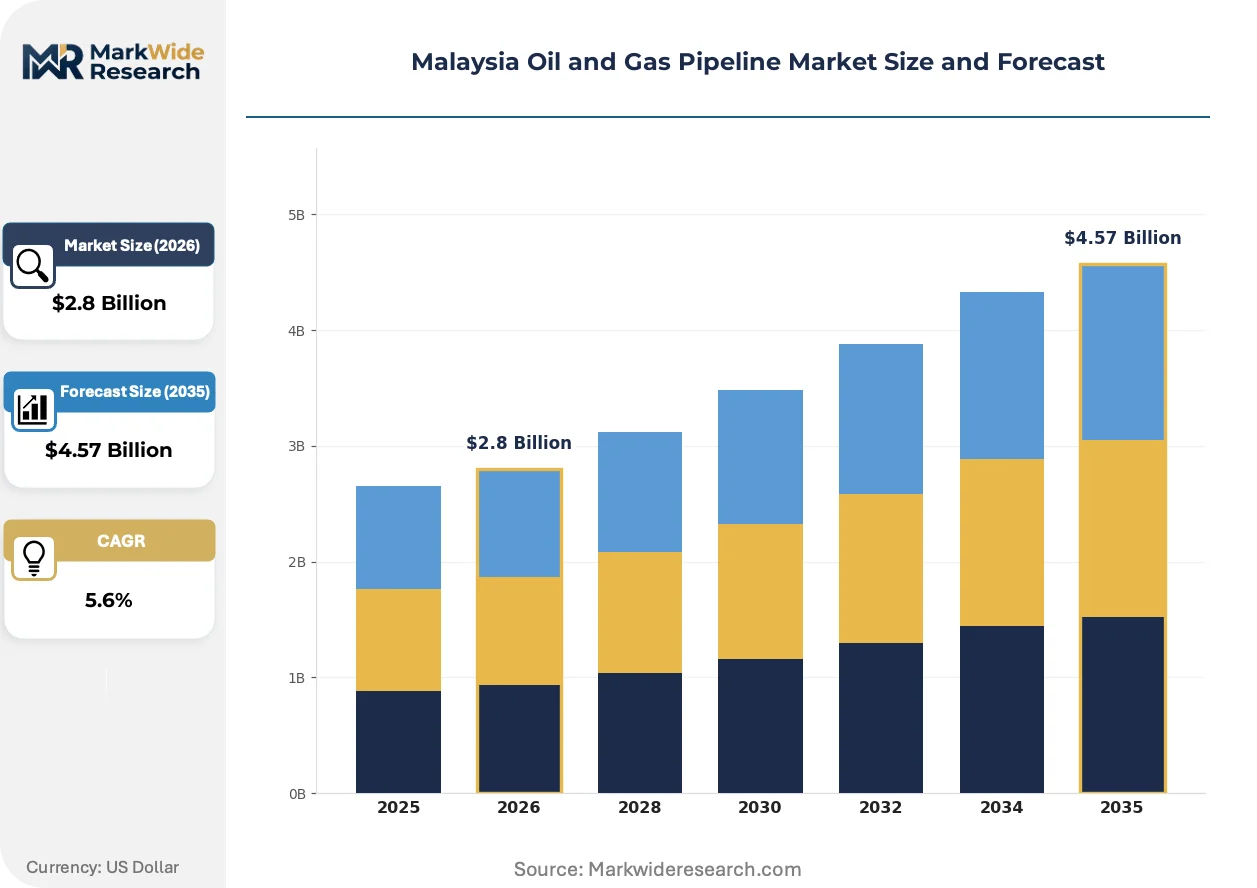
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Polyethylene, Composite, Fiberglass Installation Type: Onshore, Offshore, Subsea, Underground End User: Exploration Companies, Refining Entities, Energy Producers, Infrastructure Developers Service Type: Construction, Maintenance, Inspection, Repair |
| Companies Covered | Dialog Group Berhad, Bumi Armada, Petronas, Gas Malaysia Berhad, Muhibbah Engineering, PETRONAS Gas Berhad, MISC Berhad, Deleum Berhad, Sapura Energy Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Oil and Gas Pipeline Market Shifts & Advancements
Reeling lay methods and automated welding systems are compressing offshore construction windows while regulatory pressure on carbon intensity is reshaping material specifications across the value chain.
Reel-lay installation technology is migrating from shallow-water developments to deepwater Sabah blocks where vessel motion compensation systems enable continuous pipe deployment without flanged connections. PETRONAS and its tier-one contractors are specifying this method for 2026-2028 marginal field campaigns. The shift is eliminating traditional J-lay spreads and consolidating procurement around single-source reel-capable vessel operators.
Malaysia's Petroleum Regulations and Safety Act amendments are tightening integrity management protocols for pipelines crossing indigenous land reserves and ecologically sensitive coastal zones. The Department of Occupational Safety and Health now mandates real-time monitoring systems and accelerated corrosion survey frequencies. Operators are responding by embedding fiber-optic sensing cables during new construction rather than retrofitting legacy assets.
Integrated service contracts are displacing fragmented procurement where engineering, procurement, construction, and installation were tendered separately. PETRONAS is bundling these scopes into single-responsibility packages that transfer interface risk to contractors. This consolidation is most visible in Sarawak's offshore gas expansion where Dialog Group Berhad and Sapura Energy Berhad are competing on total-project delivery rather than discrete pipe supply.
Malaysia Oil and Gas Pipeline Market Segmentation
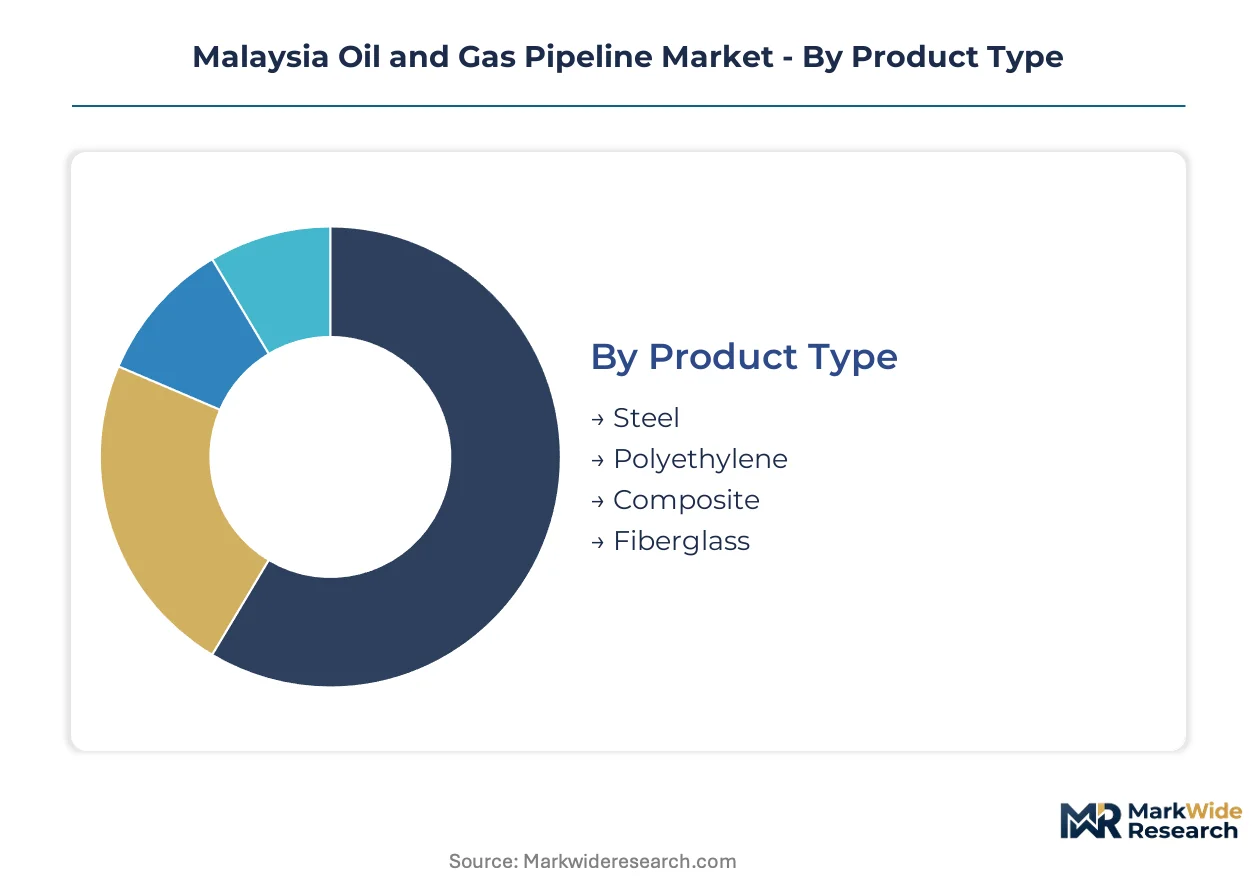
Pipeline segmentation in Malaysia reflects divergent cost structures and technical specifications across product materials, installation environments, and service modalities. Procurement patterns vary sharply between PETRONAS-operated assets and third-party infrastructure developers. Understanding these segment boundaries clarifies where margin compression and premium pricing opportunities concentrate.
Product Type:
Cost tier determines material selection, with carbon grades dominating baseline applications and corrosion-resistant alloys capturing high-pressure offshore developments.
- Steel:Carbon and alloy steel pipes constitute the procurement baseline for Malaysia's high-pressure offshore reservoirs, with API 5L X65 and X70 grades specified for Kertih-Klang Valley transmission corridors. Demand concentrates in PETRONAS-operated marginal field tiebacks where established welding protocols and inspection frameworks reduce project risk.
- Polyethylene:Flexible thermoplastic pipes serve low-pressure distribution networks and water injection lines in mature Peninsular fields. Adoption is climbing fastest in shallow-water cluster developments where corrosion immunity and reduced installation weight offset pressure limitations.
- Composite:Reinforced thermoplastic pipes address specific sour gas applications with reduced weight penalties versus steel equivalents.
- Fiberglass:Glass-reinforced epoxy pipes handle corrosive produced water and chemical injection duties in onshore processing facilities.
Steel holds installed capacity. Polyethylene is rotating up the share rankings.
Installation Type:
Application environment dictates contractor specialization, vessel requirements, and regulatory scrutiny intensity across Malaysia's diverse terrain.
- Offshore:Surface-laid pipelines connecting platforms to subsea tie-in points command premium margins due to limited regional pipe-lay vessel availability. Sarawak's deepwater expansion is absorbing MISC Berhad's specialized marine assets for reel-lay campaigns in CO2-rich reservoirs.
- Subsea:Seabed-embedded flowlines and export pipelines in Sabah's undeveloped gas discoveries require trenching and burial capabilities that few Southeast Asian contractors possess. Specification upgrades to duplex stainless grades are accelerating here.
- Onshore:Peninsular Malaysia's industrial corridor extensions face compressed construction windows and indigenous land reserve crossing complexities.
- Underground:Urban Klang Valley distribution networks demand horizontal directional drilling to minimize surface disruption in dense manufacturing zones.
Offshore commands revenue concentration. Subsea is climbing the fastest.
End User:
Customer type shapes contract structure, with integrated operators bundling scopes and independent developers fragmenting procurement across specialized vendors.
- Energy Producers:PETRONAS and production-sharing contractors drive volume concentration through integrated project delivery models. Third-party access mandates under Malaysia's Gas Distribution Act are expanding addressable infrastructure beyond traditional operator boundaries.
- Exploration Companies:Frontier acreage holders in deepwater Sabah blocks require pipeline infrastructure to monetize unconnected gas discoveries.
- Refining Entities:Downstream processors in Johor's manufacturing zones seek lateral pipeline connections to secure feedstock supply.
- Infrastructure Developers:Independent power producers and industrial off-takers are emerging as pipeline capacity purchasers under open-access transmission regulations.
Energy Producers anchor procurement volume. Infrastructure Developers are gaining share fastest.
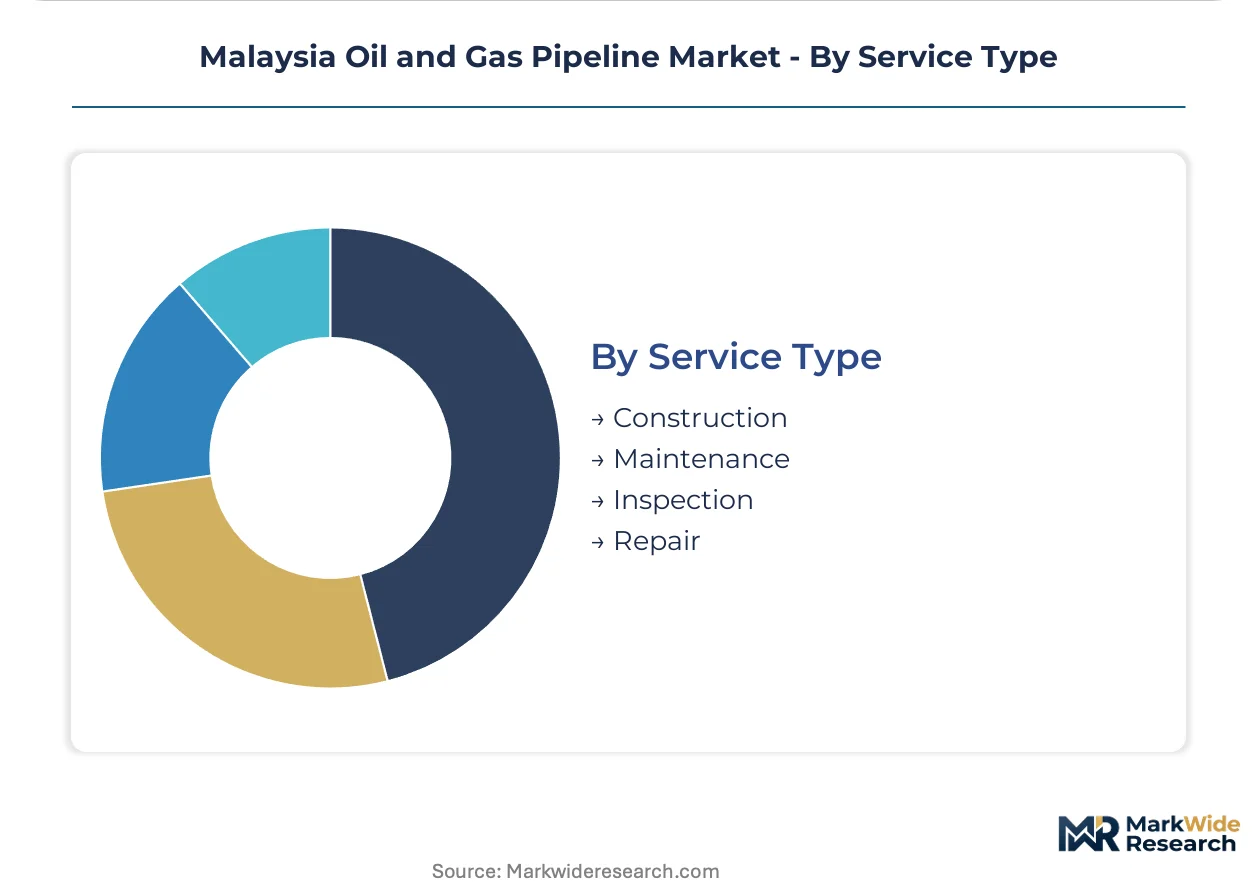
Service Type:
Maturity gradient separates construction opportunities in frontier basins from aftermarket services in Peninsular Malaysia's aging asset base.
- Construction:Greenfield pipeline fabrication and installation captures the largest contract values, particularly in Sarawak's offshore gas expansion where Dialog Group Berhad and Sapura Energy Berhad compete on EPCI bundling.
- Maintenance:Integrity management contracts for aging Peninsular assets are expanding as Malaysia's Petroleum Regulations tighten inspection frequencies for pipelines crossing ecologically sensitive zones.
- Inspection:Real-time fiber-optic monitoring and accelerated corrosion surveys are embedding into new construction specifications rather than retrofitting legacy systems.
- Repair:Hot-tap capabilities for live platform tie-ins represent a technical bottleneck with limited regional contractor availability.
Construction dominates awarded contract value. Maintenance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater pipe-lay vessel availability concentrates installation capacity with Singapore and Malaysian-flagged operators, compressing project timelines for frontier basin developments. This supply-side constraint shapes procurement patterns across Southeast Asian offshore corridors.
Sarawak
Offshore gas infrastructure expansion is accelerating specification upgrades to duplex stainless grades for CO2-rich reservoirs. Malaysia's Petroleum Regulations and Safety Act governs integrity standards for pipelines crossing ecologically sensitive coastal zones. The Bintulu LNG complex anchors downstream demand, with unconnected gas discoveries awaiting tie-in infrastructure.
Sabah
Deepwater block developments require reel-lay installation methods and trenching capabilities that few regional contractors possess. The Department of Occupational Safety and Health enforces ASME Section IX welder certification renewals that lag project staffing needs. Kota Kinabalu serves as the logistics hub for marine construction campaigns targeting undeveloped gas fields.
Peninsular Malaysia
The Kertih-Klang Valley industrial gas belt is driving lateral pipeline extensions into southern Johor manufacturing zones. Malaysia's Gas Distribution Act mandates third-party access to transmission networks, expanding addressable demand beyond PETRONAS-operated assets. Johor's refining and petrochemical clusters are emerging as anchor customers for open-access pipeline capacity.
Kertih
Marginal field tiebacks are forcing procurement cycles toward modular, pre-fabricated pipeline segments. The Safety and Health Authority mandates periodic integrity assessments for aging pipelines crossing indigenous land reserves. This Terengganu processing hub connects upstream production to Peninsular Malaysia's industrial consumption centers.
Klang Valley
Urban distribution networks demand horizontal directional drilling to minimize surface disruption in dense manufacturing zones. The Department of Environment mandates extended impact assessments for pipelines traversing turtle nesting zones. Shah Alam and Port Klang anchor the downstream terminus of Malaysia's primary gas transmission corridor.
Malaysia Oil and Gas Pipeline Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Malaysian pipeline sector exhibits tiered concentration, with PETRONAS-linked entities controlling offshore installation capacity and independent engineering firms capturing maintenance and inspection scopes. Three archetypes dominate: integrated EPCI contractors bundling engineering through installation; specialized marine operators with captive vessel fleets; and downstream service providers targeting integrity management. Competitive dynamics center on EPCI scope consolidation and reel-lay vessel utilization rates.
Within the integrated contractor tier, Dialog Group Berhad and Sapura Energy Berhad exemplify full-project-delivery positioning. MISC Berhad anchors the marine installation segment with specialized pipe-lay vessel capability. These three entities collectively represent the competitive core for Sarawak offshore expansion and Peninsular corridor extensions.
| Leading Market Players |
|---|
| Dialog Group Berhad |
| Bumi Armada |
| Petronas |
| Gas Malaysia Berhad |
| Muhibbah Engineering |
| PETRONAS Gas Berhad |
| MISC Berhad |
| Deleum Berhad |
| Sapura Energy Berhad |
| Others |
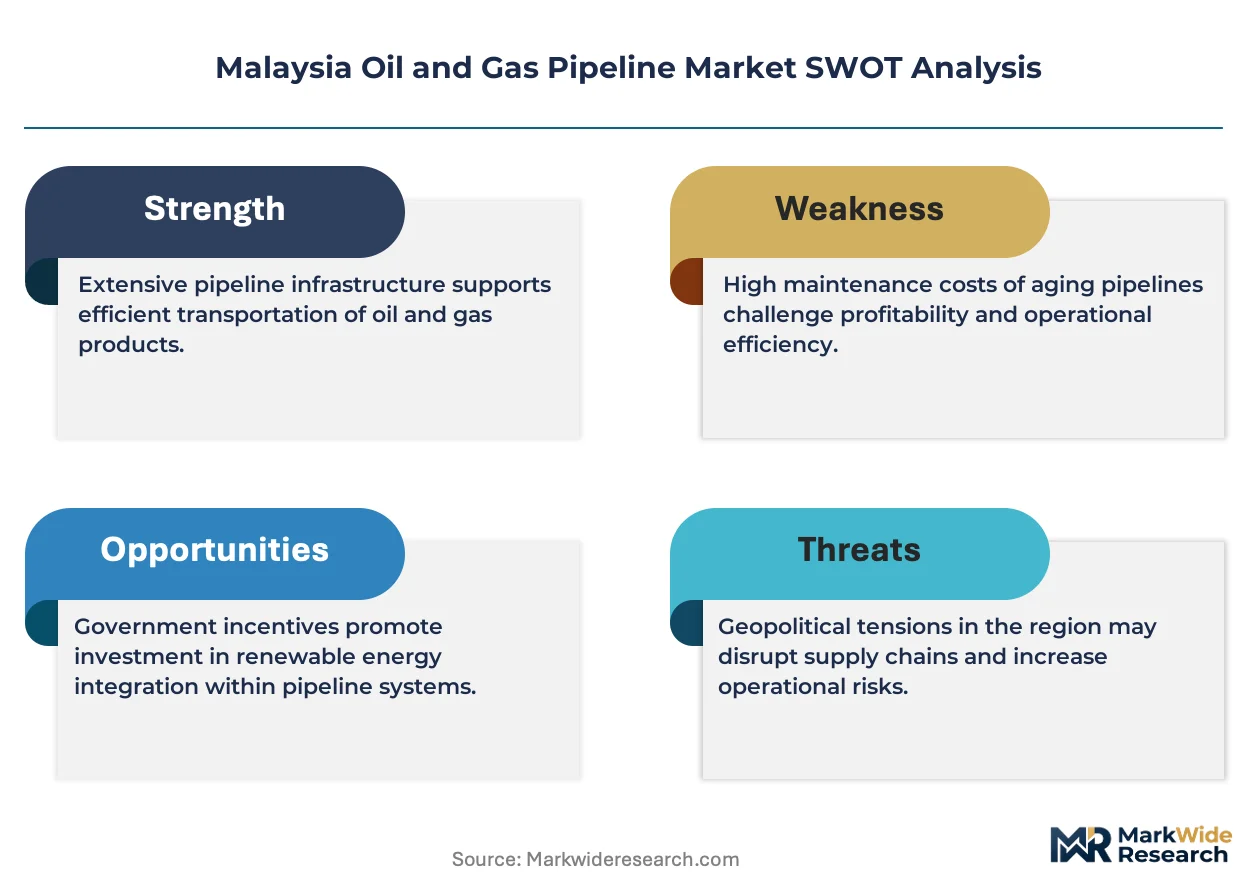
Supply & Pricing Matrix
Single-source dependency on Korean and Japanese API 5L X70+ steel mills compresses pricing power for Malaysian EPCI contractors while simultaneously forcing supply chain reconfiguration toward extended inventory positions and alternative specification sourcing. This import concentration creates a dual-tier cost structure where projects with locked-in mill contracts operate at structural advantage against spot-market exposed competitors.
Pricing Analysis
Malaysia's Petroleum Regulations and Safety Act dictates the pricing tier structure by mandating corrosion-resistant alloy specifications for CO2-rich Sarawak reservoirs that command premium procurement brackets against standard carbon steel baselines. Three-tier pricing structure across premium duplex grades, standard API X65-X70, and economy polyethylene alternatives separates deepwater developers from Peninsular corridor extensions and shallow-water cluster operators. Cost compression in the standard steel tier is intensifying because domestic mills lack high-grade production capability, exposing project budgets to East Asian mill pricing volatility. Independent power producers accessing transmission networks under the Gas Distribution Act exhibit highest price sensitivity, while PETRONAS-operated marginal field developers prioritize technical specification compliance over unit cost minimization.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard for Korean and Japanese mill contracts, stretching contractor working capital and favoring balance-sheet-strong operators like Dialog Group Berhad and MISC Berhad. Geographic supply concentration rests on South Korea, Japan, and Singapore, with the latter anchoring specialized reel-lay vessel availability for deepwater Sabah campaigns. Raw material dependencies center on nickel-alloy feedstocks for duplex grades, high-purity steel slabs, and marine-grade anti-corrosion coatings. Single-source vulnerability concentrates in the regional pipe-lay vessel fleet where MISC Berhad and limited Singapore-flagged operators control deployment schedules. Distribution runs through Port Klang and Bintulu LNG terminal logistics hubs with final mile coordination via Kota Kinabalu for Sabah deepwater blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ASME Section IX-certified welders and hot-tap capable contractors creates a capability bottleneck that determines competitive positioning across Sarawak expansion and Peninsular maintenance cycles. This skill gap favors incumbents with established training pipelines and captive certification programs.
For Market Incumbents: Harden welder certification pipelines through captive training academies to preempt staffing shortfalls that delay PETRONAS marginal field timelines. Secure multi-year mill contracts with Korean suppliers before spot price volatility intensifies. Locking in API 5L X70+ supply commitments now defends margin position against emerging EPCI competitors lacking balance-sheet depth for extended payment terms.
For New Entrants and Emerging Players: Sabah's undeveloped deepwater gas discoveries offer the most penetrable geography for specialized subsea construction capabilities that incumbent integrated contractors have deprioritized. Target inspection and fiber-optic monitoring services for aging Peninsular pipelines where regulatory tightening under the Petroleum Regulations accelerates contract frequency. Partner with regional engineering consultancies to bypass vessel ownership barriers and capture maintenance scopes through technical specialization rather than capital-heavy installation assets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reel-lay vessel operators and integrated EPCI bundlers over fragmented pipe suppliers. Long-term viability across the analysis window hinges on exposure to carbon capture readiness retrofit cycles and decommissioning liability transfer opportunities in mature Peninsular fields. Acquisition targets should demonstrate hot-tap platform integration capabilities or established Dialog Group Berhad-style maintenance contract books. Monitor PETRONAS procurement tender bundling patterns as the inflection signal—accelerated EPCI consolidation indicates margin compression ahead for discrete service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Reel-Lay Vessel Capacity Expansion | MISC Berhad's specialized marine assets capture premium margins in CO2-rich Sarawak deepwater blocks. |
| Backward Integration into Steel Sourcing | Long-term Korean mill partnerships reduce exposure to API 5L X70+ import price volatility. |
| Carbon Capture Readiness Certification | Anticipated Petroleum Regulations amendments will mandate CO2-compatible materials for new approvals. |
| Integrity Management Service Bundling | Real-time fiber-optic monitoring contracts expand recurring revenue from Peninsular aging asset base. |
| Third-Party Access Infrastructure Development | Gas Distribution Act mandates create addressable demand beyond traditional PETRONAS-operated corridors. |
Research Methodology
Operator-level perspectives from PETRONAS project managers, EPCI contractor procurement leads, marine vessel operations directors, and Department of Occupational Safety and Health regulators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through Malaysia Energy Commission filings, PETRONAS annual activity reports, customs import data for steel grades, and regional shipbroker vessel availability databases. Bottom-up project pipeline tracking and top-down sector expenditure analysis were triangulated to establish market sizing boundaries.
Scenario-bracketing around regulatory amendment timing and deepwater development commitment cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product material grade, installation environment complexity, end-user contract structure, and service modality maturity. CAGRs were derived from expenditure flow projections tied to announced marginal field campaigns and Bintulu LNG expansion timelines. Forecast inputs incorporated pipe-lay vessel utilization rates and welder certification renewal lag data from the Department of Occupational Safety and Health.
Practitioners should monitor regulatory amendment timing for carbon capture readiness standards and PETRONAS capital commitment announcements for early signals of trajectory revision. Forecasts reflect assumptions around third-party access mandate enforcement continuity and regional marine asset availability. Macroeconomic commodity price deviation, unexpected regulatory restriction tightening, or technological substitution in subsea tie-in methods would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Upstream Services Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Seismic Survey Equipment Market