
 Oman Oil and Gas Upstream Market | 2026-2036
Oman Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Oil and Gas Upstream Market Analytics
Omani production capacity is expanding across mature carbonate fields and frontier tight gas blocks. Petroleum Development Oman leverages decades of enhanced oil recovery expertise to sustain output from the Sultanate's largest concession areas. BP Plc anchors its regional position through deepwater exploration commitments in Block 61 and adjacent offshore licenses. Royal Dutch Shell competes via integrated gas-to-liquids operations that extend its value chain beyond conventional crude extraction.
Oman oil and gas upstream encompasses the exploration, drilling, and production of hydrocarbons from subsurface reservoirs, primarily from fractured carbonate formations with permeability ranging below 10 millidarcies in many mature fields, serving power generation feedstock and export-oriented liquefied natural gas supply. Exploration services command premium contracting terms as operators target deeper Pre-Cambrian tight gas horizons in the Khazzan-Makarem cluster. Horizontal drilling technology leads capital allocation decisions, displacing conventional vertical well architectures in fields where lateral reach unlocks compartmented reserves.
The Ministry of Energy and Minerals shapes licensing rounds and production-sharing contract terms, while the Environmental Authority enforces flaring reduction mandates and marine protection standards for offshore developments. The central bank's foreign investment rules govern capital repatriation for international joint ventures, constraining project finance structures. Stakeholders must monitor Block 6 renewal negotiations and tight gas fiscal terms to calibrate reserve booking assumptions and long-term field development schedules.
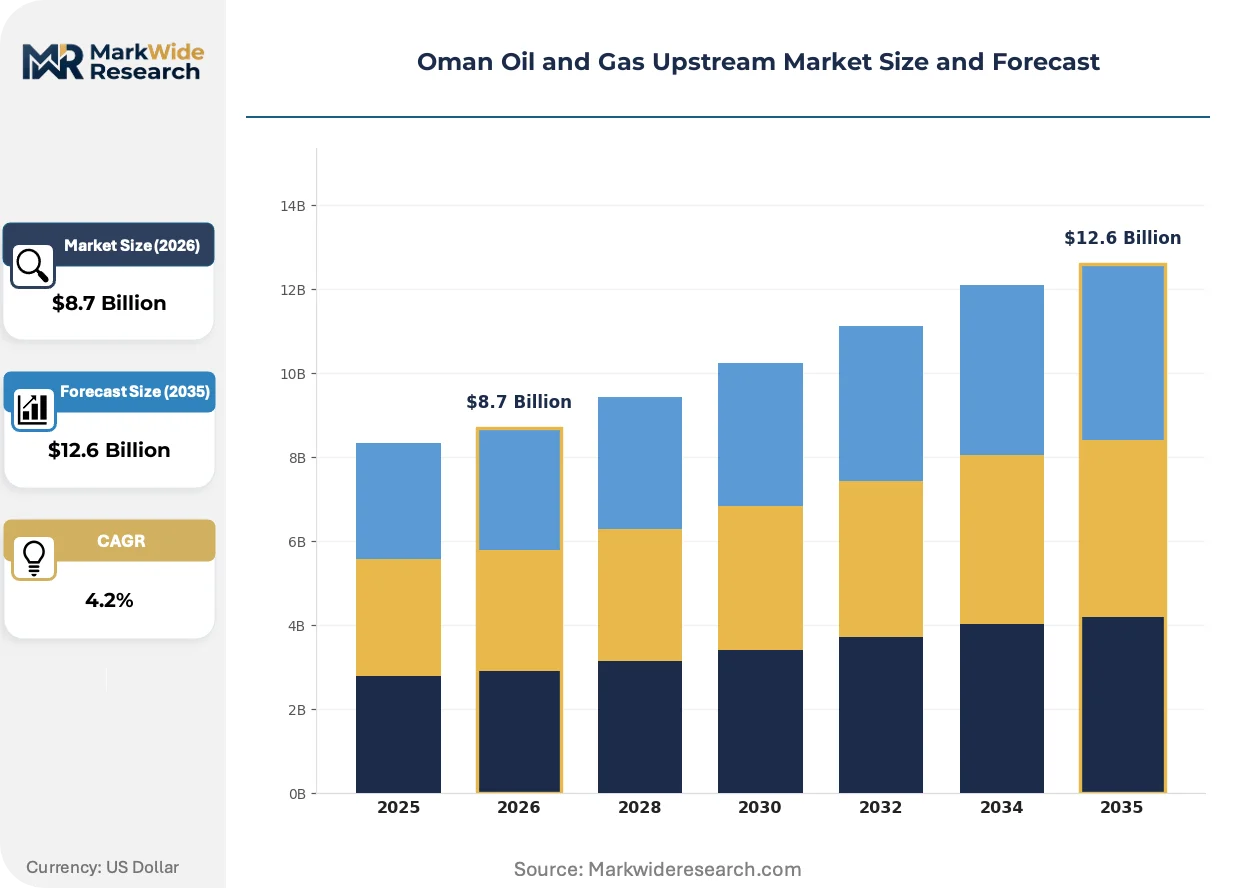
Market Dynamics
Horizontal drilling and multi-stage hydraulic fracturing are absorbing capital allocations across Oman's tight gas basins, compressing development timelines for Pre-Cambrian reservoirs while the Ministry of Energy and Minerals tightens flaring enforcement.
Growth Catalysts
- Enhanced Recovery Mandates:The Ministry of Energy and Minerals incentivizes polymer flooding and miscible gas injection across Block 6 carbonate fields, extending plateau production from mature reservoirs with permeability below 10 millidarcies.
- Khazzan-Makarem Tight Gas Cluster:Operators target deeper Pre-Cambrian horizons through extended-reach laterals, unlocking compartmented reserves previously classified as non-commercial under vertical well economics.
- Liquefied Natural Gas Feedstock Demand:Oman LNG expansion commitments require sustained dry gas supply from interior basins, pulling investment toward tight gas processing infrastructure and dehydration facilities.
Market Restraints
- Carbonate Reservoir Complexity:Fractured basement formations exhibit unpredictable permeability distribution, elevating dry hole risk and requiring dense 3D seismic grids before drilling commitment.
- Specialized Rig Scarcity:High-specification rigs capable of 6,000-meter vertical depths with managed pressure drilling concentrate in the US Permian and UAE, constraining Oman drilling schedules during peak demand windows.
- Water Injection Infrastructure:Sustained pressure maintenance demands extensive surface facility buildout in remote interior basins where pipeline corridors cross protected wadi systems regulated by the Environmental Authority.
Strategic Opportunities
- Block 61 Deepwater Frontier:Untested salt structures in offshore concessions offer multi-Tcf gas potential, with seismic acquisition now penetrating below 4,000 meters water depth.
- Electrification of Offshore Platforms:Grid-connected renewable supply from mainland solar farms displaces diesel generators, aligning with the Sultanate's net-zero operational targets and reducing OPEX volatility.
- Carbon Capture Integration:Associated CO2 from gas processing feeds enhanced oil recovery operations in mature fields, creating circular emissions utilization under emerging carbon accounting frameworks.
Industry Challenges
- Reservoir Characterization Talent Gap:Geoscientists with fractured carbonate expertise concentrate at Petroleum Development Oman, constraining independent operator technical teams during appraisal phases.
- Legacy SCADA Integration:Brownfield automation upgrades in Block 6 require protocol translation between 1990s-era distributed control systems and modern IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Oil and Gas Upstream Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Well Services Technology: Offshore Platforms, Onshore Facilities, Enhanced Oil Recovery, Horizontal Drilling Application: Natural Gas, Oil Extraction, Field Development, Well Completion End User: Energy Companies, Government Agencies, Contractors, Independent Operators |
| Companies Covered | Total SA, Occidental Petroleum Corporation, Petroleum Development Oman, Petrogas E&P LLC, Oman Oil Company SAOC, BP Plc, Eni SpA, Daleel Petroleum LLC, Royal Dutch Shell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Oil and Gas Upstream Market Evolving Landscape
Digital twin deployment is compressing field development cycles across Oman's concession areas, with real-time reservoir simulation now guiding infill drilling decisions. Three forces are reshaping upstream operations.
Managed pressure drilling systems are absorbing market share in tight gas applications, enabling precise bottom-hole pressure control through closed-loop circulation. Operators deploy this technology in Khazzan-Makarem formations where narrow drilling windows previously caused lost circulation events. The structural consequence is expanding lateral reach beyond 3,000 meters while reducing non-productive time.
The Environmental Authority's flaring reduction mandates now require 90% utilization of associated gas within three years of first production, compressing facility construction schedules. Operators must install gas compression and export pipelines concurrent with oil production startup rather than deferring gas infrastructure. Offshore Block 61 developments face the strictest timelines due to marine ecosystem proximity.
Integrated service contracts are displacing discrete vendor relationships across drilling and completions. National oil companies now bundle directional drilling, logging-while-drilling, and hydraulic fracturing under single-point accountability. This concentration is most visible in tight gas blocks where operator technical staff shortages drive preference for full-service integrated project delivery.
Oman Oil and Gas Upstream Market Segmentation
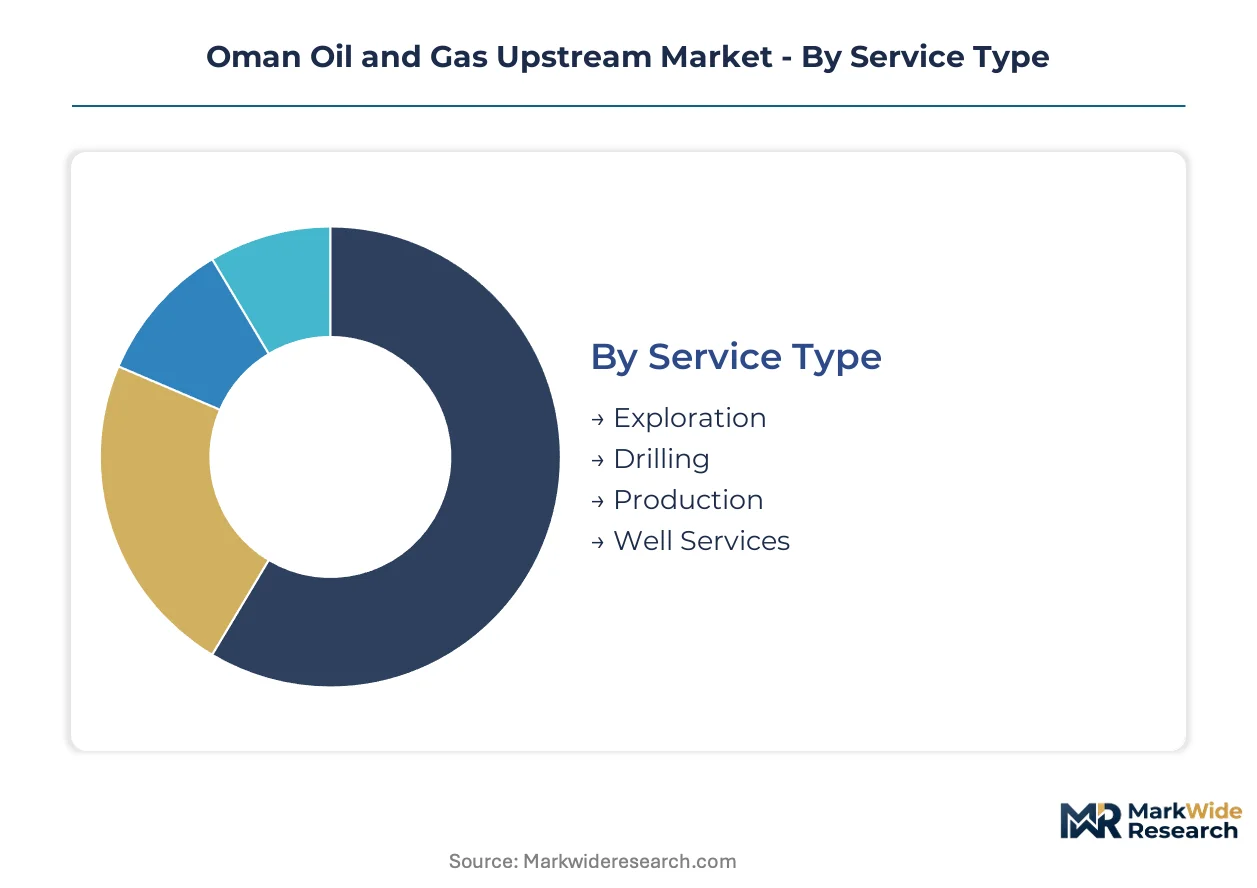
Upstream service procurement in Oman splits across reservoir maturity cycles and technical complexity tiers. Operators calibrate contracting strategies between carbonate field rehabilitation and frontier tight gas development, with each segment demanding distinct capability bundles from service providers.
Service Type:
Replacement cycles for aging production infrastructure in Block 6 fields are accelerating service demand across all four categories, with drilling and well services absorbing disproportionate capital allocation.
- Exploration:3D seismic acquisition and Pre-Cambrian tight gas prospecting dominate contracting volumes. The Ministry of Energy and Minerals' licensing rounds for interior basins pull investment toward frontier appraisal programs where dry hole risk remains elevated.
- Drilling:Extended-reach horizontal wells in Khazzan-Makarem formations require managed pressure drilling systems and 6,000-meter depth capability. High-specification rig scarcity constrains scheduling during peak demand windows.
- Production:Surface facility operations span artificial lift deployment and gas compression for Oman LNG feedstock supply. Brownfield automation upgrades integrate legacy SCADA with modern IoT sensor networks.
- Well Services:Hydraulic fracturing and completion interventions target compartmented tight gas reserves. Integrated service contracts bundle directional drilling, logging-while-drilling, and stimulation under single-point accountability.
Volume placements concentrate in Drilling; the faster expansion belongs to Well Services.
Technology:
Cost tier differentiation separates mature field rehabilitation from frontier development, with premium technology stacks commanding longer payback periods in deep gas horizons.
- Offshore Platforms:Grid-connected electrification from mainland solar farms displaces diesel generators across Block 61 developments. The Environmental Authority's marine protection standards compress facility construction schedules.
- Onshore Facilities:Dehydration and gas processing infrastructure in interior basins requires extensive pipeline corridors crossing protected wadi systems. Remote location logistics elevate installed costs above offshore equivalents.
- Enhanced Oil Recovery:Polymer flooding and miscible gas injection extend plateau production from mature carbonate reservoirs with permeability below 10 millidarcies. Petroleum Development Oman leverages decades of field-specific expertise.
- Horizontal Drilling:Multi-stage hydraulic fracturing unlocks compartmented Pre-Cambrian reserves previously classified as non-commercial. Lateral reach now exceeds 3,000 meters while non-productive time falls.
Revenue concentration sits with Enhanced Oil Recovery; Horizontal Drilling is climbing the fastest.
Application:
Customer type segmentation reveals divergent procurement patterns between state-backed operators and independent ventures.
- Natural Gas:Dry gas supply commitments for Oman LNG expansion pull investment toward tight gas processing infrastructure. The Ministry of Energy and Minerals mandates 90% associated gas utilization within three years of first production.
- Oil Extraction:Mature carbonate fields in Block 6 sustain output through infill drilling and pressure maintenance. Water injection infrastructure demands extensive surface facility buildout in remote interior basins.
- Field Development:Integrated project delivery models consolidate exploration through production phases under unified contracting structures. National oil companies favor bundled accountability over discrete vendor relationships.
- Well Completion:Multi-zone isolation and intelligent completion systems optimize production from fractured basement formations. Unpredictable permeability distribution elevates completion design complexity.
Contracting volume favors Oil Extraction; Field Development shows the steepest expansion trajectory.
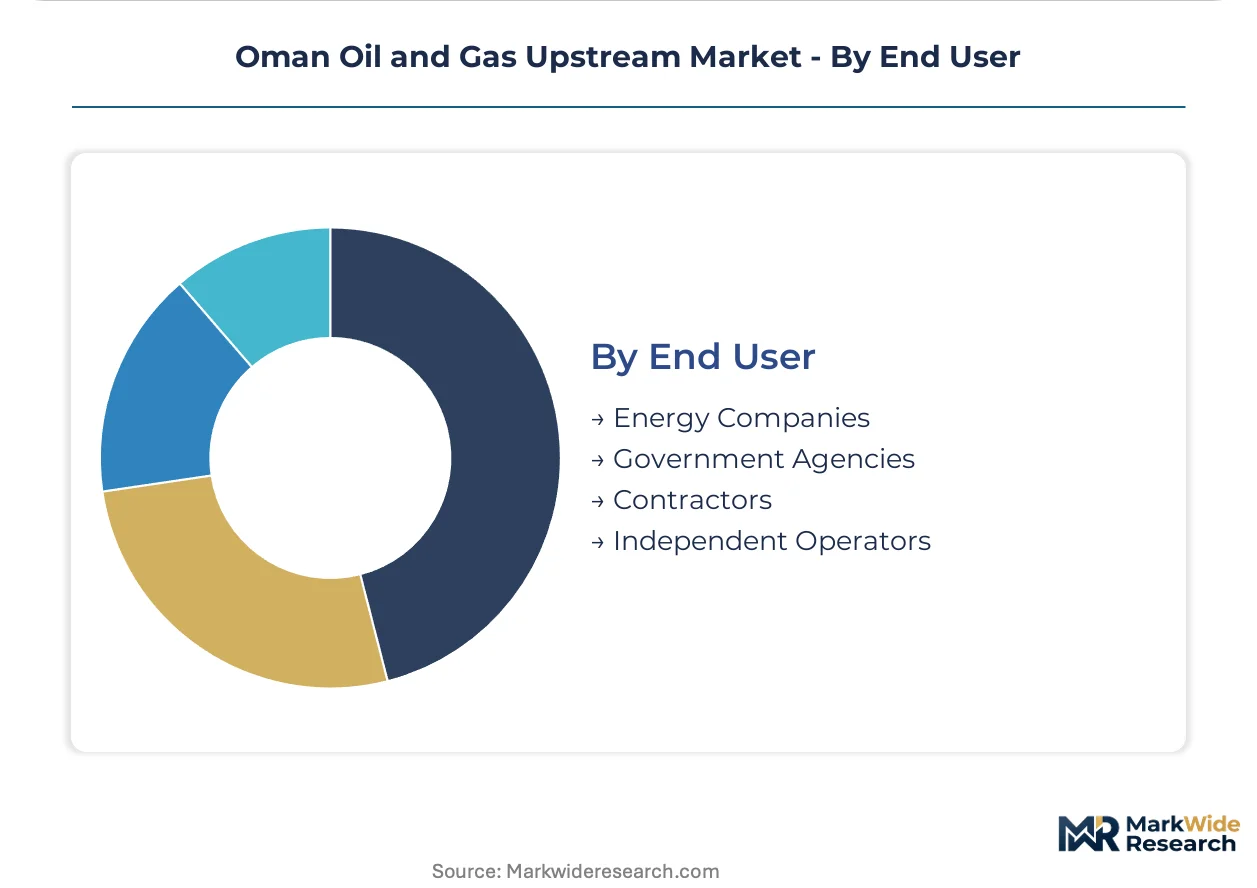
End User:
Supply concentration among state-affiliated entities shapes procurement access for international service providers.
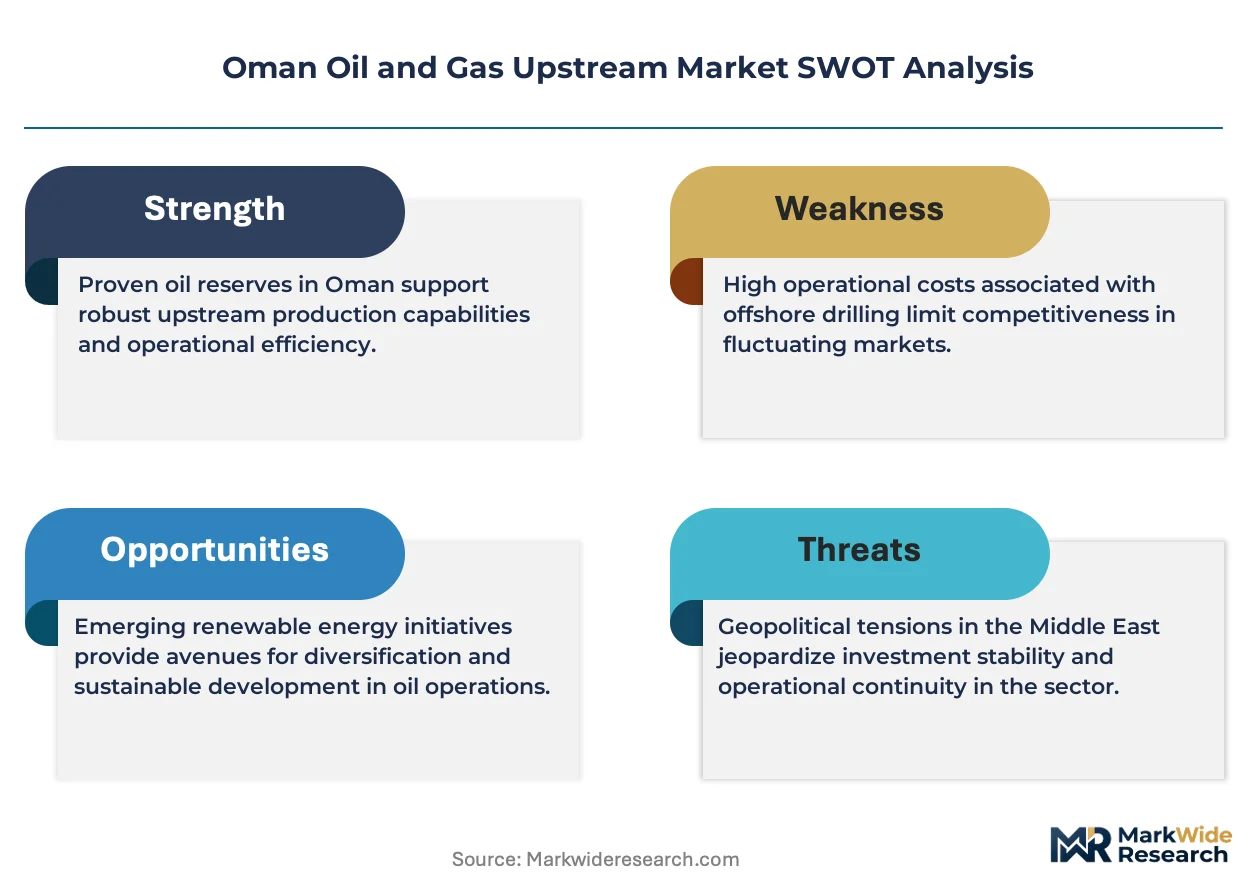
- Energy Companies:Petroleum Development Oman and BP Plc anchor upstream investment through production-sharing contracts and deepwater exploration commitments. Reserve booking assumptions depend on Block 6 renewal negotiations and tight gas fiscal terms.
- Government Agencies:The Ministry of Energy and Minerals shapes licensing rounds and contract terms while the Environmental Authority enforces flaring reduction mandates. Central bank foreign investment rules constrain project finance structures for international joint ventures.
- Contractors:Integrated service providers bundle drilling, completions, and production maintenance under long-term agreements. Technical staff shortages at independent operators drive preference for full-service project delivery.
- Independent Operators:Smaller concession holders in frontier blocks face reservoir characterization talent gaps as geoscientists with fractured carbonate expertise concentrate at established national oil companies.
Procurement volume concentrates with Energy Companies; Independent Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sultanate's interior basins and offshore concessions anchor upstream investment across fractured carbonate formations and tight gas horizons. Petroleum Development Oman dominates Block 6 operations while frontier exploration targets Pre-Cambrian reservoirs in the Khazzan-Makarem cluster.
Al Dhahirah Governorate
Tight gas development in the interior basins pulls capital toward extended-reach horizontal drilling programs. The Ministry of Energy and Minerals' licensing framework for Pre-Cambrian horizons mandates 90% gas utilization within three years of first production. Operators in the Ibri-Nizwa corridor deploy managed pressure drilling systems to navigate narrow drilling windows in compartmented reservoirs.
South Al Batinah Governorate
Gas processing infrastructure expansion supports Oman LNG feedstock commitments from interior basin supply. The Environmental Authority enforces flaring reduction mandates that compress facility construction schedules. Pipeline corridors crossing protected wadi systems in the Rustaq-Suwaiq belt require extensive regulatory coordination for water injection infrastructure buildout.
Dhofar Governorate
Frontier exploration targets in the southern interior attract seismic acquisition investment for untested tight gas structures. The Ministry of Energy and Minerals shapes production-sharing contract terms for independent operators entering marginal acreage. Salalah's industrial port infrastructure enables equipment logistics for remote drilling campaigns in the Qara Mountains foothills.
Muscat Governorate
Offshore Block 61 deepwater commitments anchor BP Plc's regional exploration portfolio beneath 4,000-meter water depths. The Environmental Authority's marine protection standards enforce strict construction timelines for platform electrification projects. Grid-connected renewable supply from mainland solar farms displaces diesel generation across offshore installations.
Al Wusta Governorate
Carbonate field rehabilitation in mature Block 6 extensions sustains output through polymer flooding and miscible gas injection. Petroleum Development Oman leverages decades of enhanced oil recovery expertise in reservoirs with permeability below 10 millidarcies. The Duqm Special Economic Zone hosts service provider consolidation for integrated drilling and completions contracts.
Oman Oil and Gas Upstream Market Competitive Landscape
Global majors compete with regional champions across concession access and tight gas technology deployment. State-affiliated entities dominate reserve holdings through production-sharing contracts, while international operators anchor frontier exploration in deepwater blocks. Three archetypes define competitive positioning: integrated national oil companies with decades of field-specific expertise, global supermajors with deepwater and LNG integration capabilities, and specialized tight gas developers with horizontal drilling specialization. Dominant competitive moves include integrated service contract bundling and strategic partnerships for infrastructure sharing in remote interior basins.
Among state-affiliated operators, Petroleum Development Oman exemplifies the integrated national oil company archetype through its Block 6 dominance and enhanced oil recovery specialization. BP Plc occupies a position representing global supermajor engagement in frontier deepwater exploration. Royal Dutch Shell sits within the gas value chain integration tier through its historical involvement in Oman's liquefied natural gas infrastructure. These three anchors illustrate the spectrum from state-captive operators to internationally integrated majors competing for concession renewals and tight gas licensing rounds.
| Leading Market Players |
|---|
| Total SA |
| Occidental Petroleum Corporation |
| Petroleum Development Oman |
| Petrogas E&P LLC |
| Oman Oil Company SAOC |
| BP Plc |
| Eni SpA |
| Daleel Petroleum LLC |
| Royal Dutch Shell |
| Others |
Value Network & Pricing Analysis
High-specification rig day rates cascade through Omani upstream contracting tiers, with managed pressure drilling premiums separating integrated service bundles from discrete vendor arrangements. The Environmental Authority's flaring enforcement compresses facility construction timelines, forcing concurrent gas infrastructure investment that reshapes project economics across Block 6 rehabilitation and Khazzan-Makarem tight gas development.
Pricing Analysis
Service bundling separates integrated drilling contracts with embedded completion guarantees from unbundled day-rate arrangements. Pricing stratifies across premium, standard, and economy tiers based on rig specification tier and reservoir complexity grade. Cost compression in standard-tier drilling packages is intensifying because high-specification rig scarcity concentrates bargaining power with UAE-based equipment lessors. Independent operators exhibit highest price sensitivity due to constrained project finance access under central bank foreign investment rules.
Supply Chain Analysis
Direct-to-operator channels handle national oil company procurement volumes, while contractor-tier distribution feeds independent operators through integrated service providers. Equipment manufacturing concentrates in the United States, the United Arab Emirates, and Singapore. Raw material dependencies include high-strength steel alloys, advanced electronics for managed pressure systems, and specialized proppant grades. Single-source vulnerability runs through managed pressure drilling system suppliers concentrated in the US Permian basin. Distribution runs through Dubai-Jebel Ali logistics hubs before overland transport to interior basin drilling sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oman upstream market functions as a vertical-integration race where control over high-specification rig capacity and tight gas completion technology determines concession access. Players are pursuing backward integration into specialized drilling equipment supply to secure scheduling priority during peak demand windows.
For Market Incumbents: Acquire high-specification rig fleets and managed pressure drilling system inventories to secure capacity priority during licensing round peaks. Block 6 renewal negotiations and tight gas fiscal term adjustments from the Ministry of Energy and Minerals threaten reserve booking assumptions for operators lacking integrated service capabilities. Vertical integration into completion chemical supply buffers margin pressure from imported proppant cost volatility. For New Entrants and Emerging Players: Enter via frontier acreage in Dhofar Governorate where seismic acquisition investment lags Block 61 development intensity. The southern interior tight gas structures offer lowest competitive density among appraised basins. Partner with established integrated service providers to overcome reservoir characterization talent gaps that constrain independent technical teams. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized tight gas developers with horizontal drilling intellectual property in Al Dhahirah Governorate. Long-term viability hinges on sustained Oman LNG feedstock demand and Ministry of Energy and Minerals licensing continuity. Watch Block 6 production-sharing contract renewal terms as inflection indicator for fiscal regime stability.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Consolidation | Petroleum Development Oman and BP Plc now bundle drilling, completions, and maintenance under single-point accountability. |
| High-Specification Rig Capacity Expansion | Managed pressure drilling system deployment in Khazzan-Makarem formations requires 6,000-meter depth capability. |
| Grid-Connected Platform Electrification | Block 61 offshore developments displace diesel generation through mainland solar farm interconnection. |
| Carbon Capture Integration | Associated CO2 from gas processing feeds enhanced oil recovery operations in mature Block 6 carbonate fields. |
| Frontier Seismic Acquisition | Untested salt structures beneath 4,000-meter water depths in Block 61 offer multi-Tcf gas potential. |
Research Methodology
Independent corroboration across petroleum development executives, drilling contractors, and Environmental Authority officials underwrites the qualitative findings in this study. Primary interviews with reservoir engineers at Petroleum Development Oman, procurement leads at international joint ventures, and technical directors at integrated service providers combined with secondary validation from Ministry of Energy and Minerals licensing round disclosures, central bank foreign investment circulars, and Oman LNG supply commitment announcements. Bottom-up field development schedule analysis and top-down concession valuation triangulation anchored volume and value estimates.
Comparable-period anchoring linked the projection horizon to historical production trends from Block 6 carbonate fields and Khazzan-Makarem tight gas commissioning timelines. The analytical framework modeled segmentation across service type, technology tier, application category, and end-user archetype throughout the forecast period. CAGRs were derived from field decline curve analysis and greenfield development pace assumptions. Industry-specific forecast inputs included managed pressure drilling adoption rates and associated gas utilization mandate compliance timelines.
Revisions become necessary when Ministry of Energy and Minerals fiscal term adjustments, Environmental Authority regulatory tightening, or high-specification rig availability shocks materialize. Forecasts reflect assumptions regarding sustained Oman LNG feedstock demand and tight gas reservoir productivity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Middle-East and Africa Pigging Services Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market