
 Latin America AI in Oil and Gas Market | 2026-2036
Latin America AI in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America AI in Oil and Gas Market Analytics
Edge-to-cloud integration is reconfiguring how AI workloads distribute across remote oilfield infrastructure in Latin America. SLB leverages its digital platform architecture to anchor deepwater deployment capabilities across Brazilian pre-salt fields. Ecopetrol specializes in onshore AI applications for its Llanos Basin operations, differentiating through localized algorithm training. Baker Hughes competes with integrated hardware-software bundles that extend predictive maintenance coverage from wellhead to processing facility.
Latin America AI in Oil and Gas encompasses machine learning, natural language processing, predictive analytics, and computer vision systems engineered to process seismic datasets exceeding 10 terabytes per survey, automate drilling parameter optimization, and detect equipment anomalies through vibration and thermal signature analysis. The technology serves primarily to reduce non-productive time, extend asset life, and improve recovery factors in mature and deepwater fields. Machine Learning commands the largest technology share due to its proven efficacy in reservoir characterization and production forecasting, while Computer Vision represents the fastest-expanding segment as operators deploy drone-mounted inspection systems across offshore platforms. Exploration applications currently absorb the greatest investment share among application categories, though Production Optimization is narrowing this gap as brownfield operators pursue incremental barrel economics.
Brazil's ANP mandates digital twin documentation for certain offshore developments, while Colombia's ANH encourages data-sharing frameworks that shape vendor platform architectures. Mexico's CNH oversight of contract terms influences how international service companies structure AI licensing agreements with Pemex and private operators. Stakeholders must weigh regulatory data-localization requirements against cloud-deployment economics when designing infrastructure for cross-border field operations.
Market Dynamics
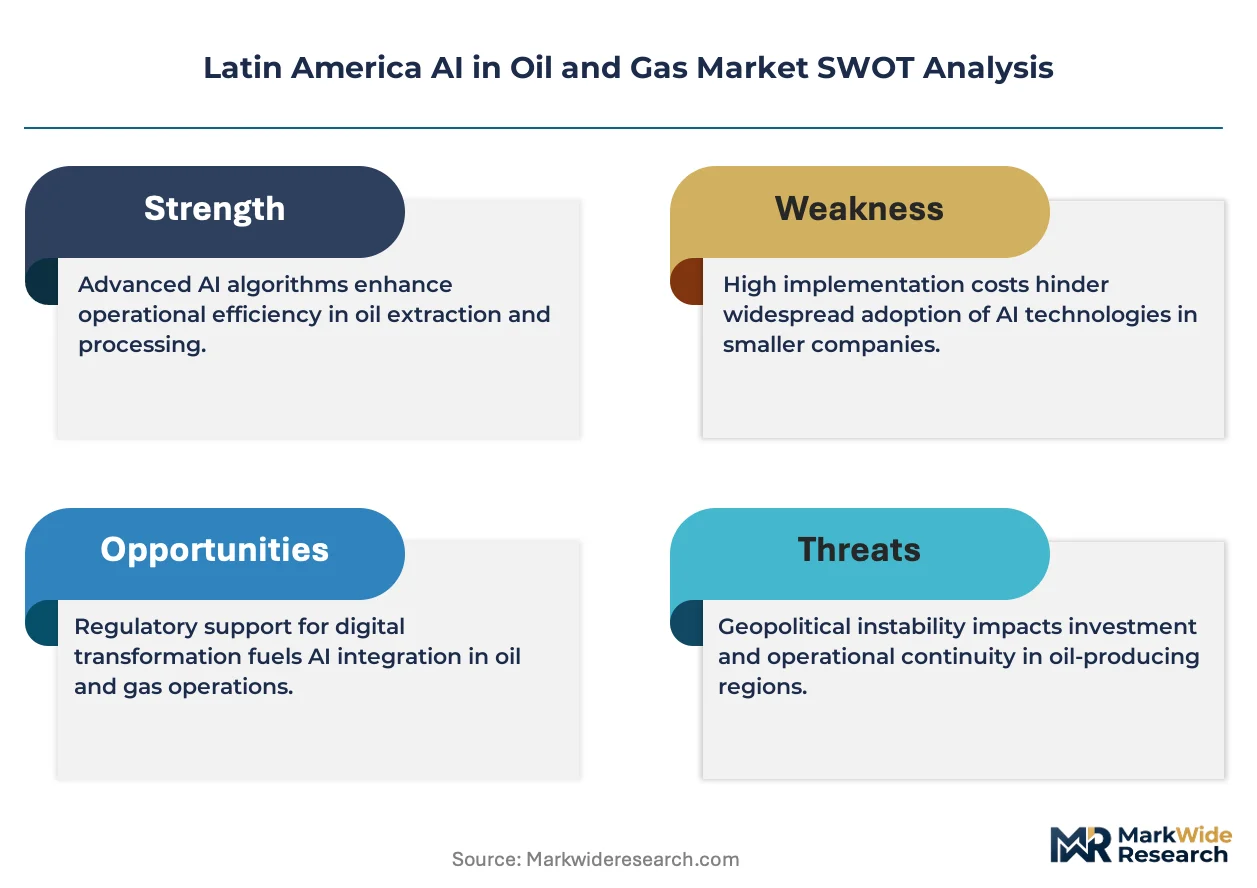
Edge computing architectures are redistributing AI inference workloads from centralized cloud infrastructure to remote wellsite processors, compressing latency for real-time drilling decisions in Brazil's pre-salt basin and Colombia's Llanos fields.
Growth Catalysts
- ANP Digital Twin Mandates:Brazil's national petroleum regulator requires virtual asset documentation for specific offshore developments, forcing operators to deploy machine learning models for predictive reservoir simulation.
- Pre-salt Production Optimization:Deepwater operators in Brazil's Santos Basin apply neural networks to manage gas-lift systems and artificial lift configurations, extracting incremental barrels from high-pressure carbonate reservoirs.
- Seismic Data Proliferation:Advanced 3D and 4D seismic surveys now generate datasets exceeding 10 terabytes per acquisition, creating computational demand that only GPU-accelerated AI architectures can process within operational timeframes.
Market Restraints
- Data Localization Requirements:Brazilian federal mandates restrict cross-border transfer of subsurface geological data, fragmenting cloud deployment architectures and raising infrastructure costs for international service providers.
- Specialized Talent Scarcity:The intersection of petroleum engineering and machine learning expertise remains concentrated in North American and European labor markets, constraining local implementation velocity.
- Legacy SCADA Integration:Decades-old control systems in mature Colombian and Mexican fields lack standardized APIs, forcing costly middleware development for AI overlay deployment.
Strategic Opportunities
- Argentina Vaca Muerta Expansion:Unconventional shale operators in Neuquén province present greenfield deployment potential for automated frac design and real-time geosteering algorithms.
- Drone-Based Computer Vision:Offshore platform inspection via autonomous aerial systems remains underpenetrated across Latin American waters, offering faster anomaly detection than rope-access methods.
- ANH Data-Sharing Frameworks:Colombia's national hydrocarbon agency encourages collaborative seismic repositories, enabling vendors to train algorithms on aggregated basin-scale datasets rather than single-operator wells.
Industry Challenges
- Petroleum Data Science Talent Pipeline:Universities in São Paulo and Bogotá produce computer science graduates lacking domain fluency in reservoir mechanics, forcing operators to build expensive in-house training programs.
- Subsea Sensor Retrofit Complexity:Installing vibration and thermal monitoring equipment on existing wellheads in deepwater fields requires costly intervention vessel deployment and production deferment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America AI in Oil and Gas Market |
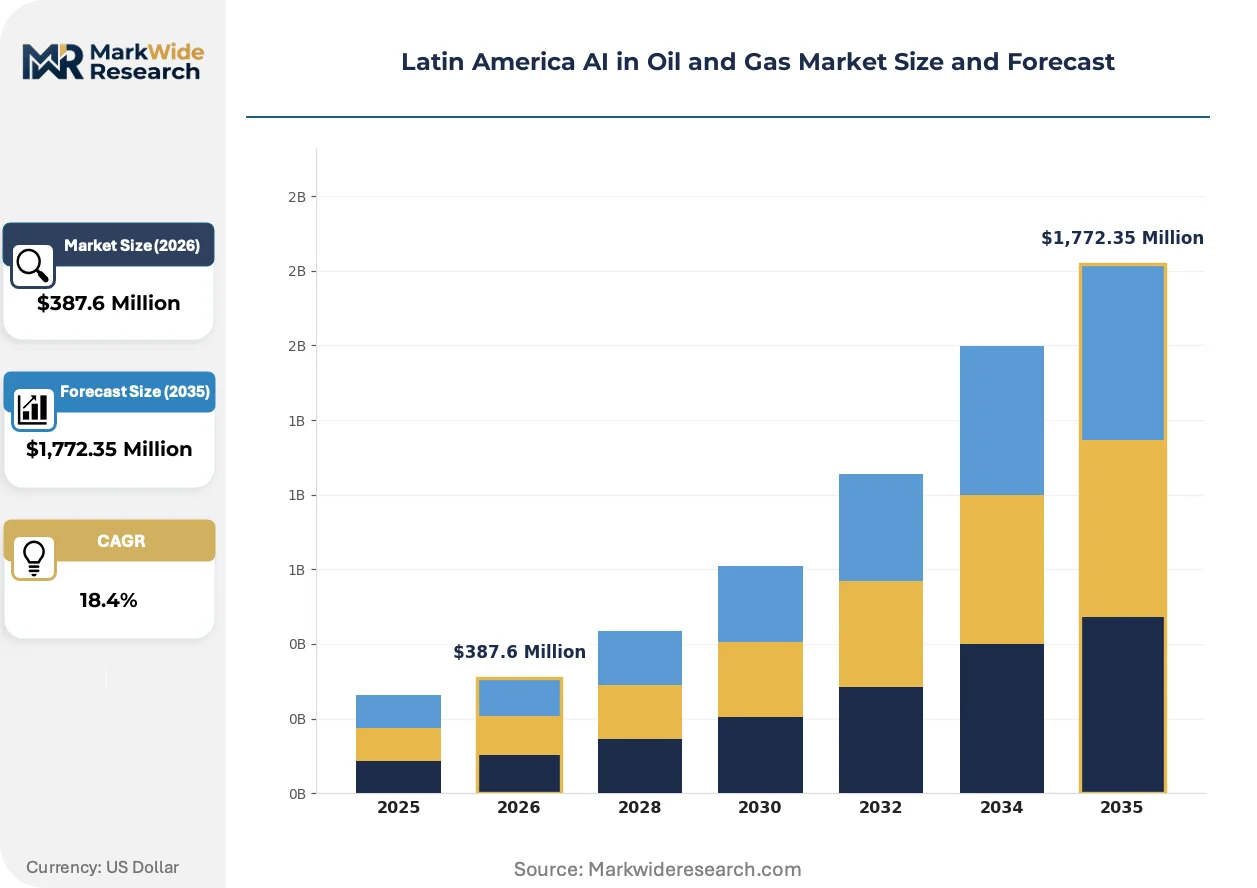
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Computer Vision Application: Exploration, Production Optimization, Maintenance, Supply Chain Management End User: Oilfield Services, E&P Companies, Refineries, Midstream Companies Deployment: Cloud, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Petrobras, Ecopetrol, Shell, ExxonMobil, TotalEnergies, SLB, Baker Hughes, Halliburton, 7Puentes, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America AI in Oil and Gas Market Evolving Landscape
Digital infrastructure across Latin American oilfields is converging on hybrid architectures that process time-critical decisions locally while feeding long-term pattern recognition to cloud-based training clusters.
Digital twin technology is virtualizing physical asset behavior across Brazilian pre-salt production facilities. Petrobras and international partners deploy these virtual replicas to simulate equipment degradation scenarios before they occur. This virtualization compresses maintenance scheduling cycles from calendar-based to condition-based intervals.
Brazil's ANP regulatory framework for digital oilfield technologies now mandates specific cybersecurity protocols and data retention standards for offshore installations. Operators must demonstrate encrypted transmission paths and redundant storage for production-critical algorithms. Deepwater developments in the Santos Basin face the steepest compliance timelines, with some projects restructuring vendor contracts to embed regulatory documentation deliverables.
Service contract structures are fragmenting from bundled field-development packages toward discrete AI module licensing. Pemex and private Mexican operators now separately procure seismic interpretation algorithms, drilling optimization software, and predictive maintenance systems. This unbundling is most visible in Mexico's shallow-water reform blocks, where international vendors compete on individual performance metrics rather than integrated project execution.
Latin America AI in Oil and Gas Market Segmentation
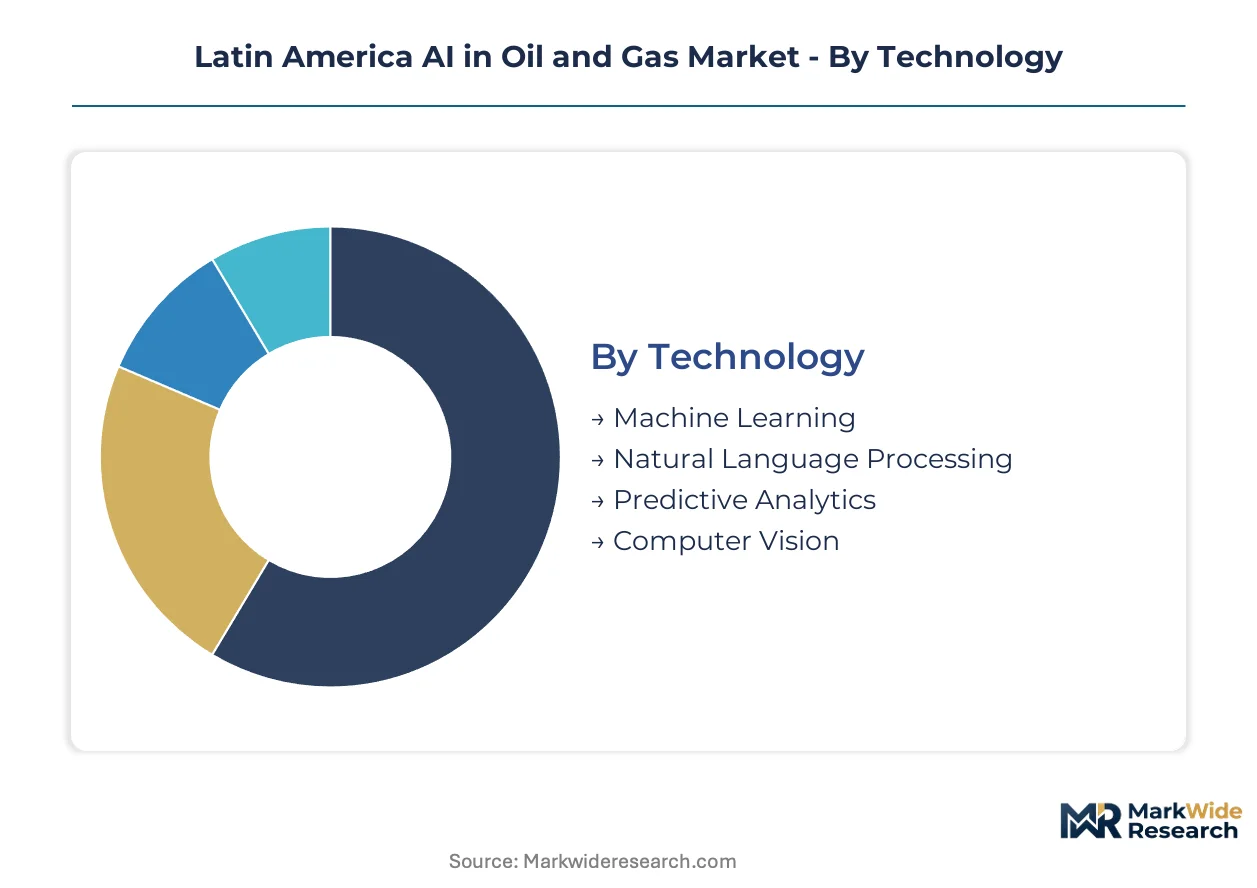
Latin American oilfield operators deploy AI across divergent technical and commercial configurations. Segmentation reveals how reservoir characteristics, infrastructure maturity, and regulatory environments shape technology procurement patterns across Brazil's pre-salt depths to Colombia's onshore conventional fields.
Technology:
Use-case spectrum spans predictive reservoir simulation through autonomous platform inspection, with computational intensity varying by data volume and latency requirements.
- Machine Learning:Neural networks and ensemble methods process seismic volumes and production histories to forecast reservoir performance. Brazilian pre-salt operators deploy these models for gas-lift optimization and artificial lift configuration in high-pressure carbonate formations.
- Computer Vision:Convolutional architectures analyze visual feeds from drone-mounted cameras and fixed platform sensors to detect corrosion, equipment misalignment, and thermal anomalies. Offshore inspection applications in Mexican and Brazilian waters are expanding most quickly as rope-access alternatives face safety and cost pressures.
- Natural Language Processing:Text extraction algorithms parse technical documentation, regulatory filings, and maintenance logs to automate knowledge retrieval across dispersed engineering teams.
- Predictive Analytics:Statistical forecasting engines project equipment failure timelines and production decline curves, enabling condition-based maintenance scheduling in mature Colombian and Mexican fields.
Established volume favors Machine Learning; emerging adoption favors Computer Vision.
Application:
Investment priority shifts upstream as brownfield economics tighten and deepwater development costs demand precision.
- Exploration:Seismic interpretation algorithms identify stratigraphic traps and direct hydrocarbon indicators from multi-terabyte survey datasets. Brazilian operators concentrate demand here as pre-salt appraisal drilling costs constrain tolerance for dry holes.
- Production Optimization:Real-time parameter adjustment maximizes recovery factors from existing wells. Colombia's Llanos Basin operators pursue incremental barrel economics through automated choke management and artificial lift tuning.
- Maintenance:Vibration and thermal signature analysis predicts pump failures and pipeline integrity degradation before catastrophic events.
- Supply Chain Management:Demand forecasting and logistics optimization coordinate offshore platform provisioning across dispersed Brazilian and Mexican installations.
Exploration commands current investment share; Production Optimization narrows the gap as field maturity advances.
End User:
Procurement authority distributes across asset ownership and service provision models, with contract structures determining whether AI deploys as operator capability or vendor-delivered service.
- E&P Companies:Integrated operators like Petrobras and Ecopetrol build proprietary algorithm teams for reservoir-centric applications where subsurface data confidentiality matters. These firms anchor demand for customized model development and digital twin infrastructure.
- Oilfield Services:Schlumberger, Baker Hughes, and Halliburton embed AI within bundled drilling and completion contracts. Service companies capture value through performance-based pricing tied to non-productive time reduction.
- Midstream Companies:Pipeline operators apply leak detection and flow optimization algorithms across Brazilian and Colombian transportation networks.
- Refineries:Process optimization and predictive maintenance target downstream units in Mexico and Brazil, though AI penetration lags upstream applications.
Upstream asset owners dominate current spend; service providers capture expanding share through integrated performance contracts.
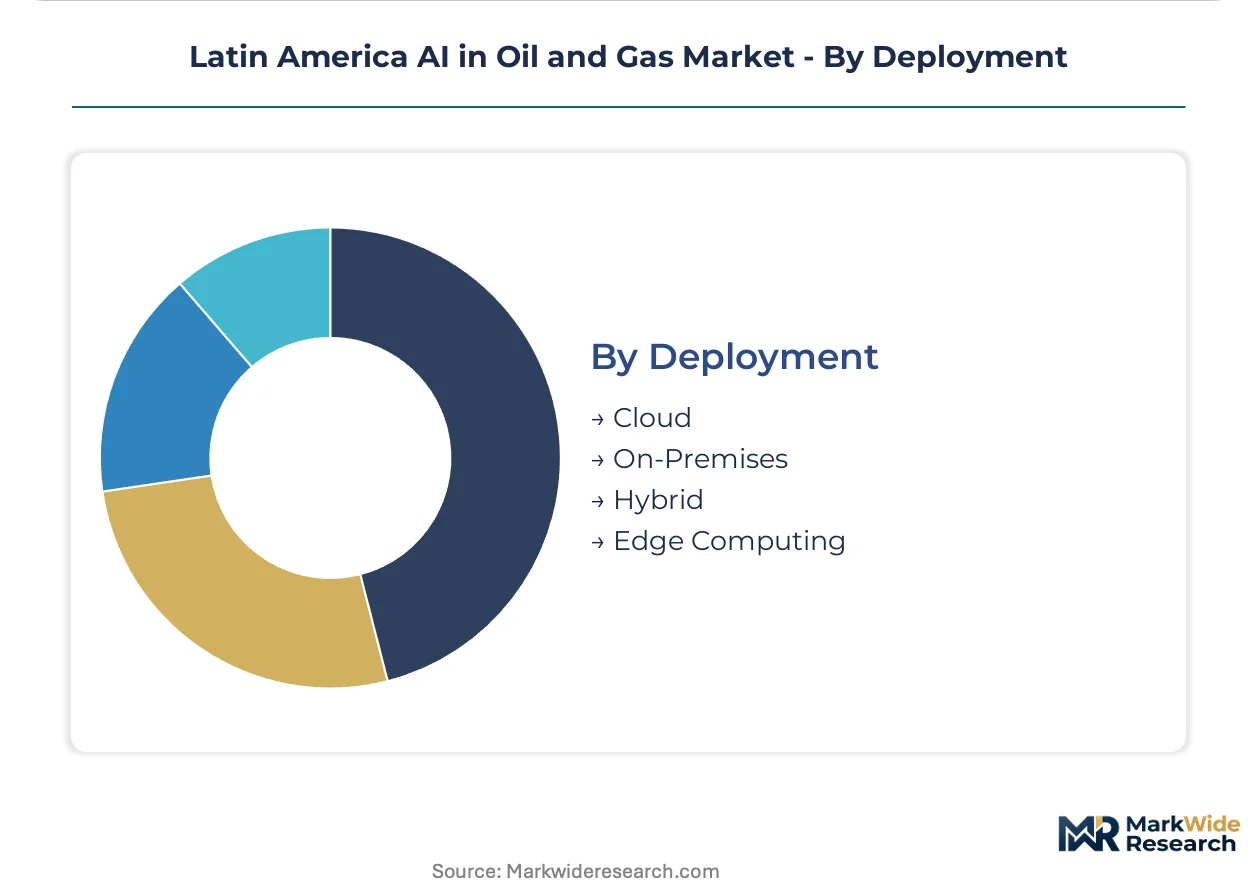
Deployment:
Infrastructure architecture balances computational proximity against scale economies, with regulatory data localization constraining pure cloud strategies.
- Edge Computing:Localized inference processors at wellsite or platform enable sub-second drilling decisions and autonomous safety shutdowns. Brazilian pre-salt fields deploy these architectures where satellite bandwidth limitations and ANP data residency requirements intersect.
- Hybrid:Time-critical workloads process locally while pattern recognition and model training feed centralized cloud clusters. This configuration dominates new installations across Latin America as vendors standardize edge-to-cloud orchestration.
- Cloud:Seismic processing and reservoir simulation training runs on GPU-accelerated remote infrastructure where data export restrictions permit.
- On-Premises:Legacy data center retention persists in Mexican and Colombian operations with established IT footprints and cybersecurity protocols.
Hybrid architectures gain preference fastest; pure cloud faces headwinds from Brazilian subsurface data localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators across Latin America concentrate procurement authority in deepwater and unconventional basins, with national oil companies anchoring capital deployment and international majors supplying specialized algorithmic capabilities.
Brazil
Petrobras drives demand through pre-salt basin digitalization, deploying neural networks for gas-lift optimization in high-pressure carbonate reservoirs. ANP mandates digital twin documentation and cybersecurity protocols for offshore developments, forcing vendor contract restructuring. Rio de Janeiro anchors vendor engineering presence, with international service firms clustering around Petrobras technical centers to support Santos Basin operations.
Colombia
Ecopetrol pursues incremental barrel economics in the Llanos Basin through automated choke management and artificial lift tuning. ANH encourages collaborative seismic data-sharing frameworks, enabling algorithm training on aggregated basin-scale datasets. Bogotá concentrates petroleum data science talent development, though universities produce computer science graduates requiring expensive domain-specific reskilling.
Mexico
Pemex and private reform-block operators unbundle AI procurement into discrete seismic interpretation, drilling optimization, and predictive maintenance modules. CNH oversight of contract terms shapes how international service companies structure licensing agreements. Ciudad del Carmen serves as the operational hub for shallow-water digital deployment, with vendors competing on individual performance metrics rather than integrated execution.
Argentina
Unconventional shale operators in Neuquén province present greenfield deployment potential for automated frac design and real-time geosteering algorithms. The country's national hydrocarbon regulator oversees data localization requirements that fragment cloud architectures. Vaca Muerta field development concentrates vendor attention, with operators seeking to compress drilling learning curves through machine-assisted parameter optimization.
Chile
Midstream and downstream applications dominate as pipeline operators apply leak detection algorithms across transportation networks and refineries pursue process optimization. The country's energy regulatory authority influences data governance standards for cross-border infrastructure. Antofagasta and Biobío regions anchor industrial demand, with copper mining-energy sector convergence creating adjacent AI talent pools for petroleum technology adaptation.
Latin America AI in Oil and Gas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure tiered by integration depth and domain specialization. National oil companies anchor demand through proprietary algorithm teams, while international service firms capture value via performance-based drilling contracts. Three archetypes dominate: integrated oilfield technology conglomerates, national operator digital divisions, and specialized algorithm vendors. Competitive moves center on unbundled module licensing and edge-to-cloud infrastructure partnerships.
Within the integrated service tier, SLB, Baker Hughes, and Halliburton occupy positions defined by bundled hardware-software deployment capabilities. These firms exemplify the shift toward discrete AI module licensing in Mexican shallow-water blocks and Brazilian pre-salt fields, where operators now separately procure seismic interpretation, drilling optimization, and predictive maintenance systems rather than integrated packages.
| Leading Market Players |
|---|
| Petrobras |
| Ecopetrol |
| Shell |
| ExxonMobil |
| TotalEnergies |
| SLB |
| Baker Hughes |
| Halliburton |
| 7Puentes |
| Others |
Value Network & Pricing Analysis
Brazilian pre-salt hardware concentration anchors margin capture at the GPU-accelerated computing tier, where NVIDIA-dominated AI chip supply feeds into Petrobras-contracted digital twin deployments. International service providers face margin compression as ANP data localization mandates force redundant infrastructure buildout across Rio de Janeiro and São Paulo data centers.
Pricing Analysis
Cost-plus contracts with Brent crude indexation dominate Brazilian pre-salt AI procurement, tying algorithm licensing fees to commodity price floors. Price differentiation hinges on ANP cybersecurity certification tier and edge-to-cloud integration depth, with certified vendors commanding premium positioning. Pricing pressure intensifies as Pemex and private Mexican operators unbundle integrated service packages into discrete module licensing. National oil companies exhibit lowest price sensitivity given proprietary algorithm investments, while midstream pipeline operators face acute cost compression in leak detection procurement.
Supply Chain Analysis
US export controls on advanced GPU architectures constrain hardware flows into Brazilian deepwater operations, fragmenting procurement channels between approved vendor tiers and secondary sourcing routes. Supply concentration centers on US semiconductor design, Taiwanese foundry capacity, and Chinese edge-computing enclosure manufacturing. Critical dependencies include high-bandwidth memory modules, subsea-rated sensor housings, and fiber-optic telemetry cables. Single-source vulnerability runs through NVIDIA's AI accelerator allocation system. Distribution runs through Schlumberger, Baker Hughes, and Halliburton field service networks with localized engineering presence in Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against cloud-native AI platforms that could displace legacy oilfield service architectures through API-first seismic interpretation tools.
For Market Incumbents: Entrench through backward integration into edge-computing hardware manufacturing, securing supply chain control over subsea-rated inference processors threatened by US export restrictions. Deepen ANP certification moats by embedding proprietary digital twin documentation workflows that cloud-native competitors cannot replicate without regulatory recertification cycles. For New Entrants and Emerging Players: Pursue Argentina's Vaca Muerta shale operators with automated frac design modules, the most penetrable geography given greenfield infrastructure absence and limited incumbent service density. Target Neuquén province drilling contractors with geosteering-as-a-service offerings priced per lateral foot rather than bundled day-rate contracts. For Investors and Strategic Acquirers: Capital is best deployed toward petroleum-domain AI specialists with proven ANP or ANH regulatory documentation capabilities and existing edge-computing deployment footprints. Long-term viability hinges on algorithm portability across Latin American regulatory regimes. Watch for Pemex procurement unbundling acceleration as the inflection signal indicating modular vendor preference shift.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Buildout | ANP data localization mandates force localized GPU deployment in Santos Basin operations. |
| Regulatory Certification Investment | ANP cybersecurity protocols create compliance moats against unlicensed algorithm vendors. |
| Digital Twin Platform Integration | Petrobras virtual asset documentation requirements anchor long-term service contracts. |
| Specialist Firm Acquisition | Petroleum-domain machine learning teams in São Paulo and Bogotá command scarcity premiums. |
| Drone-Based Inspection Partnership | Computer vision deployment across Mexican and Brazilian offshore platforms replaces rope-access methods. |
Research Methodology
A standing panel of reservoir engineering directors, digital oilfield project managers, ANP regulatory compliance officers, and petroleum data science leads provided ongoing calibration against secondary validation. Primary interviews with Petrobras, Ecopetrol, and Pemex technical procurement teams combined with SLB, Baker Hughes, and Halliburton digital platform executives. Secondary sources included ANP regulatory filings, ANH seismic data-sharing framework documentation, CNH contract term disclosures, and customs records of AI-accelerated computing hardware imports. Bottom-up project pipeline analysis triangulated against top-down E&P capital expenditure disclosures.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling technology, application, end user, and deployment segmentation dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves against disclosed Petrobras digital investment trajectories and international operator AI procurement patterns. Industry-specific inputs included pre-salt well count expansion schedules and Vaca Muerta frac stage intensity trends.
Macroeconomic conditions sit as an overlay; deviation in Brent crude price bands or Brazilian real exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding ANP regulatory timeline adherence and Pemex procurement reform velocity. Material shifts in US semiconductor export control scope or ANH data-sharing framework expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Well Casing Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Wellhead System Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Modular Gas Processing Plants Market