
 Latin America Oilfield Chemicals Market | 2026-2036
Latin America Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Oilfield Chemicals Market Foresight
HPHT-grade formulation requirements is unwinding legacy supply arrangements across Latin American basins. SLB leverages its integrated drilling and evaluation portfolio to anchor deepwater contracts in Brazil. Baker Hughes Company sustains technology leadership through specialized completion chemical systems. ChampionX differentiates via production chemical expertise tailored to mature field revitalization.
Oilfield chemicals comprise specialty formulations including corrosion inhibitors, biocides, demulsifiers, and rheology modifiers engineered to perform under reservoir temperatures exceeding 150°C and pressures above 10,000 psi, serving to maximize hydrocarbon recovery and protect asset integrity throughout the well lifecycle. Drilling fluids command the largest value share due to continuous consumption through extended-reach and deepwater campaigns, while production chemicals represent the fastest-expanding category as mature fields across Mexico and Venezuela require escalating scale of paraffin and asphaltene control. Stimulation chemicals concentrate margin pools where unconventional and carbonate reservoir development demands precision acidizing and fracturing fluid systems.
Brazil's ANP mandates local content thresholds that shape supplier qualification and domestic manufacturing investment decisions, while Mexico's ASEA enforces environmental compliance standards governing chemical discharge and waste management in offshore operations. REACH-aligned substance registration protocols from European parent companies additionally constrain product portability across the region. Stakeholders must monitor how evolving local content enforcement and carbon intensity disclosure requirements will reshape competitive access to Brazil's pre-salt and Mexico's Zama development timelines.
Market Dynamics
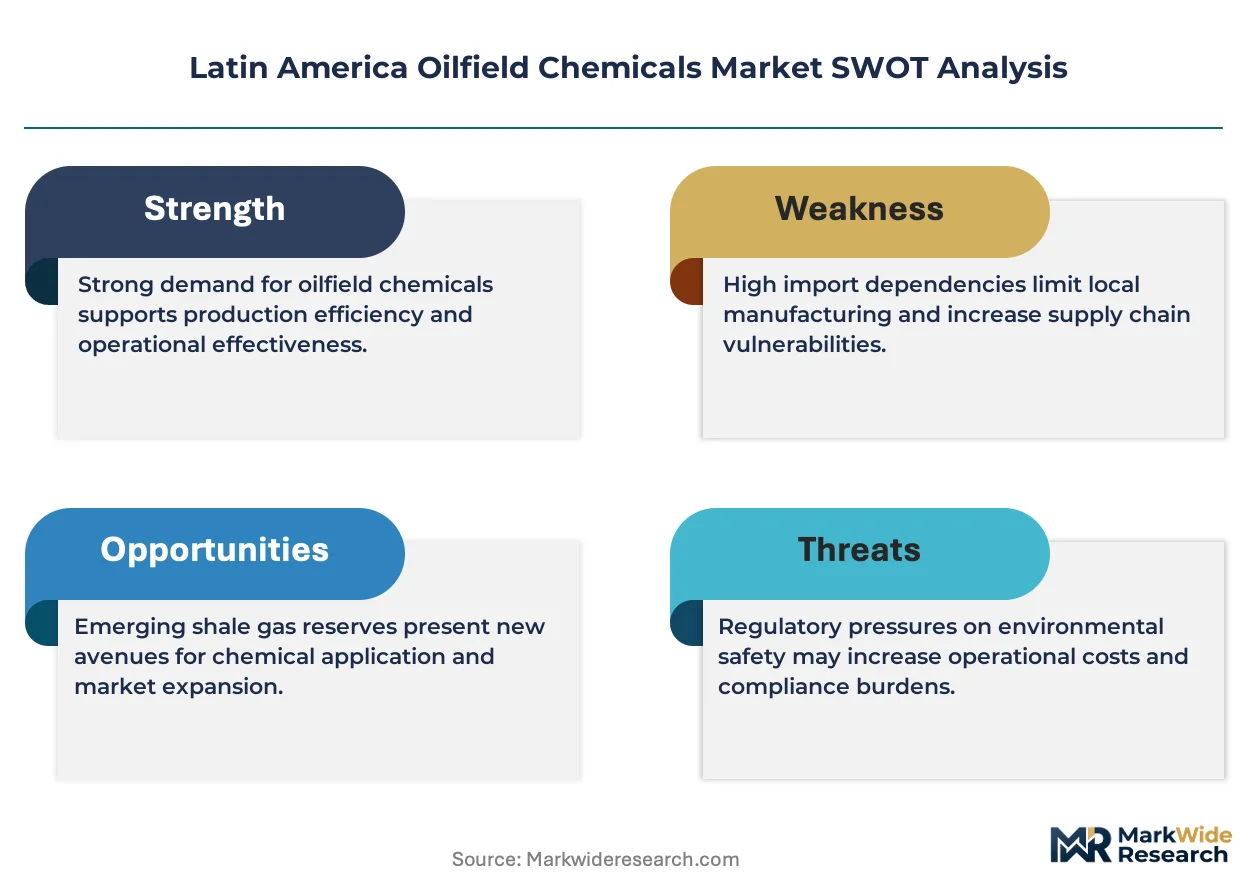
ANP's local content mandates are rewiring procurement relationships across Brazil's pre-salt supply chain, forcing international suppliers to either domesticate manufacturing or cede position to qualified local compounders.
Growth Catalysts
- Pre-salt HPHT drilling intensity:Reservoir conditions exceeding 150°C and 10,000 psi in Brazil's Santos Basin are consuming specialized synthetic-based drilling fluids at rates unmatched by conventional offshore developments.
- Mature field chemical intensity:Mexico's Cantarell and Venezuela's Lake Maracaibo assets require escalating paraffin inhibitor and asphaltene dispersant volumes to sustain production decline curves.
- ASEA environmental compliance:Mexico's offshore discharge standards are mandating biodegradable demulsifier formulations that command premium pricing and lock in qualified suppliers.
Market Restraints
- Feedstock volatility:Ethylene oxide and polyamine supply disruptions from US Gulf Coast petrochemical complexes transmit directly into surfactant cost structures for Latin American blenders.
- Import dependency:Argentina's formulation sector relies on Brazilian and US-sourced active intermediates, exposing operators to currency mismatch and logistics bottlenecks.
- REACH substance portability:European parent company registration protocols block product transfers into Latin America when dossier gaps emerge, fragmenting regional product portfolios.
Strategic Opportunities
- Colombia unconventional development:The Llanos Basin's emerging shale and tight sandstone plays lack established chemical service infrastructure, creating first-mover positioning for stimulation fluid specialists.
- Carbon intensity disclosure mandates:Brazil's pre-salt operators are beginning to scope chemical supply chain emissions, rewarding suppliers with verified low-carbon manufacturing processes.
- Digital chemical monitoring:IoT-enabled injection rate optimization and real-time corrosion monitoring are converging with production chemical service models to create subscription-based revenue streams.
Industry Challenges
- HPHT formulation expertise scarcity:Qualified chemists capable of designing stable 200°C+ drilling fluid systems are concentrated among a handful of international technology centers, constraining local workforce development.
- ANP qualification timelines:Supplier certification processes for Brazil's pre-salt campaigns extend 18-24 months, freezing out new entrants regardless of technical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Oilfield Chemicals Market |
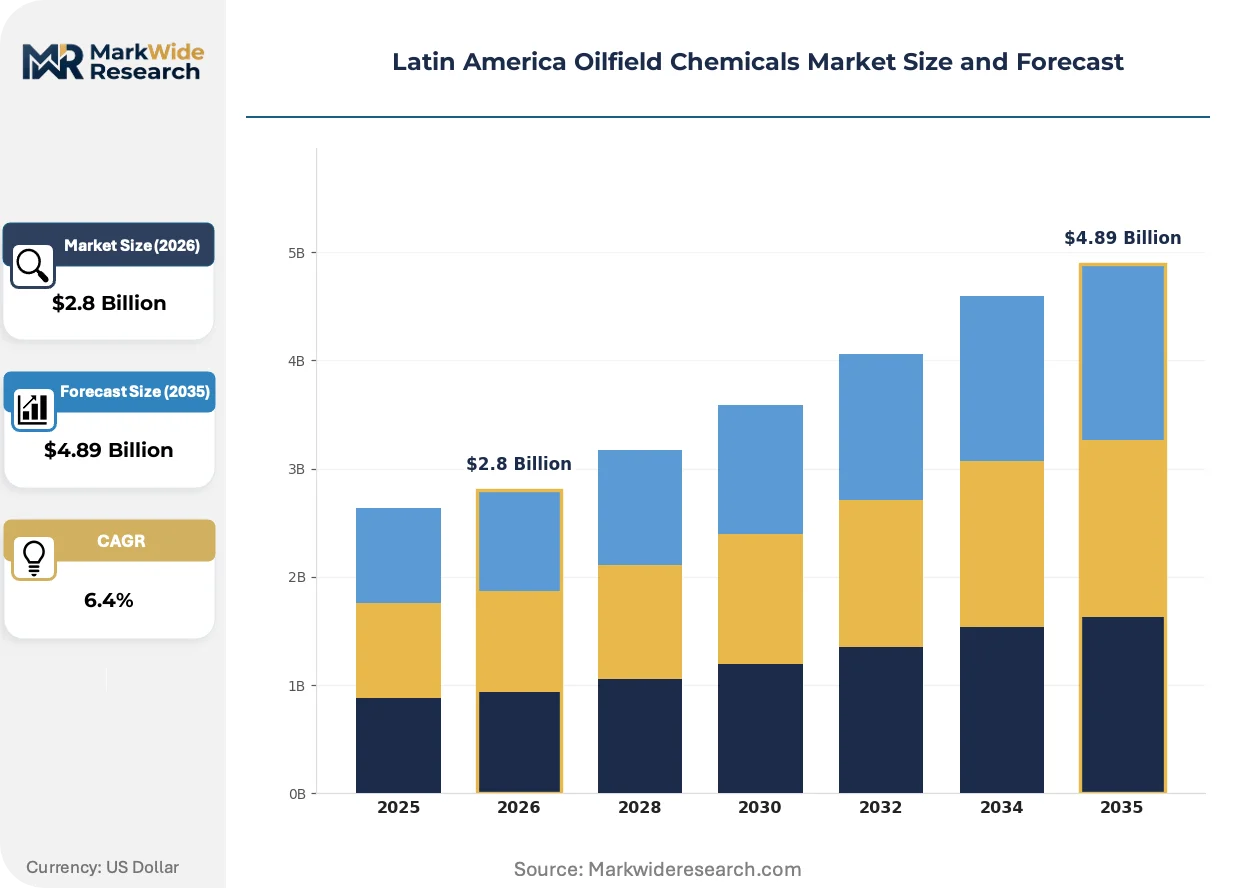
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Fluids, Completion Fluids, Production Chemicals, Stimulation Chemicals Application: Onshore Operations, Offshore Operations, Enhanced Oil Recovery, Well Stimulation End User: Exploration Companies, Production Firms, Service Providers, Equipment Manufacturers Technology: Biodegradable, Synthetic, Water-Soluble, Oil-Based |
| Companies Covered | SLB, Baker Hughes Company, ChampionX, Clariant AG, BASF SE, Dow Inc, Exxon Mobil Corporation, Halliburton, Solvay S A, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Oilfield Chemicals Market Shifts & Advancements
Synthetic base fluid chemistry and digital injection monitoring are converging to displace legacy mineral oil systems across Latin America's deepwater and mature field operations.
Silica nanoparticle-stabilized emulsion drilling fluids are fragmenting conventional invert emulsion market positions in Brazil's pre-salt campaigns. Petrobras and international operators are qualifying these systems for ultra-deepwater wells where barite sag and thermal degradation historically limited drilling efficiency. The technology is fragmenting service contracts away from integrated drilling fluid providers toward specialized nanofluid compounders with proprietary stabilization intellectual property.
ANP's updated local content measurement methodology is tightening enforcement across the chemicals value chain. The regulator now traces molecular origin through formulation stages rather than accepting blended-product certificates, compelling international suppliers to establish Brazilian manufacturing of active intermediates. Deepwater drilling fluid contracts are most affected, with operators restructuring procurement to meet 65% local content thresholds.
Performance-based chemical service contracts are displacing traditional volume-of-product purchasing across Mexico's mature fields. Pemex and private operators are transferring paraffin and corrosion treatment risk to suppliers through guaranteed production uptime clauses, compressing supplier margins while extending contract durations. The model is most visible in the southern region's heavy oil assets where chemical treatment intensity directly correlates with artificial lift run life.
Latin America Oilfield Chemicals Market Segmentation
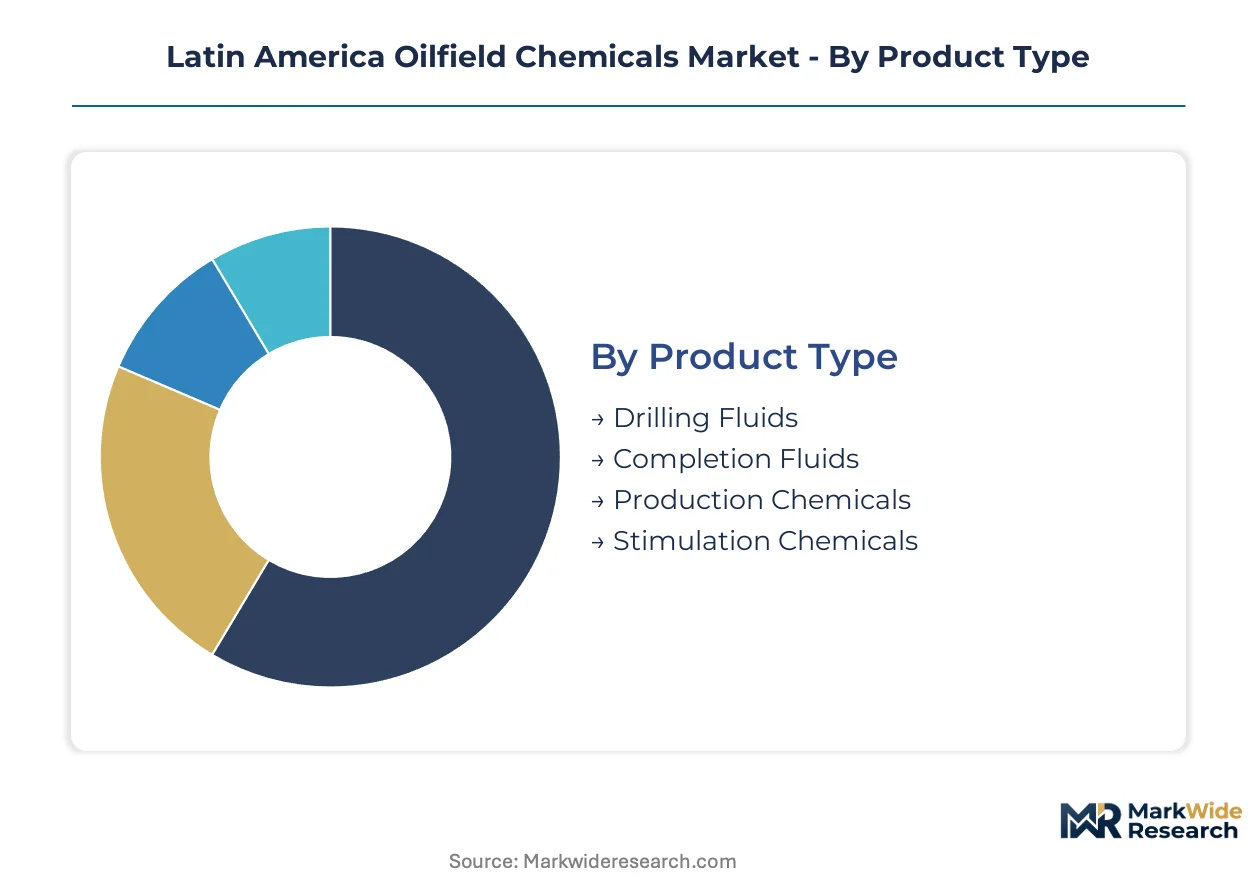
Segmentation in Latin America's oilfield chemicals market reveals how reservoir complexity and regulatory pressure fragment procurement patterns. Each dimension exposes different vulnerability to substitution, cost compression, and qualification barriers that reshape supplier economics across Brazil's pre-salt, Mexico's mature fields, and Argentina's unconventional plays.
Product Type:
Substitution pressure concentrates most acutely in drilling fluids, where synthetic-base alternatives displace mineral oil systems under ANP environmental scrutiny and HPHT performance requirements.
- Drilling Fluids:Synthetic-based and water-based formulations engineered for thermal stability above 150°C and barite sag resistance dominate Brazil's pre-salt procurement. Petrobras consumes these at volumes unmatched by conventional offshore developments, with ANP's 65% local content threshold forcing domestic blending investment.
- Production Chemicals:Paraffin inhibitors, asphaltene dispersants, and corrosion inhibitors deployed through continuous injection or batch treatment sustain output from Mexico's Cantarell and Venezuela's Lake Maracaibo assets. Pemex's performance-based contracting transfers production risk to suppliers, compressing margins while extending contract duration.
- Completion Fluids:Brine-based and viscoelastic systems for gravel packing and frac pack operations in deepwater completions.
- Stimulation Chemicals:Acidizing blends and fracturing fluid systems for carbonate and unconventional reservoir development.
Drilling fluids anchor the volume base while production chemicals gain share at the steepest rate.
Application:
Cost tier differentiation separates premium offshore specifications from commoditized onshore procurement, with environmental compliance adding a third pricing stratum.
- Offshore Operations:Deepwater and ultra-deepwater campaigns in Brazil's Santos and Campos basins consume HPHT-grade drilling fluids, completion brines, and subsea flow assurance chemicals under ASEA and ANP discharge standards. These applications command the highest technical qualification barriers and longest supplier certification timelines.
- Onshore Operations:Conventional drilling and workover activities across Argentina's Neuquén Basin and Colombia's Llanos Basin utilize standard water-based muds and basic production chemicals. Price sensitivity dominates procurement, with local compounders capturing share through logistics proximity rather than formulation differentiation.
- Enhanced Oil Recovery:Chemical EOR polymers and surfactants for mature field revitalization in Mexico and Venezuela.
- Well Stimulation:Acidizing and hydraulic fracturing treatments for tight formations and carbonate reservoirs.
Offshore operations concentrate margin pools while onshore operations expand most quickly as Argentina's shale development accelerates.
End User:
Customer type determines contract structure, with integrated operators favoring performance guarantees and independent producers prioritizing spot procurement flexibility.
- Exploration Companies:Pre-salt operators in Brazil and deepwater-focused independents in Mexico specify HPHT formulations and demand integrated drilling-evaluation-chemical service bundles. These buyers consolidate procurement through multi-year framework agreements with qualified suppliers.
- Production Firms:Pemex and mature field operators in Venezuela optimize chemical treatment intensity against artificial lift run life, driving adoption of outcome-based service contracts with guaranteed uptime clauses.
- Service Providers:Drilling contractors and completion service companies purchasing chemicals as part of integrated service delivery.
- Equipment Manufacturers:Suppliers of pumps, injection skids, and monitoring systems bundling chemical treatment hardware with formulation supply.
Production firms anchor the volume base while exploration companies drive specification escalation fastest.
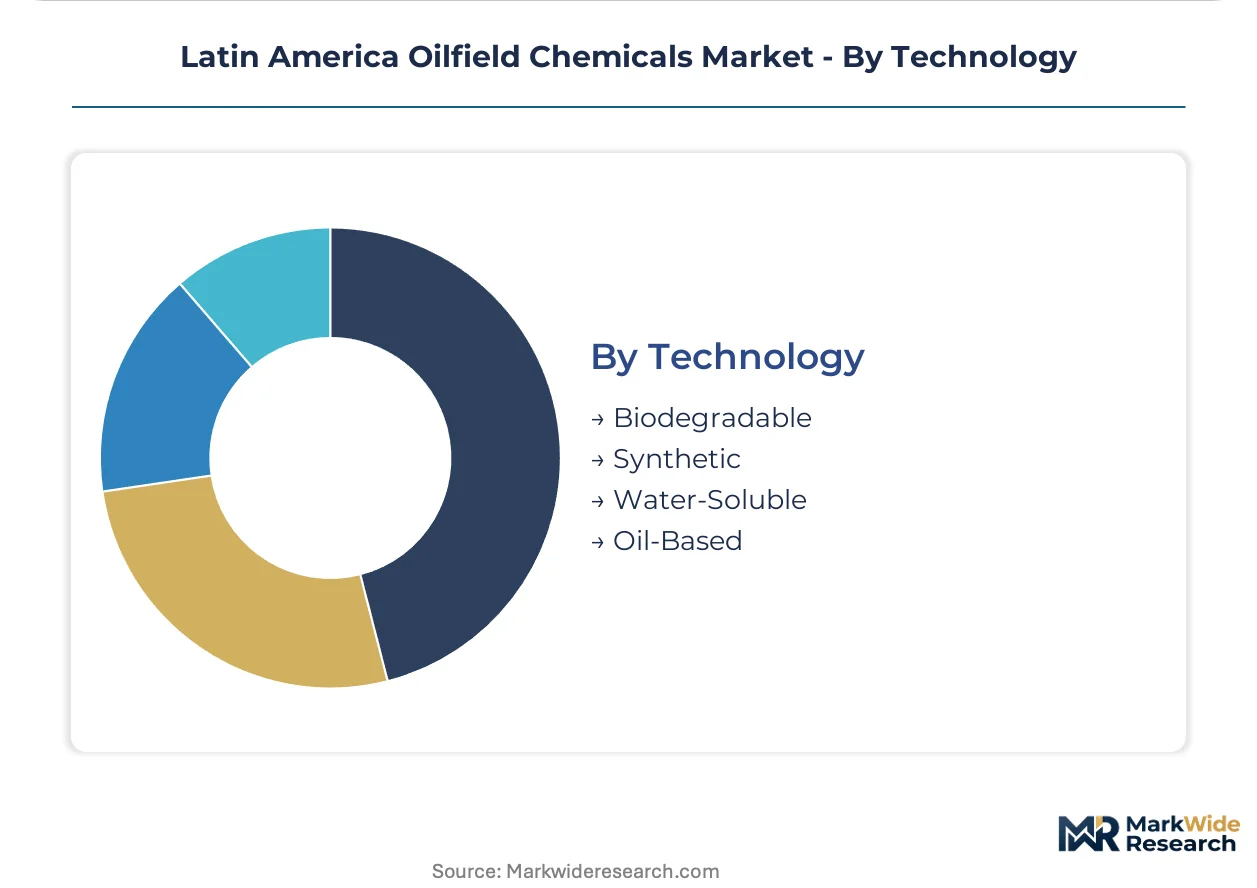
Technology:
Supply concentration in active intermediate manufacturing shapes which technology platforms achieve cost competitiveness in Latin American blending operations.
- Synthetic:Synthetic-base drilling fluids engineered from internal olefins and esters deliver thermal stability and biodegradability required for Brazil's pre-salt HPHT conditions. ANP's local content enforcement now traces molecular origin, compelling international suppliers to establish Brazilian manufacturing of base fluid precursors.
- Biodegradable:Environmentally acceptable lubricants and demulsifiers formulated for ASEA-compliant offshore discharge in Mexico and Brazil. These systems command premium pricing and lock in qualified supplier positions through regulatory pre-approval.
- Oil-Based:Conventional mineral oil and diesel-based drilling fluids facing displacement by synthetic alternatives under tightening environmental standards.
- Water-Soluble:Polymer-based systems for production chemicals and EOR applications.
Synthetic technology anchors the volume base while biodegradable formulations climb the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures across Latin America's oilfield chemicals landscape, with Brazil's pre-salt operators absorbing premium HPHT formulations while Argentina's shale drillers squeeze suppliers on standard water-based muds. This demand-elasticity contrast shapes where international suppliers anchor manufacturing versus where local compounders capture share.
Brazil
Pre-salt drilling campaigns in the Santos Basin consume synthetic-based drilling fluids at intensities unmatched elsewhere in the region. ANP's 65% local content threshold traces molecular origin through formulation stages, compelling suppliers to establish Brazilian manufacturing of base fluid precursors. The Macaé industrial corridor hosts blending facilities serving Petrobras and international operators.
Mexico
Cantarell's mature field decline drives escalating paraffin inhibitor and asphaltene dispersant volumes. ASEA enforces biodegradable demulsifier standards for offshore discharge, locking in qualified suppliers through regulatory pre-approval. Ciudad del Carmen clusters service companies supplying Pemex's southern region heavy oil assets.
Argentina
Neuquén Basin shale development accelerates stimulation chemical consumption for tight sandstone and unconventional plays. The formulation sector relies on Brazilian and US-sourced active intermediates, exposing operators to currency mismatch and logistics bottlenecks. YPF anchors procurement through framework agreements with qualified suppliers.
Colombia
Llanos Basin shale and tight sandstone plays lack established chemical service infrastructure, creating positioning opportunities for stimulation fluid specialists. The national hydrocarbons regulator enforces environmental licensing for drilling waste management. Bogotá-based procurement offices coordinate offshore Caribbean campaigns.
Chile
Minimal upstream activity concentrates demand on geothermal drilling chemicals and mining sector cross-over applications. Import dependency on Argentine and Brazilian supply chains shapes procurement timelines. Antofagasta's mining-chemicals industrial base offers potential blending capacity for future exploration.
Latin America Oilfield Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Latin America's oilfield chemicals market. Integrated service companies anchor deepwater contracts through bundled drilling-evaluation-chemical offerings, while regional compounders capture onshore share through logistics proximity. The market structures around three archetypes: global technology licensors, regional formulation blenders, and specialized nanofluid innovators. Dominant competitive moves include backward integration into active intermediate manufacturing and strategic partnerships to meet ANP qualification timelines.
Among the integrated technology tier, SLB, Baker Hughes Company, and ChampionX occupy distinct positioning vectors. SLB exemplifies the drilling-fluid-anchored service model through its integrated portfolio. Baker Hughes Company represents specialized completion chemical systems. ChampionX anchors production chemical expertise for mature field revitalization. These three illustrate how technology differentiation fragments contract capture across Brazil's pre-salt, Mexico's Cantarell, and Argentina's unconventional plays.
| Leading Market Players |
|---|
| SLB |
| Baker Hughes Company |
| ChampionX |
| Clariant AG |
| BASF SE |
| Dow Inc |
| Exxon Mobil Corporation |
| Halliburton |
| Solvay S A |
| Others |
Supply & Pricing Matrix
Synthetic-base drilling fluid chemistry displacing mineral oil systems across Brazil's pre-salt campaigns simultaneously redraws supply geography toward domestic Brazilian manufacturing and compresses pricing premiums for legacy formulations. ANP's molecular-origin tracing compels international suppliers to localize active intermediate production, fragmenting historical import-dependent cost structures while elevating qualified domestic compounders into premium contract tiers.
Pricing Analysis
Performance-based service contracts with guaranteed production uptime clauses now anchor lifetime value capture across Mexico's mature field operations. Three-tier pricing structure across premium HPHT formulations, standard offshore specifications, and economy onshore water-based muds stratifies procurement economics. Cost compression in standard-tier drilling fluids intensifies as Argentine shale drillers squeeze suppliers on commodity-grade formulations. National oil companies exhibit lowest price sensitivity for pre-salt HPHT specifications, while independent operators in Colombia's emerging plays drive hardest volume discounts.
Supply Chain Analysis
Inventory lead times for ethylene oxide and polyamine intermediates stretch across 45-60 day windows from US Gulf Coast petrochemical complexes to Latin American blending facilities. Active intermediate manufacturing concentrates in the United States, Brazil, and select European technology centers. Surfactant cost structures hinge on ethylene oxide supply continuity from Texas-Louisiana corridor operations. Single-source vulnerability pervades Argentina's formulation sector, which draws from Brazilian and US-sourced inputs. Distribution runs through Macaé industrial corridor hubs serving Petrobras, Ciudad del Carmen clusters supplying Pemex, and Neuquén Basin logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's oilfield chemicals market functions as a service-attach opportunity where digital injection monitoring and real-time corrosion management subscriptions expand faster than commodity formulation volumes. Recurring revenue from IoT-enabled chemical optimization layers now outpaces hardware-centric supply margins.
For Market Incumbents: Shield pre-salt contract positions by accelerating Brazilian manufacturing of base fluid precursors ahead of ANP's tightened molecular-origin enforcement. Backward integration into active intermediate production defends margin structures against qualified local compounders capturing share through local content compliance. Prioritize certification investment to compress 18-24 month qualification timelines for new product introductions.
For New Entrants and Emerging Players: Digital chemical monitoring service gaps in Colombia's Llanos Basin and Argentina's Neuquén shale plays offer first-mover positioning where established suppliers lack deployed infrastructure. Target stimulation fluid specialties for tight sandstone and unconventional reservoirs where technical service intensity remains underdeveloped. Pursue partnership-based go-to-market models with drilling contractors seeking bundled chemical-injection hardware and formulation supply.
For Investors and Strategic Acquirers: The market sits at a regulatory-enforcement acceleration phase that favors vertically integrated compounders with captive intermediate manufacturing and established ANP qualification status. Five-to-ten year viability centers on suppliers combining Brazilian production assets with digital service layer capabilities. Watch carbon intensity disclosure mandates as the inflection signal—operators scoping supply chain emissions will reward verified low-carbon manufacturing with preferential contract access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Intermediates | Captive ethylene oxide and polyamine supply secures ANP local content compliance for pre-salt contracts. |
| Digital Chemical Monitoring Platform Launch | IoT-enabled injection optimization creates subscription revenue streams beyond commodity formulation sales. |
| Brazilian Manufacturing Footprint Expansion | Macaé corridor blending capacity satisfies molecular-origin tracing requirements for deepwater drilling fluids. |
| Performance-Based Service Contract Structure | Guaranteed production uptime clauses transfer operational risk while extending contract duration with Pemex. |
| Biodegradable Formulation Certification | ASEA-compliant demulsifier pre-approval locks in qualified supplier positions for Mexico offshore discharge. |
Research Methodology
The analysis maps drilling fluids, production chemicals, completion fluids, and stimulation chemicals, each validated through technical discussions with plant managers at Brazilian blending facilities, procurement leads at Pemex and YPF, distribution channel partners across Andean logistics corridors, and R&D directors specializing in HPHT formulation chemistry. Primary interview insights triangulate against customs and trade data from regional import registries, ANP local content compliance filings, ASEA environmental licensing records, and SEC 10-K disclosures from integrated service companies. Bottom-up volume modeling from individual basin consumption patterns reconciles with top-down market sizing derived from national oil company procurement disclosures.
Consistency checks validate volume and value outputs against external benchmarks including petrochemical feedstock consumption trends, offshore rig deployment counts, and mature field production decline curves across the projection horizon. Segmentation dimensions span product type, application tier, end-user category, and technology platform, with additional granularity on HPHT-grade versus standard specification splits. CAGRs derive from basin-level activity forecasts, well-count projections, and chemical intensity per well type across the modeling period. Forecast inputs incorporate ANP local content enforcement trajectories, ASEA discharge standard evolution, and shale development pacing in Argentina's Neuquén Basin.
Forecasts assume regulatory continuity in Brazil's ANP local content regimes and Mexico's ASEA environmental frameworks; material policy shifts would require re-modeling qualification timelines and compliance cost structures. Forecasts reflect assumptions on feedstock supply continuity from US Gulf Coast petrochemical complexes and currency stability for Argentine import-dependent formulation sectors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Underreamers Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Delayed Coker Unit Process Technology Market