
 Europe Oilfield Services Market | 2026-2036
Europe Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oilfield Services Market Foresight
Integrated maintenance contracts bundled with real-time diagnostics is shifting how European operators procure oilfield capabilities. Schlumberger Limited leverages its digital infrastructure to anchor long-term service agreements across Norwegian offshore assets. Halliburton Company competes through specialized hydraulic fracturing expertise in unconventional shale plays. Baker Hughes Company differentiates via advanced completion technologies that reduce well intervention frequency.
Europe oilfield services encompass technical activities including drilling, completion, production optimization, and workover operations performed under reservoir pressures exceeding 10,000 psi and temperatures above 150°C, primarily to maximize hydrocarbon recovery rates and extend field economics. Drilling services occupies the largest revenue share due to sustained capital allocation toward deepwater projects in the Barents Sea and West of Shetland. Digital oilfield represents the fastest-expanding technology segment as operators deploy IoT-enabled subsea monitoring to cut unplanned downtime. Completion services commands premium margins where high-pressure high-temperature well architectures demand specialized equipment.
The EU Green Deal and F-Gas Regulation impose stringent emissions thresholds on offshore operations, compelling service providers to retrofit fleets with lower-carbon power systems and electrified drilling packages. ECHA REACH compliance adds material traceability requirements for chemicals deployed in well stimulation and enhanced recovery programs. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority jointly shape decommissioning timelines and platform abandonment standards. Stakeholders must weigh carbon intensity metrics against reservoir productivity when selecting service configurations for upcoming field development campaigns.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing operational margins across offshore service fleets, forcing rapid electrification of drilling packages and subsea power systems while reservoir depletion in mature North Sea fields accelerates brownfield redevelopment spend.
Growth Catalysts
- Digital Oilfield Deployment:Norwegian operators integrate IoT-enabled subsea monitoring to cut unplanned downtime across Barents Sea assets.
- EU Green Deal Compliance:Electrified rig retrofits qualify for carbon credit offsets, redirecting capital toward low-emission service configurations.
- Brownfield Revitalization:Maturing reservoirs in the UK North Sea trigger workover campaigns using advanced completion technologies.
Market Restraints
- Steel Alloy Supply Concentration:High-pressure drilling riser manufacturing depends on German and Japanese specialty steel mills with 18-month order backlogs.
- ECHA REACH Traceability:Chemical disclosure requirements for well stimulation fluids add 6-9 months to product registration timelines.
- Geothermal Substitution:District heating operators in the Netherlands redirect public funding from gas field services toward deep geothermal drilling.
Strategic Opportunities
- Platform Decommissioning Surge:Norway's Petroleum Safety Authority accelerates abandonment timelines, opening specialized cutting and removal service contracts.
- CCUS Integration:Carbon capture mandates create demand for repurposed wellbore infrastructure and CO2 injection expertise.
- Hydrogen Blending Infrastructure:Dutch and German offshore pipelines require retrofit services to handle hydrogen-natural gas mixtures.
Industry Challenges
- Subsea Robotics Talent Gap:ROV pilot and automation engineer shortages delay digital oilfield deployment schedules by 4-6 months.
- Legacy SCADA Integration:1990s-era platform control systems resist seamless connection to cloud-based predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oilfield Services Market |
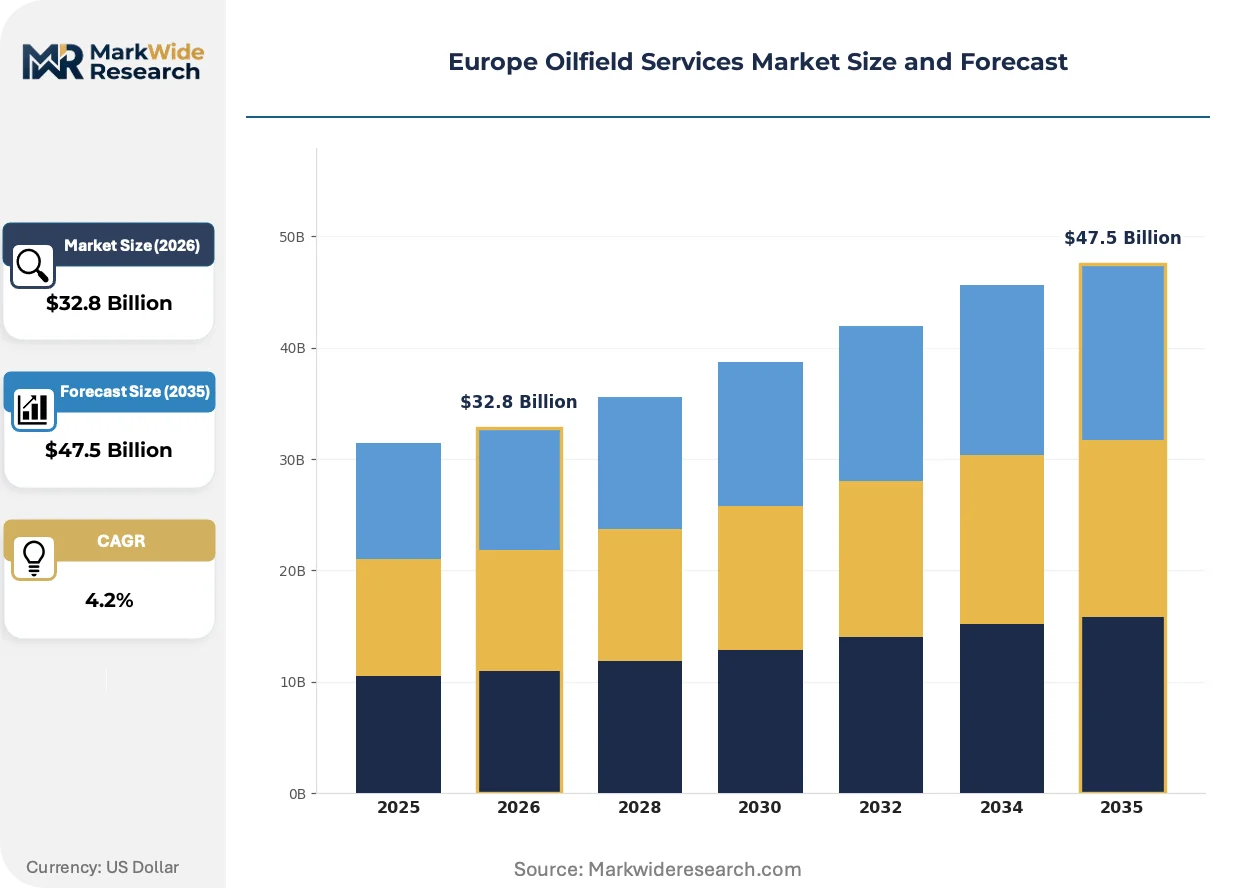
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Production Services, Completion Services, Workover Services Technology: Digital Oilfield, Hydraulic Fracturing, Enhanced Oil Recovery, Offshore Technology Application: Onshore Fields, Offshore Fields, Shale Exploration, Mature Fields End User: Independent Operators, National Oil Companies, International Oil Companies, Suppliers |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International PLC, Transocean Ltd, National Oilwell Varco, Archer, Expro Group, Saipem SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oilfield Services Market Shifts & Advancements
Real-time reservoir monitoring and predictive analytics are compressing traditional maintenance cycles, while regulatory carbon thresholds force simultaneous hardware electrification and software optimization across North Sea operations.
Autonomous underwater vehicle swarms equipped with AI-driven leak detection algorithms are absorbing routine pipeline inspection tasks previously assigned to crewed vessels. Norwegian operators deploy these systems across subsea infrastructure at 40% lower per-kilometer cost than conventional methods. The technology is absorbing capital previously allocated to manned support fleets, restructuring service provider revenue toward data analytics subscriptions.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon-based cooling systems on offshore platforms by 2030. Service contractors must retrofit HVAC and refrigeration packages with natural refrigerant alternatives, compressing equipment replacement windows. UK North Sea installations face the steepest compliance costs due to aging platform infrastructure and salt-air corrosion exposure.
Integrated service contracts now bundle drilling, completion, and 10-year maintenance obligations into single-source agreements. Independent operators in the West of Shetland basin favor this model over fragmented procurement, transferring operational risk to service providers. Norway hosts the most advanced contracting structures, with real-time performance penalties tied to production uptime guarantees.
Europe Oilfield Services Market Segmentation
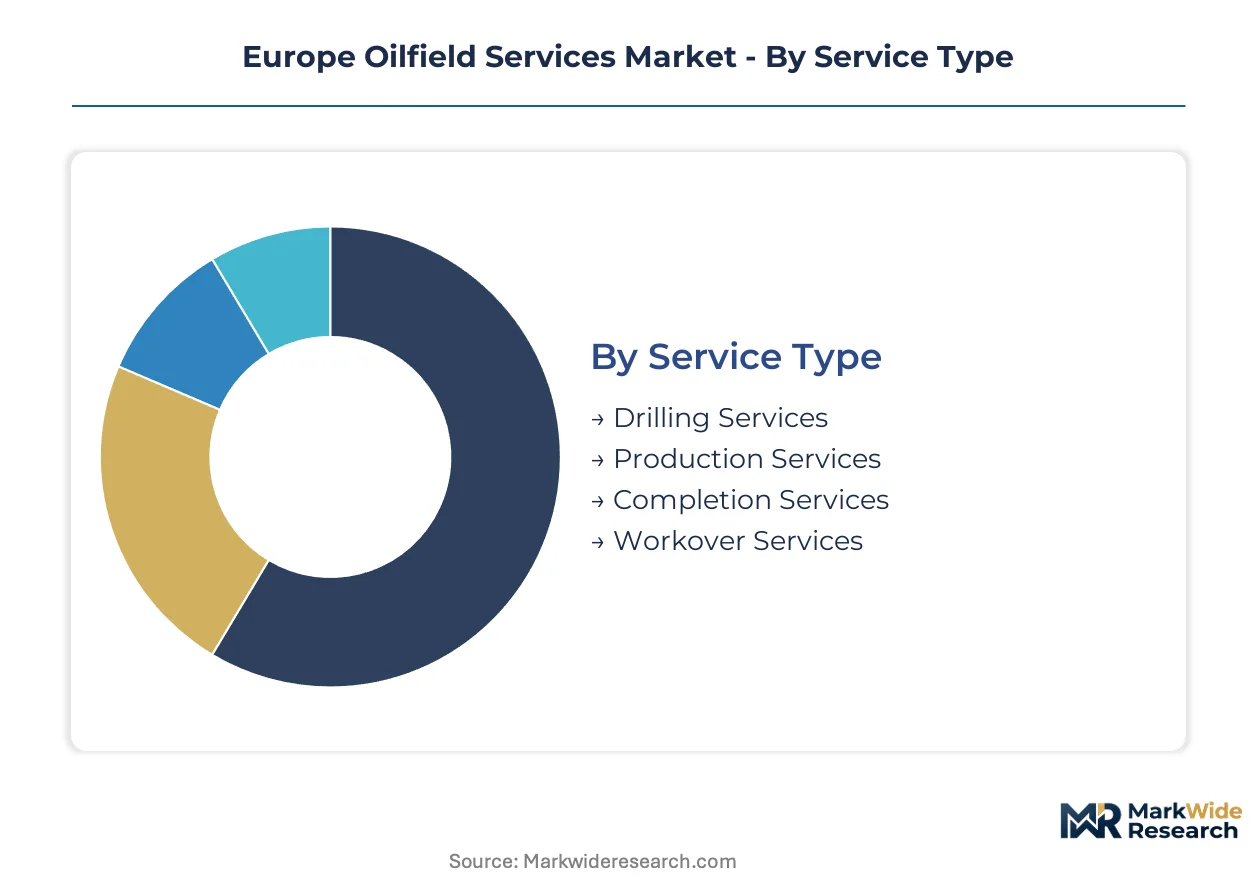
Europe's oilfield services market fragments across four distinct axes that determine procurement patterns, technology deployment, and margin structures. Service type and technology segments dominate capital allocation decisions, while application and end-user categories shape operational risk profiles and contract duration preferences across Norwegian, UK, and Dutch basins.
Service Type:
Technical complexity and reservoir pressure specifications differentiate service tiers, with high-pressure high-temperature architectures commanding specialized equipment and premium pricing.
- Drilling Services:Encompasses directional drilling, managed pressure systems, and riser operations for reservoirs exceeding 10,000 psi. Norwegian Barents Sea developments and West of Shetland deepwater projects concentrate demand, though 18-month specialty steel backlogs constrain fleet expansion.
- Completion Services:Covers wellbore architecture design, intelligent completions, and subsea tree installation. Premium margins attach to HPHT configurations where UK North Sea independents prioritize production uptime guarantees over initial cost.
- Production Services:Includes artificial lift, surface facility maintenance, and flow assurance. Mature Dutch onshore fields and UK brownfield assets drive steady demand for optimization-focused contracts.
- Workover Services:Delivers well intervention, recompletion, and plug-and-abandonment operations. Norway's accelerated decommissioning timelines are expanding rig demand for platform removal campaigns.
Drilling Services leads on scale; Completion Services leads on momentum.
Technology:
Capital deployment intensity varies sharply across technology categories, with digital infrastructure absorbing discretionary spend while hardware electrification responds to regulatory mandates.
- Digital Oilfield:Integrates IoT-enabled subsea monitoring, predictive analytics platforms, and cloud-based SCADA connectivity. Norwegian operators deploy these systems to cut unplanned downtime across Barents Sea infrastructure, though legacy platform integration resists seamless connection.
- Hydraulic Fracturing:Applies high-pressure fluid injection to unconventional shale formations. UK onshore shale exploration and Polish tight gas prospects concentrate limited European demand against public opposition headwinds.
- Enhanced Oil Recovery:Deploys chemical, thermal, or gas injection methods to extend mature field economics. UK North Sea brownfield operators evaluate polymer flooding against carbon intensity thresholds under EU Green Deal compliance.
- Offshore Technology:Encompasses subsea processing, floating production systems, and electrified drilling packages. Norway's electrification mandates and UK platform retrofits drive fleet modernization spend.
Digital Oilfield climbs fastest on investment trajectory; Offshore Technology carries the heaviest compliance burden.
Application:
Field maturity and water depth dictate service configuration requirements, with offshore developments demanding integrated contract structures that onshore operations rarely replicate.
- Offshore Fields:Requires subsea infrastructure, platform-based processing, and marine logistics coordination. Norwegian deepwater and UK North Sea developments anchor regional revenue concentration.
- Mature Fields:Demands workover campaigns, enhanced recovery programs, and eventual decommissioning services. UK and Dutch late-life assets are expanding brownfield specialist procurement.
- Onshore Fields:Encompasses conventional drilling and production optimization at lower capital intensity. Limited Netherlands and Germany activity contrasts with North American scale.
- Shale Exploration:Applies unconventional completion techniques to tight formations. UK regulatory barriers and Polish geological complexity constrain European deployment against North American benchmarks.
Offshore Fields dominates absolute spend; Mature Fields expands most quickly on decommissioning acceleration.
End User:
Ownership structure determines risk appetite, contract duration preferences, and technology adoption speed across the European basin.
- International Oil Companies:Operates integrated portfolios spanning exploration through decommissioning. Equinor and Shell anchor Norwegian and UK capital allocation with long-term service agreements.
- Independent Operators:Focuses on niche basin positions with aggressive cost structures and rapid technology adoption. UK North Sea independents favor bundled drilling-completion-maintenance contracts.
- National Oil Companies:Manages state hydrocarbon interests with strategic priority over pure commercial returns. Limited European presence outside Norway's Equinor hybrid structure.
- Suppliers:Provides equipment, chemicals, and logistical support as tiered subcontractors. REACH compliance and F-Gas retrofit requirements are reshaping qualification standards.
International Oil Companies anchors procurement volume; Independent Operators leads on contracting innovation speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys electrified drilling packages at scale, while the United Kingdom concentrates decommissioning expenditure. The Netherlands redirects capital toward geothermal substitution. Each national market operates under distinct regulatory pressures and basin maturity profiles.
Norway
Barents Sea deepwater developments and Johan Sverdrup electrification anchor drilling demand. The Petroleum Safety Authority accelerates platform abandonment timelines. Stavanger hosts the highest concentration of subsea robotics contractors deploying IoT-enabled monitoring systems.
United Kingdom
West of Shetland projects and mature North Sea brownfield workovers absorb service capacity. The North Sea Transition Authority shapes decommissioning standards and carbon intensity benchmarks. Aberdeen maintains its position as the primary procurement hub for integrated drilling-completion contracts.
Netherlands
Groningen field depletion and onshore gas production decline redirect operator capital. National climate policy favors deep geothermal drilling over hydrocarbon field services. Rotterdam port infrastructure supports offshore logistics for southern North Sea campaigns.
Germany
Specialty steel mills in the Ruhr region supply high-pressure drilling risers with 18-month order backlogs. ECHA REACH compliance requirements add traceability burdens for chemical suppliers. Hamburg anchors marine equipment fabrication for North Sea offshore technology.
Denmark
Tyra field redevelopment and Danish North Sea late-life asset optimization sustain production service demand. National regulators align decommissioning schedules with EU Green Deal carbon thresholds. Esbjerg functions as the primary logistics base for offshore installation campaigns.
Europe Oilfield Services Market Competitive Landscape
Top-tier vendors anchor integrated service contracts, while mid-tier specialists compete on niche technology segments. The market structure concentrates around full-service providers with digital infrastructure capabilities and regional specialists with basin-specific expertise. Three archetypes dominate: integrated technology platforms, hydraulic fracturing specialists, and advanced completion technology providers. Competitive moves center on long-term performance-based contracting and fleet electrification retrofits.
Within the integrated technology tier, Schlumberger Limited and Baker Hughes Company exemplify full-service positioning across Norwegian and UK offshore assets. Halliburton Company occupies a specialized position in unconventional completion methodologies. These three entities represent contrasting strategic postures: digital infrastructure anchoring, premium completion technology, and fracturing expertise respectively.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International PLC |
| Transocean Ltd |
| National Oilwell Varco |
| Archer |
| Expro Group |
| Saipem SpA |
| Others |
Supply & Pricing Matrix
EU Green Deal electrification mandates are forcing rapid fleet retrofits across Norwegian and UK offshore operations, compelling service providers to absorb upfront capital costs while negotiating long-term performance contracts that transfer operational risk from operators.
Pricing Analysis
Capacity additions in Norway's electrified rig fleet are reshaping price floors for integrated drilling packages as contractors compete for Johan Sverdrup and Barents Sea work. Three-tier pricing structure across premium HPHT configurations, standard deepwater systems, and economy brownfield units reflects completion complexity and uptime guarantee terms. Cost compression in standard-tier services is intensifying because German specialty steel backlogs extend equipment delivery timelines. Independent operators in the UK North Sea exhibit highest price sensitivity, while Equinor anchors premium-tier procurement with decade-long bundled agreements.
Supply Chain Analysis
Direct-to-operator channels handle integrated service demand from Norwegian and UK international oil companies, bypassing tiered distributors for drilling-completion bundles. Manufacturing concentrates in Germany for high-pressure riser steel, Japan for subsea robotics components, and the Netherlands for offshore platform HVAC systems. Raw material flows draw from Ruhr region alloy mills, North Sea offshore fabrication yards, and Rotterdam port logistics hubs. Single-source vulnerability in German specialty steel creates procurement bottlenecks for HPHT drilling architectures. Distribution runs through Stavanger and Aberdeen service bases for North Sea campaign mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe oilfield services market functions as a stable compounder, with regulatory-mandated electrification spend and brownfield decommissioning cycles providing durable revenue visibility across the projection horizon.
For Market Incumbents: Anticipate margin compression from EU F-Gas retrofit deadlines by securing captive supply agreements with German steel mills and accelerating in-house production of electrified drilling packages. Vertical integration into subsea robotics talent pipelines defends against ROV pilot shortages that delay digital oilfield deployment schedules. For New Entrants and Emerging Players: Platform decommissioning specialists represent the most penetrable segment, as Norway's Petroleum Safety Authority accelerates abandonment timelines faster than incumbent capacity expansion. CCUS wellbore repurposing expertise offers a second white-space target. Partner with UK North Sea independents through outcome-based maintenance contracts that transfer uptime risk from operator balance sheets. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier completion technology providers holding basin-specific HPHT expertise in the West of Shetland. Long-term viability hinges on exposure to Norwegian electrification mandates rather than Dutch geothermal substitution headwinds. Watch carbon credit pricing trajectories as the inflection signal for low-emission service configuration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Retrofit | EU Green Deal compliance unlocks carbon credit offsets for Norwegian Barents Sea operators. |
| Subsea Robotics Talent Acquisition | ROV pilot pipelines in Stavanger address 4-6 month deployment delays for digital oilfield programs. |
| Integrated Service Contract Expansion | Bundled drilling-completion-maintenance agreements transfer operational risk from UK independents. |
| Platform Decommissioning Capability Buildout | Norway's Petroleum Safety Authority timelines open specialized cutting and removal service contracts. |
| CCUS Wellbore Infrastructure Repurposing | Carbon capture mandates create demand for CO2 injection expertise across UK North Sea assets. |
Research Methodology
Direct dialogue with drilling contractors, subsea equipment procurement managers, North Sea platform operators, and EHS compliance officers grounded the qualitative foundation, cross-referenced with Norwegian Petroleum Directorate production statistics, UK North Sea Transition Authority decommissioning databases, EU ETS carbon price series, and ECHA REACH chemical registration filings. Bottom-up rig count and service intensity models triangulated against top-down operator capital expenditure disclosures.
Bottom-up segmentation modeled service type, technology category, application maturity, and end-user ownership structure across the analysis window. CAGRs derived from rig dayrate trajectories, electrification retrofit spend curves, and brownfield workover frequency patterns. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and Norway's platform abandonment timeline acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon credit pricing volatility and geothermal substitution rates in the Netherlands. Forecasts reflect documented assumptions around regulatory enforcement consistency and specialty steel supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Downhole Tools Market