
 Construction Sustainable Materials Market | 2026-2036
Construction Sustainable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Sustainable Materials Market Analysis
Commercial project pipelines are repositioning toward net-zero certifications, pulling specification power away from traditional residential volume plays. BASF SE leverages its chemical R&D depth to develop lower-carbon concrete admixtures that meet tightening performance thresholds. Saint-Gobain anchors its position through integrated glass and insulation systems designed for circular material recovery. Kingspan Group dominates insulated panel fabrication with manufacturing scale that spans multiple climate zones.
Construction sustainable materials comprise engineered and naturally sourced inputs selected for reduced embodied carbon, renewable feedstock origin, or end-of-life recyclability, with specifications typically targeting below 500 kg CO2 equivalent per cubic meter for structural concrete alternatives. These materials serve to decarbonize the built environment while maintaining compressive strength, thermal performance, and fire resistance parameters required by building codes. Eco-friendly concrete variants containing supplementary cementitious materials currently lead volume due to their drop-in compatibility with existing formwork and finishing trades. Bamboo and engineered timber represent the fastest-growing material type category as structural grading standards mature and prefabrication workflows expand. Recycled metal occupies a mature margin position where price volatility in virgin ore markets creates intermittent demand spikes.
The EU Green Deal and REACH frameworks enforce embodied carbon disclosure and restricted substance lists that reshape product qualification across member states. The EPA and state-level building codes in California and New York impose parallel low-carbon procurement standards that filter through to material specifications. BIS certification requirements in India and China's GB standards for green building materials add compliance layers for multinational suppliers. Stakeholders must monitor regulatory divergence between carbon accounting methodologies as this determines which material innovations achieve cross-border market access.
Market Dynamics
EU Green Deal embodied carbon limits are compressing specification windows for structural materials, forcing developers to pre-qualify suppliers against tightening CO2 thresholds before project financing closes.
Growth Catalysts
- REACH substance restrictions:The ECHA restricted substance list eliminates high-carbon additives from concrete formulations, pulling demand toward SCM-blended alternatives that satisfy disclosure mandates.
- Cross-laminated timber grading:Structural certification for engineered timber now covers mid-rise commercial spans, opening specification in German and Austrian municipal housing tenders.
- India's green building codes:BIS certification requirements for low-carbon cement create procurement pull in commercial real estate developments across Mumbai and Bangalore.
Market Restraints
- Biogenic feedstock volatility:Bamboo harvest cycles in Southeast Asia face climate-driven yield compression, creating raw material price instability for panel manufacturers.
- Admixture supply concentration:Lower-carbon concrete additives depend on fly ash and slag streams concentrated in Chinese and Indian steel production corridors.
- Performance certification gaps:Fire resistance testing protocols for mass timber lag behind steel and concrete standards in several EU member state building codes.
Strategic Opportunities
- Brazilian commercial construction:ANVISA-aligned green building standards remain underpenetrated, creating first-mover positioning for certified insulation system suppliers.
- Digital material passports:Blockchain-tracked embodied carbon data converges with BIM workflows, enabling specification premiums for documented supply chains.
- California procurement mandates:State-level low-carbon concrete standards create guaranteed offtake for admixture innovators meeting Buy Clean thresholds.
Industry Challenges
- Structural engineer retraining:Mass timber design competency remains scarce in markets where concrete-dominated curricula dominate university programs.
- Multi-certification stacking:Projects pursuing both LEED and BREEAM ratings face conflicting documentation requirements that extend pre-construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Sustainable Materials Market |
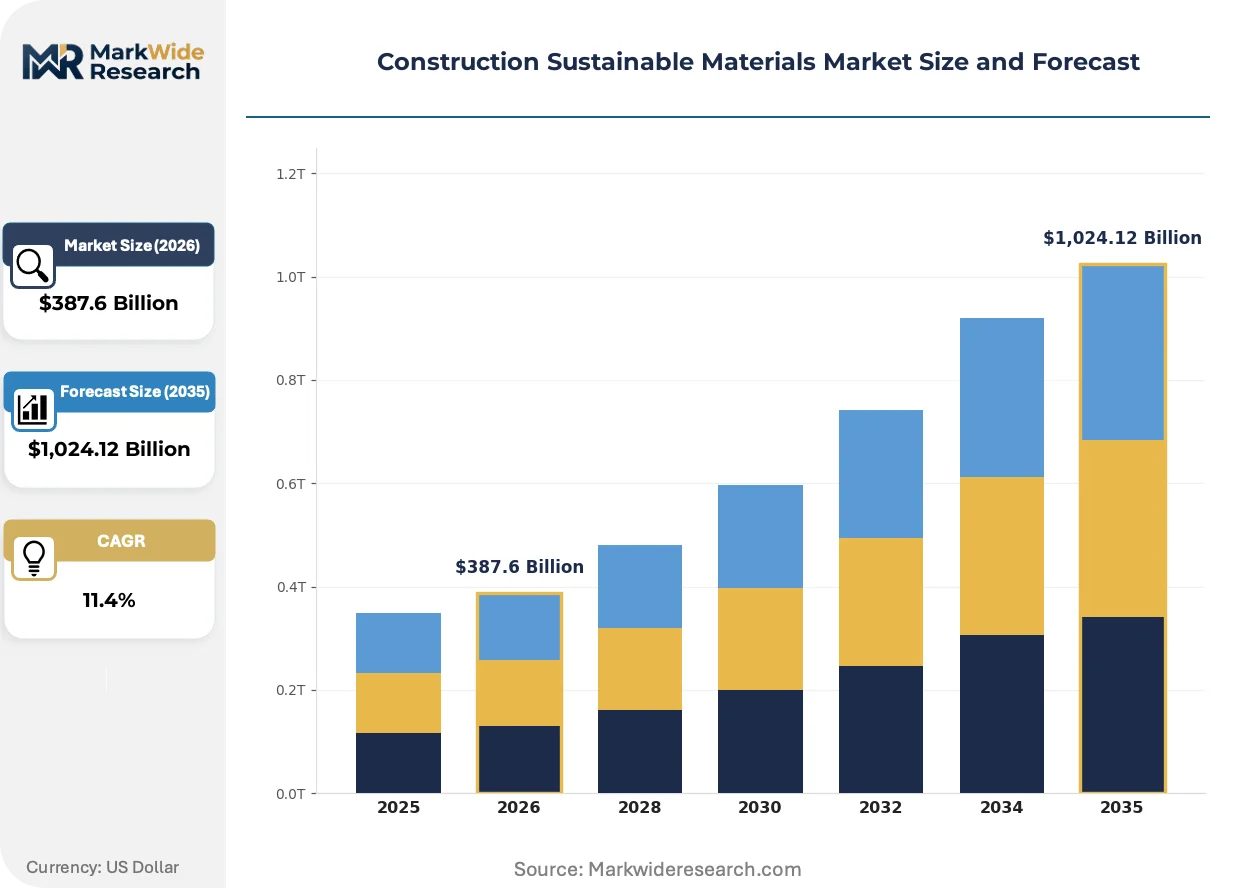
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Bamboo, Recycled Metal, Hemp, Eco-friendly Concrete Application: Residential Buildings, Commercial Projects, Road Construction, Infrastructure Development Manufacturing Stage: Raw Material Sourcing, Processing, Fabrication, Installation End User: Architects, Contractors, Developers, Owners |
| Companies Covered | BASF SE, Kingspan Group, LafargeHolcim, Saint-Gobain, Sika AG, Owens Corning, DuPont, CRH, CEMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Sustainable Materials Market Emerging Trajectories
Material innovation pipelines are pivoting from performance-only optimization toward integrated carbon accounting, with digital tracking tools now embedded in specification workflows.
Geopolymer concrete formulations is overtaking traditional Portland-based mixes in Nordic infrastructure tenders. Danish and Swedish transport agencies now specify these binders for bridge decks and tunnel linings. The shift is compressing demand for conventional cement in public procurement channels.
California's Buy Clean California Act mandates embodied carbon disclosure for structural materials in state-funded projects. Contractors must submit Environmental Product Declarations before bid acceptance. Steel and concrete suppliers with verified low-carbon production methods now capture preferential scoring in Los Angeles and San Francisco municipal evaluations.
Design-build firms are consolidating material selection authority that architects previously held. Tier-one contractors in Germany and the Netherlands now maintain pre-qualified supplier lists based on carbon intensity data rather than unit pricing. This concentration is visible in Amsterdam's waterfront redevelopment and Hamburg's port district conversions.
Construction Sustainable Materials Market Segmentation
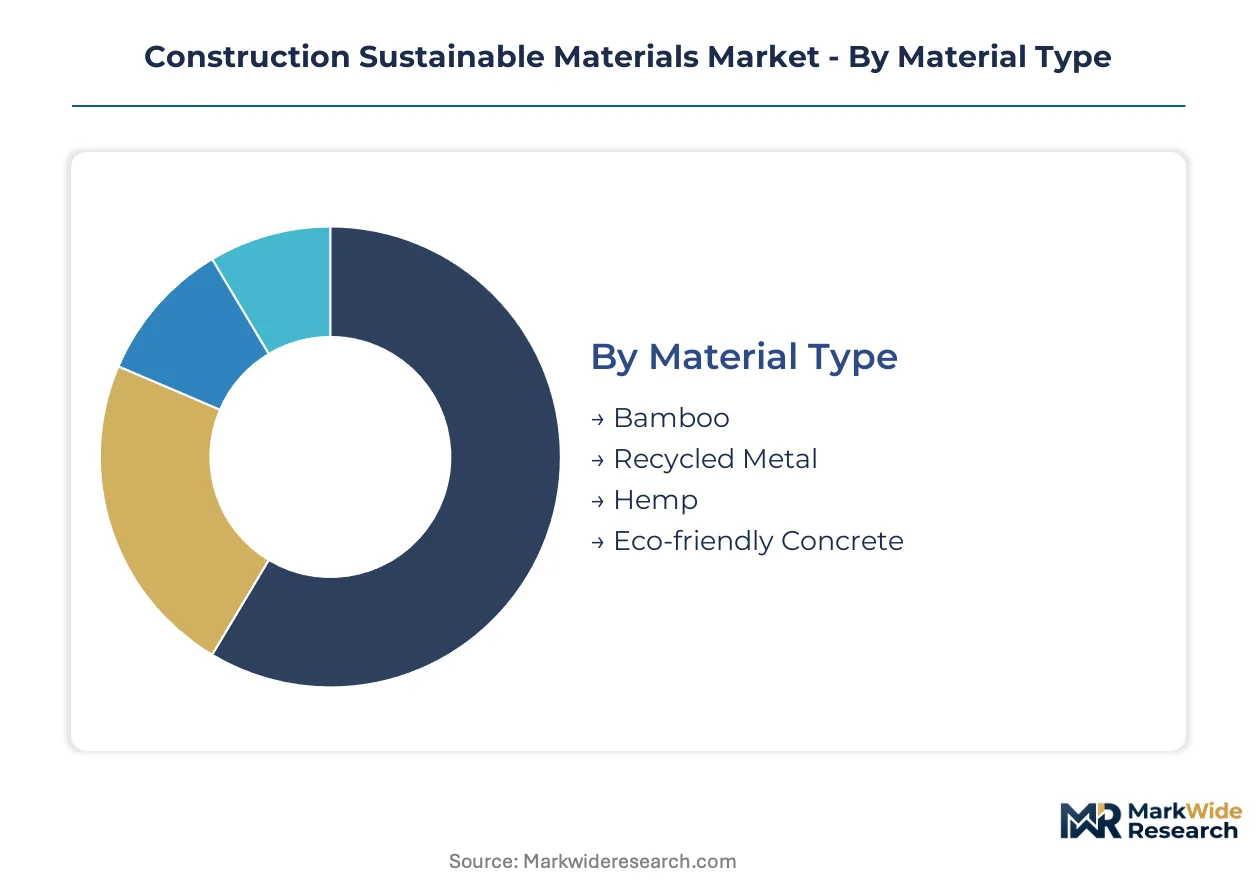
Material specification in sustainable construction follows distinct decision pathways where embodied carbon thresholds, structural performance requirements, and procurement authority determine category prioritization. Segmentation reveals how technical specifications diverge across project types and stakeholder roles, with regulatory pressure compressing acceptable ranges for carbon-intensive alternatives.
Material Type:
Buyers select materials based on embodied carbon benchmarks against structural performance requirements, with specification windows narrowing as EU Green Deal thresholds tighten.
- Bamboo:Rapidly renewable grass species harvested on 3-5 year cycles deliver tensile strength comparable to timber in non-structural applications. German and Austrian municipal housing tenders now specify bamboo paneling for interior finishes as ECHA substance restrictions eliminate synthetic alternatives. Supply volatility from Southeast Asian climate-driven yield compression creates intermittent procurement challenges.
- Eco-friendly Concrete:Portland cement replacements incorporating fly ash, slag, or calcined clay achieve compressive strength above 30 MPa while cutting embodied carbon below 350 kg CO2 per cubic meter. California's Buy Clean Act mandates EPD submission for state-funded projects, pulling specification toward verified low-carbon formulations in Los Angeles and San Francisco municipal evaluations.
- Recycled Metal:Reprocessed steel and aluminum from end-of-life building components and industrial scrap feed structural framing with reduced virgin ore dependency.
- Hemp:Bast fiber and hurd from cannabis sativa cultivars provide bio-aggregate for lime-based insulating renders and lightweight concrete alternatives.
Volume sits with eco-friendly concrete; growth tilts toward bamboo as prefabrication workflows mature and structural grading standards expand.
Application:
Project scale and certification targets reshape material selection, with net-zero commercial developments commanding premium specifications unavailable to volume residential builders.
- Commercial Projects:Mid-rise office and retail developments pursuing LEED Platinum or BREEAM Outstanding ratings specify cross-laminated timber for primary structure and low-carbon concrete for foundation systems. Amsterdam's waterfront redevelopment and Hamburg's port district conversions demonstrate consolidated contractor authority over pre-qualified supplier lists based on carbon intensity data.
- Infrastructure Development:Bridge decks, tunnel linings, and transport corridors in Nordic markets specify geopolymer concrete binders that eliminate Portland cement entirely. Danish and Swedish transport agencies now mandate these formulations for public procurement channels, compressing conventional cement demand in government-funded construction.
- Residential Buildings:Single-family and multi-family housing volume operates under tighter margin constraints that limit sustainable material premiums to code-minimum compliance.
- Road Construction:Pavement and sub-base applications incorporate recycled aggregates and alternative binders where performance testing protocols accommodate variable feedstock quality.
Commercial applications command specification premiums; infrastructure channels show steepest expansion trajectory as public procurement mandates proliferate.
Manufacturing Stage:
Carbon accounting boundaries now extend across production stages, with digital material passports tracking embodied emissions from extraction through site delivery.
- Raw Material Sourcing:Extraction of bamboo culms, industrial by-products for SCMs, and recovered metal scrap requires verified chain-of-custody documentation for EPD compliance.
- Processing:Drying, crushing, and chemical treatment of bio-based feedstocks determines final material properties and carbon intensity scores.
- Fabrication:Cross-laminated timber panel pressing, concrete batching, and insulation system assembly concentrates value-add in factory-controlled environments.
- Installation:Site assembly of prefabricated components reduces waste generation and enables end-of-life material recovery planning through BIM-integrated tracking.
Fabrication captures margin concentration; installation gains strategic weight as design-build firms consolidate material selection authority.
End User:
Procurement influence is migrating from design-phase architects to construction-phase contractors as guaranteed maximum price contracts transfer specification risk.
- Contractors:Tier-one design-build firms in Germany and the Netherlands now maintain proprietary supplier databases ranked by verified carbon intensity rather than unit pricing. Pre-qualification requirements ahead of project financing close compress acceptable supplier windows to documented low-carbon producers.
- Developers:Residential and commercial project sponsors face EU Green Deal embodied carbon limits that force early-stage supplier validation against tightening CO2 thresholds.
- Architects:Specification authority diminishes as performance risk transfers to contractors under integrated project delivery models.
- Owners:Institutional asset holders demand operational and embodied carbon disclosure for portfolio ESG reporting, filtering through to material selection criteria.
Contractors hold expanding specification control; developer procurement teams gain influence through early-stage supplier pre-qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of supplementary cementitious materials concentrates in Chinese and Indian steel corridors, while consumption tilts toward German and Dutch construction markets where procurement mandates enforce embodied carbon thresholds. This geographic split shapes supplier qualification requirements and cross-border material flows.
Germany
Residential developers in Bavaria and North Rhine-Westphalia accelerate cross-laminated timber specifications as the EU Green Deal tightens embodied carbon limits for new buildings. The KBA and federal building codes enforce disclosure mandates that compress acceptable supplier windows. Hamburg's port district conversions demonstrate consolidated contractor authority over pre-qualified low-carbon material lists.
United States
California and New York municipal procurement drives specification of verified low-carbon concrete through state-level building codes. The EPA and Buy Clean California Act mandate Environmental Product Declarations for state-funded projects. Los Angeles and San Francisco municipal evaluations now score steel and concrete suppliers with documented production methods preferentially.
India
Commercial real estate developments in Mumbai and Bangalore pull procurement toward BIS-certified low-carbon cement as green building codes expand. The Bureau of Indian Standards certification requirements create compliance layers for multinational suppliers entering the market. Maharashtra and Karnataka state infrastructure projects increasingly specify fly ash and slag-blended alternatives.
Sweden
Danish and Swedish transport agencies mandate geopolymer concrete binders for bridge decks and tunnel linings, eliminating Portland cement entirely from public procurement. The Nordic municipal procurement frameworks favor certified sustainable materials for infrastructure. Stockholm and Gothenburg transport corridors demonstrate steepest expansion trajectory for cement-free formulations.
Brazil
ANVISA-aligned green building standards in São Paulo and Rio de Janeiro remain underpenetrated, creating positioning opportunities for certified insulation system suppliers. The national health surveillance agency's building material protocols add compliance layers distinct from European frameworks. Southeastern commercial construction clusters show emerging demand for documented supply chains.
Construction Sustainable Materials Market Vendor Landscape
Top-tier vendors anchor the chemical and building materials segment, while regional specialists occupy fabrication and installation tiers. The market structure consolidates around integrated material systems providers with captive R&D pipelines and multi-certification capabilities. Strategic archetypes include chemical conglomerates with admixture portfolios, integrated glass-insulation system houses, and prefabricated panel fabricators with climate-zone-spanning manufacturing scale. Dominant competitive moves center on backward integration into raw material sourcing and technology licensing for geopolymer formulations.
Among European-headquartered conglomerates, BASF SE and Saint-Gobain occupy positions exemplifying divergent strategic archetypes. BASF SE represents the chemical R&D depth vector, while Saint-Gobain anchors the integrated building systems approach. Kingspan Group sits within the fabrication-scale tier, demonstrating manufacturing footprint expansion across multiple climate zones. Sika AG exemplifies the specialty chemicals positioning focused on construction additives and bonding systems.
| Leading Market Players |
|---|
| BASF SE |
| Kingspan Group |
| LafargeHolcim |
| Saint-Gobain |
| Sika AG |
| Owens Corning |
| DuPont |
| CRH |
| CEMEX |
| Others |
Supply Flow & Price Mechanics
Tier-one design-build contractors in Germany and the Netherlands now consolidate procurement authority through pre-qualified supplier databases ranked by verified carbon intensity rather than unit pricing, compressing acceptable windows to documented low-carbon producers and reshaping how sustainable materials command premium positioning.
Pricing Analysis
Margin tightening in mass timber and geopolymer concrete reflects certification bottlenecks and limited qualified supplier pools. Three-tier pricing structure across premium certified, standard compliant, and economy baseline levels separates EPD-verified producers from disclosure-gap competitors. Cost-down pressure on conventional Portland cement accelerates as EU Green Deal thresholds disqualify high-carbon formulations from municipal tenders. Volume residential developers exhibit highest price sensitivity; net-zero commercial developers absorb certification premiums.
Supply Chain Analysis
Domestic-content mandates in California's Buy Clean Act and India's BIS certification requirements reshape sourcing toward verified local production. Supply concentrates in Chinese and Indian steel corridors for fly ash and slag feedstocks, German and Austrian engineered timber fabrication clusters, and Nordic geopolymer binder production. Raw material flows draw from Southeast Asian bamboo harvests, European industrial by-product streams, and recovered construction metal scrap. Single-source vulnerability in admixture feedstocks creates procurement risk. Distribution runs through contractor-controlled pre-qualification systems rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction sustainable materials sector sits in a technology-transition phase where geopolymer binders and cross-laminated timber systems displace Portland cement and steel framing in mid-rise commercial and infrastructure applications.
For Market Incumbents: Anchor market position through backward integration into SCM feedstock streams and captive R&D pipelines for cement-free formulations. Threat from specialty chemical entrants with patented admixture technologies intensifies as patent cliffs approach on core concrete additive portfolios. Prioritize certification investment for EPD coverage across product lines to maintain pre-qualification status in EU and California procurement channels. For New Entrants and Emerging Players: Launch via direct contractor engagement models that bypass traditional distribution. Brazilian commercial construction clusters and Indian green building code compliance services represent underpenetrated white-space where ANVISA-aligned standards and BIS certification create first-mover positioning. Target digital material passport platforms that integrate with BIM workflows to capture specification premiums through documented supply chain transparency. For Investors and Strategic Acquirers: The window for entry favors geopolymer formulation specialists and regional timber engineering fabricators with structural certification coverage. Long-term viability hinges on regulatory ratchet effects that permanently disqualify high-carbon alternatives from public procurement. Watch for EU Green Deal threshold tightening announcements as inflection indicators that compress incumbent repositioning timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SCM Feedstocks | Secures fly ash and slag supply from Chinese and Indian steel production corridors against admixture concentration risk. |
| Geopolymer Formulation Licensing | Enables cement-free concrete production for Nordic infrastructure tenders eliminating Portland entirely. |
| Digital Material Passport Platform | Converges blockchain-tracked embodied carbon data with BIM workflows for specification premiums. |
| Cross-Laminated Timber Certification Expansion | Opens German and Austrian municipal housing tenders through structural grading standard maturity. |
| Regional Fabrication Scale Buildout | Spans multiple climate zones to capture insulated panel demand from design-build contractor consolidation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across plant managers at concrete batching facilities, procurement leads at tier-one contractors, technical R&D directors at admixture suppliers, and sustainability officers at institutional asset holders. Bottom-up volume modeling triangulated against top-down regulatory mandate impact assessments using EPD databases, EU Green Deal implementation trackers, and California Air Resources Board procurement disclosures.
Segment-level modeling applied material type, application, manufacturing stage, and end-user procurement authority dimensions across the projection horizon. CAGRs derived from regression analysis against embodied carbon threshold tightening schedules and public infrastructure spending patterns. Forecast inputs incorporated prefabrication workflow adoption curves and structural engineer retraining pipeline data.
Regulatory divergence between carbon accounting methodologies, biogenic feedstock climate volatility, and performance certification protocol gaps are the dominant revision risks to material substitution timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Porcelain Tiles Market