
 Urethane Concrete Sealer Market | 2026-2036
Urethane Concrete Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
Urethane Concrete Sealer Market Outlook
Asset-light leasing models for application equipment is tilting competitive dynamics toward service-integrated distributors. Sika AG leverages its global formulation network to sustain specification-grade positioning across commercial projects. BASF SE anchors its presence through captive supply of aliphatic isocyanate precursors. RPM International Inc. competes via multi-brand channel control spanning professional contractors and retail hardware.
Urethane concrete sealers comprise aliphatic polyurethane dispersions that cure into abrasion-resistant, UV-stable films typically applied at 2-4 mils dry thickness over prepared concrete substrates, primarily protecting industrial and commercial floors from chemical attack, moisture intrusion, and mechanical wear. Water-based formulations now lead volume as VOC compliance tightens, while hybrid systems capture margin pools where rapid return-to-service drives specification. Solvent-based grades retain dominance in heavy-industrial corrosion protection despite regulatory pressure, and infrastructure application growth outpaces residential channels where epoxy alternatives dominate.
EPA VOC regulations, OSHA slip-resistance standards, and ISO 9001 quality certification frameworks collectively shape product development cycles and market access barriers for urethane sealer manufacturers. The EU REACH chemical registration regime and California Air Resources Board limits further constrain formulation flexibility for cross-border suppliers. Stakeholders must monitor regulatory divergence between federal and state-level VOC thresholds when allocating R&D budgets across product platforms.
Market Dynamics
EPA VOC emission standards for architectural coatings are compressing formulation flexibility while warehouse operators demand faster return-to-service performance, creating a structural tension between compliance velocity and application efficiency.
Growth Catalysts
- California Air Resources Board limits:Water-based urethane formulations gain specification share as contractors face mandatory VOC thresholds on commercial projects.
- Logistics facility refurbishment cycles:E-commerce fulfillment centers drive specification-grade sealer volumes for polished concrete durability.
- Aliphatic isocyanate precursor availability:Captive supply chains from specialty chemical producers stabilize raw material access for high-performance grades.
Market Restraints
- Raw material concentration:Aliphatic diisocyanate production clusters in Germany and China, exposing formulators to transatlantic shipping volatility.
- Epoxy substitution in residential:DIY homeowners select lower-cost epoxy kits for garage floors, capping urethane penetration in consumer channels.
- REACH registration burden:EU chemical compliance costs block mid-tier manufacturers from European commercial specification pools.
Strategic Opportunities
- India industrial corridor buildout:Dedicated freight corridors and manufacturing zones create greenfield demand for heavy-traffic floor protection.
- Hybrid system convergence:Water-borne urethane-acrylic hybrids capture margin pools where rapid cure meets VOC compliance.
- Equipment-as-a-service distribution:Leasing models for spray application systems embed formulators deeper in contractor workflows.
Industry Challenges
- Applicator certification timelines:OSHA slip-resistance testing protocols extend project onboarding for new contractor networks.
- Legacy substrate compatibility:Existing epoxy-coated floors require mechanical profiling before urethane overlay, adding labor cost uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urethane Concrete Sealer Market |
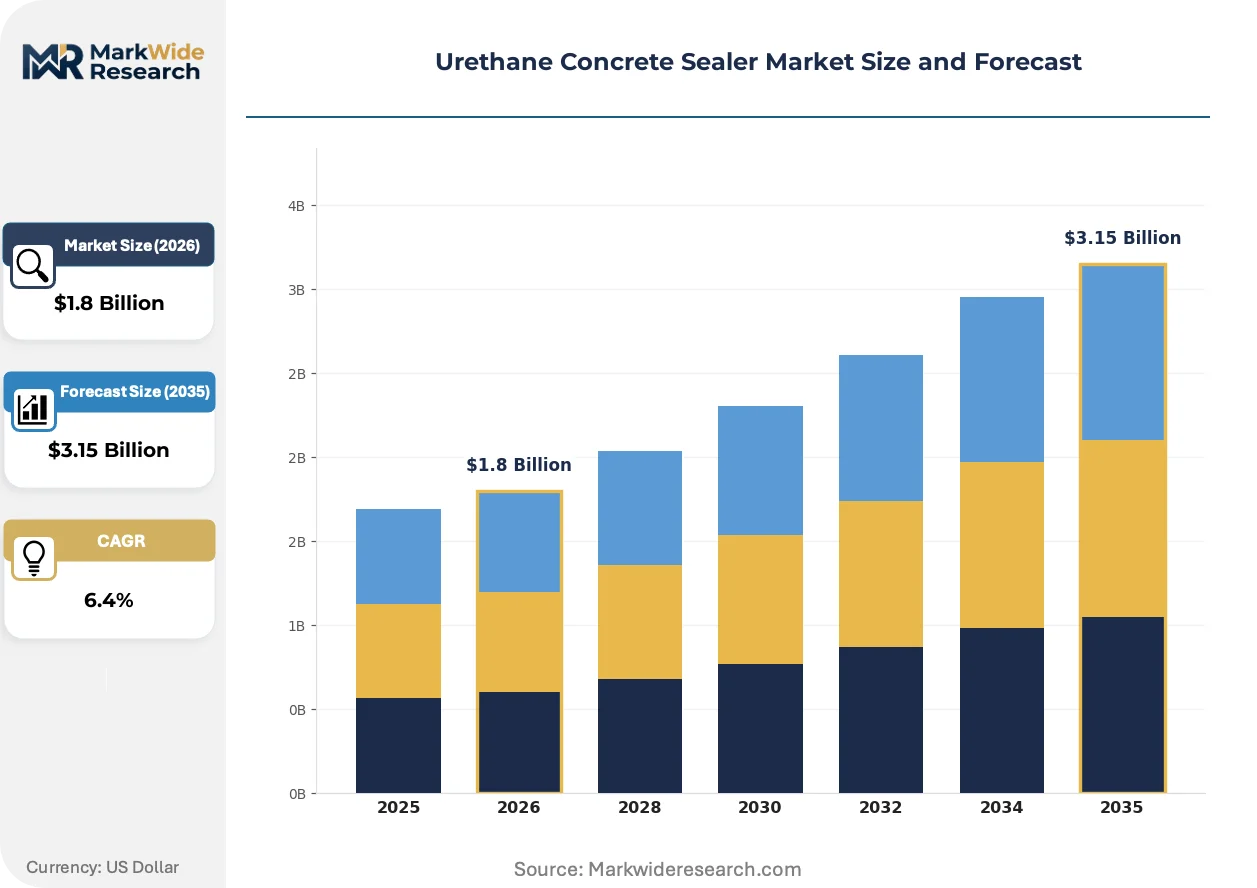
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hybrid, Epoxy Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Homeowners, Builders, Facility Managers Distribution Channel: Online Retail, Direct Sales, Distributors, Hardware Stores |
| Companies Covered | Sika AG, BASF SE, RPM International Inc., Sherwin-Williams Company, PPG Industries, Inc., Evonik Industries AG, Mapei S.p.A., LATICRETE International, Inc., Prosoco, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urethane Concrete Sealer Market Strategic Shifts
Formulation chemistry and application logistics are converging as regulatory windows narrow and facility downtime costs escalate, reshaping how sealer value is captured across the supply chain.
Moisture-cure polyurethane technology is digitizing specification workflows by embedding cure-time predictability into project management software. Large-scale distribution center operators now mandate digital cure tracking for warranty validation. The technology is digitizing contractor bidding processes by compressing schedule risk premiums.
EPA architectural coating VOC rules are forcing reformulation investment toward exempt-solvent and water-borne platforms. Manufacturers face split R&D allocation between federal compliance and state-level thresholds that diverge in California and the Northeast. Water-based systems are capturing specification share fastest in commercial retail and healthcare verticals.
Facility managers now bundle floor protection into comprehensive maintenance contracts rather than discrete capital projects. National retail chains centralize procurement through approved contractor networks, displacing traditional distributor relationships. This concentration is most visible in United States big-box retail and grocery distribution networks.
Urethane Concrete Sealer Market Segmentation
Urethane concrete sealer purchasing decisions split across formulation chemistry, project scale, and procurement authority. Specification-grade buyers prioritize VOC compliance and cure predictability over unit cost, while residential channels trade performance for accessibility.
Product Type:
Formulation chemistry determines regulatory compliance trajectory and performance ceiling for substrate protection.
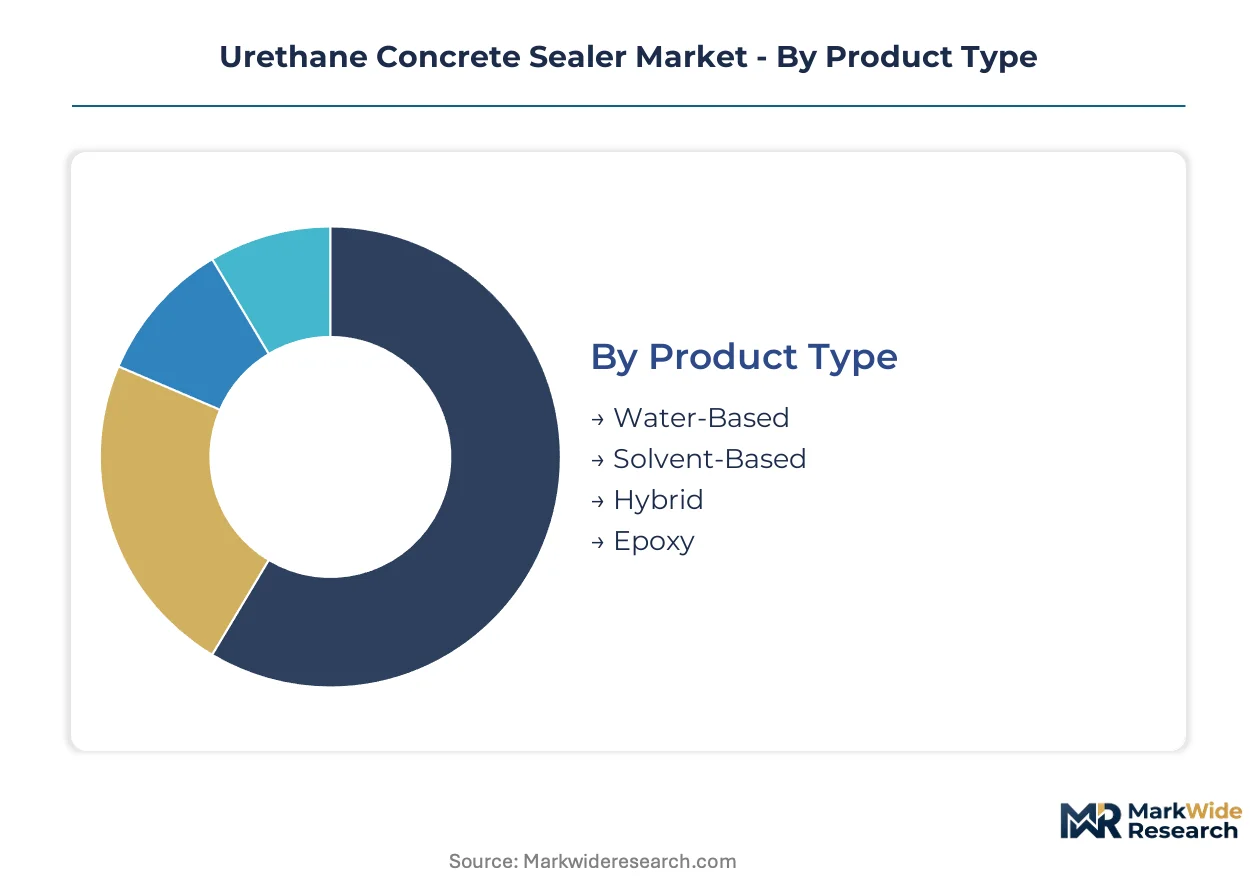
- Water-Based:Polyurethane dispersions in aqueous carriers achieve sub-100 g/L VOC content for EPA architectural coating compliance. Demand concentrates in California retail construction and Northeast healthcare facilities where CARB and state-level thresholds exceed federal stringency.
- Solvent-Based:Aliphatic polyurethane solutions in aromatic or aliphatic hydrocarbon carriers deliver superior chemical resistance and film hardness for heavy-industrial exposure. Specification persists in US Gulf Coast petrochemical facilities and German manufacturing plants where corrosion protection overrides emission concerns.
- Hybrid:Water-borne urethane-acrylic copolymers balance rapid cure with compliance flexibility.
- Epoxy:Epoxy-urethane blends occupy price-sensitive specification niches.
Water-based formulations command the established base in commercial specification. The steepest expansion runs through hybrid systems capturing margin pools where rapid return-to-service meets tightening VOC windows.
Application:
Project scale and traffic intensity dictate film thickness requirements, warranty terms, and contractor qualification thresholds.
- Commercial:Polished concrete protection in retail, healthcare, and institutional buildings demands UV-stable, abrasion-resistant finishes at 2-4 mils dry thickness. US big-box distribution networks and Indian shopping mall developments drive specification-grade volume through national contractor procurement programs.
- Industrial:Manufacturing floors, warehouses, and logistics centers require chemical-resistant, high-build systems for forklift traffic and spill exposure. E-commerce fulfillment center refurbishment cycles in the United States and greenfield industrial corridor buildouts in India concentrate demand for heavy-traffic formulations.
- Residential:Garage floors and basements favor lower-cost alternatives.
- Infrastructure:Bridge decks, parking structures, and transit facilities specify urethane for carbonation protection.
Industrial application anchors revenue concentration through facility refurbishment cycles. Commercial application gains share fastest as retail chains centralize floor maintenance procurement.
End User:
Procurement authority and technical sophistication determine specification control and price elasticity across the demand base.
- Contractors:Professional applicators control specification in commercial and industrial channels through warranty-backed installation networks. US national flooring contractors and German specialist applicators drive demand for certified-compatible product systems with documented cure tracking.
- Facility Managers:Corporate maintenance departments bundle floor protection into comprehensive service contracts. National retail and grocery distribution networks in the United States displace traditional distributor relationships through centralized procurement of approved contractor networks.
- Builders:New construction developers specify sealer as part of concrete finishing packages.
- Homeowners:DIY purchasers select consumer-packaged products through retail hardware.
Contractors retain specification influence in project-based industrial work. Facility managers are capturing procurement authority fastest as maintenance contracts replace discrete capital projects.
Distribution Channel:
Channel structure determines formulator access to specification workflows and inventory carrying economics.
- Distributors:Specialty chemical distributors stock specification-grade formulations and provide applicator training, warranty support, and project-based logistics. US regional flooring supply houses and German construction chemical distributors embed formulators in commercial contractor workflows.
- Direct Sales:Manufacturer-direct relationships serve national account customers with volume commitments and custom formulation support. Large US retail chains and Indian industrial developers negotiate direct supply agreements for multi-site floor protection programs.
- Online Retail:E-commerce platforms serve consumer and light commercial purchasers.
- Hardware Stores:Big-box retailers stock DIY-grade products for residential garage and basement applications.
Distributor relationships command the established base in specification-grade commercial work. Direct sales channels are expanding fastest as national accounts consolidate procurement and demand embedded service capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC emission standards for architectural coatings are compressing formulation flexibility while warehouse operators demand faster return-to-service performance. California Air Resources Board limits and REACH registration requirements in Europe are forcing parallel compliance investments across major markets.
United States
E-commerce fulfillment center refurbishment cycles and big-box retail distribution networks drive specification-grade sealer volumes for polished concrete durability. EPA architectural coating VOC rules and OSHA slip-resistance standards shape product development cycles and contractor qualification thresholds. The US Gulf Coast petrochemical corridor and Midwest logistics hubs concentrate heavy-industrial demand where corrosion protection overrides emission concerns.
Germany
Aliphatic diisocyanate production clusters and specialty chemical precursor availability anchor European supply chain stability for high-performance grades. EU REACH chemical registration regime and CE marking requirements constrain formulation flexibility for cross-border suppliers. The Rhine-Ruhr industrial belt and Bavarian manufacturing zones sustain specification-grade demand for chemical-resistant floor protection in automotive and machinery plants.
China
Dedicated freight corridors and manufacturing zone buildouts create greenfield demand for heavy-traffic floor protection in logistics and industrial facilities. GB standards and MIIT industrial policy frameworks govern construction chemical quality certification and environmental compliance. The Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate both production capacity and end-use specification for abrasion-resistant coatings.
India
Dedicated freight corridors and industrial corridor buildouts under the PLI scheme generate specification demand for warehouse and logistics facility floor protection. BIS certification requirements and state-level environmental clearances shape product registration timelines for construction chemical suppliers. The Delhi-Mumbai Industrial Corridor and Gujarat manufacturing zones anchor greenfield industrial construction where polished concrete protection commands premium positioning.
United Arab Emirates
Mega-project construction and logistics hub development in Dubai South and Abu Dhabi KIZAD drive demand for UV-stable, abrasion-resistant floor finishes in commercial and industrial facilities. MOHAP product registration and Emirates Authority for Standardization and Metrology specifications govern construction chemical import and application standards. Dubai's Jebel Ali logistics corridor and Abu Dhabi's industrial cities concentrate specification-grade procurement through centralized contractor networks.
Urethane Concrete Sealer Market Competitive Environment
Channel-controlling players compete with product-specialist players across differentiated procurement workflows. The vendor base clusters around three strategic archetypes: formulation-integrated chemical conglomerates, multi-brand coating portfolios, and specification-focused construction chemical specialists. Dominant competitive moves include captive supply chain integration for aliphatic isocyanate precursors and equipment-as-a-service distribution models that embed formulators in contractor workflows.
Within the formulation-integrated tier, Sika AG exemplifies global specification-grade positioning through construction chemical distribution networks, while BASF SE anchors presence through in-house production of specialty chemical precursors. RPM International Inc. occupies a position spanning professional contractor and retail hardware channels through multi-brand portfolio control. These three entities represent the dominant competitive archetypes: specification-integrated distributor, upstream-integrated chemical supplier, and channel-diversified brand house.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| RPM International Inc. |
| Sherwin-Williams Company |
| PPG Industries, Inc. |
| Evonik Industries AG |
| Mapei S.p.A. |
| LATICRETE International, Inc. |
| Prosoco, Inc. |
| Others |
Value Chain & Pricing Dynamics
Delhi-Mumbai Industrial Corridor freight costs compress margins for formulators shipping aliphatic isocyanate precursors from Germany and China, concentrating pricing power among captive producers while forcing tiered cost pass-through to facility managers and national retail procurement networks.
Pricing Analysis
Certification level (ISO 9001/REACH-compliant) creates the primary spread between specification-grade and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, cure-time predictability, and warranty-backed installation networks. Cost compression in water-based tiers is intensifying because EPA VOC compliance investments outpace volume scaling. Facility managers at national retail chains exhibit lowest price sensitivity due to bundled maintenance contracts, while DIY homeowners in residential channels drive economy-tier volume.
Supply Chain Analysis
Extended payment terms from specialty chemical distributors to contractor networks stabilize working capital for applicator certification investments. Aliphatic diisocyanate production clusters in Germany, China, and the United States. Raw material flows draw from petrochemical feedstocks, aliphatic hydrocarbon carriers, and polyurethane dispersion polymers. Single-source vulnerability runs through transatlantic shipping lanes for European precursor imports. Distribution runs through specialty chemical distributors embedding formulators in commercial contractor workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through national retail chains centralizing floor maintenance procurement, fragmenting traditional distributor relationships and compressing margin capture for non-integrated formulators.
For Market Incumbents: Pre-empt epoxy substitution in residential channels by accelerating water-borne hybrid R&D investment ahead of EPA VOC threshold tightening. Defend specification-grade positioning through captive aliphatic isocyanate supply and embedded equipment-as-a-service distribution. Channel control remains the priority lever against emerging construction chemical specialists. For New Entrants and Emerging Players: Establish a beachhead in India's industrial corridor buildout where BIS certification timelines block mid-tier incumbents. Target greenfield logistics facility procurement in Gujarat and Maharashtra manufacturing zones. Lead with rapid-cure hybrid formulations and localized applicator training partnerships to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation-integrated players with upstream precursor control over pure-play distributors. Long-term viability rests on regulatory compliance velocity and specification-grade certification density. Acquisition target archetype: regional construction chemical specialists with captive applicator networks. The signal to watch is CARB threshold divergence from federal EPA standards accelerating R&D fragmentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aliphatic Isocyanates | Captive precursor supply insulates Sika and BASF from transatlantic shipping volatility. |
| Water-Borne Hybrid Formulation Launch | EPA VOC compliance acceleration captures specification share in California retail construction. |
| Equipment-as-a-Service Distribution | Leasing models embed formulators in contractor workflows across US big-box retail networks. |
| Applicator Certification Network Expansion | OSHA slip-resistance protocol mastery accelerates project onboarding for national accounts. |
| India Industrial Corridor Joint Venture | PLI scheme-aligned partnerships secure greenfield logistics facility specifications in Gujarat. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at logistics facility operators, distribution channel partners, and technical R&D directors and secondary validation through customs/trade data, ACC industry reports, and SEC 10-K filings anchors the qualitative findings. Bottom-up volume modeling triangulates against top-down market sizing across formulation chemistry, application scale, and procurement authority segments.
Calibration against historical volume trajectories and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation type, project scale tier, end-use industry vertical, and regional regulatory cluster. CAGRs derive from regression analysis of correlated construction spending and refurbishment cycle data. Key inputs include e-commerce fulfillment center buildout rates and EPA VOC threshold enforcement intensity.
Stress conditions across raw material price volatility, transatlantic shipping disruption, and regulatory threshold acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance velocity and facility manager procurement centralization. Macroeconomic contraction, regulatory divergence, or moisture-cure technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Geofoam Market