
 GCC Construction Market | 2026-2036
GCC Construction Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Construction Market Insights
The Emirates Green Building Council's escalating technical standards is decoupling conventional concrete-intensive methods from premium project pipelines across Dubai and Abu Dhabi. Saudi Binladin Group leverages its decades-long mosque and infrastructure legacy to sustain dominance in Makkah-region developments. ALEC Engineering and Contracting anchors its portfolio through airport and aviation specialization, while Nesma & Partners Contracting differentiates via marine and coastal infrastructure expertise spanning Red Sea giga-projects.
GCC construction encompasses the planning, design, execution, and maintenance of built assets across residential, commercial, infrastructure, and industrial categories, utilizing concrete, steel, wood, and composite material systems engineered to withstand extreme desert thermal cycling and seismic loads. Infrastructure project types command the deepest public budgets, with road-rail-airport networks absorbing sovereign wealth deployment across Saudi Arabia and the UAE. Residential construction maintains volume leadership but faces margin compression as government-subsidized housing programs cap developer returns, while commercial segments concentrate in Dubai's free zone clusters where speculative office supply encounters tenant-quality upgrading pressures.
Saudi Building Code enforcement and Bahrain's Green Building Regulations tighten energy-efficiency thresholds for glazing, insulation, and HVAC integration, compelling contractors to recertify supply chains or forfeit eligibility on ministry tenders. The UAE's MOHAP safety protocols and Qatar's QSAS sustainability standards add compliance layers that favor contractors with captive engineering capabilities over pure-build subcontractors. Stakeholders must weigh sovereign project pipeline announcements against actual budget release timelines, as commitment-to-execution gaps define working capital risk across the Gulf contractor landscape.
Market Dynamics
The Saudi Building Code enforcement is compressing conventional construction methods while sovereign giga-project pipelines pull modular and prefabricated systems into mainstream adoption across the Gulf.
Growth Catalysts
- NEOM giga-project corridor:Saudi Arabia's linear city development is normalizing factory-built volumetric modules for residential and hospitality assets, creating pull-through demand for offsite manufacturing capabilities.
- Emirates Green Building Council tiered certification:Pearl rating upgrades are mandating high-performance glazing and thermal breaks, redirecting material specifications toward low-carbon concrete and recycled steel suppliers.
- Modular building techniques:Accelerated project timelines on Red Sea coastal developments are proving repeatable design-to-delivery cycles that compress traditional on-site labor dependencies.
Market Restraints
- Steel reinforcement input volatility:Rebar and structural steel pricing swings tied to Turkish and Chinese export volumes are compressing fixed-price contract margins for mid-tier contractors.
- Specialized engineering labor concentration:Gulf nationals with BIM and modular coordination expertise cluster in Riyadh and Dubai, leaving secondary cities dependent on expatriate talent with visa renewal friction.
- SFDA material import protocols:Saudi Arabia's construction product conformity assessments add 8-14 week clearance timelines for European HVAC and glazing systems, delaying project mobilization.
Strategic Opportunities
- Bahrain Green Building Regulations:The island kingdom's accelerated energy-efficiency mandates for new commercial stock create first-mover positioning for contractors with Pearl/Green Star dual certification.
- Aviation infrastructure convergence:Airport expansion pipelines in Oman and Kuwait favor contractors with airside security clearance and MEP-structural integration capabilities.
- Desert thermal cycling materials:Polymer-modified concrete and phase-change insulation systems engineered for 50°C ambient swings represent uncaptured specification share in industrial and data center verticals.
Industry Challenges
- BIM-to-field coordination gaps:Design-intent models clash with as-built tolerances on fast-track giga-projects, forcing rework cycles that erode target margins.
- Green certification timeline compression:Pearl and LEED documentation requirements now overlap with construction schedules, demanding dedicated sustainability officers that smaller contractors cannot staff.
- Cross-border payment settlement:UAE-dirham and Saudi-riyal contract denomination mismatches expose contractors to working capital strain when parent entities domicile in third jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Construction Market |
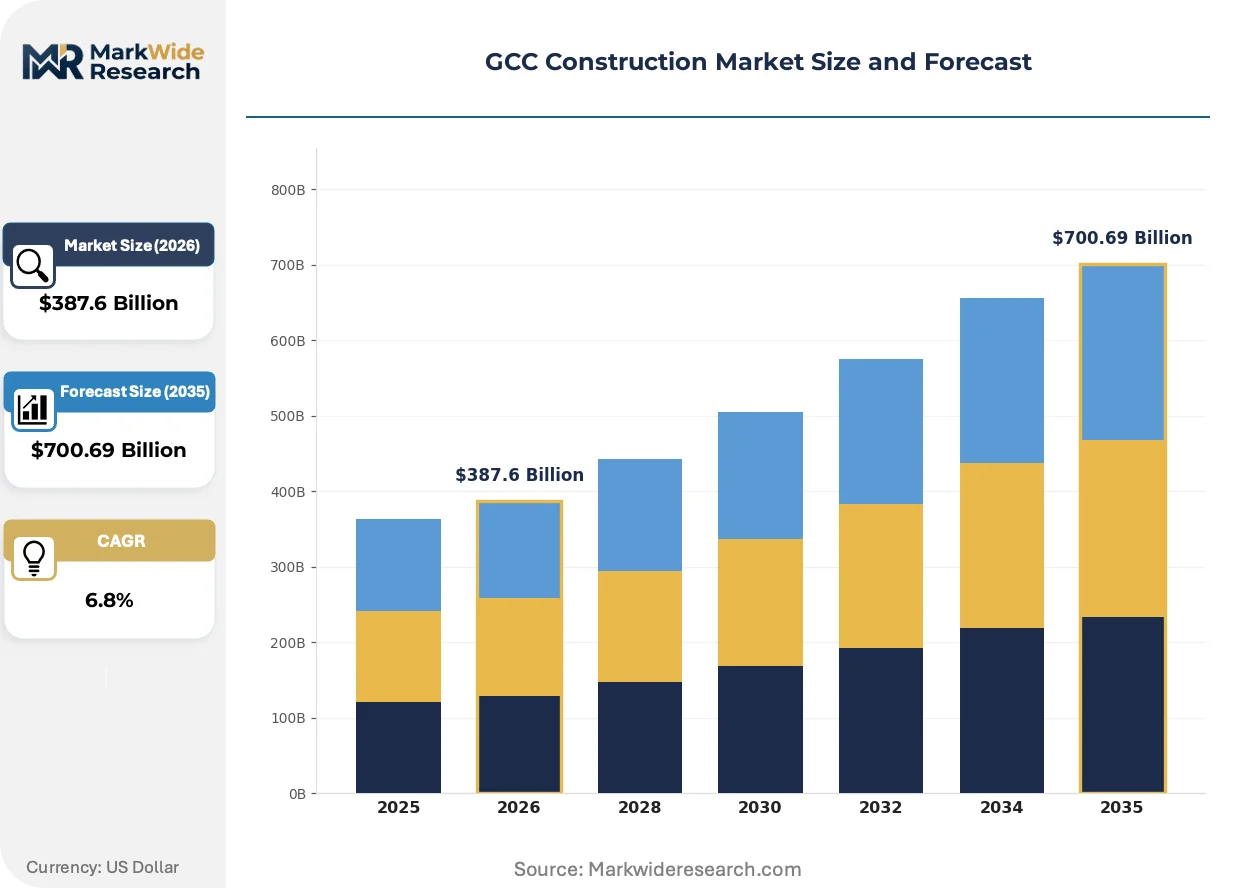
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Infrastructure, Industrial Material Type: Concrete, Steel, Wood, Composites Construction Phase: Planning, Design, Execution, Maintenance Client Type: Private Developers, Government, NGOs, Contractors |
| Companies Covered | Nesma & Partners Contracting, Albawani Group, ALEC Engineering and Contracting, Arabian Construction Company, ASGC Construction, Saudi Binladin Group, Al Naboodah Construction Group, Almabani General Contractors, China State Construction Engineering Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Construction Market Trends and Innovations
Digital fabrication and regulatory ratcheting are compressing traditional construction cycles while procurement models fragment toward performance-guaranteed delivery structures across the Gulf.
3D concrete printing is decentralizing structural component production by enabling on-site casting of complex geometries without formwork. Qiddiya entertainment district contractors are piloting gantry-based systems for themed facade elements, compressing specialized precast supplier dependencies. This technology is decentralizing supply chain control from centralized precast yards to project-adjacent mobile production cells.
MOHAP safety protocols in the UAE now mandate real-time worker location tracking and heat-stress monitoring on sites above 10,000 square meters. Contractors must integrate wearable IoT networks with project management platforms or face tender disqualification. Infrastructure and high-rise segments absorb the highest compliance costs, driving consolidation toward contractors with captive digital engineering teams.
Asset owners across Dubai's free zones are unbundling design-build contracts into separate design-consultancy and performance-guaranteed construction agreements. This fragmentation shifts risk retention toward contractors willing to underwrite energy and maintenance outcomes. Saudi Arabia's PIF-backed developments exhibit the most aggressive outcome-based contracting, with hospitality and healthcare assets leading the transition.
GCC Construction Market Segmentation
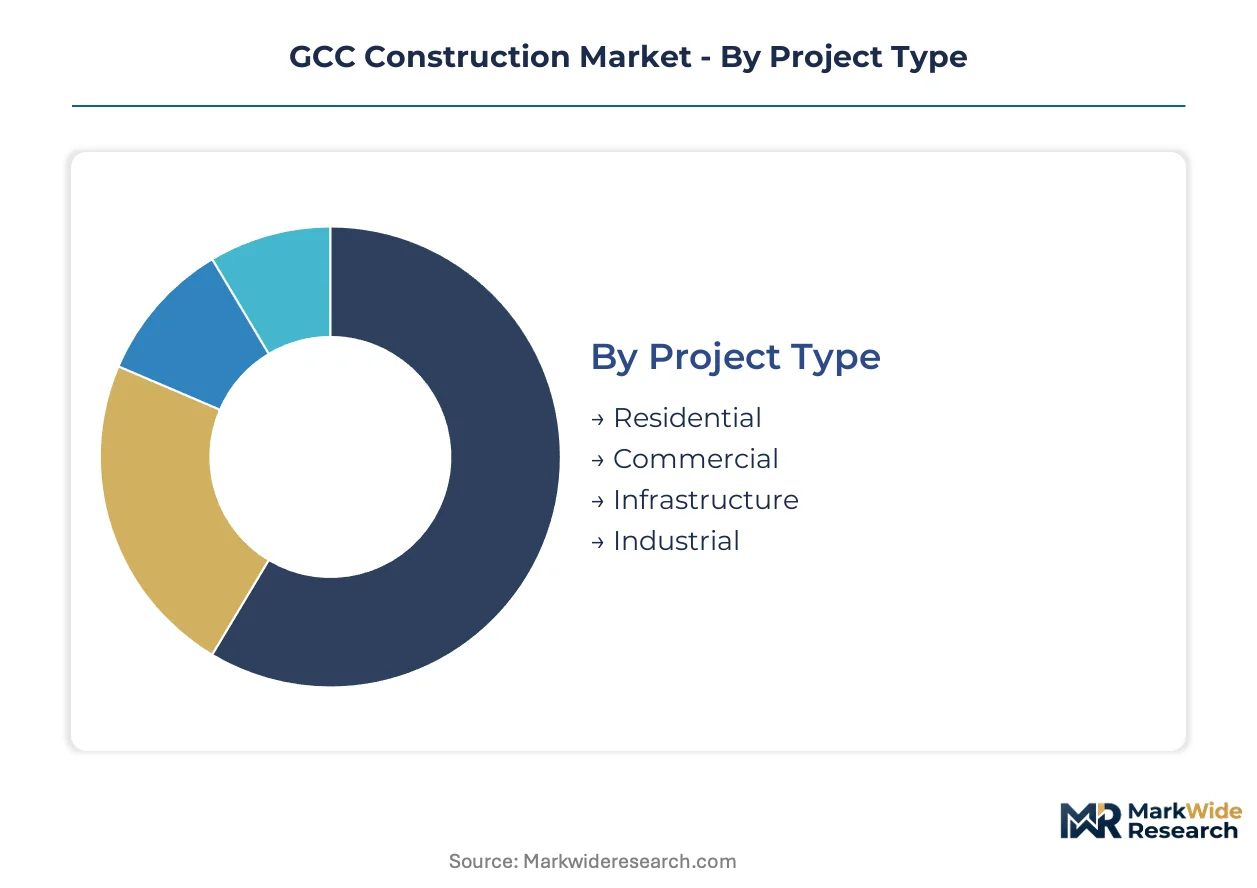
GCC construction segmentation reveals how capital deployment, regulatory compliance, and sovereign project pipelines reshape contractor specialization. Material specifications and client procurement models fragment competitive positioning across the Gulf's giga-project corridor.
Project Type:
Capital intensity peaks in infrastructure and industrial verticals, where sovereign balance sheets absorb decade-long construction cycles and specialized engineering requirements.
- Infrastructure:Road-rail-airport networks command the deepest public budgets across Saudi Arabia and the UAE. Riyadh's metro expansion and Dubai's Al Maktoum International absorb sovereign wealth deployment with 15-20 year concession structures.
- Residential:Volume leadership masks margin compression as Saudi government-subsidized housing programs cap developer returns. NEOM's linear city modules and Red Sea coastal villas normalize factory-built delivery methods.
- Commercial:Dubai's free zone clusters concentrate speculative office supply where tenant-quality upgrading pressures dominate. Abu Dhabi's financial district assets face Pearl rating mandates that elevate glazing and MEP specifications.
- Industrial:Data center and logistics verticals in Saudi Arabia's giga-project zones absorb polymer-modified concrete systems engineered for 50°C thermal cycling.
Infrastructure absorbs the bulk of installed capacity; residential is expanding most quickly through modular prefabrication adoption.
Material Type:
Cost tier stratification separates commodity bulk materials from performance-graded systems required by green building codes.
- Concrete:Low-carbon formulations with supplementary cementitious materials dominate Saudi Building Code compliance. NEOM contractors specify 50% clinker reduction targets for structural elements.
- Steel:Recycled content mandates under Emirates Green Building Council Pearl ratings redirect procurement toward electric-arc furnace suppliers. Rebar pricing volatility tied to Turkish export volumes compresses fixed-price contract margins.
- Wood:Cross-laminated timber gains traction in Bahrain's commercial mid-rise segment where humidity-controlled storage infrastructure remains limited.
- Composites:Glass-reinforced polymer rebar and facade cladding systems penetrate coastal infrastructure exposed to Red Sea salt corrosion.
Concrete retains dominant volume share; composites are climbing the fastest on durability specifications for marine environments.
Construction Phase:
Margin concentration shifts toward front-end planning and back-end maintenance as execution commoditizes under competitive tendering.
- Planning:Feasibility and master planning services cluster around Riyadh and Dubai advisory firms with sovereign relationship depth. Saudi PIF-backed developments demand integrated financing-technical proposals.
- Design:BIM-enabled architectural and engineering consultancies capture premium fees on giga-projects where design-intent models must coordinate with modular manufacturing tolerances.
- Execution:On-site construction margins compress as Saudi and UAE contractors consolidate around captive fabrication capabilities and direct labor forces.
- Maintenance:Asset lifecycle contracts expand in Dubai's mature commercial stock where performance-guaranteed energy outcomes shift risk retention toward facility operators.
Execution absorbs the bulk of installed capacity; maintenance is gaining share fastest through outcome-based contracting adoption.
Client Type:
Procurement authority and payment security differentiate client segments, with sovereign entities dominating contract award volumes.
- Government:Saudi Arabia's Ministry of Housing and UAE's infrastructure ministries release tender pipelines with 18-24 month budget commitment horizons. SFDA material conformity protocols add clearance friction for European HVAC imports.
- Private Developers:Dubai's free zone master developers and Saudi mixed-use project sponsors face financing access constraints that compress project mobilization timelines.
- Contractors:Tier-one Saudi Binladin Group and ALEC Engineering self-perform on balance-sheet developments, blurring traditional client-contractor boundaries.
- NGOs:Limited procurement footprint concentrated in Qatar's World Cup legacy foundation projects and UAE humanitarian infrastructure.
Government absorbs the bulk of installed capacity; private developers are recovering fastest on Dubai commercial restart activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's giga-project corridor dominates GCC construction deployment, with sovereign wealth pipelines absorbing the bulk of regional capital allocation across the Gulf's six member states.
Saudi Arabia
NEOM's linear city and Qiddiya entertainment district accelerate modular fabrication demand. Saudi Building Code enforcement compels low-carbon concrete specifications on ministry tenders. The Red Sea coastal zone concentrates marine-capable contractors for hospitality and infrastructure assets.
United Arab Emirates
Dubai's free zone commercial stock and Abu Dhabi's financial district sustain premium project pipelines. Emirates Green Building Council Pearl ratings mandate high-performance glazing and thermal break systems. Al Maktoum International airport expansion anchors aviation-specialized contractor clusters.
Qatar
World Cup legacy infrastructure transitions toward hospitality and healthcare asset maintenance. QSAS sustainability standards layer compliance requirements onto commercial developments. Doha's West Bay district concentrates high-rise residential and office construction activity.
Kuwait
Sovereign housing programs and airport modernization sustain public contract volumes. Central Bank financing directives influence developer liquidity for mixed-use schemes. The Shuwaikh industrial area clusters contractors serving oil and gas adjacent construction.
Oman
Aviation infrastructure expansion at Muscat International favors airside-cleared contractors. Port and logistics zone developments along the Al Batinah coast absorb marine construction capacity. Special Economic Zone incentives attract cross-border contractor establishment.
GCC Construction Market Competitive Landscape
The competitive structure tilts toward sovereign-backed tier-one contractors with captive fabrication capabilities. Saudi Binladin Group and ALEC Engineering anchor the premium tier through decades-long infrastructure legacies and aviation specialization respectively. Mid-tier players face margin compression on fixed-price ministry tenders where material cost volatility erodes returns. Consolidation pressures intensify as SFDA import protocols and green certification timelines demand compliance investments beyond smaller balance sheets. Strategic moves center on modular manufacturing partnerships and captive engineering team acquisition.
Within the heritage-contractor archetype, Saudi Binladin Group occupies a position reflecting decades of mosque and infrastructure delivery across the Makkah region. ALEC Engineering and Contracting exemplifies the aviation-specialist tier with airport and airside project concentration. Nesma & Partners Contracting represents marine-capable positioning through Red Sea coastal and offshore infrastructure exposure. These three anchors illustrate how geographic legacy and technical specialization stratify competitive access to sovereign giga-project pipelines.
| Leading Market Players |
|---|
| Nesma & Partners Contracting |
| Albawani Group |
| ALEC Engineering and Contracting |
| Arabian Construction Company |
| ASGC Construction |
| Saudi Binladin Group |
| Al Naboodah Construction Group |
| Almabani General Contractors |
| China State Construction Engineering Corporation |
| Others |
Pricing and Supply Chain Analysis
Emirates Green Building Council Pearl rating mandates gate qualified supply access and premium-tier pricing power across Dubai and Abu Dhabi developments. Contractors lacking dual-certification capabilities face exclusion from ministry tender pipelines while certified specialists command performance-guaranteed contract premiums.
Pricing Analysis
Outcome-based pricing anchors contract structures where contractors underwrite energy performance and maintenance outcomes on hospitality and healthcare assets. Pricing stratifies across Pearl-certified premium tiers, standard code-compliant mid-market, and economy-grade conventional delivery. Cost compression in standard-tier residential runs through Saudi government-subsidized housing program caps. Private developers in Dubai's free zones exhibit highest price sensitivity; sovereign PIF-backed entities absorb premium-tier markups with least negotiation.
Supply Chain Analysis
Material returns and refurbishment flows remain underdeveloped across the Gulf, with demolition waste largely landfilled rather than reprocessed into aggregate feedstock. Supply concentrates in China, Turkey, and India for structural steel and rebar; low-carbon cementitious materials draw from UAE and Saudi domestic production. SFDA import protocols and Turkish export volatility constitute primary supply chain risks. Distribution runs through project-adjacent fabrication yards serving NEOM and Red Sea coastal corridors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering labor scarcity props pricing power for contractors with captive BIM and modular coordination teams. Capacity bottlenecks in certified supply chains sustain margin premiums for early compliance investors.
For Market Incumbents: Hedge against Turkish rebar volatility through backward integration into captive steel fabrication or long-term offtake agreements with electric-arc furnace suppliers. Reinforce position in aviation and marine segments where airside clearance and Red Sea coastal expertise create defensible moats. Prioritize Saudi Building Code recertification investments to maintain ministry tender eligibility.
For New Entrants and Emerging Players: Enter via Bahrain's accelerated green building mandate window where Pearl-Green Star dual certification requirements outpace established contractor compliance rates. Target Oman's aviation infrastructure expansion and Kuwait's airport modernization where airside-cleared capacity remains constrained. Pursue modular manufacturing partnerships as the primary go-to-market angle rather than pure construction bidding.
For Investors and Strategic Acquirers: PIF project pipeline acceleration is the leading indicator that sovereign capital deployment will sustain contractor valuations across the analysis window. Acquisition targets should emphasize marine-capable specialists with Red Sea coastal exposure and captive engineering teams. Monitor SFDA import clearance timeline reductions as the signal for European HVAC and glazing system supplier market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Manufacturing Partnership | NEOM's volumetric module demand pulls factory-built capabilities into mainstream Gulf adoption. |
| Green Certification Investment | Pearl and Saudi Building Code compliance gates access to premium sovereign tender pipelines. |
| Aviation Infrastructure Specialization | Al Maktoum International and Muscat expansions concentrate contracts with airside-cleared contractors. |
| Backward Integration into Steel | Electric-arc furnace sourcing hedges Turkish rebar volatility on fixed-price ministry contracts. |
| Marine Capability Acquisition | Red Sea coastal and offshore expertise differentiates access to giga-project hospitality assets. |
Research Methodology
Document review covered Saudi Building Code enforcement circulars, Emirates Green Building Council certification databases, and PIF project disclosure filings, complemented by interviews with project directors at tier-one contractors, ministry procurement officers, and modular manufacturing specialists. Secondary validation drew from customs trade data, construction tender aggregators, and sovereign wealth fund capital deployment trackers. Bottom-up project pipeline enumeration and top-down macroeconomic scenario modeling were triangulated to ground regional forecasts.
Segmentation outputs reflect project-type, material-grade, and client-archetype dimensions modeled across the projection horizon. CAGRs derive from installed capacity build-up curves tied to announced giga-project mobilization timelines and historical budget commitment-to-execution conversion rates. Forecast inputs incorporate thermal cycling material specifications and BIM adoption curves as technology penetration variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sovereign budget release delays or SFDA protocol extensions. Forecasts reflect documented assumptions regarding PIF capital deployment velocity and modular manufacturing scale-up rates. Practitioners should monitor ministry tender pipeline announcement-to-award conversion timelines and European HVAC import clearance durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Middle East Data Center Construction Market
Building Construction
El Salvador Construction Market
Building Construction
UK Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Kuwait Construction Market
Building Construction
UAE Facade Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Brazil Construction Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Turkey Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Middle East Building Construction Market
Building Construction
Latin America Construction Market
Building Construction
GCC Prefabricated Housing Market