
 Sawn Timber Market | 2026-2036
Sawn Timber Market Size, Share, and Industry Trends Forecast 2026-2036
Sawn Timber Market Analytics
The EU Timber Regulation is decoupling European market access from uncertified tropical and boreal supply lines, forcing importers to rebuild traceability systems. West Fraser Timber Co Ltd leverages its vertically integrated British Columbia coastal operations to sustain FSC-certified throughput into EU ports. Stora Enso Oyj anchors Nordic softwood supply through controlled chain-of-custody documentation from forest to mill. Weyerhaeuser Company competes on scale, extending its Southern Yellow Pine distribution network across North American homebuilding corridors.
Sawn timber consists of logs processed through longitudinal cutting into dimensional lumber with specified moisture content, grain orientation, and structural grade for load-bearing or finish applications. Softwood dominates volume flows into North American platform framing, while engineered wood and laminated veneer lumber capture margin pools in mid-rise commercial construction where fire-rated spans exceed solid-sawn capacity. Hardwood supply concentrates in furniture and flooring segments where contractors and furniture manufacturers pay premiums for clear-grade appearance specifications.
The US Lacey Act, EU Timber Regulation, and Canada's SFI standard collectively enforce chain-of-custody documentation that shapes procurement decisions across the contractor and retailer tiers. Japan's METI building codes and Australia's NCC bushfire construction standards further segment export-grade production by treatment and density requirements. Stakeholders must monitor divergence between EU EUDR geolocation mandates and emerging US state-level carbon accounting rules that will redefine which mill systems retain market access without retrofit.
Market Dynamics
The EU Timber Regulation is forcing importers to rebuild traceability systems, decoupling European market access from uncertified tropical and boreal supply lines and redirecting capital toward FSC-certified mill networks.
Growth Catalysts
- EU Deforestation Regulation geolocation mandates:Contractors in Germany and France now require satellite-verified origin documentation, pulling certified softwood volumes into EU ports at premium pricing.
- Mass timber fabrication hubs:Engineered wood adoption in mid-rise commercial construction is displacing steel and concrete in fire-rated spans across Vancouver, Portland, and Stuttgart.
- Japan METI building code revisions:Seismic-grade laminated veneer lumber specifications are opening export-grade production slots for Canadian and Nordic suppliers.
Market Restraints
- Input cost volatility in pulpwood and resin binders:Phenol and methanol price swings compress margins for engineered wood producers in British Columbia and the US Southeast.
- Supply concentration in coastal British Columbia:Fires and beetle infestations have concentrated softwood log supply among three integrated coastal operators, creating single-source vulnerability.
- Technical limitation in solid-sawn fire ratings:Building codes above six stories effectively exclude dimensional lumber from core structural loads in favor of glued laminated timber.
Strategic Opportunities
- Underpenetrated Australian bushfire construction standards:NCC-compliant treated softwood framing remains undersupplied in New South Wales and Victoria, creating import substitution openings for North American producers.
- Regulatory tailwind from US Inflation Reduction Act:Carbon accounting provisions for mass timber in federal buildings are redirecting GSA procurement toward domestic cross-laminated timber fabricators.
- Technology convergence of AI grading and blockchain traceability:Machine-vision lumber grading is converging with distributed ledger documentation to automate EU Deforestation Regulation compliance at mill scale.
Industry Challenges
- Certification timeline compression:Chain-of-custody documentation from forest to retail now requires 18-month audit cycles that lag behind contract award windows.
- Capex intensity in kiln drying and treatment capacity:Heat treatment and acetylation lines for European export compliance demand capital deployment that mid-scale sawmills cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sawn Timber Market |
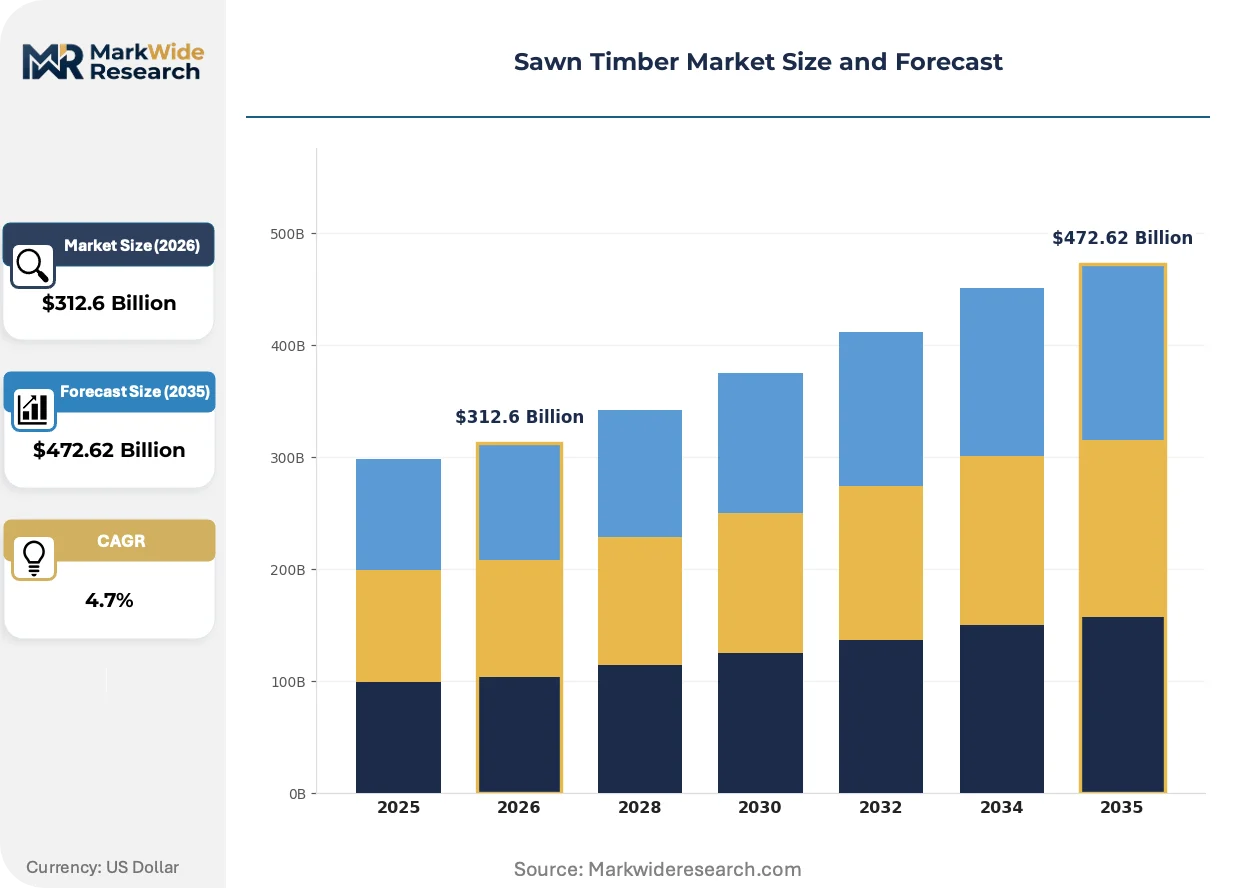
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softwood, Hardwood, Engineered Wood, Laminated Veneer Lumber Application: Construction, Furniture, Flooring, Pallets End User: Contractors, Furniture Manufacturers, Retailers, DIY Consumers Sales Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | West Fraser Timber Co Ltd, Weyerhaeuser Company, Canfor Corporation, Stora Enso Oyj, Interfor Corporation, UPM-Kymmene Oyj, Sierra Pacific Industries, Georgia-Pacific LLC, Sumitomo Forestry Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sawn Timber Market Evolving Landscape
Digital traceability and engineered wood manufacturing are compressing the traditional divide between commodity lumber and performance-grade structural materials.
Cross-laminated timber manufacturing is converging with robotic prefabrication systems to produce panelized wall and floor assemblies. Multi-story residential developers in Sweden and Austria are specifying these systems for 12-to-18-story buildings. This convergence is compressing on-site labor hours and erection schedules, displacing conventional platform framing in urban infill projects.
REACH chemical restrictions on wood preservatives are forcing European treaters to reformulate copper-azole and micronized copper quaternary systems. Industrial consequence includes accelerated testing of thermally modified softwood alternatives. Nordic suppliers are capturing specification share in German and Dutch exterior cladding markets as a result.
Buyer concentration among national homebuilders is compressing supplier negotiation cycles and unbundling traditional distribution markups. Large US builders are contracting directly with sawmill systems for framing packages, bypassing wholesale yards. This pattern is most visible in the US Sun Belt where D.R. Horton and Lennar operate captive procurement desks.
Sawn Timber Market Segmentation
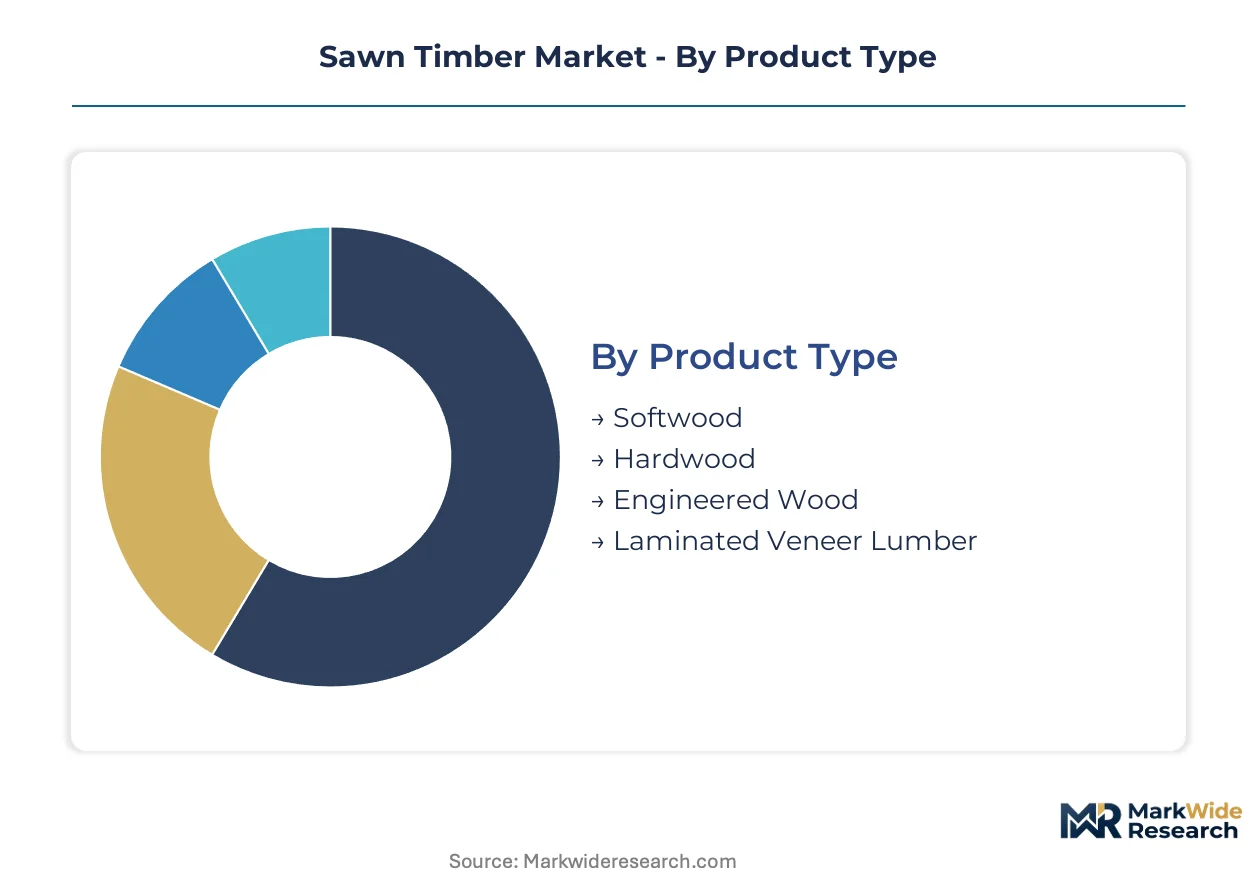
Sawn timber segmentation reveals divergent capital requirements across product categories, with engineered wood demanding fabrication infrastructure while commodity softwood rewards scale economies. Procurement patterns vary sharply by end-user sophistication, from specification-driven contractors to price-sensitive DIY channels.
Product Type:
Capital intensity varies dramatically across timber categories, with engineered wood requiring continuous press lines and resin handling systems that softwood sawmills avoid entirely.
- Softwood:Dimensional lumber cut from coniferous species with standardized moisture content and structural grading for load-bearing applications. North American platform framing contractors in the United States and Canada specify SPF and Southern Yellow Pine in multi-billion-board-foot annual volumes, though beetle damage and fire risk in coastal British Columbia have tightened supply concentration.
- Engineered Wood:Composite products including oriented strand board and I-joists manufactured from veneers, strands, or flakes bonded with structural adhesives. German and Austrian multi-story residential developers specify cross-laminated timber panels for 12-to-18-story buildings, displacing steel and concrete in fire-rated spans where solid-sawn capacity fails.
- Hardwood:Deciduous species processed for appearance-grade applications requiring clear grain and specified color matching.
- Laminated Veneer Lumber:Peeled veneer layers bonded in parallel grain orientation for high-strength structural members.
Softwood absorbs the bulk of installed capacity; engineered wood is expanding most quickly.
Application:
Margin structures diverge by application, with construction commanding volume premiums and furniture retaining value-based pricing power.
- Construction:Structural framing, sheathing, and finish carpentry across residential and commercial building types. United States homebuilders D.R. Horton and Lennar operate captive procurement desks contracting directly with sawmill systems, bypassing wholesale yards and compressing traditional distribution markups in the Sun Belt.
- Furniture:Appearance-grade hardwood and softwood components for case goods, upholstery frames, and millwork. Italian and Polish manufacturers pay premiums for FSC-certified clear-grade oak and ash, with EU Timber Regulation documentation now mandatory for market access.
- Flooring:Tongue-and-groove planks and engineered wood floor systems.
- Pallets:Low-grade dimensional lumber and recycled wood for material handling systems.
Construction dominates volume flows; furniture retains the steepest pricing power.
End User:
Procurement sophistication separates specification-driven commercial buyers from price-sensitive retail channels.
- Contractors:Licensed builders and specialty trades requiring grade-stamped lumber with chain-of-custody documentation. Japanese construction firms sourcing seismic-grade laminated veneer lumber under revised METI building codes demand third-party certification and mill-specific quality protocols.
- Furniture Manufacturers:Industrial wood processors with exacting moisture content and defect tolerances.
- Retailers:Big-box and specialty lumber yards serving pro-sumer and small contractor segments.
- DIY Consumers:Home improvement purchasers selecting pre-cut project packs and dimensional framing lumber.
Contractors absorb the bulk of certified volume; furniture manufacturers are gaining share fastest.
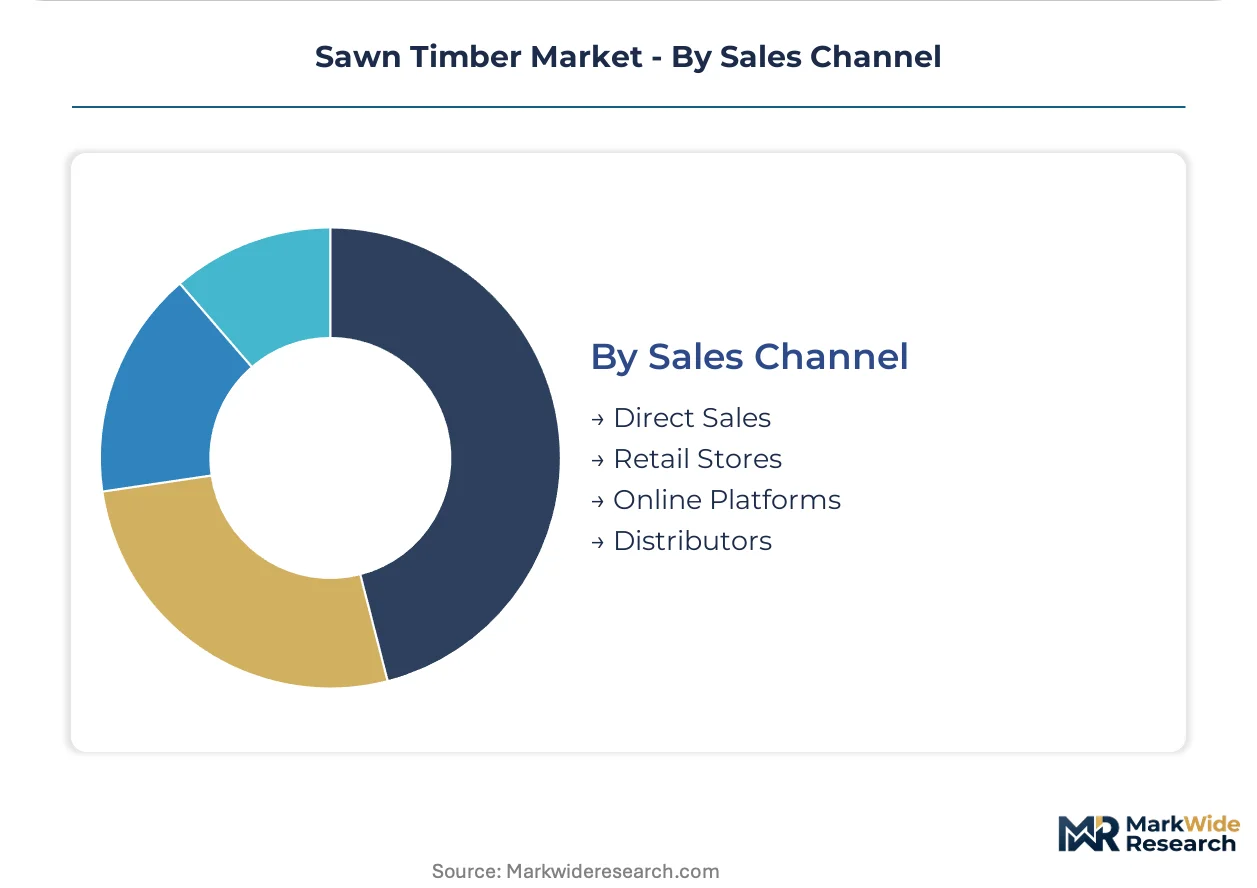
Sales Channel:
Channel economics reflect inventory carrying costs and specification support requirements.
- Direct Sales:Mill-to-builder contracting for large-scale framing packages with dedicated logistics coordination. Australian developers in New South Wales and Victoria increasingly source NCC-compliant treated softwood directly from North American producers to bypass undersupplied domestic wholesale networks.
- Distributors:Regional and national wholesale yards aggregating mixed loads and providing credit terms.
- Retail Stores:Physical lumber yards and home centers with immediate availability.
- Online Platforms:Digital marketplaces for standardized grades with delivered pricing.
Direct sales absorb the bulk of large-project volume; online platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Northwest Special Economic Zone in coastal British Columbia concentrates integrated softwood operations serving trans-Pacific export corridors. German mass timber fabrication clusters leverage EU Green Deal construction subsidies to anchor European engineered wood capacity.
United States
Southern Yellow Pine framers supply Sun Belt homebuilders D.R. Horton and Lennar through direct mill contracting. The Inflation Reduction Act carbon accounting provisions redirect GSA procurement toward domestic cross-laminated timber. Pacific Northwest operators face beetle damage and fire risk tightening log supply concentration among coastal integrated mills.
Canada
Seismic-grade laminated veneer lumber exporters target Japan METI building code revisions. British Columbia coastal operators sustain FSC-certified throughput into EU ports under chain-of-custody documentation. Alberta and Quebec sawmill systems serve US Midwest platform framing contractors bypassing traditional wholesale yards.
Germany
Multi-story residential developers in Stuttgart specify cross-laminated timber panels for 12-to-18-story buildings. The EU Deforestation Regulation geolocation mandates pull certified softwood volumes into Hamburg and Bremen ports at premium pricing. Baden-Württemberg fabrication hubs displace steel and concrete in fire-rated commercial spans.
Japan
Construction firms sourcing seismic-grade engineered wood demand third-party certification and mill-specific quality protocols. METI building code revisions open export-grade production slots for Canadian and Nordic suppliers. Osaka and Nagoya industrial zones concentrate laminated veneer lumber import processing for domestic distribution.
Australia
Developers in New South Wales and Victoria source NCC-compliant treated softwood directly from North American producers. Bushfire construction standards remain undersupplied, creating import substitution openings. Sydney and Melbourne procurement desks increasingly bypass undersupplied domestic wholesale networks for direct mill contracting.
Sawn Timber Market Competitive Landscape
North American producers anchor the scale-driven tier; Nordic specialists hold certification-premium positioning. The vendor base separates into three strategic archetypes: vertically integrated coastal operators with captive forest tenure, engineered wood fabricators with continuous press infrastructure, and regional softwood sawmills serving homebuilder direct contracts. Dominant competitive moves include backward integration into forestland assets and geographic expansion of kiln-drying capacity to meet EU export compliance.
Within the integrated operator tier, West Fraser Timber Co Ltd and Weyerhaeuser Company exemplify scale-based positioning across North American distribution corridors. Stora Enso Oyj anchors Nordic softwood supply through controlled chain-of-custody documentation from forest to mill. These three entities represent divergent geographic emphases—Pacific Northwest coastal operations, Southern Yellow Pine distribution networks, and Baltic-Nordic export systems—each occupying a distinct procurement channel for residential and commercial construction.
| Leading Market Players |
|---|
| West Fraser Timber Co Ltd |
| Weyerhaeuser Company |
| Canfor Corporation |
| Stora Enso Oyj |
| Interfor Corporation |
| UPM-Kymmene Oyj |
| Sierra Pacific Industries |
| Georgia-Pacific LLC |
| Sumitomo Forestry Co. Ltd |
| Others |
Value Network & Pricing Analysis
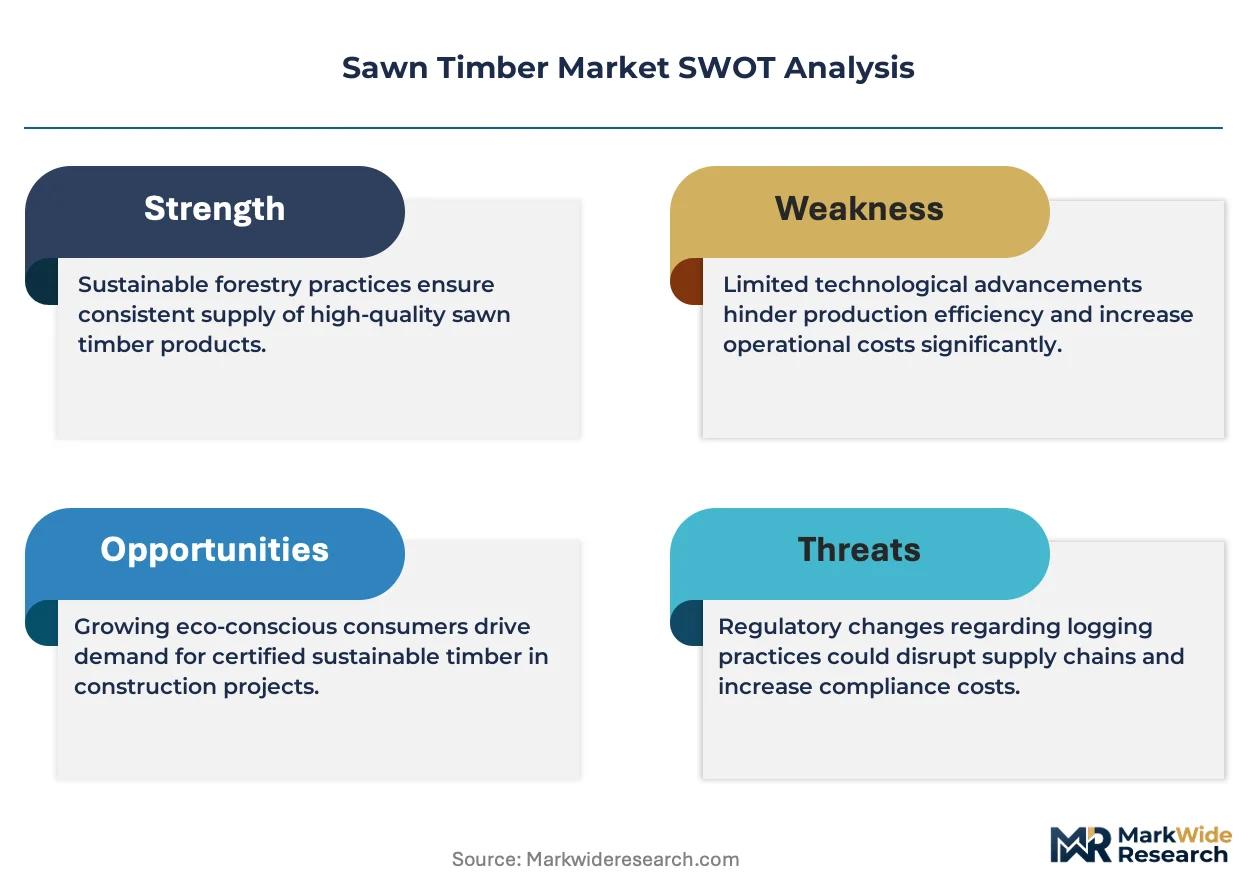
Certified sawmill operators in coastal British Columbia command wage premiums that widen the spread between FSC-certified structural grades and commodity dimensional lumber. Labor-cost differentials between unionized Pacific Northwest mills and automated Southern Yellow Pine facilities in the US Southeast translate directly into three-tier pricing stratification across premium certified, standard grade-stamped, and economy spot-market tiers.
Pricing Analysis
Short lead-time premiums for just-in-time framing packages from direct mill contracts run 8-12 percent above spot wholesale pricing in the US Sun Belt. Price differentiation rests on FSC chain-of-custody certification tiers and volume-scale contracting with national homebuilders. Cost compression in economy-grade SPF is intensifying because beetle-damaged log supply in British Columbia has concentrated among three coastal operators. National homebuilders D.R. Horton and Lennar exhibit lowest price sensitivity due to captive procurement desks, while independent contractors in Australian bushfire zones show highest sensitivity to landed cost spreads.
Supply Chain Analysis
Trans-Pacific container rates and inland rail tariffs from Vancouver to Chicago determine effective delivered pricing for Asian and Midwest markets. Log supply concentrates in Canada, the United States, and Sweden, with finished lumber distribution running through direct mill-to-builder channels, regional wholesale yards, and big-box retail. Raw material dependencies include coastal British Columbia hemlock-fir stands, US Southern Yellow Pine plantations, and Nordic spruce-boreal forest tenure. Single-source vulnerability from fire and beetle damage in coastal British Columbia creates concentrated supply risk for FSC-certified export grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: kiln-drying and heat-treatment capacity bottlenecks for EU Deforestation Regulation compliance are propping pricing premiums for certified throughput. The 18-month certification audit cycles lag contract award windows, locking in scarcity rents for compliant operators.
For Market Incumbents: Anticipate margin compression from phenol and methanol input volatility by securing long-term resin binder supply agreements with Gulf Coast chemical producers. Backward integration into captive forest tenure in Alberta and Quebec insulates against British Columbia supply concentration risk. Prioritize automated machine-vision grading systems to compress EU Deforestation Regulation compliance costs at mill scale. For New Entrants and Emerging Players: Blockchain-anchored traceability platforms offer a technology-first wedge into documentation-starved segments of the Australian and Southeast Asian import markets. Target NCC-compliant treated softwood framing in New South Wales and Victoria where domestic wholesale networks remain undersupplied. Pursue direct mill-to-developer contracting models that bypass established distribution markups. For Investors and Strategic Acquirers: The window for entry favors engineered wood fabricators with continuous press infrastructure and existing FSC chain-of-custody documentation. Mid-scale sawmills with retrofit-ready kiln capacity in the US Southeast and Central Europe retain long-term viability as carbon-accounting rules tighten federal procurement. Watch for divergence between EU EUDR geolocation mandates and emerging US state-level carbon accounting rules as the inflection signal for mill-system market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Tenure | Captive log supply in Alberta and Quebec insulates against British Columbia concentration risk. |
| Automated Machine-Vision Grading Deployment | AI lumber grading at West Fraser and Interfor mills compresses EU compliance documentation costs. |
| Direct Mill-to-Builder Contracting Expansion | Lennar and D.R. Horton captive procurement desks bypass wholesale markups in US Sun Belt corridors. |
| Cross-Laminated Timber Capacity Buildout | Stuttgart and Vancouver fabrication hubs capture Inflation Reduction Act federal building procurement. |
| Blockchain Traceability Platform Integration | Distributed ledger documentation automates EU Deforestation Regulation geolocation compliance at scale. |
Research Methodology
Independent corroboration across sawmill operations executives, residential construction procurement directors, and EU regulatory compliance officers underwrites the qualitative findings in this study. Primary interviews with mass timber fabrication engineers, laminated veneer lumber quality managers, and Australian bushfire construction specifiers combined with secondary validation from customs trade data, SEC 10-K filings, and EU Timber Regulation enforcement disclosures. Bottom-up volume triangulation across product categories reconciled with top-down macroeconomic construction spend indicators.
Rate-of-change decomposition across softwood, engineered wood, and hardwood segments structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application, end-user sophistication, and sales channel configuration. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and capacity expansion announcements. Forecast inputs incorporated METI building code revision timelines and EU Deforestation Regulation geolocation mandate compliance curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained phenol price volatility or accelerated beetle infestation in coastal British Columbia. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
GCC Exterior Sheathing Market