
 Geogrid Market | 2026-2036
Geogrid Market Size, Share, and Industry Trends Forecast 2026-2036
Geogrid Market Analysis
Geotechnical engineering talent scarcity is redrawing competitive boundaries across the geogrid supply base. Tensar International leverages its in-house polymer research capabilities to sustain specification leadership in North American transportation projects. HUESKER Synthetic GmbH anchors its position through backward integration into high-tenacity polyester yarn production. Maccaferri S.p.A. competes by dominating mechanically stabilized earth wall systems across European rail corridors.
Geogrid denotes a planar polymeric or metallic grid structure with aperture dimensions typically exceeding 6.5 mm, manufactured through extrusion, weaving, or welding processes to reinforce soil and aggregate masses against lateral deformation and settlement. Its primary commercial purpose centers on improving load-bearing capacity while reducing base course thickness in civil infrastructure. Polymer geogrid commands the largest installed base due to corrosion immunity and lightweight handling, though steel geogrid retains margin concentration in heavy mining applications where puncture resistance dominates specification. Road construction represents the fastest-growing application channel as agencies shift toward perpetual pavement designs requiring subgrade stabilization.
FHWA design guidelines and AASHTO material specifications govern geogrid deployment in US federal highway projects, while the EU Green Deal's embodied carbon tracking requirements are reshaping polymer sourcing compliance across European public procurement. India's Ministry of Road Transport and Highways mandates BIS-certified geosynthetics in national highway contracts, creating localized qualification barriers for imported products. Stakeholders must monitor evolving lifecycle assessment protocols that increasingly weight recyclability against raw performance metrics in infrastructure tender evaluations.
Market Dynamics
Perpetual pavement design mandates from transportation agencies are compressing base course thickness requirements while elevating specification-grade geogrid procurement, fundamentally restructuring supplier qualification hierarchies.
Growth Catalysts
- India's National Highway Expansion Program:BIS-certified geosynthetics mandates in national highway contracts are accelerating specification-grade polymer geogrid deployment across subgrade stabilization applications.
- FHWA Design Guidelines:US federal highway projects governed by AASHTO material specifications are institutionalizing geogrid-reinforced pavement sections as standard design practice.
- EU Green Deal Infrastructure Resilience Mandates:Embodied carbon tracking requirements are reshaping polymer sourcing compliance and favoring low-carbon geogrid formulations in European public procurement.
Market Restraints
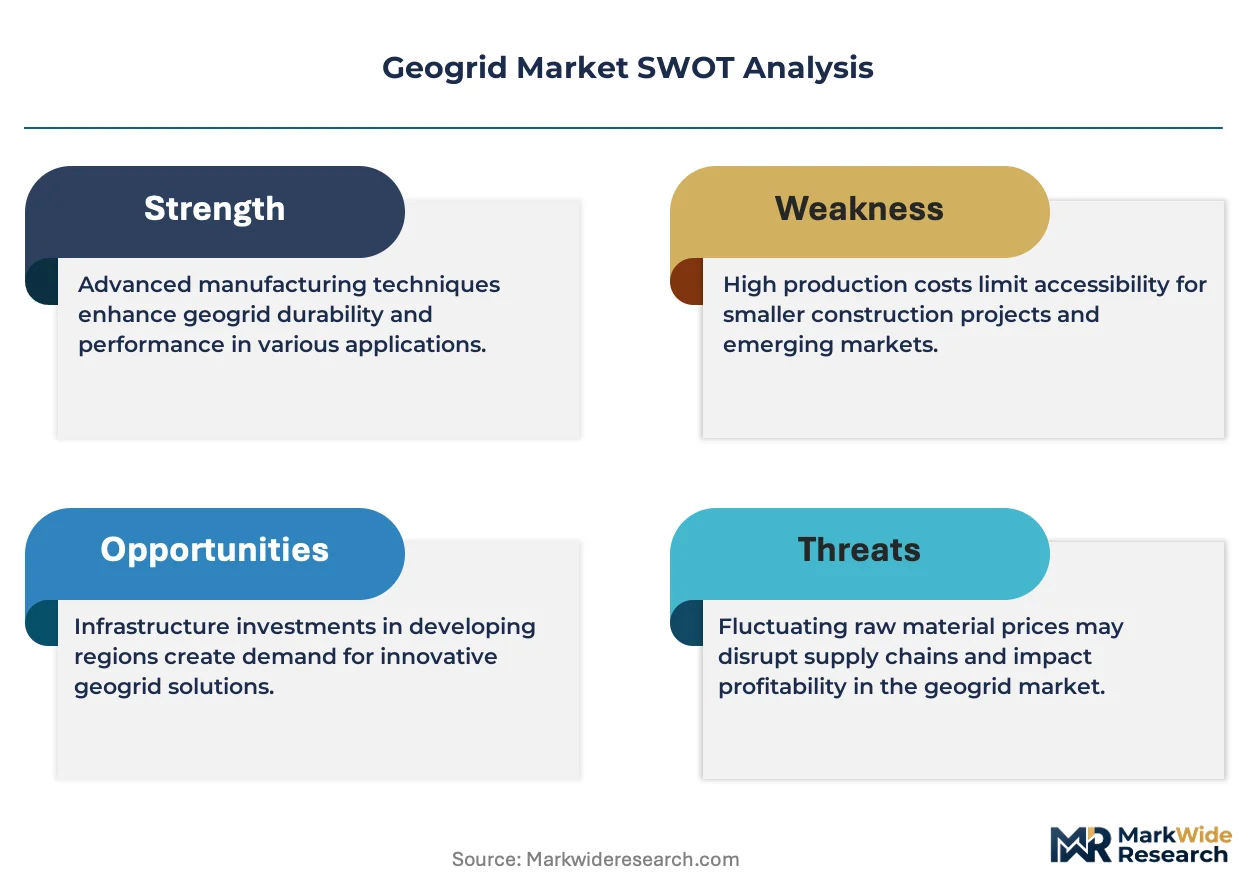
- High-Tenacity Polyester Yarn Supply Concentration:Backward integration by dominant European and Asian yarn producers creates captive supply risks for non-integrated geogrid manufacturers.
- Steel Geogrid Corrosion Vulnerability:Polymer alternatives are displacing metallic grids in coastal and chemically aggressive environments where lifecycle cost calculations favor synthetic materials.
- REACH Compliance Burden:European chemical registration requirements impose documentation costs and reformulation timelines that disadvantage smaller geogrid suppliers without dedicated regulatory affairs functions.
Strategic Opportunities
- Mining Tailings Stabilization:Heavy mining applications in Australia and Chile present white-space demand for puncture-resistant biaxial geogrid configurations in heap leach pad construction.
- Rail Corridor Mechanically Stabilized Earth Systems:European rail electrification programs are expanding MSE wall specifications requiring high-strength uniaxial geogrid reinforcement.
- Recycled Polymer Feedstock Integration:Lifecycle assessment protocols in Nordic countries are creating preference premiums for geogrids manufactured with post-consumer recycled content meeting ISO 14040 frameworks.
Industry Challenges
- Geotechnical Engineering Talent Scarcity:Specification design and installation supervision functions face recruitment bottlenecks as civil engineering graduates gravitate toward software and energy sectors.
- Multi-Jurisdiction Certification Timelines:BIS certification for India, CE marking for Europe, and state DOT approvals in the US require parallel testing programs that compress margin on international contracts.
- Legacy Pavement Rehabilitation Integration:Overlay designs incorporating geogrid interlayers demand specialized equipment and contractor training that slow adoption in maintenance-focused agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geogrid Market |
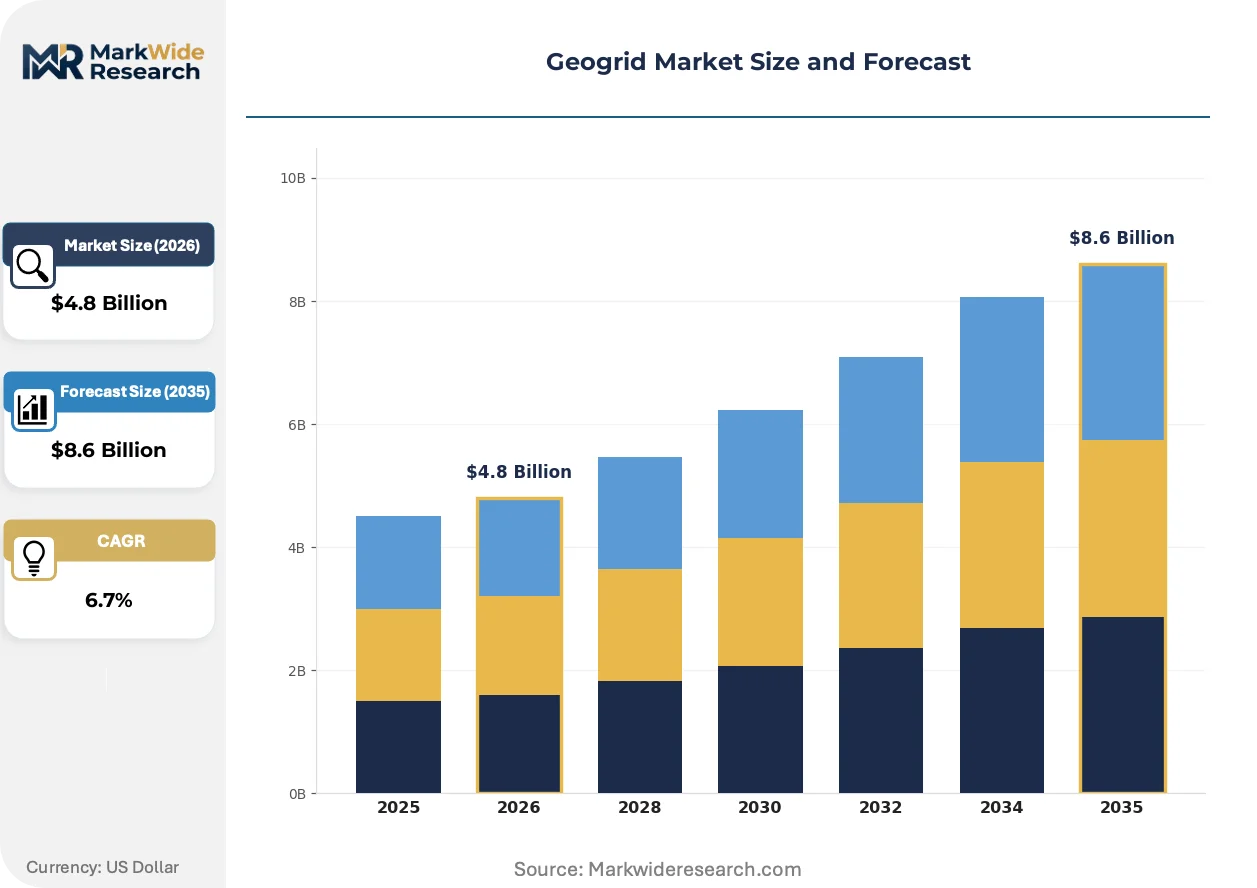
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Geogrid, Steel Geogrid, Composite Geogrid, Glass Geogrid Application: Reinforced Soil Structures, Erosion Control, Road Construction, Retaining Walls End User: Construction, Transportation, Mining, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | Tensar International, HUESKER Synthetic GmbH, Maccaferri S.p.A., Strata Systems, Inc., ACE Geosynthetics, NAUE GmbH & Co. KG, TenCate Geosynthetics, TENAX Corporation, Commercial Metals Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geogrid Market Emerging Trajectories
Material science advances and procurement digitization are converging to compress specification cycles and elevate performance transparency requirements across geogrid supply chains.
Triaxial punched-and-drawn polypropylene geogrid is displacing traditional biaxial configurations in subgrade stabilization applications. State DOTs in Texas and California are specifying triaxial products for perpetual pavement test sections. The technology is displacing conventional base course thickness calculations by enabling 30-40% aggregate reduction while maintaining structural number requirements.
EU Green Deal embodied carbon tracking mandates are forcing polymer resin sourcing disclosures in infrastructure tender documentation. Public procurement authorities in Germany and the Netherlands now require Environmental Product Declarations compliant with EN 15804 for geosynthetic materials. Suppliers with ISO-verified lifecycle assessments are capturing specification preference in rail and highway contracts.
Buyers are consolidating geogrid procurement through integrated civil works contractors rather than direct material sourcing. Engineering-procurement-construction firms in India's national highway program are negotiating multi-year supply agreements that bundle geogrid with aggregate and installation services. This concentration is most visible in Andhra Pradesh and Maharashtra where NHAI project bundling has reduced the number of qualified geogrid vendors per corridor.
Geogrid Market Segmentation
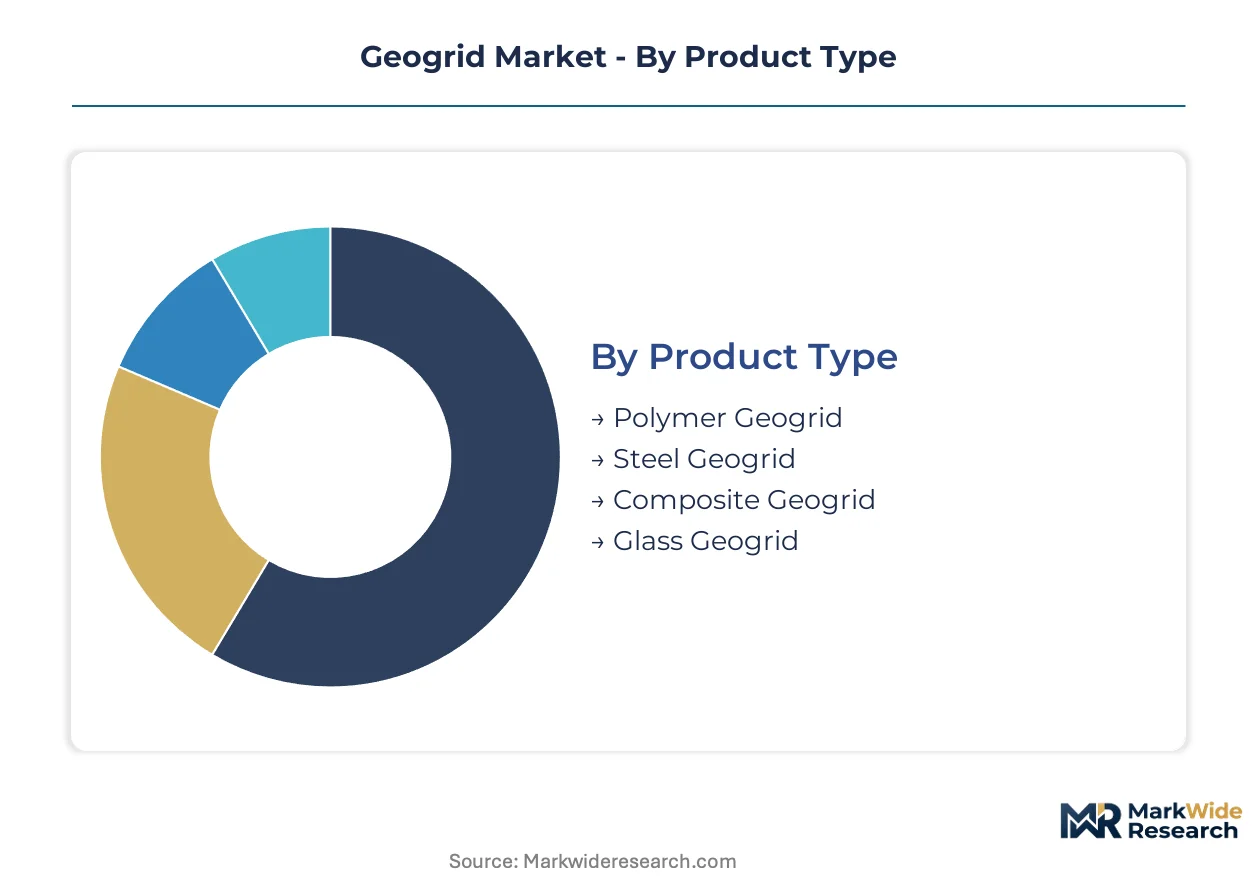
Specification-grade procurement in federal highway programs creates divergent compliance pathways across material categories. Regulatory frameworks in the US, India, and the EU enforce distinct testing protocols that reshape competitive positioning within each segment.
Product Type:
REACH compliance in Europe and BIS certification in India enforce divergent polymer formulation standards that fragment supplier qualification across material categories.
- Polymer Geogrid:Extruded polypropylene and high-density polyethylene grids dominate specification-grade road construction through corrosion immunity and lightweight handling. India's NHAI mandates BIS-certified polymer geogrids in national highway contracts, concentrating procurement among qualified domestic and import suppliers meeting tensile strength and aperture stability protocols.
- Steel Geogrid:Welded wire mesh configurations retain margin concentration in heavy mining applications where puncture resistance dominates specification. Australian and Chilean heap leach pad operators specify steel grids for load-bearing capacity under aggressive chemical exposure, though coastal infrastructure projects increasingly specify polymer alternatives due to corrosion vulnerability lifecycle calculations.
- Composite Geogrid:Hybrid polymer-fiber constructions address specialized drainage and filtration reinforcement in European rail MSE wall systems.
- Glass Geogrid:Fiberglass-reinforced asphalt overlays serve pavement rehabilitation applications requiring thermal stability and crack propagation resistance.
Polymer geogrid handles the majority of throughput; composite geogrid is the fastest mover on share.
Application:
Perpetual pavement design mandates from state DOTs and national highway agencies are compressing base course thickness requirements while elevating specification-grade procurement.
- Road Construction:Subgrade stabilization and base course reinforcement applications command specification priority as agencies shift toward perpetual pavement designs. Texas and California DOTs specify triaxial punched-and-drawn polypropylene geogrid for test sections enabling aggregate reduction while maintaining structural number requirements.
- Reinforced Soil Structures:Mechanically stabilized earth wall systems dominate European rail corridor applications where electrification programs expand uniaxial geogrid reinforcement specifications. Maccaferri S.p.A. anchors market presence through integrated design-build capabilities across Italian, French, and German rail infrastructure tenders.
- Retaining Walls:Segmental block and panel-faced MSE systems serve commercial and residential grade separation in urbanizing Indian corridors.
- Erosion Control:Slope stabilization and channel protection applications deploy biaxial and triaxial configurations in coastal and riverine environments.
Road construction absorbs the largest contract value; reinforced soil structures are expanding most quickly on specification volume.
End User:
Engineering-procurement-construction firm consolidation is bundling geogrid procurement with aggregate and installation services, reshaping vendor relationships across customer categories.
- Transportation:Federal and state highway agencies institutionalize geogrid-reinforced pavement sections through FHWA design guidelines and AASHTO material specifications. US federal projects mandate third-party certification of tensile strength, junction efficiency, and creep resistance for specification compliance.
- Construction:Integrated civil works contractors in India's NHAI program negotiate multi-year supply agreements that compress vendor margins while ensuring material traceability. Andhra Pradesh and Maharashtra project bundling has reduced qualified geogrid vendors per corridor from twelve to four in select tenders.
- Mining:Australian and Chilean tailings stabilization projects specify puncture-resistant biaxial configurations for heap leach pad construction.
- Agriculture:Farm access road and silage pad applications represent fragmented, price-sensitive demand with minimal specification oversight.
Transportation channels command premium pricing; construction is gaining share fastest through EPC bundling.
Distribution Channel:
Procurement digitization and lifecycle assessment transparency requirements are elevating documentation standards across supply chain configurations.
- Direct Sales:Manufacturer-direct relationships with state DOTs and national highway authorities ensure specification compliance and technical support. Tensar International sustains North American transportation leadership through in-house polymer research and direct engineering engagement with Texas, California, and federal project designers.
- Contractors:EPC firms in India's national highway program bundle geogrid with aggregate sourcing and installation supervision, consolidating procurement decisions at the prime contractor level. HUESKER Synthetic GmbH leverages backward integration into high-tenacity polyester yarn production to secure multi-year supply agreements with European rail construction consortia.
- Distributors:Regional stocking networks serve maintenance-focused agencies and smaller civil contractors with standardized product lines.
- Online Retail:Digital platforms address agricultural and residential erosion control applications with limited technical specification requirements.
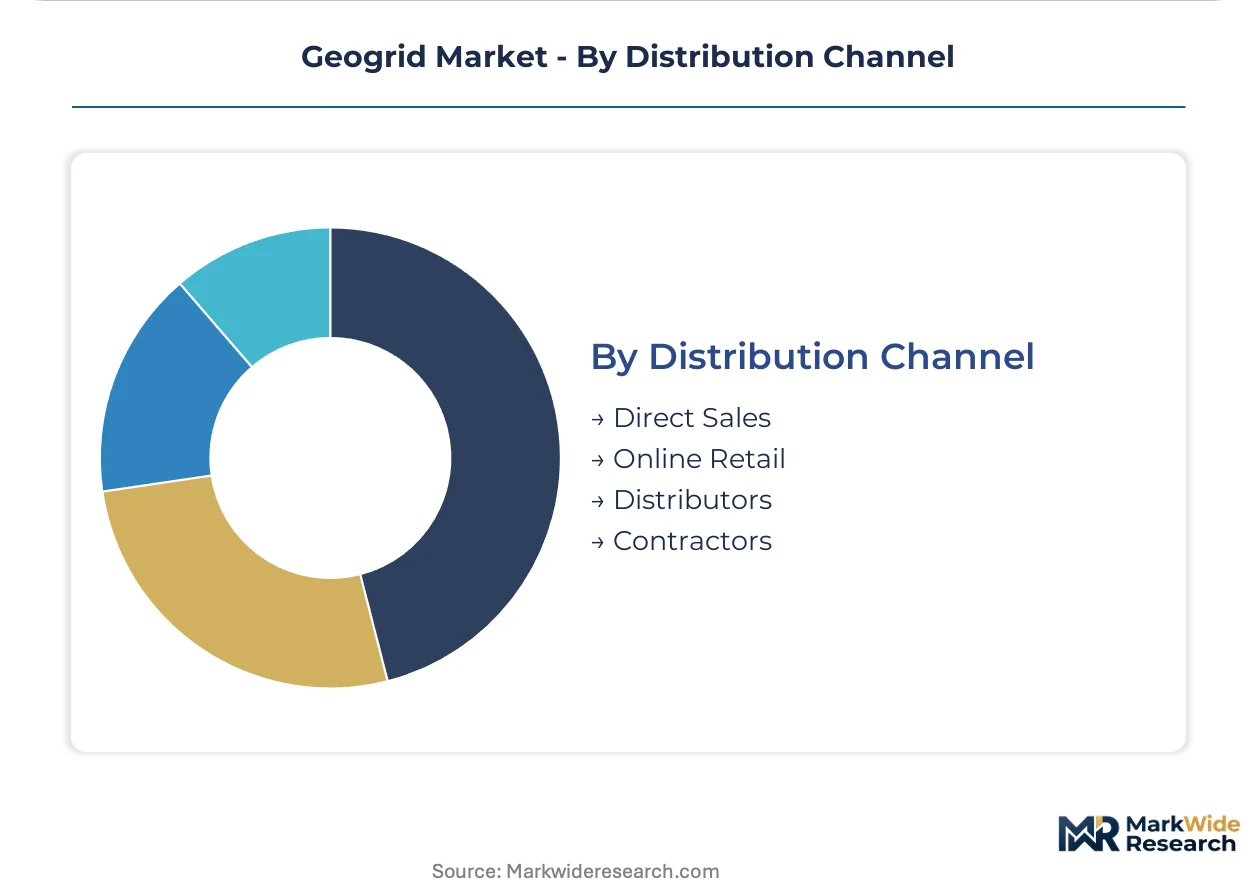
Contractor channels carry the highest throughput volume; direct sales are climbing the fastest on specification-grade contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FHWA design guidelines anchor the United States as the dominant specification geography, while India's NHAI program and the EU Green Deal reshape procurement compliance across their respective jurisdictions. National certification requirements are fragmenting supplier qualification pathways.
United States
State DOTs in Texas and California specify triaxial polypropylene geogrid for perpetual pavement test sections. FHWA guidelines institutionalize geogrid-reinforced pavement sections as standard federal design practice. The Southeast corridor concentrates aggregate-reduction pilot programs around Atlanta and Charlotte metropolitan infrastructure agencies.
India
NHAI project bundling in Andhra Pradesh and Maharashtra compresses qualified vendors per corridor from twelve to four. BIS certification mandates create localized barriers for imported polymer geogrid products. Western and Southern state highway programs drive specification-grade procurement volume through integrated EPC contracting.
Germany
Rail electrification programs across North Rhine-Westphalia and Bavaria expand MSE wall specifications requiring high-strength uniaxial reinforcement. EU Green Deal embodied carbon tracking mandates force polymer resin sourcing disclosures in tender documentation. The Rhine-Ruhr industrial corridor anchors backward-integrated polyester yarn production for captive geogrid supply.
Australia
Heap leach pad operators in Western Australia specify puncture-resistant biaxial configurations for mining tailings stabilization. State environmental regulators impose lifecycle cost calculations favoring synthetic materials over steel grids in coastal infrastructure. The Pilbara region concentrates heavy mining applications where load-bearing capacity dominates specification.
Chile
Copper mining operations in the Atacama Desert deploy steel geogrid for aggressive chemical exposure environments. National mining regulators require third-party certification of tensile strength and junction efficiency for tailings containment systems. The Antofagasta region anchors South American demand for puncture-resistant reinforcement in heap leach construction.
Geogrid Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on certification velocity and regional specification relationships. The upper tier controls polymer research capabilities and backward-integrated yarn production, while mid-scale fabricators concentrate on single-jurisdiction qualification. Three archetypes define competitive positioning: specification-grade leaders with in-house R&D, backward-integrated European manufacturers with captive supply chains, and regional specialists bundling installation services. Dominant competitive moves include multi-year EPC supply agreements and parallel certification programs across BIS, CE marking, and state DOT approval pathways.
Among integrated specialists with research capabilities, Tensar International exemplifies the specification-leader archetype through direct engineering engagement with transportation agencies. HUESKER Synthetic GmbH and Maccaferri S.p.A. occupy positions within the backward-integrated and MSE-system tiers respectively, with each representing distinct competitive vectors in European and North American procurement channels. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Tensar International |
| HUESKER Synthetic GmbH |
| Maccaferri S.p.A. |
| Strata Systems, Inc. |
| ACE Geosynthetics |
| NAUE GmbH & Co. KG |
| TenCate Geosynthetics |
| TENAX Corporation |
| Commercial Metals Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at high-tenacity polyester yarn facilities in Germany and China shapes both supply concentration and price floors for specification-grade polymer geogrid. Backward-integrated manufacturers leverage captive resin supply to maintain margin stability while non-integrated fabricators face input cost volatility that compresses pricing power in competitive tenders.
Pricing Analysis
Price spreads between European and Asian polymer geogrid suppliers widen during periods of raw material volatility. Three-tier pricing structure across premium certification-grade, standard DOT-approved, and economy non-certified levels dominates procurement. Price differentiation hinges on BIS/CE/state DOT certification status and volume scale commitments in multi-year EPC contracts. Cost compression in standard-grade segments is intensifying because India's NHAI bundling concentrates buyer power. Maintenance-focused agencies and agricultural end-users exhibit highest price sensitivity; federal highway programs and mining operators demonstrate lowest.
Supply Chain Analysis
Germany and China anchor high-tenacity polyester yarn production for captive geogrid supply, while the United States concentrates extruded polypropylene manufacturing. Raw material flows draw from petroleum-derived polymer resins, recycled PET feedstocks, and specialized UV stabilizer additives. Single-source vulnerability in certified yarn supply creates qualification bottlenecks for non-integrated fabricators seeking multi-jurisdiction approval. Distribution runs through engineering-procurement-construction firms in India, direct manufacturer relationships with state DOTs in North America, and regional stocking distributors for maintenance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure capital expenditure cycles favor geogrid demand recovery as transportation agencies accelerate perpetual pavement programs and rail electrification investments.
For Market Incumbents: Shield specification-grade positioning through parallel BIS, CE marking, and state DOT certification investments that extend qualification moats. Deepen backward integration into high-tenacity yarn production or secure long-term offtake agreements with European and Asian resin suppliers to neutralize input cost volatility threatening margin stability. For New Entrants and Emerging Players: Differentiate on recycled polymer feedstock integration targeting Nordic lifecycle assessment premiums and EU Green Deal compliance mandates. Mining tailings stabilization in Australia and Chile presents the most penetrable white-space, with entry via specialized puncture-resistant biaxial configurations and technical partnership with heap leach pad engineering firms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated specialists with captive yarn supply and established multi-jurisdiction certification. Long-term viability over the coming decade rests on polymer research capabilities and EPC bundling relationships rather than commodity fabrication scale. Watch for inflection in India's NHAI vendor consolidation velocity as signal for regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Tenacity Yarn | Captive supply secures margin stability against polyester price volatility in European procurement. |
| Multi-Jurisdiction Certification Investment | Parallel BIS, CE marking, and state DOT approvals unlock NHAI and federal highway contract access. |
| Recycled Polymer Feedstock Integration | Post-consumer content meets EN 15804 EPD requirements for EU Green Deal tender compliance. |
| EPC Supply Agreement Bundling | Multi-year contracts with Indian highway consortia compress vendor count and lock in volume. |
| Triaxial Product Line Expansion | Punched-and-drawn polypropylene configurations capture Texas and California DOT perpetual pavement specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from geotechnical engineering directors, state DOT materials engineers, EPC procurement leads, and polymer R&D managers and refined through secondary validation. Primary fieldwork encompassed structured discussions across transportation agencies in Texas, California, Germany, and India, plus mining operators in Western Australia and Chile. Secondary sources included FHWA design guideline documentation, BIS certification registries, EU tender databases, AASHTO material specifications, and customs trade records for polymer resin flows. Bottom-up project pipeline assessments were triangulated against top-down infrastructure expenditure forecasts.
Variance decomposition across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. Modeled segmentation encompassed polymer/steel/composite/glass material categories, road construction/reinforced soil/retaining wall/erosion control applications, and transportation/construction/mining/agriculture end users. CAGRs were derived from regression against historical infrastructure investment correlations and forward-looking perpetual pavement adoption curves. Key inputs included NHAI project bundling timelines, EU embodied carbon tracking implementation velocity, and state DOT specification revision cycles.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure expenditure levels, stable polymer resin pricing, or unchanged certification requirements would require recalibration. Forecasts reflect documented assumptions regarding perpetual pavement mandate expansion, BIS enforcement consistency, and REACH compliance burden trajectories. Recalibration cycles align with material shifts in federal highway appropriations, EU Green Deal procurement rulemaking, and Indian EPC market consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
North America Residential Water Heater Market