
 GCC Coconut Water Market | 2026-2036
GCC Coconut Water Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Coconut Water Market Intelligence
Fitness centers and hospitality groups are unwinding traditional sports-drink procurement in favor of natural hydration alternatives. PepsiCo leverages its Gulf distribution infrastructure to secure shelf dominance in hypermarket chains. Harmless Harvest differentiates through cold-pressed processing claims and organic certification. Celebes Coconut Corporation anchors supply reliability through integrated plantation-to-bottle operations in Southeast Asian source regions.
GCC coconut water is the clear liquid extracted from young green coconuts, typically harvested at six to seven months maturity when natural sugar content reaches five to eight percent and electrolyte concentrations peak. The beverage serves commercial buyers seeking isotonic hydration without synthetic additives or artificial coloring. Pure coconut water leads volume shipments through Gulf supermarkets, while flavored variants capture premium margins in health food stores and boutique fitness channels. Cartons dominate institutional procurement for food service providers, though aluminum cans are gaining traction in convenience retail due to extended shelf stability and ambient storage compatibility.
Saudi Food and Drug Authority standards govern nutritional labeling and health claim verification for imported coconut water entering the Kingdom. UAE Ministry of Industry and Advanced Technology enforces Gulf Standardization Organization technical regulations on packaging materials and shelf-life declarations. Dubai Municipality food safety inspections add another compliance layer for products distributed through the emirate's hospitality sector. Stakeholders must monitor evolving halal certification requirements and sugar-content disclosure rules as Gulf regulators align with broader consumer transparency mandates.
Market Dynamics
Fitness centers and hospitality groups across the Gulf Cooperation Council are unwinding decades-long sports-drink procurement contracts in favor of electrolyte-rich natural alternatives, forcing distributors to reconfigure shelf-space allocation and cold-chain logistics around ambient-stable packaging formats.
Growth Catalysts
- SFDA Labeling Standards:Saudi Food and Drug Authority tightening of health-claim verification is filtering out diluted or additive-heavy imports, elevating pure coconut water credibility among institutional buyers.
- Hypermarket Shelf Expansion:Carrefour and Lulu Group are dedicating expanded chilled-beverage sections to functional hydration, creating dedicated facings for isotonic natural drinks in Dubai and Riyadh.
- Hospitality Procurement Pivot:Jumeirah Group and Rotana Hotels are replacing synthetic sports beverages with cold-pressed coconut water in minibar and restaurant programs across UAE properties.
Market Restraints
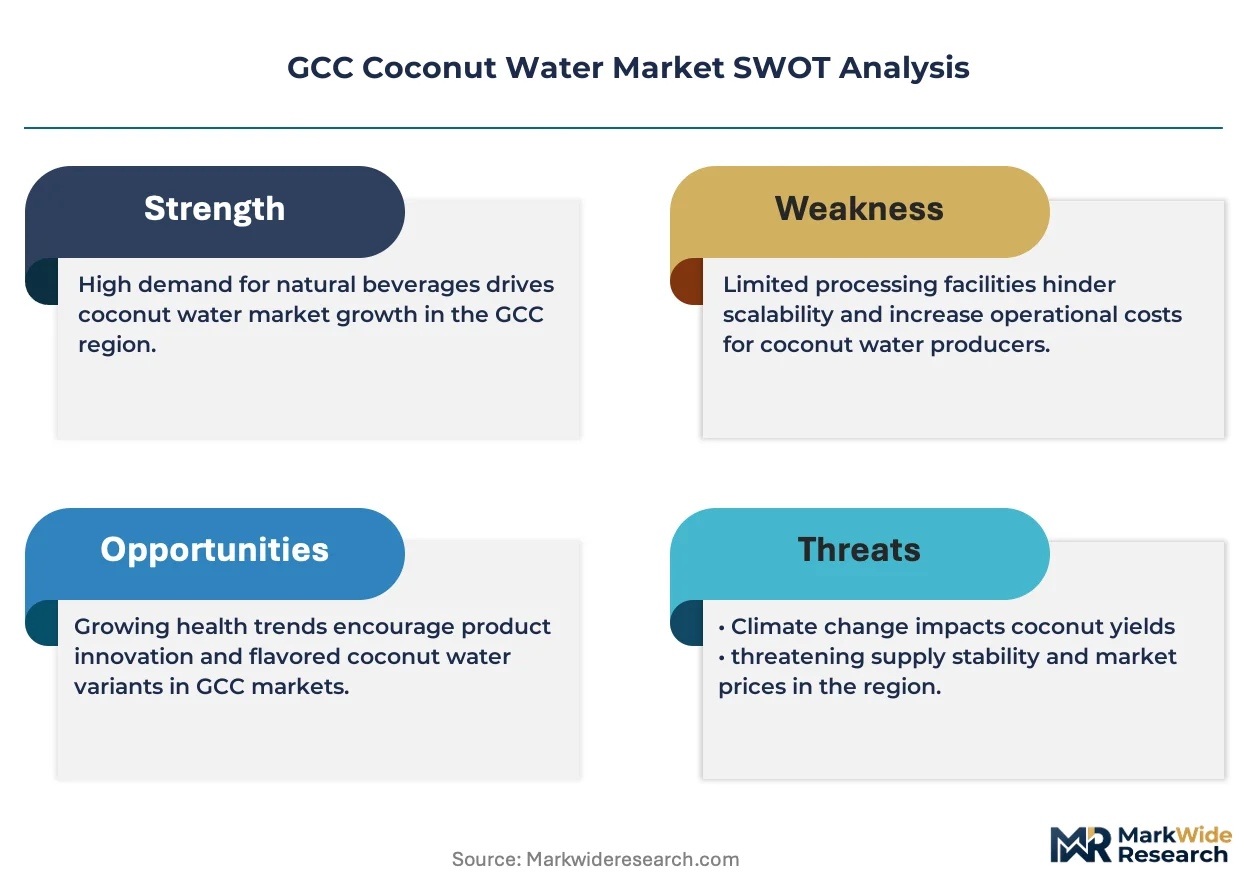
- Southeast Asian Supply Concentration:Over eighty percent of GCC coconut water originates from integrated Philippine and Indonesian plantation operations, exposing importers to monsoon-related harvest volatility and shipping lane congestion through the Strait of Malacca.
- Aluminum Input Cost Sensitivity:Can packaging faces margin compression from LME aluminum price fluctuations, complicating the shift from carton to ambient-stable formats that convenience retailers prefer.
- Synthetic Isotonic Substitution:Gatorade and Powerade maintain entrenched vending-machine presence in Saudi fitness chains, slowing natural-alternative penetration in high-frequency consumption occasions.
Strategic Opportunities
- Kuwait Health-Food Channel:Sultan Center and Saveco are expanding organic-certified beverage sections with minimal incumbent coconut water presence, offering first-mover positioning for cold-pressed entrants.
- Halal Certification Alignment:Gulf Standardization Organization harmonization of halal beverage standards is reducing multi-country compliance duplication, streamlining cross-border distribution from UAE hub operations into Oman and Bahrain.
- Fitness Boutique Integration:Warehouse Gym and Fitness First are piloting branded cooler partnerships with natural hydration suppliers, embedding coconut water into membership experience packages.
Industry Challenges
- Cold-Chain Skill Scarcity:Maintaining six-to-eight degree Celsius integrity from Jebel Ali port through last-mile delivery requires trained handlers that Gulf logistics providers are struggling to recruit at scale.
- Shelf-Life Validation Timelines:Dubai Municipality extended stability testing protocols for ambient-stored beverages are adding four-to-six months to product registration, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Coconut Water Market |
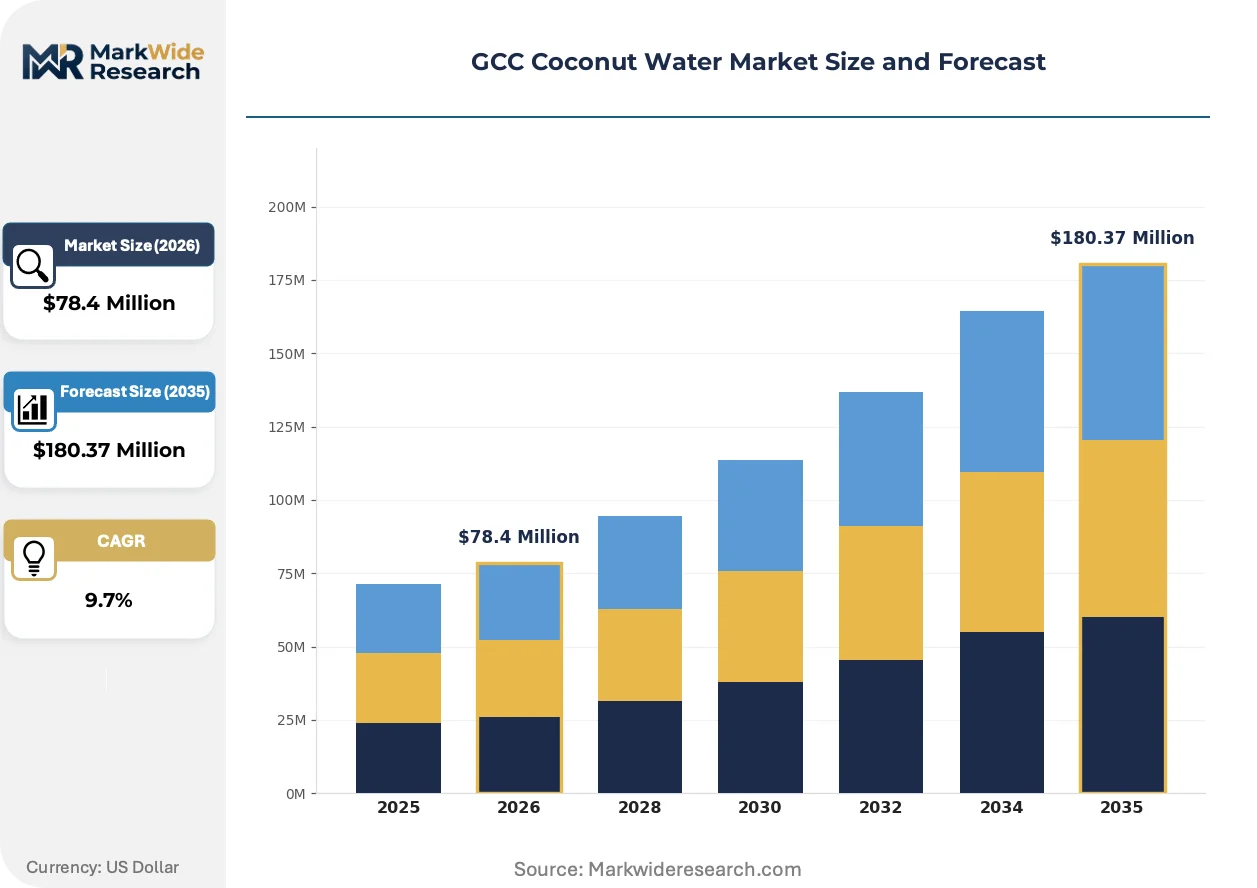
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $180.37 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Coconut Water, Flavored Coconut Water, Coconut Nectar, Coconut Milk Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores End User: Retail Consumers, Food Service Providers, Fitness Centers, Hospitals Packaging Type: Cartons, Bottles, Cans, Pouches |
| Companies Covered | Harmless Harvest, Celebes Coconut Corporation, PepsiCo, Wichy Plantation Company (Pvt) Ltd, C2O Coconut Water, Coca-Cola (Zico), Taste Nirvana International, Inc., Vaivai SAS, Goya Foods, Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Coconut Water Market Strategic Shifts & Innovations
Cold-pressed processing technology and ambient-stable packaging formats are compressing the traditional trade-off between nutritional integrity and distribution reach, enabling natural beverage penetration beyond the chilled-case perimeter into vending and convenience channels.
High-pressure processing is supplanting thermal pasteurization in premium coconut water production. Dubai-based health-food distributors are adopting HPP-treated SKUs at triple-digit annual rates. This shift is enabling twelve-month ambient shelf life without nutrient degradation, collapsing the historical chilled-only distribution constraint that limited Gulf retail density.
SFDA sugar-content disclosure mandates are tightening nutritional transparency requirements for imported beverages. Manufacturers must now declare total and added sugars separately on Arabic-English bilingual labels. Pure coconut water variants with sub-five-percent natural sugar are leveraging this to differentiate against flavored competitors in Saudi supermarket aisles.
Boutique fitness chains are consolidating beverage procurement under single-source natural hydration contracts. Warehouse Gym UAE terminated its multi-brand cooler program in favor of exclusive organic coconut water partnerships. This concentration is most visible in Dubai's Marina and Downtown clusters, where membership premiums now bundle unlimited beverage access.
GCC Coconut Water Market Segmentation
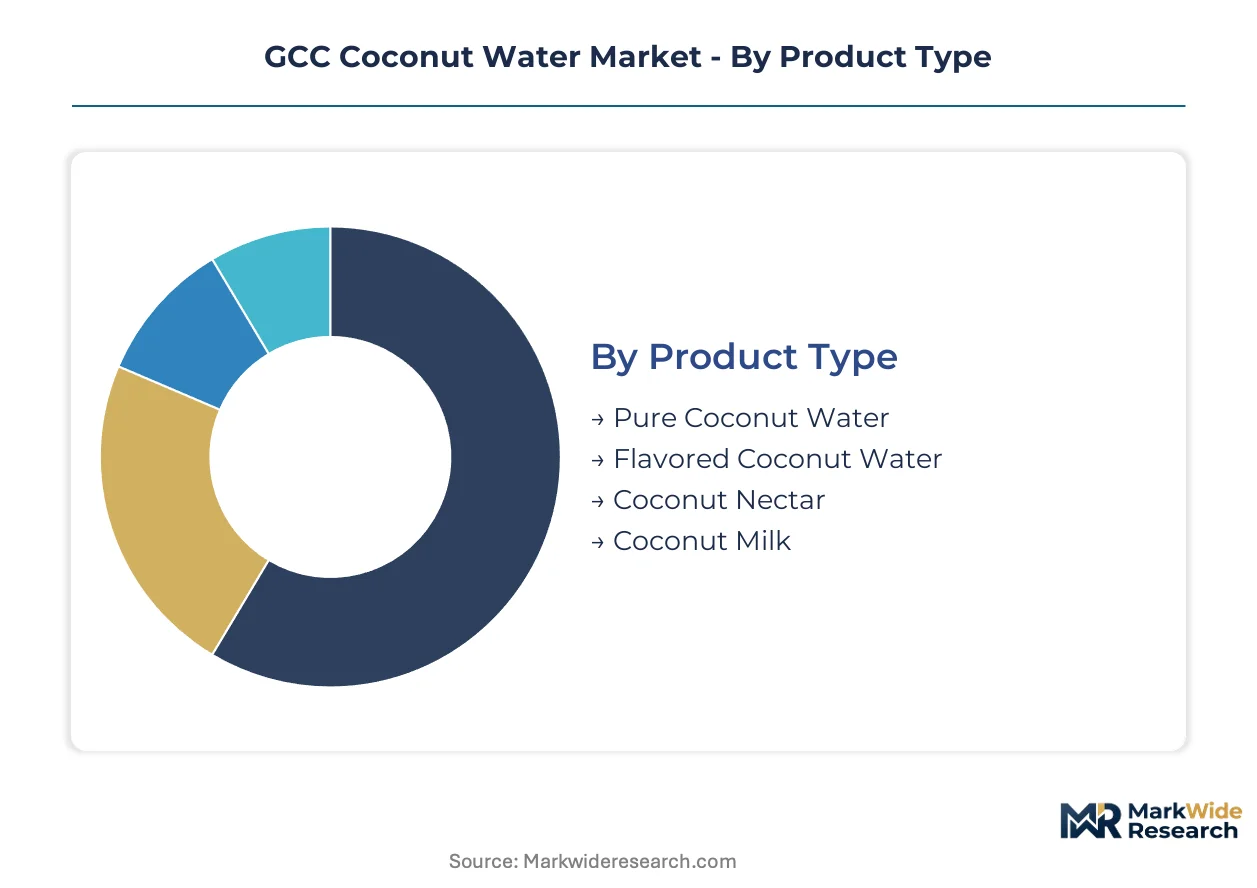
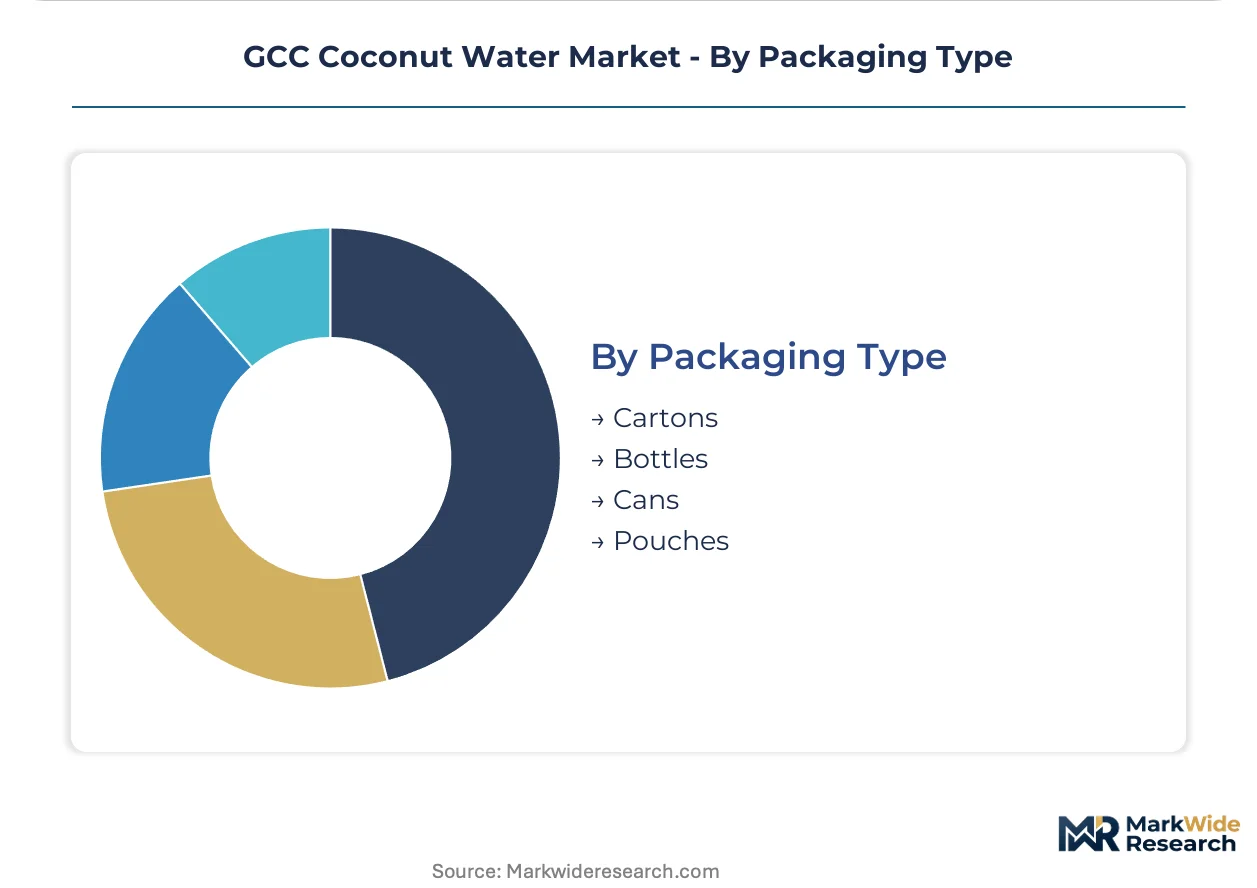
Segmentation in the GCC coconut water market reveals divergent growth vectors across product formats and channel strategies. Pure variants and ambient-stable packaging are capturing institutional procurement contracts, while flavored SKUs and digital channels reshape consumer access patterns across Saudi Arabia and the UAE.
Product Type:
Domestic Gulf production remains negligible, so every segment relies on Southeast Asian import pipelines through Dubai's Jebel Ali hub and direct Saudi port entry.
- Pure Coconut Water:Single-source extraction from young green coconuts with no added sugars or preservatives. Carrefour and Lulu Group chilled sections in Dubai and Riyadh are expanding facings for isotonic natural hydration as SFDA labeling verification elevates credibility.
- Flavored Coconut Water:Infusions with tropical fruit extracts or natural essences commanding premium shelf positioning. Health food stores in Kuwait's Sultan Center network are piloting mango and pineapple variants with minimal incumbent competition.
- Coconut Nectar:Concentrated sap-derived sweetener for beverage formulation and baking applications. Food service providers in UAE hospitality clusters are substituting refined sugars in smoothie programs.
- Coconut Milk:Emulsified kernel extract for culinary and dairy-alternative applications. Saudi food manufacturers are integrating into packaged dessert and curry base production.
Pure coconut water commands the established base. The steepest expansion runs through flavored variants.
Distribution Channel:
Channel economics stratify sharply between high-volume ambient distribution and cold-chain dependent premium placement.
- Supermarkets:Hypermarket chains dominate volume throughput with dedicated functional beverage aisles. Chilled-section expansion in Dubai Mall and Riyadh Park retail complexes is reallocating space from synthetic sports drinks.
- Health Food Stores:Curated SKU environments emphasizing organic certification and cold-pressed processing claims. Saveco in Kuwait and Organic Foods and Cafe in Dubai are expanding coconut water sections at triple-digit rates.
- Online Retailers:Direct-to-consumer platforms and quick-commerce apps. Noon and Amazon.ae are building ambient-stable multipack offerings for subscription replenishment.
- Convenience Stores:Grab-and-go formats favoring aluminum cans for ambient storage compatibility. ENOC and ADNOC retail networks across UAE are adding single-serve SKUs to forecourt coolers.
Supermarkets anchor current volume. Online retailers are climbing the fastest as fulfillment infrastructure matures.
End User:
Procurement sophistication varies dramatically between price-sensitive institutional buyers and premium-seeking individual consumers.
- Retail Consumers:Individual purchasers through grocery and digital channels. Saudi households are substituting coconut water for traditional laban and fruit juice in daily hydration routines.
- Food Service Providers:Restaurants, cafes, and catering operations requiring bulk ambient-stable formats. Jumeirah Group properties are replacing synthetic beverages in minibar programs across Dubai beachfront resorts.
- Fitness Centers:Boutique gyms and wellness clubs seeking isotonic natural alternatives. Warehouse Gym UAE has consolidated cooler partnerships under exclusive organic coconut water contracts.
- Hospitals:Clinical nutrition and patient hydration programs. Dubai Health Authority facilities are piloting coconut water as oral rehydration therapy for post-surgical recovery.
Retail consumers hold the volume base. Fitness centers are gaining share fastest as membership bundles incorporate unlimited beverage access.
Packaging Type:
Material selection determines cold-chain requirements, shelf-life extension, and retail channel compatibility across Gulf climate conditions.
- Cartons:Aseptic multilayer packaging for twelve-month ambient stability. Institutional food service procurement in Saudi Arabia and Bahrain relies on one-liter formats for back-of-house efficiency.
- Bottles:PET and glass containers for premium positioning and transparency marketing. Health food stores in Dubai's Jumeirah district favor clear bottles showcasing liquid clarity.
- Cans:Aluminum containers gaining traction in convenience retail. ENOC forecourt locations across Abu Dhabi and Dubai are expanding can facings for ambient storage and single-serve portability.
- Pouches:Flexible film packaging for cost-sensitive markets and child-oriented portions. Limited current presence in GCC, with pilot programs in Saudi school nutrition initiatives.
Cartons dominate institutional procurement. Cans are expanding most quickly as convenience retail reallocates cooler space.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine and Indonesian plantation operations export through Dubai's Jebel Ali hub to Saudi Arabia, the UAE, and Kuwait, with direct Saudi port entry bypassing the UAE for bulk institutional contracts.
Saudi Arabia
Fitness centers in Riyadh and Jeddah are unwinding Gatorade procurement contracts in favor of electrolyte-rich natural alternatives. Saudi Food and Drug Authority labeling requirements for health claims are tightening product qualification standards for imported beverages. The Riyadh Park retail complex is expanding chilled-beverage sections dedicated to functional hydration products.
United Arab Emirates
Hospitality groups across Dubai are replacing synthetic sports beverages with cold-pressed coconut water in minibar programs. Dubai Municipality food safety inspections enforce extended stability testing protocols for ambient-stored beverages. Dubai's Marina and Downtown fitness clusters are piloting exclusive organic coconut water partnerships with boutique gym chains.
Kuwait
Health-food retailers in Kuwait City are expanding organic-certified beverage sections with minimal incumbent coconut water presence. The country's national food safety regulator aligns with Gulf Standardization Organization technical regulations on packaging materials. Sultan Center and Saveco networks are piloting mango and pineapple flavored variants in curated SKU environments.
Bahrain
Food service providers in Manama are substituting refined sugars with coconut nectar in smoothie programs. Gulf Standardization Organization harmonization of halal beverage standards is streamlining cross-border distribution from UAE hub operations. The Seef District hospitality corridor is reallocating premium beverage shelf space toward natural hydration alternatives.
Oman
Convenience retail networks in Muscat are adding aluminum can SKUs for ambient storage compatibility. The Sultanate's national standards body enforces shelf-life declaration requirements on imported beverages. ENOC forecourt locations across the Muscat metropolitan area are expanding single-serve coconut water facings.
GCC Coconut Water Market Key Industry Players
Player mix skews toward multinational beverage conglomerates with Gulf distribution infrastructure and Southeast Asian plantation-integrated suppliers. Market structure concentrates shelf dominance among three to four entities with hypermarket chain partnerships, while mid-tier cold-pressed specialists capture premium health-food margins. Strategic archetypes include ambient-stable mass distributors, organic-certified premium processors, and integrated plantation-to-bottle operators. Competitive moves center on aluminum can format transitions and exclusive fitness channel partnerships.
Among multinational beverage conglomerates, PepsiCo leverages established Gulf hypermarket relationships to secure volume placement, while Coca-Cola occupies a position within the isotonic natural drinks segment through its Zico brand. On the plantation-integrated vector, Celebes Coconut Corporation anchors supply reliability through captive Southeast Asian source operations. Harmless Harvest exemplifies the cold-pressed premium archetype, differentiating through organic certification claims in health-food retail environments.
| Leading Market Players |
|---|
| Harmless Harvest |
| Celebes Coconut Corporation |
| PepsiCo |
| Wichy Plantation Company (Pvt) Ltd |
| C2O Coconut Water |
| Coca-Cola (Zico) |
| Taste Nirvana International, Inc. |
| Vaivai SAS |
| Goya Foods, Inc. |
| Others |
Cost & Logistics Intelligence
Integrated plantation-to-bottle operations in the Philippines and Indonesia generate scale economies that compress unit costs for ambient-stable formats while elevating price floors for cold-pressed premium variants. These scale dynamics concentrate procurement leverage among hypermarket chains and institutional food service buyers, forcing mid-tier processors to absorb margin compression or retreat to health-food niche positioning.
Pricing Analysis
Cold-pressed processing technology commands a three-tier pricing structure across premium, standard, and economy levels, with HPP-treated SKUs fetching health-food premiums against thermally pasteurized mass-market alternatives. Price differentiation rests on organic certification tier and ambient shelf-life extension capability. Pricing pressure stems from LME aluminum volatility complicating can-format transitions that convenience retailers demand. Food service providers exhibit highest price sensitivity due to bulk procurement volumes, while boutique fitness chains accept premium positioning for membership bundling.
Supply Chain Analysis
The Philippines and Indonesia anchor coconut water extraction and aseptic packaging operations, with Thailand contributing smaller volumes of organic-certified supply. Raw material dependencies center on young green coconut harvests, multilayer carton substrates, and aluminum can sheet. Single-source vulnerability runs through the Strait of Malacca shipping corridor, where monsoon congestion disrupts Jebel Ali port arrivals. Distribution runs through Dubai's logistics hub for UAE, Kuwait, and Bahrain re-export, with direct Saudi port entry bypassing the UAE for Riyadh and Jeddah institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained cold-chain handlers capable of maintaining six-to-eight degree Celsius integrity from Gulf ports through last-mile delivery represent the critical capability gap constraining premium segment expansion. This scarcity filters market access to players with sufficient capital to build in-house logistics competencies or secure exclusive third-party partnerships.
For Market Incumbents: Consolidate hypermarket shelf dominance through exclusive ambient-format supply agreements with Carrefour and Lulu Group, neutralizing cold-pressed specialists' distribution reach. Deepen backward integration into Philippine plantation operations to buffer monsoon-related harvest volatility and secure volume commitments for institutional contracts.
For New Entrants and Emerging Players: Differentiate on halal certification alignment and SFDA pre-approval status to capture Kuwait and Bahrain health-food channel whitespace before incumbent repositioning. Target Sultan Center and Saveco expansion programs with organic-certified SKUs, leveraging minimal current coconut water presence in curated retail environments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated processors with captive Southeast Asian source operations and long-term hospitality procurement contracts. Acquisition candidates with established Jebel Ali hub operations and Dubai Municipality registration pipelines offer strongest five-to-ten year viability. Monitor SFDA sugar-content disclosure enforcement as signal for premium pure-variant demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Can Format Transition | ENOC and ADNOC forecourt expansion enables ambient retail penetration beyond chilled-case constraints. |
| Cold-Pressed Processing Scale-Up | HPP technology adoption collapses distribution limitations that previously confined premium SKUs to health-food channels. |
| Exclusive Fitness Channel Partnerships | Warehouse Gym and Fitness First branded cooler programs embed coconut water into membership experience bundles. |
| Halal Certification Harmonization | Gulf Standardization Organization alignment reduces multi-country compliance duplication for UAE hub operators. |
| Direct Saudi Port Entry Infrastructure | Bypassing Jebel Ali for bulk institutional contracts shortens lead times for Riyadh food service procurement. |
Research Approach
A spread of perspectives from beverage procurement managers at hypermarket chains, cold-chain logistics operators, SFDA regulatory consultants, and hospitality food service directors converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through Gulf Standardization Organization technical regulations, Dubai Municipality food safety inspection protocols, and customs import records for coconut water shipments through Jebel Ali and direct Saudi port entry. Bottom-up channel sizing and top-down macroeconomic triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user archetype across the analysis window. CAGRs were derived from trend extrapolation of fitness center procurement pivots, hospitality minibar program shifts, and retail shelf-space reallocation patterns. Industry-specific forecast inputs incorporated SFDA labeling timeline enforcement and aluminum packaging cost trajectory assumptions.
Material uncertainties — monsoon-related harvest disruption, LME aluminum price spikes, and extended Dubai Municipality stability testing delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding cold-chain infrastructure buildout and health-food retail expansion rates. Recalibration cycles align with material shifts in Gulf regulatory harmonization and Southeast Asian supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit Beverages Market
Beverages
GCC Fruit Juice Market
Beverages
Dairy Based Beverages Market
Beverages
Birch Water Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
South America Ready to Drink Beverages Market
Beverages
India Cafes & Bars Market
Beverages
Bottled Beverages Market
Beverages
Carbonated Soft Drinks Market
Beverages
Morocco Bottled Water Market
Beverages
Fusion Beverages Market
Beverages
Fruit Juices and Nectars Market
Beverages
North America Juices Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Sarsaparilla Market