
 North America Juices Market | 2026-2036
North America Juices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Juices Market Insights
Florida citrus processing capacity is decoupling from historical grove acreage as Brazilian concentrate imports reshape raw material flows. PepsiCo Inc. leverages its Gatorade manufacturing network to co-produce sports-positioned juice hybrids. The Coca-Cola Company anchors North American distribution through its Minute Maid refrigerated logistics footprint. Ocean Spray Cranberries Inc. differentiates via cooperative-structured cranberry procurement that controls upstream berry supply.
North America juices encompass aqueous extracts from fruits, vegetables, or botanicals, typically standardized to specific Brix levels for soluble solids content and pasteurized to achieve microbial stability for shelf-safe consumption. These beverages serve retail, foodservice, and institutional channels as refreshment, nutrition delivery, or recipe ingredients. Fruit Juices retains the largest revenue pool, though Blends command expanding shelf space as manufacturers combine vegetable bases with fruit masking to reduce sugar declarations. Ready-to-Drink Form dominates volume, while Concentrated sustains margin advantages in bulk institutional supply to restaurants and cafés.
FDA nutrition labeling mandates and USDA organic certification requirements shape product formulation decisions and premium positioning across the United States. Health Canada and CFIA enforce parallel juice standards in Canada, including strict identity requirements for products labeled as pure juice versus beverages with juice content. Mexico's COFEPRIS regulates labeling and sanitary registration for imported juice products entering through its retail and foodservice channels. Stakeholders must monitor evolving added-sugar disclosure thresholds and state-level container deposit legislation that could alter packaging material selection and reverse logistics costs.
Market Dynamics
FDA's added-sugar disclosure mandates are forcing wholesale reformulation across the North American juices landscape. Cold-pressed processing infrastructure is absorbing capital as manufacturers retool to meet clean-label expectations while maintaining shelf stability.
Growth Catalysts
- Millennial functional beverage demand:Health-conscious consumers in California and Texas are expanding purchases of probiotic and adaptogenic juice varieties, creating pull-through for premium SKUs.
- COFEPRIS retail modernization:Mexico's streamlined sanitary registration for imported juices is accelerating shelf-space expansion in Oxxo and Soriana distribution networks.
- High-pressure processing (HPP):This non-thermal pasteurization technology is enabling extended refrigerated shelf life without nutrient degradation, supporting cold-chain logistics investments.
Market Restraints
- Brazilian orange concentrate dependency:Florida processors rely on São Paulo suppliers for frozen concentrate, exposing margins to currency volatility and harvest fluctuations.
- Glass and PET resin cost inflation:Packaging materials represent 35-45% of COGS for mid-tier juice brands, compressing profitability when petrochemical feedstocks spike.
- USDA organic certification backlog:Three-year transition requirements for conventional groves are constraining certified organic juice supply growth.
Strategic Opportunities
- Canada's underserved prairie provinces:Manitoba and Saskatchewan exhibit juice consumption per capita 40% below Ontario levels, presenting white-space distribution potential.
- Direct-to-subscription models:Cold-pressed juice brands are bypassing traditional retail slotting fees through weekly delivery subscriptions to health-club members and corporate wellness programs.
- Vegetable-forward blends:Carrot, beet, and celery bases masked with citrus are capturing shelf space as consumers seek reduced-sugar alternatives that retain clean-label positioning.
Industry Challenges
- Flavor chemist talent scarcity:Reformulation expertise for sugar reduction without taste compromise commands premium salaries, constraining mid-market manufacturer R&D capacity.
- Refrigerated logistics capex intensity:Cold-chain compliance for HPP juices requires fleet upgrades and warehouse retrofitting that strains balance sheets.
- State container deposit fragmentation:California, Oregon, and Maine operate incompatible redemption systems, complicating national packaging standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Juices Market |
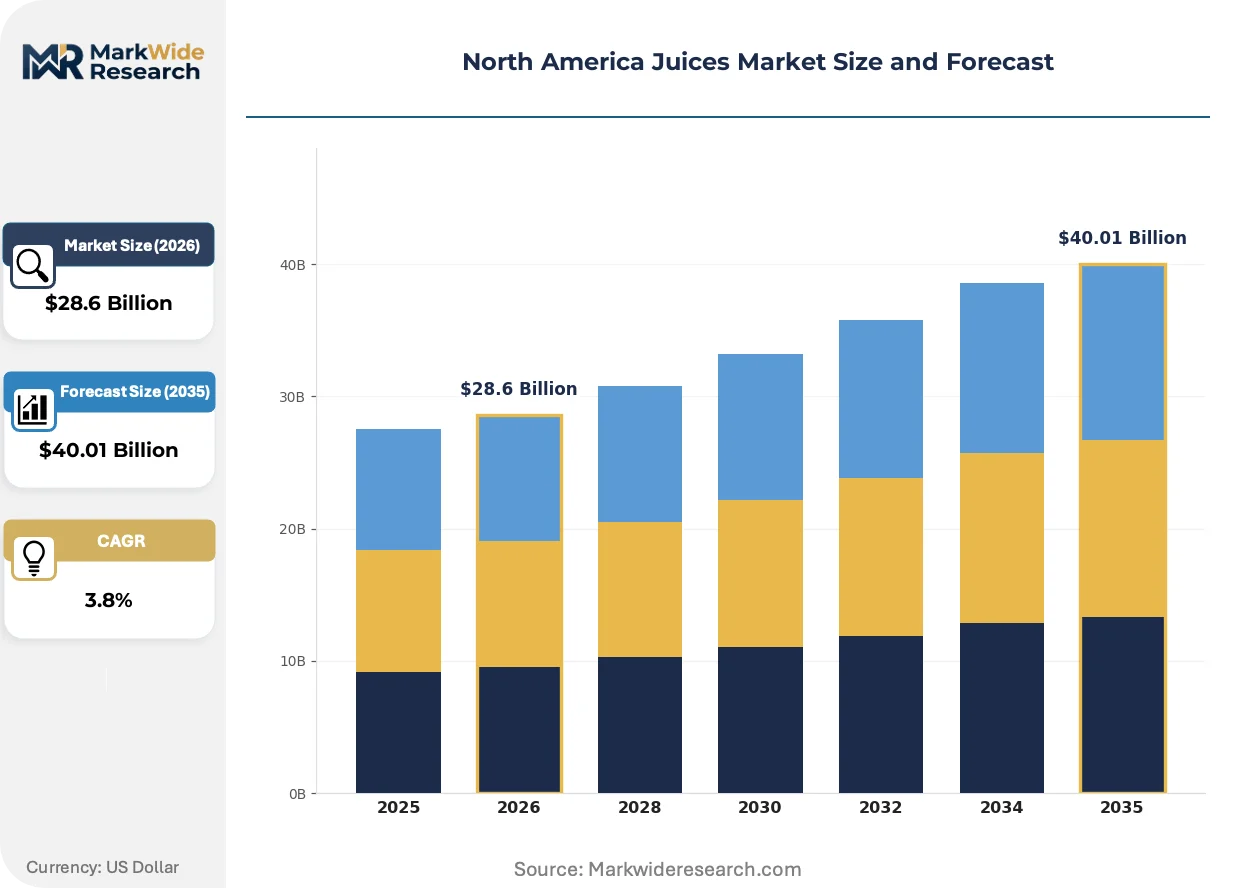
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Juices, Vegetable Juices, Blends, Nectars Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Food Stores End User: Households, Restaurants, Cafés, Juice Bars Form: Concentrated, Ready-to-Drink, Powdered, Frozen |
| Companies Covered | PepsiCo Inc., The Coca-Cola Company, Tropicana Brands Group, Keurig Dr Pepper Inc., Ocean Spray Cranberries Inc., The Kraft Heinz Company, Campbell Soup Company, Naked Juice, Bolthouse Farms, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Juices Market Trends and Innovations
Clean-label processing technologies are displacing conventional thermal pasteurization across premium juice tiers. Regulatory pressure on sugar content is accelerating ingredient innovation and portfolio restructuring.
High-pressure processing (HPP) is absorbing market share from hot-fill pasteurization in the refrigerated juice category. Premium brands and foodservice distributors are adopting HPP equipment at 15-20% annual capacity expansion rates. The technology is absorbing margin pressure by enabling longer distribution radii for perishable products without preservatives.
FDA's updated Nutrition Facts labeling requirements for added sugars are compressing formulation flexibility. Manufacturers must now disclose grams of added sugars separate from naturally occurring fruit sugars, forcing recipe re-engineering. The mandate is reshaping product portfolios most aggressively in children's juice and cocktail mixer segments, where reformulation timelines average 18-24 months.
Direct-to-consumer subscription models are fragmenting traditional grocery channel dominance. Cold-pressed juice startups are bypassing slotting fees and retailer margin requirements through weekly delivery to fitness studios and corporate campuses. This shift is most visible in Los Angeles, New York, and Toronto metropolitan corridors, where logistics density supports profitable last-mile economics.
North America Juices Market Segmentation
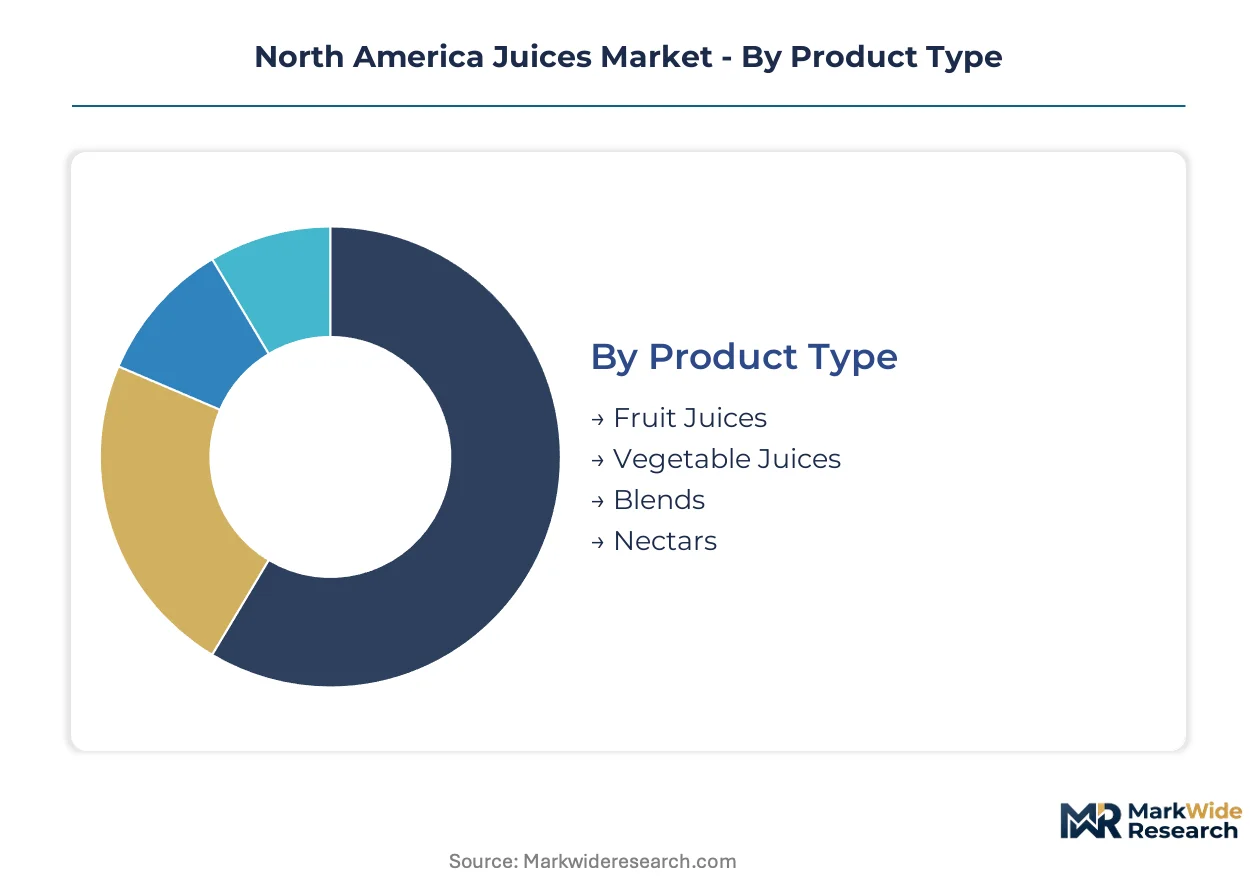
Segmentation in the North American juices market reveals distinct upgrade cycles across product types and distribution channels. Manufacturers track these patterns to time reformulation investments and channel expansion strategies.
Product Type:
Upgrade cycles vary by intrinsic shelf stability and consumer health perception, with refrigerated premium tiers commanding shorter replacement timelines than ambient-stable commodity lines.
- Fruit Juices:Aqueous extracts standardized to specific Brix levels and pasteurized for microbial stability. California and Florida households drive volume through daily consumption routines, though FDA added-sugar disclosure mandates are compressing formulation flexibility in children's SKUs.
- Blends:Vegetable bases masked with fruit extracts to reduce sugar declarations while retaining palatability. Texas and New York health-conscious consumers are expanding purchases of carrot-citrus and beet-berry combinations, pulling shelf space from pure fruit variants.
- Vegetable Juices:Tomato and carrot-dominant formulations targeting sodium-conscious demographics. Cold-pressed processing infrastructure absorbs capital as manufacturers retool for clean-label positioning.
- Nectars:Thickened beverages with 25-50% juice content and added sweeteners permitted. Mexico's Oxxo and Soriana networks sustain volume through price-accessible positioning.
Fruit Juices sits at the top of the volume ranking, with Blends climbing the fastest.
Distribution Channel:
Channel cost structures dictate margin tiering, with slotting fee intensity and cold-chain requirements creating divergent profitability profiles across the retail landscape.
- Supermarkets:Full-service retail with refrigerated case infrastructure and weekly promotional cycles. Kroger and Safeway banners in California and Texas dominate volume through private-label penetration and national brand blocking strategies.
- Online Retailers:Direct-to-subscription models bypassing traditional slotting economics. Los Angeles and Toronto metropolitan corridors support profitable last-mile logistics for cold-pressed juice startups targeting fitness studios and corporate campuses.
- Convenience Stores:Grab-and-go positioning with ambient-stable concentrates and single-serve chilled formats. 7-Eleven and Circle K networks prioritize turnover velocity over SKU breadth.
- Health Food Stores:Premium positioning with certified organic and HPP-processed SKUs. Whole Foods Market and Sprouts Farmers Market anchor this channel with proprietary quality standards.
Supermarkets command the volume base, with Online Retailers gaining share fastest through subscription density.
End User:
End-user concentration patterns reflect occasion-based consumption rituals, with institutional buyers exhibiting steadier offtake but compressed margins versus household premiumization.
- Households:Daily refreshment and nutrition delivery occasions across breakfast and snacking dayparts. Canadian prairie provinces show 40% per-capita consumption gaps versus Ontario, signaling white-space distribution potential.
- Restaurants:Recipe ingredient demand for cocktail mixers and culinary applications. Reformulation timelines average 18-24 months as operators adapt to sugar disclosure transparency.
- Cafés:Coffee accompaniments and standalone beverage occasions. Cold-pressed juice hybrids absorb capital as operators differentiate from commodity orange juice.
- Juice Bars:Fresh-pressed and custom-blended occasions with highest per-ounce pricing. High-pressure processing equipment adoption enables extended distribution radii without preservatives.
Households anchor volume throughput, with Juice Bars expanding most quickly through wellness positioning.
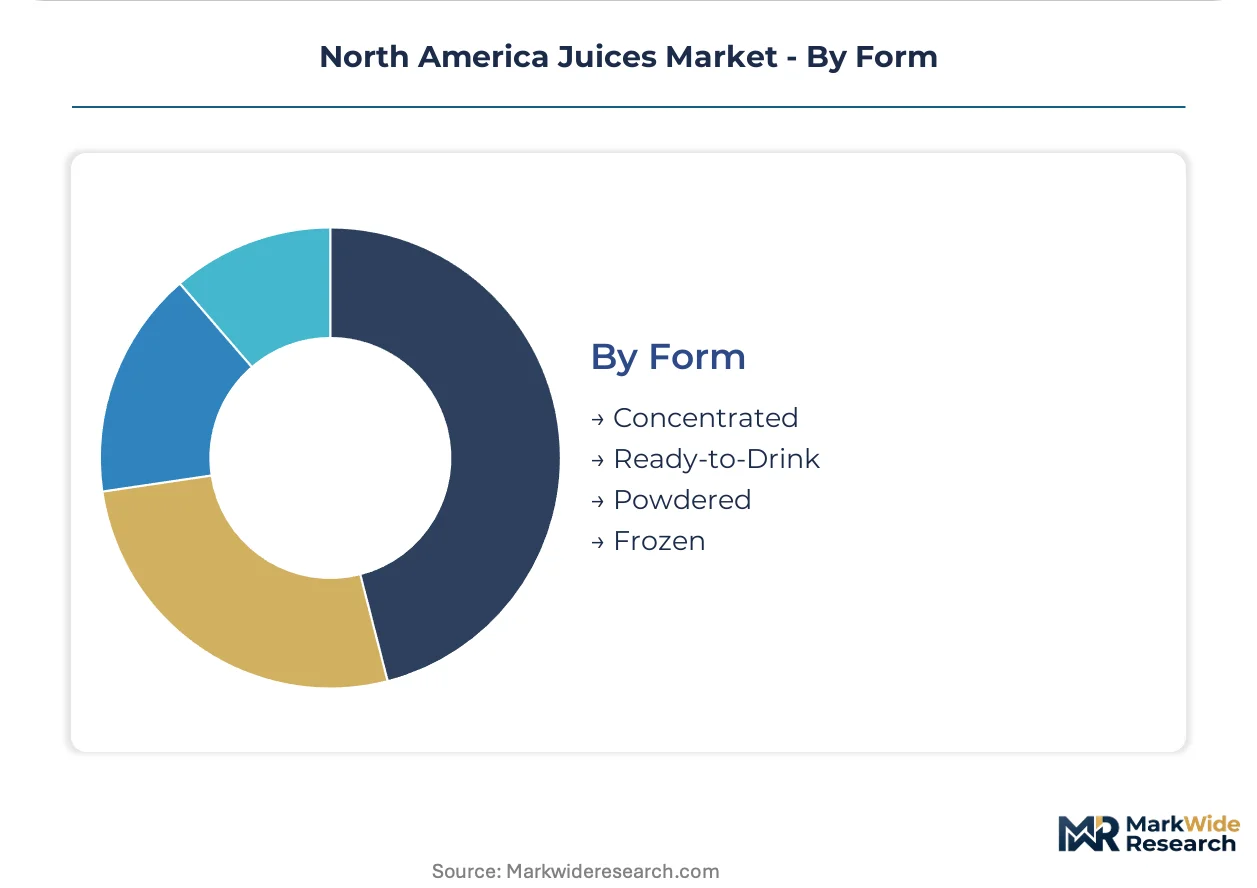
Form:
Form selection correlates with supply chain configuration, with concentrated formats sustaining margin advantages in bulk institutional supply while ready-to-drink commands retail shelf presence.
- Ready-to-Drink:Single-serve and multi-serve chilled or ambient beverages. PepsiCo's Gatorade manufacturing network enables sports-positioned juice hybrid production at scale.
- Concentrated:Frozen or ambient concentrates requiring dilution prior to consumption. Florida processors rely on São Paulo suppliers, exposing margins to currency volatility and harvest fluctuations.
- Frozen:Extended shelf-life formats for foodservice bulk procurement. Brazilian orange concentrate dependency shapes raw material flows.
- Powdered:Dehydrated extracts targeting institutional and emergency preparedness applications. Lower logistics intensity supports remote distribution economics.
Ready-to-Drink dominates volume, with Concentrated sustaining institutional margin advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined sanitary registration and lower compliance costs. Mexico's COFEPRIS modernization and Canada's Health Canada alignment create distinct cost-of-compliance tiers that influence cross-border investment flows.
United States
California's innovation corridor and Texas metropolitan clusters drive cold-pressed juice premiumization through fitness-studio distribution partnerships. FDA's added-sugar disclosure mandates are compressing formulation timelines for children's SKUs and cocktail mixers. Florida's citrus processing infrastructure is decoupling from historical grove acreage as Brazilian concentrate imports reshape raw material sourcing patterns.
Canada
Health Canada and CFIA enforce strict identity requirements that differentiate pure juice from beverages with juice content, creating premium certification tiers. Manitoba and Saskatchewan exhibit juice consumption per capita 40% below Ontario levels, signaling white-space distribution potential. Toronto's metropolitan corridor anchors cold-pressed subscription logistics for fitness-studio delivery models.
Mexico
Oxxo and Soriana distribution networks are expanding shelf space for price-accessible nectar formats as COFEPRIS streamlines sanitary registration for imported products. Mexico City Metro concentrates demand for grab-and-go chilled beverages through convenience-store velocity. Northern Border States are absorbing cross-border logistics investments from US manufacturers seeking tariff-advantaged production positioning.
North America Juices Market Competitive Landscape
United States producers anchor the scale-driven tier; Canadian and Mexican specialists hold regional distribution advantages through regulatory proximity. The vendor base concentrates around beverage conglomerates with refrigerated logistics footprints and cooperative-structured procurement networks. Two strategic archetypes dominate: diversified beverage conglomerates leveraging manufacturing network synergies, and cooperative-organized specialists controlling upstream agricultural supply. Competitive moves center on cold-pressed processing capacity expansion and direct-to-subscription channel development that bypasses traditional retail slotting economics.
Within the diversified conglomerate tier, PepsiCo Inc. and The Coca-Cola Company exemplify scale-driven positioning through extensive refrigerated distribution infrastructure. Ocean Spray Cranberries Inc. represents the cooperative-structured archetype with upstream berry supply control. These three entities anchor competitive dynamics across conventional retail, foodservice, and emerging subscription channels.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| The Coca-Cola Company |
| Tropicana Brands Group |
| Keurig Dr Pepper Inc. |
| Ocean Spray Cranberries Inc. |
| The Kraft Heinz Company |
| Campbell Soup Company |
| Naked Juice |
| Bolthouse Farms |
| Others |
Pricing and Supply Chain Analysis
Brazilian frozen orange concentrate feeds through São Paulo suppliers into Florida processors, translating currency volatility and harvest fluctuations into margin compression across private-label and mid-tier branded tiers. Packaging materials—glass and PET resin—absorb 35-45% of cost-of-goods-sold, transmitting petrochemical feedstock spikes directly into shelf-price adjustments and SKU rationalization decisions.
Pricing Analysis
Distributor margins in the supermarket channel absorb slotting fee intensity and refrigerated case infrastructure costs, compressing net returns for mid-tier brands. Three-tier pricing structure across premium, standard, and economy levels separates HPP-processed cold-pressed SKUs from conventional pasteurized lines and private-label concentrates. Price differentiation hinges on organic certification tier and clean-label processing technology. Cost compression in the economy nectar segment is intensifying because Mexican retail modernization accelerates price-accessible volume. Foodservice buyers exhibit highest price sensitivity due to reformulation timeline pressures, while health-club subscription channels show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with São Paulo suppliers for frozen orange concentrate, exposing North American processors to Brazilian real volatility and citrus greening disease impacts. Geographic supply concentration centers on Brazil for citrus inputs, Mexico for tropical fruit purees, and California for domestic berry and vegetable bases. Raw material dependencies rest on PET resin, glass containers, and high-pressure processing equipment imports. Tariff exposure runs through US-Mexico-Canada Agreement rules-of-origin compliance for cross-border concentrate movements. Distribution runs through PepsiCo and Coca-Cola refrigerated logistics networks, cooperative-structured procurement for cranberry, and direct-to-subscription cold-chain startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America juices market functions as a stable compounder, with FDA disclosure mandates and millennial functional beverage demand sustaining steady premiumization cycles across the forecast window.
For Market Incumbents: Anchor shelf position through HPP capacity expansion in California and Texas corridors, defending against cold-pressed startup encroachment. Deepen backward integration into organic grove supply to bypass USDA certification backlogs constraining certified juice growth. Control slotting economics in Kroger and Safeway banners through private-label blocking strategies and promotional fund concentration. For New Entrants and Emerging Players: Capture white-space in Canada's prairie provinces, where Manitoba and Saskatchewan per-capita consumption trails Ontario by 40 percentage points. Target direct-to-subscription delivery to corporate wellness programs and fitness studios, bypassing traditional retailer margin requirements. Lead with vegetable-forward blends—carrot-citrus and beet-berry formulations—masking reduced sugar with clean-label positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative-structured procurement networks face generational ownership transitions and refrigerated logistics capex intensity strains balance sheets. Five-to-ten year viability favors targets with captive organic supply and HPP equipment installed base. Watch cold-pressed subscription churn rates as inflection indicator for channel economics sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Capacity Expansion | Enables extended distribution radii for perishable products without preservatives. |
| Direct-to-Subscription Launch | Bypasses slotting fees through weekly delivery to fitness studios and corporate campuses. |
| Vegetable-Forward SKU Introduction | Captures reduced-sugar demand through carrot, beet, and celery bases masked with citrus. |
| Backward Integration into Organic Supply | Secures certified juice growth against three-year grove transition backlogs. |
| Prairie Distribution Channel Expansion | Addresses 40% per-capita consumption gaps in Manitoba and Saskatchewan versus Ontario. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with juice category managers at PepsiCo and Coca-Cola, procurement leads at Kroger and Safeway, COFEPRIS registration specialists, and cold-pressed startup founders with secondary validation. Nielsen retail audit data, FDA labeling guidance documents, USDA organic certification records, and Brazilian agricultural export statistics anchored supply-side and demand-side calibration. Bottom-up SKU-level volume builds and top-down macroeconomic scenario triangulation converged on segment-level estimates.
Comparable-period anchoring tied projection assumptions to historical reference intervals across the modeling period, with growth rates derived from segment-specific elasticity models rather than extrapolation. Segmentation dimensions included product type, distribution channel, end-user occasion, and form factor, with regulatory compliance tier and processing technology as industry-specific overlays. Forecast inputs incorporated FDA added-sugar disclosure implementation timelines, HPP equipment capacity expansion trajectories, and COFEPRIS registration velocity for imported products.
Currency volatility in Brazilian real-US dollar pairings, citrus greening disease progression, and state-level container deposit legislation fragmentation are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Dairy Beverages Market
Beverages
Ready to Drink Premixes Market
Beverages
Europe Smoothies Market
Beverages
North America Yerba Mate Market
Beverages
Europe Beverage Market
Beverages
Reconstituted Juice Market
Beverages
Global Squash Drinks Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Germany Probiotic Drinks Market
Beverages
Collagen-Infused Water Market
Beverages
Semillon Market
Beverages
India Sports Drinks Market
Beverages
Middle East Energy Drinks Market
Beverages
Bottled Water Processing Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Fruit Water Market