
 South America Ready to Drink Beverages Market | 2026-2036
South America Ready to Drink Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ready to Drink Beverages Market Analytics
Market Dynamics
Asset-light contract manufacturing and third-party co-packing arrangements is reconfiguring competitive entry barriers across the South America Ready to Drink Beverages Market. Ambev leverages its captive bottling infrastructure to dominate Brazil's retail shelf space. PepsiCo sustains regional relevance through deep convenience store partnerships in Colombia and Peru. The Coca-Cola Company anchors premium positioning via controlled cold-chain distribution networks.
Product Landscape
Ready to Drink Beverages comprise pre-formulated, shelf-stable or refrigerated drinks packaged in cans, PET bottles, or cartons for immediate consumption without preparation, typically requiring aseptic filling or hot-fill processing to ensure microbiological safety. Energy Drinks command the highest per-unit margins while Iced Tea volumes expand fastest among health-conscious segments. Flavored Water competes aggressively in mid-range Price Tier slots, whereas E-commerce penetration accelerates fastest in urban Consumer Segment clusters of on-the-go professionals.
Regulatory Environment
ANVISA governs ingredient safety and front-of-package warning labels in Brazil, while Argentina's national food code authority enforces parallel sugar disclosure mandates that constrain formulation flexibility. Peru's DIGEMID and Chile's Ministry of Health apply additional caffeine thresholds and advertising restrictions that shape product portfolios. Stakeholders must monitor pending harmonization talks between Mercosur member states that could unify compliance costs or fragment them further.
Market Dynamics
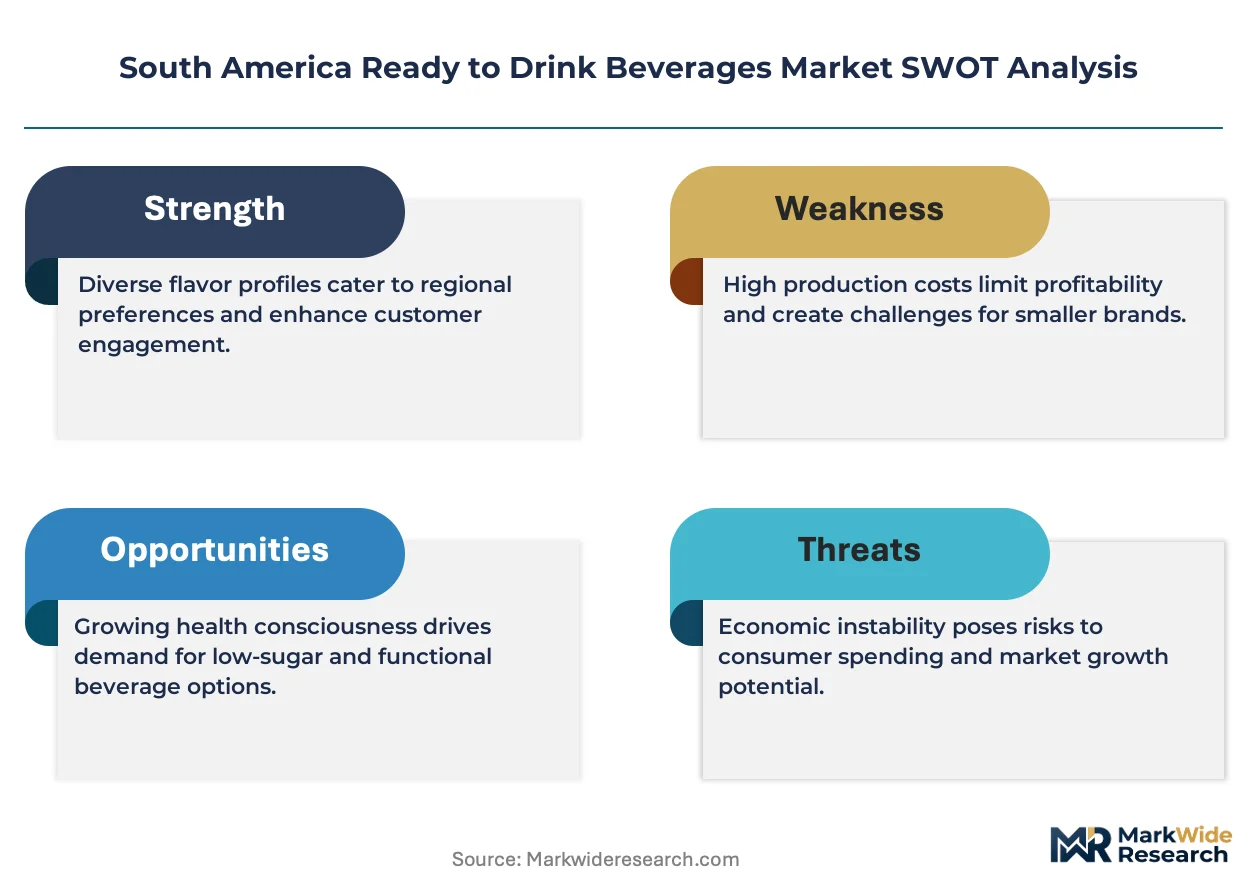
ANVISA's front-of-package sugar warning labels are forcing reformulation across Brazil's ready to drink portfolio, compressing profit margins while accelerating clean-label innovation cycles throughout the Mercosur trade zone.
Growth Catalysts
- Functional ingredient integration:Adaptogens and nootropics are penetrating energy drink formulations as urban professionals in São Paulo seek cognitive performance benefits from convenience formats.
- Argentina's sugar disclosure mandates:The national food code authority's parallel labeling requirements are creating harmonized compliance pathways that reduce cross-border formulation costs for regional producers.
- Third-party co-packing infrastructure:Asset-light contract manufacturing networks in Colombia and Peru are lowering capital barriers for niche brand entry into convenience store channels.
Market Restraints
- High-fructose corn syrup price volatility:Input cost swings tied to Brazilian agricultural commodity cycles constrain margin predictability for mid-tier producers.
- Cold-chain distribution concentration:Premium refrigerated beverage segments depend on infrastructure concentrated in Brazil's southeastern corridor, limiting geographic expansion.
- Caffeine threshold compliance:Peru's DIGEMID enforces strict limits that fragment product portfolios and prevent standardized regional SKUs.
Strategic Opportunities
- Chilean functional water penetration:The Ministry of Health's progressive regulatory framework permits novel ingredient claims that remain restricted elsewhere in South America.
- E-commerce direct-to-consumer channels:Urban professional clusters in Buenos Aires and Santiago are adopting subscription models for specialized functional beverages.
- Aseptic carton technology convergence:Hot-fill processing advances combined with plant-based packaging materials are opening shelf-stable premium positioning.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise for reduced-sugar stability without artificial sweeteners remains scarce across regional R&D centers.
- Mercosur harmonization timeline uncertainty:Pending trade bloc negotiations create compliance planning paralysis for multi-country product launches.
- Legacy distributor integration friction:Traditional wholesale networks resist data-sharing requirements for demand-forecasting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ready to Drink Beverages Market |
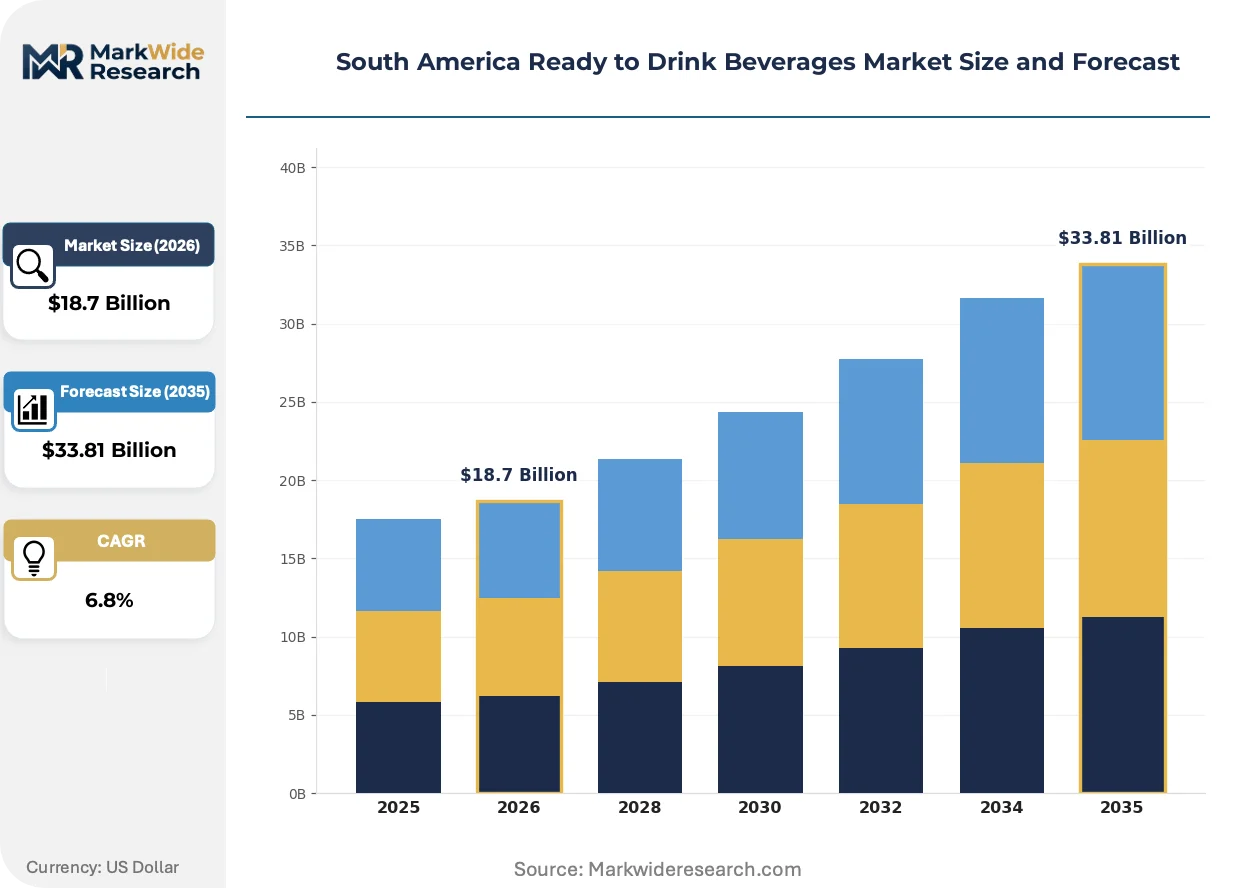
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iced Tea, Coffee Drinks, Energy Drinks, Flavored Water Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Food Service Price Tier: Premium, Mid-range, Budget, Value Packs Consumer Segment: Health-conscious Consumers, On-the-go Professionals, Students, Families |
| Companies Covered | Monster Beverage Corporation, WOW! Nutrition, The Coca-Cola Company, Ambev, Red Bull GmbH, Diageo plc, PepsiCo Inc, Alpina Productos Alimenticios SA, Nestle SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ready to Drink Beverages Market Evolving Landscape
Digital traceability systems are penetrating South American beverage supply chains, enabling real-time ingredient provenance verification that responds to consumer safety concerns and regulatory audit requirements.
Aseptic filling technology is digitizing quality assurance protocols across Brazilian production facilities. Mid-sized processors in Minas Gerais are retrofitting lines with IoT-enabled microbiological monitoring systems. This infrastructure investment is compressing batch release timelines from days to hours while satisfying ANVISA's escalating documentation demands.
Chile's Ministry of Health has tightened advertising restrictions on caffeine-containing beverages targeting adolescents. The regulatory friction is redirecting marketing expenditure toward adult functional benefit claims. Energy drink portfolios are pivoting toward workplace productivity positioning rather than youth lifestyle associations.
Urban convenience purchasing patterns are fragmenting traditional channel hierarchies. On-the-go professionals in São Paulo and Buenos Aires are bypassing supermarkets for automated retail and delivery apps. This behavioral rotation is forcing reformulation toward single-serve portability and ambient stability for non-refrigerated distribution points.
South America Ready to Drink Beverages Market Segmentation
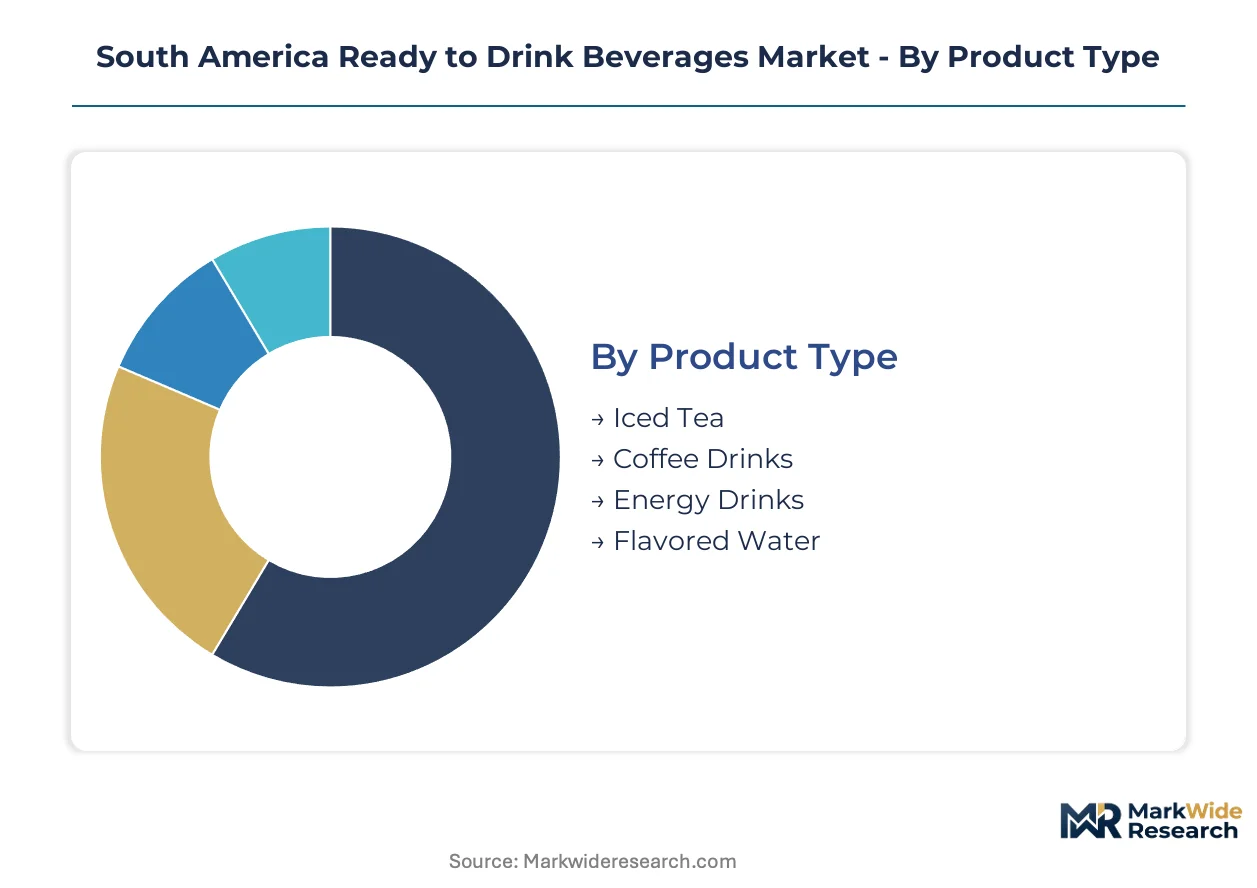
Segmentation in South America's ready-to-drink beverages market exposes divergent margin profiles and channel requirements. Distinct formulation, packaging, and distribution strategies apply to each category, with regulatory compliance costs varying sharply across product types and price tiers.
Product Type:
After-sales service intensity concentrates in refrigerated segments requiring cold-chain maintenance and freshness guarantees, while shelf-stable formats demand minimal post-purchase support.
- Energy Drinks:Caffeine-forward formulations with taurine and B-vitamin complexes dominate functional positioning. Demand clusters among on-the-go professionals in São Paulo's financial district, driven by workplace productivity culture and extended commuting patterns. ANVISA's caffeine disclosure mandates constrain label claims and force reformulation for cross-border Mercosur compliance.
- Flavored Water:Low-calorie fruit-infused variants with natural flavor systems and carbonation or still bases. Health-conscious consumers in Buenos Aires and Santiago are displacing sugary sodas, though clean-label stability without preservatives challenges regional food technologist capacity.
- Iced Tea:Brewed tea extracts with cane sugar or stevia sweetening, positioned as natural alternatives to carbonated soft drinks.
- Coffee Drinks:Cold brew and dairy-based RTD formats targeting premium convenience channels.
By volume, Energy Drinks leads. By growth pace, Flavored Water is ahead.
Distribution Channel:
Channel economics vary by working capital intensity, with direct-store-delivery models demanding higher operational investment than centralized warehousing approaches.
- Convenience Stores:Small-format retail with high turnover velocity and impulse-driven purchasing. São Paulo and Rio de Janeiro's urban corridors concentrate refrigerated grab-and-go placement, where single-serve pricing premiums offset slotting fees. Ambev's captive distribution secures preferential shelf positioning.
- E-commerce:Direct-to-consumer and marketplace platforms with subscription mechanics. Buenos Aires and Santiago professional clusters adopt recurring delivery for functional beverage portfolios, though last-mile refrigeration constraints limit SKU expansion.
- Supermarkets:Multi-brand retail with promotional pricing cycles and family-size pack concentration.
- Food Service:On-premise consumption channels including cafés, quick-service restaurants, and workplace catering.
Supermarkets capture the largest revenue base. E-commerce is climbing the fastest.
Price Tier:
Margin architecture separates captive ingredient sourcing capabilities from commodity-dependent competitors, with premium tiers rewarding formulation differentiation and budget tiers rewarding scale economics.
- Premium:Positioning above mainstream price points through novel ingredients, controlled-origin sourcing, or functional claims. Chile's progressive regulatory framework permits adaptogen and nootropic labeling that remains restricted under ANVISA and DIGEMID, creating geographic pricing arbitrage.
- Mid-range:Volume-heavy positioning balancing quality signals with mass-market accessibility. Brazil's southeastern corridor concentrates this tier's competitive intensity.
- Budget:Price-driven placement with minimized ingredient costs and standardized formulations.
- Value Packs:Multi-unit bundling for household stockpiling and pantry loading behaviors.
Mid-range holds the deepest volume. Premium is gaining share fastest.
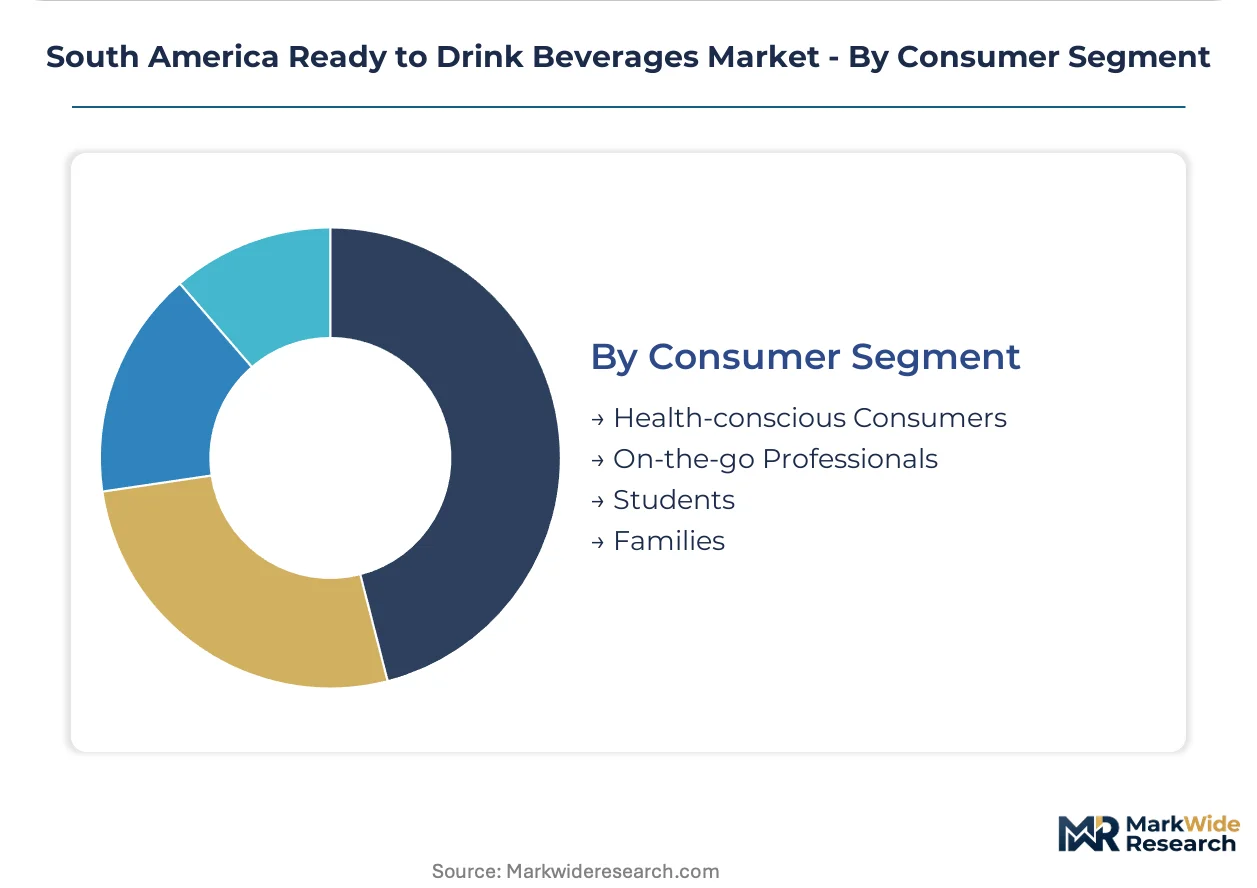
Consumer Segment:
Usage occasion and benefit expectations determine formulation priorities, with professional segments prioritizing functional efficacy and family segments prioritizing value and safety assurances.
- On-the-go Professionals:Time-constrained urban workers seeking portable energy and cognitive support. São Paulo's Pinheiros and Itaim Bibi districts concentrate automated retail adoption and delivery app usage for RTD replenishment.
- Health-conscious Consumers:Label-attentive purchasers prioritizing reduced sugar, natural ingredients, and transparent sourcing. Argentina's front-of-package warning mandates accelerate this segment's displacement of conventional soft drinks.
- Students:Price-sensitive demand with high caffeine tolerance and social consumption patterns.
- Families:Multi-person household purchasing with bulk-buying preferences and child-safe formulation requirements.
On-the-go Professionals drives premium volume. Health-conscious Consumers shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southeastern corridor generates surplus production capacity that supplies neighboring Mercosur markets, while Argentina's persistent currency volatility creates import substitution pressures that reshape cross-border trade flows.
Brazil
São Paulo state's automated retail density and Pinheiros district professional clusters drive premium functional beverage uptake. ANVISA's front-of-package sugar warning labels force reformulation across Minas Gerais processing facilities. Rio de Janeiro's convenience store networks concentrate cold-chain distribution investment for refrigerated RTD segments.
Argentina
Buenos Aires urban professionals adopt subscription delivery models for specialized functional beverages at accelerating rates. The national food code authority enforces parallel sugar disclosure mandates that create compliance harmonization with Brazilian standards. Córdoba's dairy processing heritage anchors RTD coffee drink manufacturing expansion.
Chile
Santiago's health-conscious consumer clusters displace conventional soft drinks with flavored water and adaptogen-infused formats. The Ministry of Health permits novel ingredient claims restricted elsewhere in South America, creating regulatory arbitrage for premium positioning. Valparaíso's port infrastructure facilitates ingredient import efficiency for regional formulation centers.
Colombia
Bogotá's convenience store partnership networks sustain mid-range price tier volume distribution. Third-party co-packing infrastructure lowers capital barriers for niche brand entry into urban retail channels. Medellín's beverage processing clusters leverage asset-light manufacturing to serve Andean market demand.
Peru
Lima's on-the-go professional segments drive energy drink consumption despite DIGEMID caffeine threshold constraints. Strict regulatory limits fragment product portfolios and prevent standardized regional SKU deployment. Arequipa's emerging processing capacity targets export-oriented production for southern cone markets.
South America Ready to Drink Beverages Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and packaging supply. Brazil's RTD beverage structure concentrates around captive bottling infrastructure and deep convenience store partnerships. Three archetypes dominate: multinational beverage conglomerates with integrated distribution, regional dairy and coffee processors leveraging existing cold-chain assets, and energy drink specialists relying on third-party co-packing networks. Competitive moves center on portfolio diversification into functional claims and geographic expansion through Mercosur trade bloc leverage.
Within the multinational tier, Monster Beverage Corporation and Red Bull GmbH exemplify energy-focused specialists navigating regulatory fragmentation across ANVISA and DIGEMID jurisdictions. The Coca-Cola Company anchors premium positioning through controlled cold-chain networks, while Ambev leverages captive bottling infrastructure to dominate Brazil's retail shelf space. PepsiCo sustains regional relevance through convenience store partnerships in Colombia and Peru. Nestle SA and Diageo plc occupy positions spanning dairy-based RTD coffee and adult beverage adjacencies respectively.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| WOW! Nutrition |
| The Coca-Cola Company |
| Ambev |
| Red Bull GmbH |
| Diageo plc |
| PepsiCo Inc |
| Alpina Productos Alimenticios SA |
| Nestle SA |
| Others |
Value Network & Pricing Analysis
The São Paulo-Rio de Janeiro refrigerated logistics corridor anchors cost dynamics across Brazil's RTD beverage market, with per-kilometer cold-chain premiums concentrating supply among Ambev's captive distribution networks while forcing price differentiation between ambient-stable and refrigerated formats throughout Mercosur trade flows.
Pricing Analysis
On-the-go professionals anchor premium pricing power in São Paulo's automated retail corridors, where single-serve functional beverages command three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ANVISA compliance certification tiers and cold-chain delivery guarantees. Cost compression in mid-range flavored water is intensifying because high-fructose corn syrup input volatility squeezes contract manufacturers. Students show highest price sensitivity; health-conscious consumers in Santiago demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Brazilian retail consolidators strain working capital for Minas Gerais processors, accelerating supply-chain finance facility adoption among third-party co-packers. Geographic supply concentrates in Brazil, Argentina, and Chile. Raw material dependencies center on cane sugar, stevia extracts, and aseptic carton substrates. Single-source vulnerability runs through Brazilian high-fructose corn syrup processors exposed to agricultural commodity cycles. Distribution runs through Ambev's captive direct-store-delivery networks and PepsiCo's convenience store partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail networks in Brazil's southeastern corridor, with supermarket and convenience store chains extracting slotting fee concessions that fragment margin pools for mid-tier producers.
For Market Incumbents: Build regulatory compliance moats through ANVISA certification investments that emerging entrants cannot replicate quickly. Deepen cold-chain infrastructure in São Paulo and Rio de Janeiro to defend against third-party co-packing challengers. Capacity addition in Minas Gerais processing clusters reinforces formulation control over adaptogen stability. For New Entrants and Emerging Players: Establish a beachhead in Chile's functional water segment where progressive Ministry of Health labeling permits novel ingredient claims restricted under ANVISA and DIGEMID. Subscription direct-to-consumer channels in Buenos Aires professional clusters offer lowest customer acquisition friction against incumbent shelf-space dominance. For Investors and Strategic Acquirers: Asset-light contract manufacturers with established convenience store relationships in Colombia and Peru represent acquisition targets with platform expansion potential. Long-term viability hinges on Mercosur regulatory harmonization progress; the signal to watch is ANVISA-DIGEMID caffeine threshold alignment talks.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | ANVISA sugar warning mandates force portfolio-wide ingredient replacement without artificial sweetener stability gaps. |
| Cold-Chain Infrastructure Expansion | Refrigerated RTD segments depend on São Paulo-Rio corridor density for freshness guarantees and premium positioning. |
| Subscription Model Launch | Buenos Aires and Santiago professional clusters adopt recurring delivery for specialized functional beverages. |
| Third-Party Co-Packing Partnership | Asset-light manufacturing in Colombia and Peru lowers capital barriers for niche brand convenience store entry. |
| Mercosur Compliance Harmonization | Pending trade bloc negotiations determine whether regional SKU standardization reduces cross-border formulation costs. |
Research Methodology
Desk research of ANVISA regulatory filings, customs trade records, and Nielsen retail audit data preceded structured interviews with beverage brand managers, category buyers at Brazilian supermarket chains, third-party co-packing facility operators, and food technology R&D directors. Primary fieldwork across São Paulo, Buenos Aires, and Santiago validated secondary estimates through bottom-up volume triangulation against top-down trade flow analysis.
Assumptions held fixed include ANVISA labeling enforcement timelines, Mercosur tariff structures, and Brazilian agricultural commodity price bands; variables stress-tested spanned currency volatility in Argentina and Peru, DIGEMID caffeine threshold adjustments, and cold-chain logistics cost inflation. The analytical framework modeled product type, distribution channel, price tier, and consumer segment dimensions across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory shock impacts and urban professional segment penetration curves.
Stress conditions across high-fructose corn syrup price bands, Argentine peso depreciation scenarios, and Chilean functional claim regulatory scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Kombucha Market
Beverages
Cold Pressed Juice Market
Beverages
Milk Tea Powder Market
Beverages
Chocolate Malt Drink Market
Beverages
Fruit Water Market
Beverages
Gluten Free Beverages Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Asia-Pacific Juices Market
Beverages
Ginger Ale Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Herb Infused Water Market
Beverages
China Orange Juice Market
Beverages
Fruit Juices and Nectars Market
Beverages
United States Smoothie Market
Beverages
Europe Animal-Based Food and Beverage Market