
 North America Ready-To-Drink (RTD) Beverages Market | 2026-2036
North America Ready-To-Drink (RTD) Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ready-To-Drink (RTD) Beverages Market Insights
FDA nutrition labeling reform is shifting the cost-of-entry calculus for new RTD entrants, forcing reformulation investments before products reach retail shelves. PepsiCo leverages its bottling infrastructure to sustain distribution density across convenience channels. Nestle S.A. anchors its portfolio in functional coffee and tea blends that command premium placement. Danone S.A. competes through specialized probiotic and protein-forward offerings that differentiate beyond conventional refreshment.
Ready-to-drink beverages are commercially prepared, single-serve liquid refreshments packaged in aluminum cans, glass bottles, or polyethylene terephthalate containers, manufactured through aseptic cold-filling or hot-fill processes to ensure shelf stability without consumer preparation. These products serve industrial and commercial purposes by capturing impulse purchases in away-from-home consumption occasions and replacing traditional preparation time with immediate gratification. Soda and tea categories occupy mature volume positions with established manufacturing scale, while coffee and juice segments attract faster growth as functional ingredient integration expands margin pools. Distribution through supermarkets sustains baseline volume, though online retail and convenience stores capture shifting purchase patterns toward smaller basket sizes and immediate need fulfillment.
The FDA governs ingredient safety and nutrition disclosure, while USDA organic certification shapes premium positioning, and state-level container deposit laws in California and New York influence packaging material decisions across the value chain. These regulatory layers elevate compliance costs but simultaneously create structural barriers that protect incumbent scale advantages. Stakeholders must monitor evolving sugar taxation proposals and extended producer responsibility legislation that could restructure cost allocation between manufacturers and packaging suppliers.
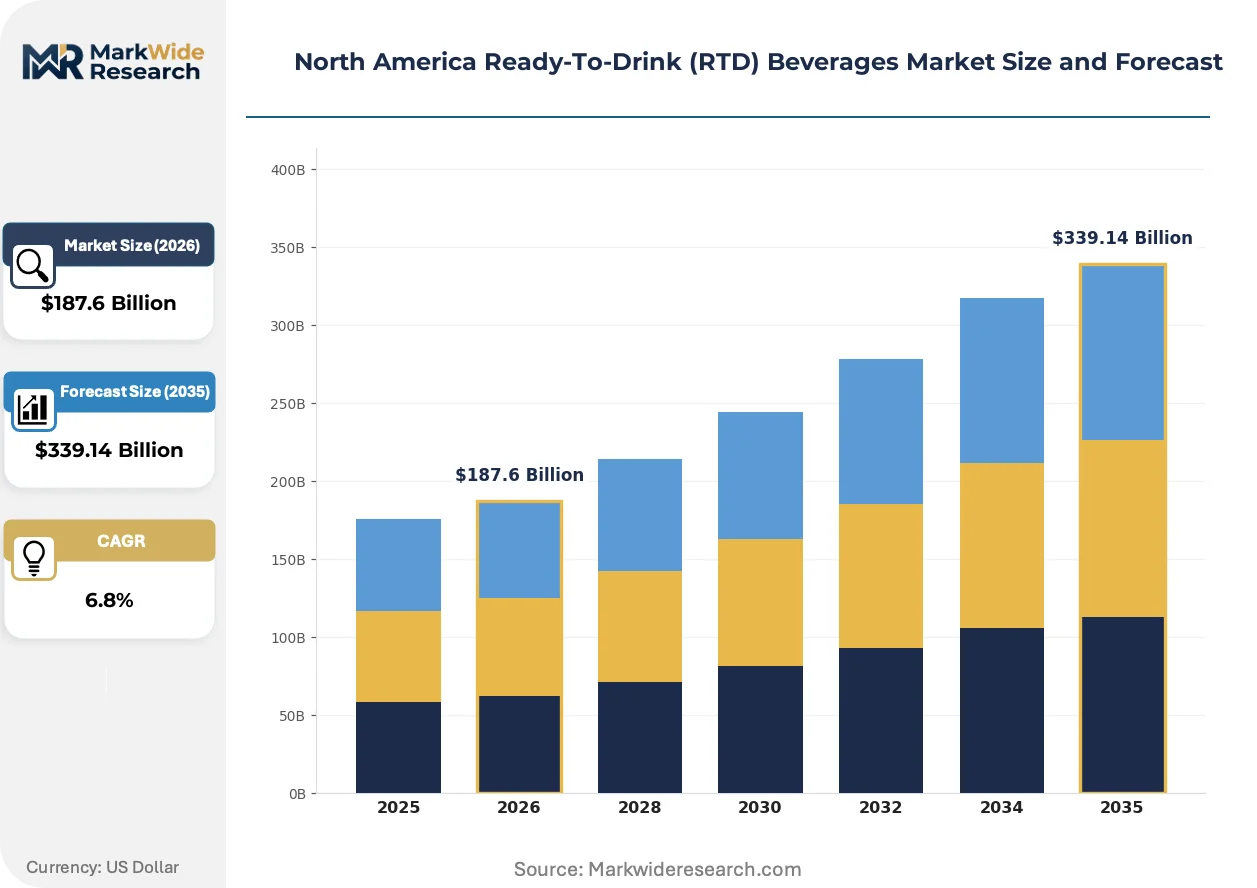
Market Dynamics
FDA's updated nutrition labeling requirements for added sugars are forcing reformulation investments across the North America RTD Beverages Market, elevating compliance costs while creating structural barriers that protect incumbent scale advantages and reshape competitive entry calculus.
Growth Catalysts
- Convenience channel expansion:Convenience stores are expanding shelf space for chilled single-serve formats across the US Sun Belt states, capturing impulse purchases in away-from-home consumption occasions.
- USDA organic certification:Premium positioning through USDA organic certification commands price premiums in functional coffee and tea segments, attracting margin-focused portfolio investments.
- Functional ingredient integration:Probiotic and protein-forward formulations are expanding margin pools beyond conventional refreshment categories, differentiating products in saturated soda and tea segments.
Market Restraints
- Aluminum input cost volatility:Primary aluminum price swings directly compress packaging material margins, forcing hedging strategies or pass-through pricing negotiations with retail partners.
- State-level container deposit complexity:Divergent deposit laws in California and New York create fragmented packaging compliance requirements, elevating operational complexity for multi-state distribution.
- Sugar taxation proposals:Pending municipal and state-level sugar taxation initiatives threaten volume elasticity in sweetened beverage categories, constraining pricing flexibility.
Strategic Opportunities
- Extended producer responsibility legislation:Emerging EPR frameworks in Canada and select US states create first-mover advantages for manufacturers investing in closed-loop packaging systems and recycling infrastructure partnerships.
- Online retail channel penetration:Direct-to-consumer subscription models and e-commerce platforms capture shifting purchase patterns toward smaller basket sizes and immediate need fulfillment outside traditional retail.
- Hot-fill process innovation:Aseptic cold-filling technology convergence with barrier-enhanced PET formulations enables shelf-stable functional beverages without preservative dependency.
Industry Challenges
- Reformulation R&D timeline compression:FDA compliance deadlines accelerate product development cycles, straining sensory science and stability testing capabilities.
- Legacy bottling infrastructure retrofitting:Hot-fill to aseptic cold-fill line conversions demand capital-intensive equipment upgrades with extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ready-To-Drink (RTD) Beverages Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soda, Tea, Coffee, Juice Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Coffee Shops Form: Carbonated, Non-Carbonated, Ready-To-Serve, Concentrated Consumer Demographics: Millennials, Gen Z, Working Professionals, Fitness Enthusiasts |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestle S.A., Danone S.A., Diageo, Anheuser-Busch InBev, Keurig Dr Pepper, Constellation Brands, Bacardi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ready-To-Drink (RTD) Beverages Market Trends and Innovations
Aseptic cold-filling technology is actively reshaping manufacturing economics and product formulation possibilities across the North America RTD Beverages Market, enabling cleaner-label positioning while compressing thermal processing costs.
Cold aseptic filling systems utilizing hydrogen peroxide vapor sterilization are electrifying production line throughput capabilities for sensitive functional beverages. Mid-sized regional bottlers across Texas and Florida are adopting these systems at accelerated replacement cycles. This electrifying shift is compressing the cost gap between premium functional offerings and mass-market refreshment categories.
The FDA's updated nutrition labeling requirements for added sugars are mandating gram-level disclosure granularity that exposes hidden sweetener loads. Industrial consequence includes forced reformulation of legacy portfolios before products reach retail shelves. Functional coffee and tea segments in California and New York are responding fastest with stevia and monk fruit substitution programs.
Single-serve consumption patterns are fragmenting purchase occasions across convenience stores, gas stations, and micro-market vending. The traditional supermarket stock-up trip is losing share to immediate-need fulfillment in smaller format channels. This behavioral rotation is most visible in Sun Belt metropolitan corridors where on-the-go consumption dominates daily routines.
North America Ready-To-Drink (RTD) Beverages Market Segmentation
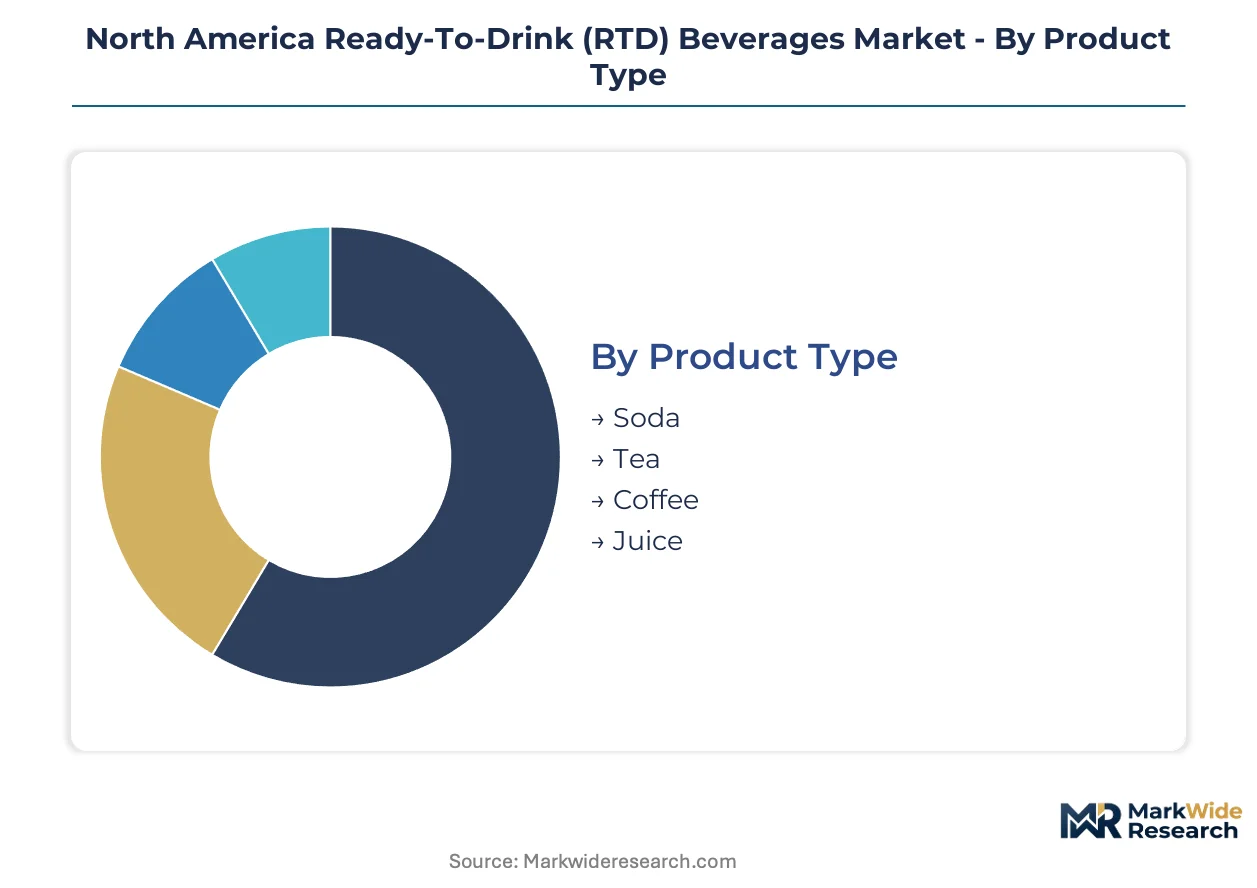
RTD beverage segmentation reveals divergent margin architectures across product categories and channel strategies. Volume-heavy soda and tea segments compete on manufacturing scale, while coffee and juice command premium positioning through functional ingredient integration.
Product Type:
The volume versus premium split separates mature refreshment categories from emerging functional formats with expanding margin pools.
- Soda:Carbonated formulations with established sweetener and flavoring systems dominate manufacturing throughput. Demand concentrates in convenience store impulse purchases across Texas and Florida, though FDA added-sugar labeling reform is accelerating reformulation toward zero-sugar variants.
- Tea:Ready-to-serve iced tea and functional blends with adaptogens or probiotics capture shelf-stable distribution advantages. Sun Belt metropolitan corridors anchor volume, with organic certification commanding placement premiums in California and New York specialty retailers.
- Coffee:Cold brew and nitro-infused formats with extended shelf stability through aseptic processing.
- Juice:Functional blends with protein fortification or probiotic cultures, constrained by shorter shelf life and cold-chain requirements.
Today's leader: Soda. Tomorrow's challenger: Coffee.
Distribution Channel:
Channel selection determines margin capture versus volume throughput, with immediate-need formats displacing traditional stock-up occasions.
- Supermarkets:Baseline volume sustains multi-pack and family-size formats with established slotting fee structures. Category management negotiations in Kroger and Albertsons banners favor incumbent scale players with full portfolio breadth.
- Convenience Stores:Single-serve chilled formats command impulse pricing premiums in Sun Belt gas station and urban micro-market locations.
- Online Retail:Direct-to-consumer subscription models and same-day delivery platforms capture smaller basket sizes outside traditional retail footprints.
- Coffee Shops:Branded RTD cooler placement in Starbucks and Dunkin' locations extends brand reach into away-from-home consumption.
Supermarkets retain volume dominance. Convenience stores are climbing the fastest in value contribution per square foot.
Form:
Carbonation status and preparation requirements segment manufacturing capital intensity and formulation flexibility.
- Carbonated:Pressurized filling lines with CO₂ injection systems require specialized bottling infrastructure. Legacy PepsiCo and Coca-Cola bottling networks sustain cost advantages in this format.
- Non-Carbonated:Still beverages including teas, juices, and functional waters with simpler filling requirements and lower packaging pressure tolerances.
- Ready-To-Serve:Single-serve consumption formats predominate in away-from-home channels with no dilution or preparation steps required.
- Concentrated:Syrup and dilution-base formats for fountain and foodservice applications with extended shelf stability.
Carbonated formats defend incumbent scale. Non-carbonated alternatives offer the steepest expansion trajectory for new functional entrants.
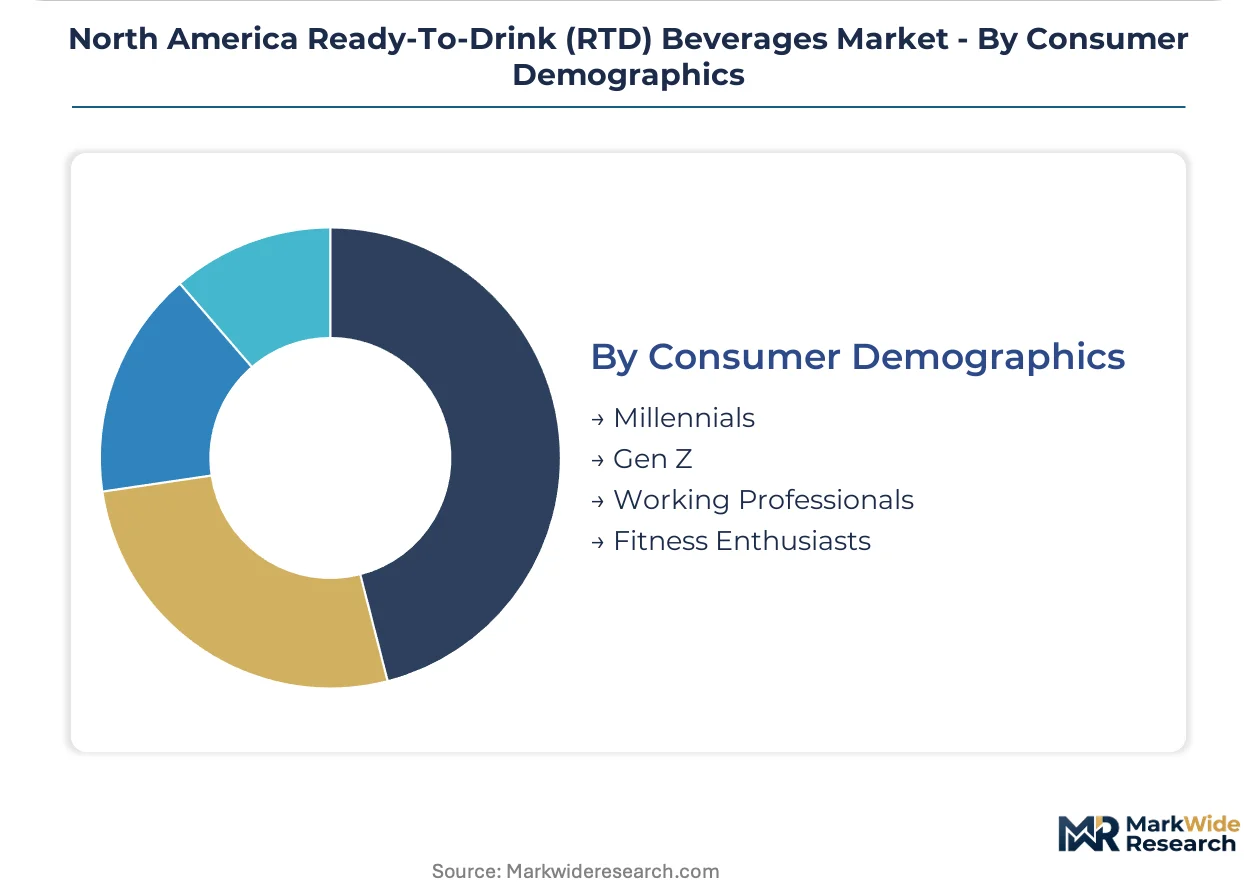
Consumer Demographics:
Generational and lifestyle segmentation maps occasion-based demand to product positioning and channel presence.
- Millennials:Premium functional coffee and organic tea purchases with price elasticity for clean-label positioning and sustainability credentials.
- Gen Z:Novel flavor innovation and TikTok-discovered brands with preference for bold formulations and limited-edition drops.
- Working Professionals:Caffeine-forward RTD coffee and energy blends for commute and workplace consumption occasions.
- Fitness Enthusiasts:Protein-fortified shakes and electrolyte-enhanced hydration with gym channel placement and subscription replenishment patterns.
Millennials anchor current premium spending. Gen Z is gaining share fastest as purchase influence expands into household buying decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentrated beverage formulation talent pools in the US Sun Belt and Canadian metropolitan corridors anchor North American RTD innovation capacity. Cross-border supply chains integrate Mexican bottling infrastructure with US flavor houses and Canadian distribution networks. Regulatory divergence between federal and state-level frameworks fragments compliance architecture across the continent.
United States
Sun Belt metropolitan corridors from Houston to Miami drive single-serve consumption velocity through year-round warm climates and commuter-heavy urban layouts. FDA added-sugar labeling mandates are accelerating reformulation timelines for legacy portfolios. Texas and Florida bottling clusters are retrofitting hot-fill lines to aseptic cold-fill systems to capture functional beverage growth.
Canada
Urban centers in Ontario and British Columbia sustain premium organic tea and functional coffee demand through health-conscious demographic concentrations. Health Canada and PMRA govern ingredient safety with stricter additive approval timelines than US counterparts. The Greater Toronto Area hosts specialized aseptic filling equipment suppliers serving cross-border RTD manufacturers.
Mexico
Glass bottle and aluminum can manufacturing clusters in Monterrey and Guadalajara supply North American packaging demand with integrated raw material access. Mexican beverage regulations under COFEPRIS align gradually with US FDA standards to facilitate export compatibility. The Bajío region's expanding industrial parks attract contract bottling investments from US brands seeking nearshore capacity.
California
Silicon Valley and Los Angeles metro areas incubate venture-backed functional beverage startups targeting wellness-oriented Millennials. State-level container deposit laws and sugar taxation proposals create the continent's most stringent compliance environment. The Central Valley's agricultural processing infrastructure supplies fruit concentrate inputs for juice and functional blend categories.
New York Metro
Financial services and media industry workforces sustain premium RTD coffee and energy beverage consumption during extended commute and office hours. New York's bottle deposit legislation predates most state frameworks and influences packaging material decisions. Brooklyn and Queens manufacturing zones host craft-scale cold brew operations with direct-to-retail distribution models.
North America Ready-To-Drink (RTD) Beverages Market Competitive Landscape
The competitive structure tilts toward diversified multinational conglomerates with captive bottling infrastructure and beverage-only specialists competing on formulation agility. Scale advantages concentrate in players owning aluminum can manufacturing partnerships and refrigerated distribution networks. Two strategic archetypes dominate: integrated beverage conglomerates leveraging cross-category portfolio breadth, and functional specialists commanding premium placement through ingredient innovation. Competitive moves center on aseptic line retrofitting investments and direct-to-consumer channel buildouts.
Within the integrated conglomerate tier, PepsiCo and The Coca-Cola Company exemplify scale-driven positioning through bottling network control and convenience channel density. Nestle S.A. and Danone S.A. occupy the functional specialist vector with coffee and probiotic-forward portfolios. Keurig Dr Pepper represents hybrid positioning bridging carbonated heritage with cold coffee expansion. These archetypes reflect divergent capital allocation priorities between manufacturing infrastructure and brand equity building.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestle S.A. |
| Danone S.A. |
| Diageo |
| Anheuser-Busch InBev |
| Keurig Dr Pepper |
| Constellation Brands |
| Bacardi Limited |
| Others |
Pricing and Supply Chain Analysis
Beverage formulation chemists and aseptic processing specialists concentrated in Texas and Florida bottling corridors create labor-cost differentials that widen pricing-tier spreads between mass-market refreshment and premium functional segments.
Pricing Analysis
Bundled direct-to-consumer subscription services versus unbundled single-serve convenience store purchases split pricing architectures across the North America RTD Beverages Market. Three-tier pricing structure across premium, standard, and economy levels separates functional coffee with adaptogen fortification from conventional iced teas and value-positioned sodas. Price differentiation hinges on USDA organic certification tier and refrigerated distribution density. Cost compression in economy-tier carbonated variants is intensifying because aluminum input volatility forces pass-through negotiations with retail partners. Value-conscious Gen Z consumers in Sun Belt gas station channels exhibit highest price sensitivity, while fitness enthusiasts demonstrate lowest elasticity for protein-fortified functional beverages.
Supply Chain Analysis
Refrigerated freight cost premiums between Mexican bottling clusters and US Sun Belt distribution centers compress margins on cold-chain-dependent juice and probiotic formats. Primary aluminum smelting concentrates in Canada, primary PET resin production anchors in US Gulf Coast petrochemical corridors, and aseptic filling equipment manufacturing clusters in Germany. Raw material dependencies draw from aluminum coil stock, high-barrier PET formulations, and natural flavor concentrates. Single-source vulnerability in specialized aseptic valve components creates procurement risk for mid-sized regional bottlers. Distribution runs through captive Coca-Cola and PepsiCo bottling networks for carbonated formats, while functional specialists rely on third-party cold-chain logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
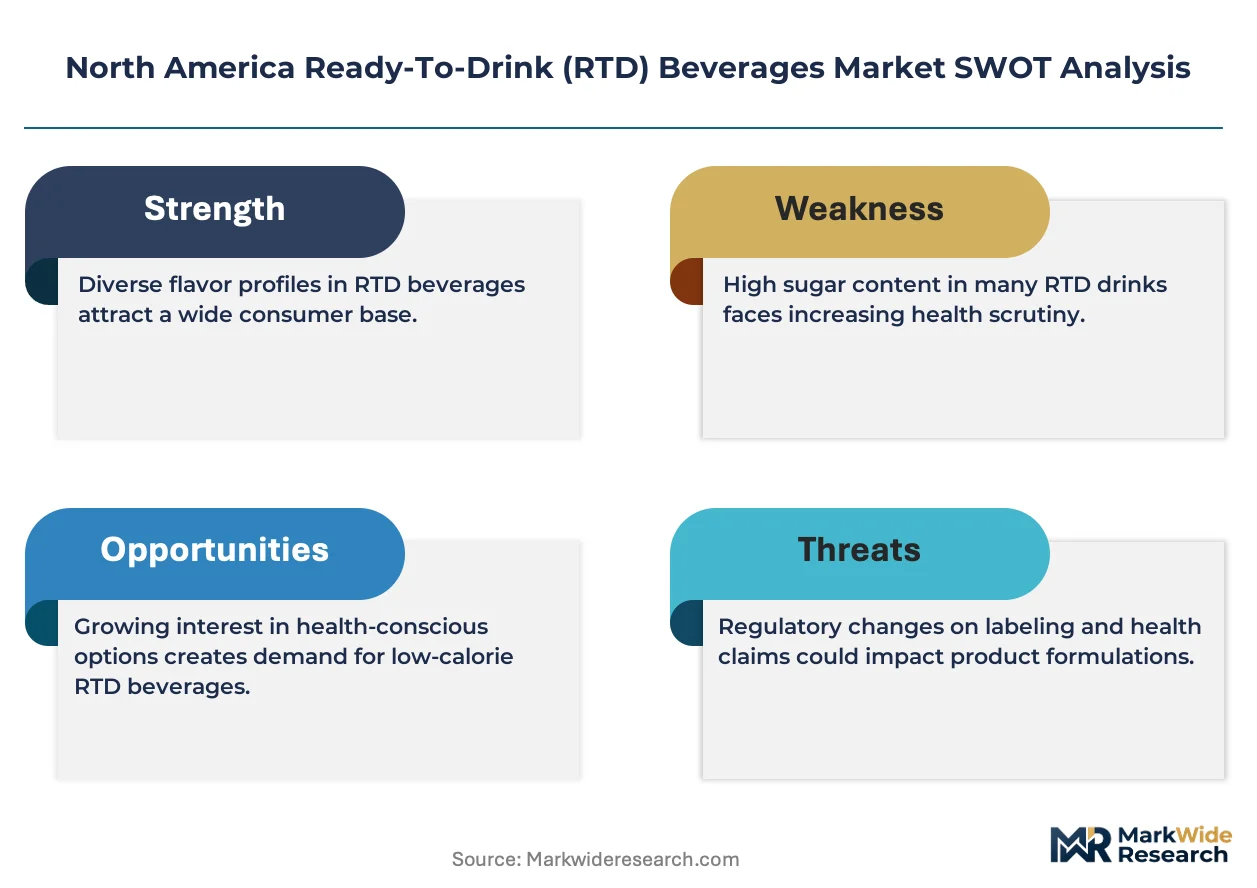
The North America RTD Beverages Market functions as a geographic-arbitrage play where FDA added-sugar labeling compliance costs in California and New York create 15-20% operating cost premiums versus Texas and Florida manufacturing bases.
For Market Incumbents: Anchor defensive positioning through captive aseptic cold-fill line retrofitting in Texas and Florida bottling corridors to capture functional beverage growth before emerging specialists scale. Accelerate zero-sugar reformulation timelines to preempt sugar taxation proposals in California and New York municipal jurisdictions. Vertical integration into aluminum can manufacturing partnerships mitigates primary metal price volatility threatening economy-tier soda margins. For New Entrants and Emerging Players: Convenience store distributors in Sun Belt metropolitan corridors represent the most accessible channel partners for functional coffee and probiotic-forward portfolios seeking immediate-need placement. Target underpenetrated gym and micro-market vending locations in Houston, Miami, and Phoenix for protein-fortified and electrolyte-enhanced formats. Pursue direct-to-consumer subscription models with same-day delivery partnerships to bypass incumbent slotting fee barriers in Kroger and Albertsons banners. For Investors and Strategic Acquirers: Integrated beverage conglomerates with cross-category portfolio breadth are the most active acquirer in this space, seeking functional specialists to fill premium positioning gaps. Long-term viability over a 5-10 year window rests on aseptic processing capabilities and organic certification infrastructure rather than brand equity alone. Monitor California sugar taxation proposal advancement as the critical inflection signal for reformulation investment urgency across sweetened beverage portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Line Retrofitting | Texas and Florida bottlers capture functional beverage margin expansion through hydrogen peroxide vapor sterilization adoption. |
| Zero-Sugar Reformulation Program | Stevia and monk fruit substitution pipelines address FDA added-sugar disclosure mandates before compliance deadlines. |
| Direct-to-Consumer Subscription Launch | Bypasses incumbent slotting fee structures while capturing smaller basket sizes outside traditional retail footprints. |
| USDA Organic Certification Investment | Commands placement premiums in California and New York specialty retailers for functional tea and coffee segments. |
| Closed-Loop Packaging Partnership | Extended producer responsibility frameworks in Canada create first-mover advantages for recycling infrastructure alignment. |
Research Methodology
Bottom-up convenience channel and online retail modeling reconciled against top-down bottling capacity and aluminum can production tracking forms the analytical core of this study. Primary interviews with beverage brand managers, category buyers at Kroger and Albertsons, aseptic processing equipment suppliers in the Greater Toronto Area, and cold-chain logistics operators combined with secondary validation. Secondary sources encompass FDA nutrition labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and SEC 10-K filings from publicly traded beverage conglomerates. Triangulation between demand-side consumption pattern analysis and supply-side manufacturing capacity assessment ensures forecast robustness.
Historical trendline analysis of volume throughput by product category and channel mix establishes baseline growth trajectories across the analysis window. Segmentation dimensions modeled include product type, distribution channel, carbonation status, and generational demographic with regional regulatory cluster overlay. CAGRs derive from weighted average of category-specific volume elasticities and value-per-unit expansion assumptions. Industry-specific forecast inputs incorporate FDA compliance timeline acceleration effects and Sun Belt climate-driven consumption seasonality patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sugar taxation proposal adoption rates and extended producer responsibility legislation implementation timing. Forecasts reflect documented assumptions regarding aluminum price stabilization and aseptic equipment commissioning schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Semillon Market
Beverages
Vegetable Juice Market
Beverages
Packaged Cactus Water Market
Beverages
Blackstrap Molasses Market
Beverages
Foaming Creamer Market
Beverages
Beverage Premix Market
Beverages
Blenders Market
Beverages
India Cafes & Bars Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
GCC Fruit Juice Market
Beverages
Double Valve Moka Pots Market
Beverages
Wellness Water Market
Beverages
Caffeinated Beverage Market
Beverages
Fermented Foods and Beverages Market
Beverages
Japan Energy Drink Market
Beverages
Bottled Beverages Market