
 Synthetic Food Preservatives Market | 2026-2036
Synthetic Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Food Preservatives Market Insights
Recurring formulation service contracts is shifting how preservative suppliers monetize relationships beyond bulk chemical sales. Cargill leverages its integrated ingredient platforms to bundle preservatives with texturizers and sweeteners for North American beverage clients. BASF SE anchors European supply through its Ludwigshafen manufacturing complex, where propionate output serves dairy processors across Germany and France. Kerry Group differentiates via clean-label positioning that navigates tightening consumer scrutiny of E-number additives in retail channels.
Synthetic food preservatives are chemically synthesized antimicrobial or antioxidant compounds, typically manufactured through organic acid fermentation or petrochemical routes, designed to inhibit microbial spoilage and oxidative rancidity in packaged foods. Sorbates dominate volume due to broad pH efficacy and established GRAS status across multiple jurisdictions, while benzoates command margin concentration in acidic beverage applications where lower dosage rates suffice. Powder and granular forms lead industrial procurement because of extended shelf stability and freight efficiency, though liquid concentrates are gaining traction in automated dosing systems at large meat processing facilities.
The FDA maintains its food additive petition process under 21 CFR, while the EMA and EFSA jointly evaluate preservative safety through reauthorization cycles under EU Regulation 1333/2008. China's SAMR enforces GB 2760 maximum usage levels, creating compliance friction for imported preservative blends. Stakeholders must monitor divergent residue limit trajectories across FDA, EFSA, and SAMR jurisdictions to avoid reformulation costs.
Market Dynamics
Recurring formulation service contracts are restructuring supplier-buyer relationships across the synthetic food preservatives value chain, moving revenue streams beyond commodity chemical sales toward integrated solution packages that bundle antimicrobial compounds with application-specific technical support.
Growth Catalysts
- EU Regulation 1333/2008 Reauthorization:Tightening maximum residue limits for sulfites redirect dairy and beverage formulators toward benzoate and propionate alternatives, expanding addressable demand for compliant preservative portfolios.
- Cold-Chain Infrastructure Buildout:Brazil, India, and Indonesia are expanding processed meat manufacturing capacity, driving procurement of sorbate-based preservation systems for ambient-stable packaged proteins.
- Encapsulation Technology Maturation:Microencapsulation of propionic acid enables controlled-release preservation in high-moisture bakery applications, extending functional performance windows for industrial bakers.
Market Restraints
- Petrochemical Feedstock Volatility:Propionic acid and benzoic acid production remains tethered to benzene and ethylene derivatives, exposing margin structures to crude oil price oscillations without viable bio-based substitution at scale.
- Clean-Label Substitution Pressure:Consumer rejection of E-number additives in Western European and North American retail channels compresses volume opportunity for synthetic antimicrobials in branded consumer packaged goods.
- SAMR Import Compliance Friction:China's GB 2760 maximum usage levels and registration requirements for imported preservative blends create documentation burdens and reformulation costs for foreign suppliers.
Strategic Opportunities
- Indonesian Poultry Processing Expansion:Domestic meatpackers are modernizing slaughter and further-processing operations, creating first-mover advantage for preservative suppliers offering integrated shelf-life extension protocols.
- Dual-Use Pharmaceutical-Food Grade Sorbates:Manufacturers with pharmaceutical-grade potassium sorbate capability can cross-serve injectable drug and high-purity food applications, capturing margin premiums in both segments.
- Automated Liquid Dosing Systems:Large Brazilian beef processors are retrofitting production lines with precision injection equipment, favoring liquid concentrate preservative formats over traditional powders.
Industry Challenges
- Reformulation Timeline Compression:Accelerated regulatory cycles under EFSA reauthorization protocols force R&D teams to validate alternative preservative systems within compressed windows, straining toxicology and stability testing resources.
- Clean-Label Technical Performance Gap:Natural antimicrobial alternatives demonstrate inconsistent efficacy across pH ranges and temperature abuse scenarios, requiring synthetic preservative suppliers to defend technical specifications against inferior substitutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Food Preservatives Market |
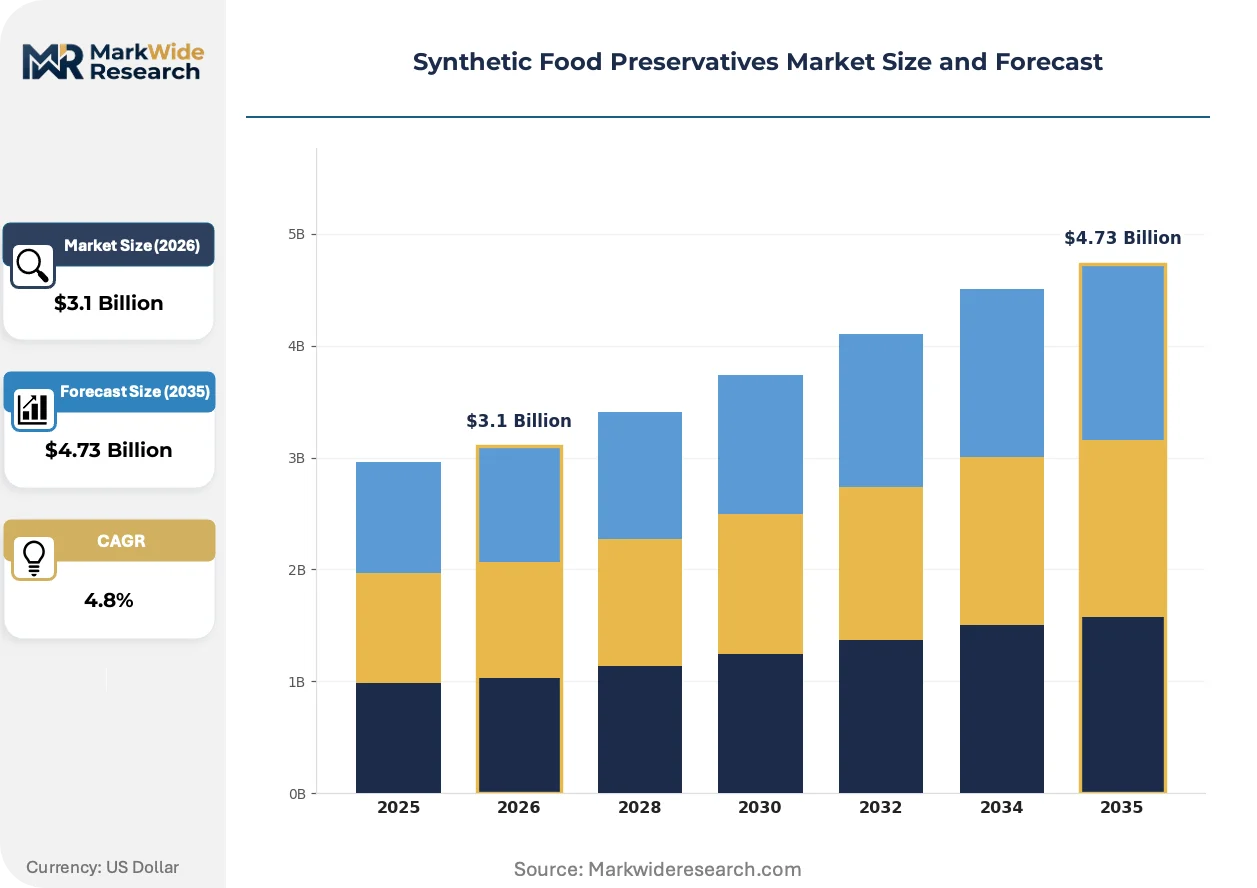
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Propionates, Sulfites Application: Beverages, Dairy Products, Baked Goods, Meat Products Form: Liquid, Powder, Granular, Concentrate End User: Food Manufacturers, Retailers, Foodservice, Home Cooks |
| Companies Covered | Cargill, DSM, DuPont, Kerry Group, ADM, Kemin Industries, BASF SE, Tate & Lyle, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Food Preservatives Market Trends and Innovations
Active restructuring of preservative supply relationships is compressing traditional distribution layers while elevating technical service intensity as the primary competitive differentiator in mature markets.
Microencapsulated organic acid systems are consolidating preservation technology architecture across high-moisture bakery and ready-to-eat meat categories. Industrial bakers in Germany and France are adopting these systems to achieve controlled-release antimicrobial activity without moisture migration defects. The technology is consolidating supplier value capture toward formulation-integrated solution providers and away from standalone chemical merchants.
EFSA's systematic re-evaluation of food additive safety under EU Regulation 1333/2008 is compressing approved substance lists and shortening authorization periods for legacy preservatives. This regulatory tightening forces reformulation investments across dairy, beverage, and condiment manufacturers operating in EU member states. Acidic beverage processors are responding fastest, accelerating transitions from benzoate-sorbate combinations toward propionate-dominant systems.
Buyers in North American meat processing are unbundling preservative procurement from compound feed additive purchasing, creating direct relationships with antimicrobial suppliers that bypass traditional distributor intermediaries. This channel disintermediation concentrates volume with suppliers capable of delivering technical field support and regulatory documentation directly. The pattern is most visible among mid-cap beef and pork processors in the US Midwest seeking customized shelf-life protocols.
Synthetic Food Preservatives Market Segmentation
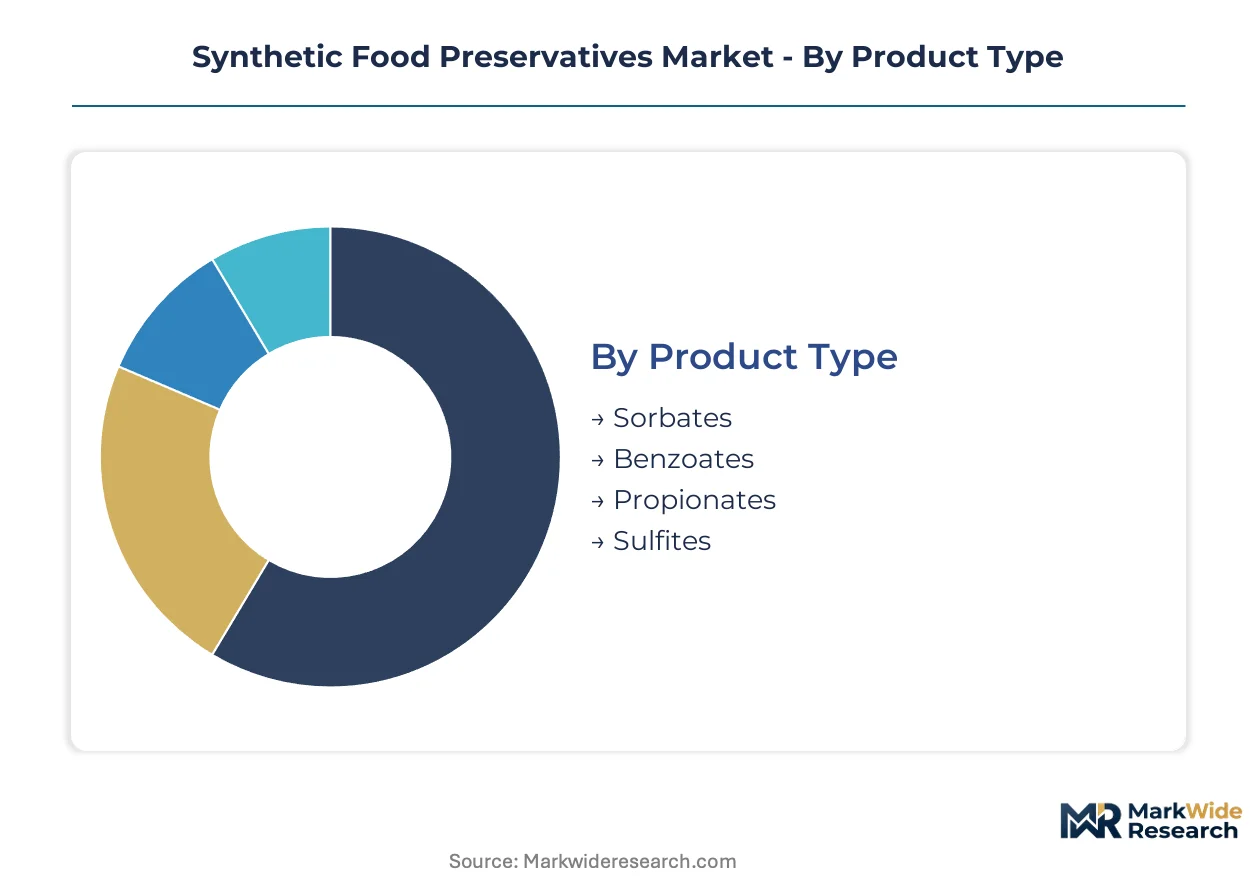
Synthetic food preservatives exhibit distinct demand profiles across product chemistry, application format, and customer type. Each dimension shapes procurement patterns, margin structures, and regulatory compliance burdens differently for suppliers and buyers.
Product Type:
Supply concentration in organic acid fermentation capacity and petrochemical feedstock access determines competitive positioning across preservative chemistries.
- Sorbates:Potassium and sodium sorbate salts deliver broad-spectrum antimicrobial efficacy across pH ranges up to 6.5, making them indispensable for dairy and baked goods manufacturers in Germany and France seeking stable shelf-life extension. Demand concentrates in high-volume dairy processing where GRAS status simplifies formulation approval.
- Benzoates:Sodium and potassium benzoate variants achieve optimal antimicrobial performance in acidic conditions below pH 4.5, commanding margin premiums in beverage applications where lower dosage rates reduce total formulation costs. Brazilian juice processors and Chinese carbonated drink manufacturers drive procurement volume as they reformulate away from sulfite alternatives.
- Propionates:Calcium and sodium propionate salts inhibit mold and rope bacteria in bakery applications with minimal flavor impact, serving industrial bakers in the US Midwest and Western Europe.
- Sulfites:Sulfur dioxide and metabisulfite compounds face contracting demand in EU and Australian markets due to tightening maximum residue limits, though wine and dried fruit processors in emerging markets sustain residual volume.
Today's leader: Sorbates. Tomorrow's challenger: Benzoates.
Application:
End-use differentiation in processing conditions, pH requirements, and regulatory scrutiny creates distinct value capture opportunities across food manufacturing verticals.
- Beverages:Acidic liquid matrices favor benzoate-dominant preservation systems with rapid microbial kill rates; Chinese municipal food safety bureaus enforce GB 2760 compliance across thousands of local processors.
- Dairy Products:Neutral pH environments and temperature-sensitive supply chains drive sorbate adoption for yogurt, cheese, and fluid milk applications in France and Germany.
- Baked Goods:High-moisture formulations and extended ambient distribution require propionate-based mold inhibition; German and French industrial bakers adopt microencapsulated systems for controlled release.
- Meat Products:Processed meat manufacturers in Brazil, India, and Indonesia expand sorbate procurement as cold-chain infrastructure expands slaughter and further-processing capacity.
Beverages command the steepest expansion trajectory among applications.
Form:
Physical format selection reflects automation level, dosing precision requirements, and freight economics across customer segments.
- Powder:Extended shelf stability and bulk freight efficiency sustain dominance in small-to-mid scale food manufacturing; Indonesian poultry processors favor powder sorbates for manual blending operations.
- Granular:Reduced dusting and improved flow characteristics serve high-throughput bakery and dairy compounders in Germany.
- Liquid:Automated dosing compatibility drives adoption among large Brazilian beef processors retrofitting precision injection equipment.
- Concentrate:Reduced water content lowers transport costs for remote food manufacturing facilities in India's interior states.
Liquid formats are gaining share fastest in automated processing environments.
End User:
Customer scale and technical capability determine service intensity, contract structure, and pricing architecture for preservative suppliers.
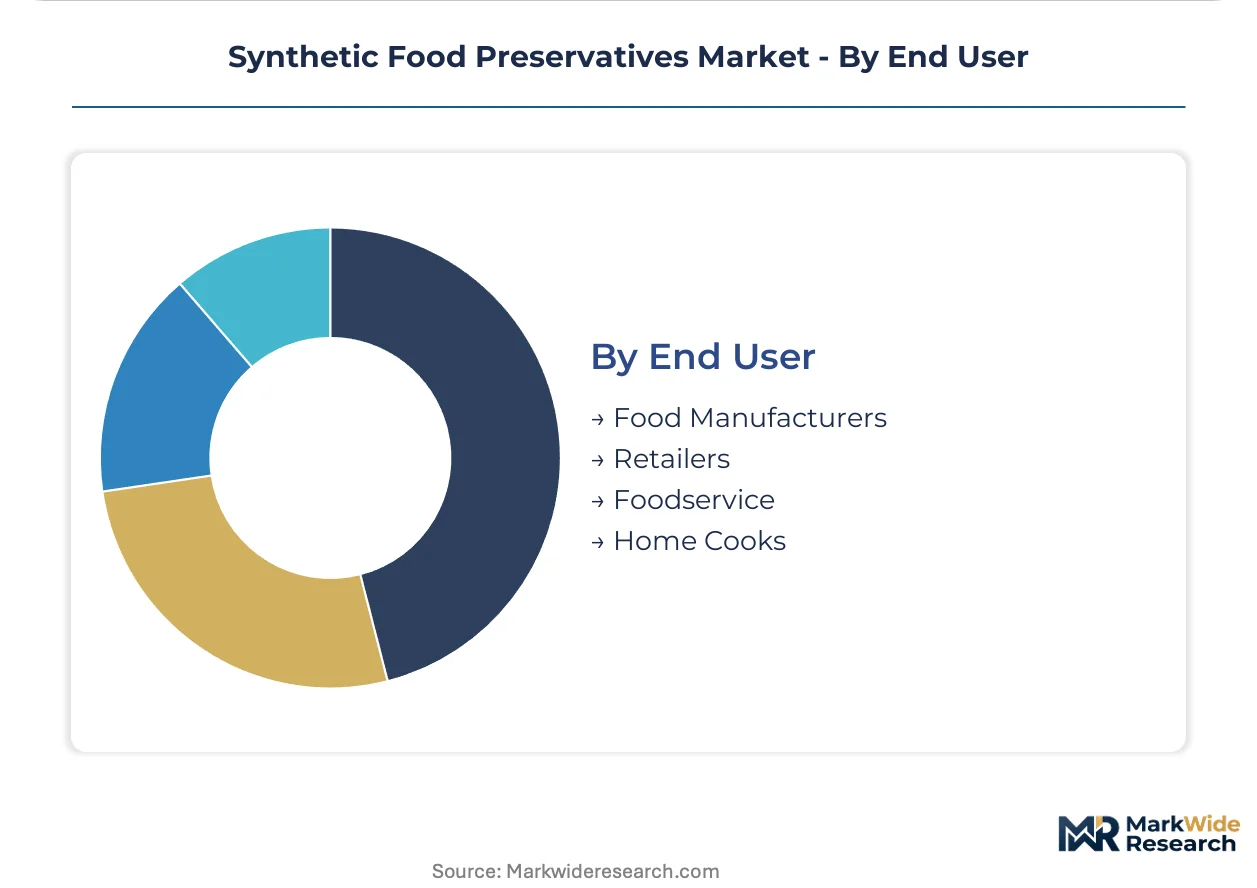
- Food Manufacturers:Direct procurement relationships with integrated technical support dominate; North American meat processors unbundle preservative purchasing from compound feed additives to secure customized shelf-life protocols.
- Retailers:Private-label packaged goods specifications drive clean-label substitution pressure in Western European and North American channels.
- Foodservice:Distributed procurement through broadline distributors sustains powder and granular format demand for ingredient preparation.
- Home Cooks:Minimal volume concentration in consumer-packaged preservative salts for home canning and preservation.
Food Manufacturers anchor current volume. Retailers represent the most contested segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's municipal food safety bureaus enforce GB 2760 compliance across thousands of local processors, while Brazil's expanding cold-chain infrastructure drives contrasting procurement patterns in ambient-stable meat preservation.
China
SAMR enforces GB 2760 maximum usage levels for benzoates and sorbates across dairy and beverage manufacturing. Municipal food safety bureaus in Shanghai and Guangzhou conduct compliance inspections that create documentation burdens for imported preservative blends. Yangtze River Delta dairy processors dominate technical-grade sorbate procurement.
Brazil
Processed meat manufacturers expand sorbate-based preservation systems as slaughter capacity grows in São Paulo state. ANVISA regulates maximum residue limits for sulfites in wine and dried fruit applications. Beef processors in Minas Gerais retrofit automated liquid dosing systems for precision injection operations.
Germany
Industrial bakers in Bavaria adopt microencapsulated propionate systems for controlled-release mold inhibition in high-moisture formulations. EFSA's systematic re-evaluation under EU Regulation 1333/2008 compresses approved substance lists. Ludwigshafen chemical manufacturing anchors European propionate supply for dairy processors.
United States
Mid-cap beef and pork processors in the Midwest unbundle preservative procurement from compound feed additives to secure customized shelf-life protocols. FDA maintains its food additive petition process under 21 CFR for GRAS determinations. Chicago-area meatpackers drive liquid concentrate format adoption in automated processing lines.
Indonesia
Domestic poultry processors modernize slaughter operations and expand procurement of powder sorbates for manual blending workflows. The country's national food safety regulator enforces maximum usage standards for antimicrobial additives. Jakarta and Surabaya meatpacking facilities concentrate demand for ambient-stable preservation systems.
Synthetic Food Preservatives Market Competitive Landscape
Top-tier vendors anchor integrated ingredient platforms, while mid-scale specialists concentrate on regional fermentation capacity and technical service intensity. The vendor base stratifies across petrochemical-derived organic acid producers, fermentation-based sorbate manufacturers, and formulation-integrated solution providers. Strategic archetypes include backward-integrated chemical conglomerates, clean-label positioning specialists, and regional distribution-focused compounders. Competitive moves concentrate on M&A for fermentation capacity and geographic expansion into emerging meat processing markets.
Within the integrated platform tier, Cargill represents the bundled-ingredient archetype combining preservatives with texturizers and sweeteners. BASF SE anchors European supply through its Ludwigshafen manufacturing complex. Kerry Group exemplifies the clean-label positioning strategy that navigates tightening consumer scrutiny of E-number additives in Western retail channels.
| Leading Market Players |
|---|
| Cargill |
| DSM |
| DuPont |
| Kerry Group |
| ADM |
| Kemin Industries |
| BASF SE |
| Tate & Lyle |
| Corbion |
| Others |
Pricing and Supply Chain Analysis
Premium-grade pharmaceutical-food dual-use sorbates command 40-60% price premiums over technical-grade alternatives, concentrating margin capture with BASF SE and DSM while commodity benzoate producers in China compete on volume scale and freight efficiency. This bifurcation channels procurement decisions: multinational dairy processors in Germany and France pay premiums for EFSA-compliant documentation bundles, whereas Indonesian poultry processors prioritize powder format availability and manual-blending compatibility over certification depth.
Pricing Analysis
Capacity additions in China's Shandong and Jiangsu provinces are reshaping price floors for benzoate salts, compressing margins for European petrochemical-derived producers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels anchors contract negotiations. Cost compression in commodity sorbates is intensifying because Brazilian meat processors are unbundling procurement from distributor intermediaries. Mid-scale Indonesian poultry processors exhibit highest price sensitivity, while North American beverage manufacturers prioritize formulation service intensity over unit cost.
Supply Chain Analysis
Specialized fermentation technicians and chemical process engineers concentrate in Germany's Ludwigshafen complex and China's Yangtze River Delta, constraining rapid capacity scaling elsewhere. Manufacturing gravity centers on Germany, China, and the United States, with propionate output anchored in Ludwigshafen and sorbate fermentation clustered in Shandong. Feedstock supply draws from benzene derivatives and ethylene cracking operations, exposing margin structures to crude oil volatility. Single-source vulnerability concentrates in pharmaceutical-grade potassium sorbate capability. Distribution runs through integrated ingredient platforms like Cargill and direct technical service relationships with large meat processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: EFSA's systematic re-evaluation under EU Regulation 1333/2008 is forcing reformulation investments that favor suppliers with toxicology documentation depth and cross-jurisdictional regulatory expertise over commodity merchants.
For Market Incumbents: Hedge against clean-label substitution pressure by acquiring fermentation-based natural antimicrobial specialists and deepening backward integration into petrochemical feedstocks. Prioritize certification investment for dual-use pharmaceutical-food grade sorbates to capture margin premiums in injectable drug applications. Channel control through direct technical service relationships with Brazilian beef processors defends position against distributor disintermediation. For New Entrants and Emerging Players: Launch via automated liquid dosing system partnerships with large Brazilian beef processors retrofitting precision injection equipment. Target Indonesian poultry processing modernization as the most penetrable geography, where powder sorbate demand outstrips qualified supplier presence. White-space exists in microencapsulated propionate systems for German industrial bakers seeking controlled-release functionality. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fermentation specialists possessing pharmaceutical-grade capability and clean-label positioning expertise. Long-term viability hinges on regulatory navigation capacity across FDA, EFSA, and SAMR jurisdictions rather than commodity scale. Watch EFSA reauthorization timelines as the signal to watch for consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | BASF SE's Ludwigshafen complex secures captive benzene supply for propionate manufacturing. |
| Pharmaceutical-Food Grade Certification Investment | DSM captures margin premiums by cross-serving injectable drug and high-purity food applications. |
| Microencapsulation Technology Licensing | Controlled-release propionate systems penetrate German and French high-moisture bakery segments. |
| Direct Technical Service Expansion | Cargill bundles preservatives with texturizers for North American beverage clients. |
| Indonesian Distribution Partnership | Kerry Group establishes shelf-life protocol relationships with Jakarta poultry processors. |
Research Methodology
Bottom-up beverage and dairy processor demand modeling reconciled against top-down organic acid fermentation capacity tracking forms the analytical core. Primary interviews with plant managers at Brazilian meat processing facilities, procurement leads at German industrial bakeries, regulatory affairs directors at multinational ingredient suppliers, and technical R&D heads at Chinese dairy compounders combined with secondary validation from FDA food additive petitions, EFSA scientific opinions under Regulation 1333/2008, SAMR GB 2760 compliance databases, and customs trade data for potassium sorbate and sodium benzoate shipments. Triangulation across these sources validates volume and pricing assumptions.
Input-output matrices map preservative chemistry to end-use application requirements, processing conditions, and jurisdictional compliance burdens across the projection horizon. Segmentation dimensions include product chemistry tier, physical format, end-use vertical, and customer scale archetype. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporate EFSA reauthorization timelines and cold-chain infrastructure buildout rates in Brazil, India, and Indonesia.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regulatory cycles or petrochemical feedstock price spikes. Forecasts reflect assumptions regarding EFSA substance list compressions, SAMR import documentation requirements, and clean-label substitution velocity in Western European retail channels. Material deviation in EFSA reauthorization pacing or Chinese GB 2760 enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market