
 Philippines Cold Storage Warehouse Market | 2026-2036
Philippines Cold Storage Warehouse Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Cold Storage Warehouse Market Analytics
Market Context
Project finance and sale-leaseback structures is rewriting competitive entry barriers for cold storage developers across the archipelago. VVS Cold Storage & Processing Plant Corporation leverages its vertical integration into blast freezing and port-adjacent land holdings to dominate Luzon throughput. Glacier Megafridge Inc. anchors its position through specialized seafood handling infrastructure serving tuna exporters in General Santos. ORCA Cold Chain Solutions Inc. differentiates via pharmaceutical-grade certification that sustains premium pricing against generalist competitors.
Technical Definition and Segment Structure
A cold storage warehouse is a thermally insulated commercial facility engineered to maintain sub-ambient temperatures through mechanical refrigeration, typically employing ammonia or CO2-based direct expansion systems with precision controls between minus 25 degrees Celsius and plus 15 degrees Celsius to preserve perishable commodities across extended durations. Frozen food product type leads volume throughput due to sustained domestic consumption of imported poultry and processed proteins, while pharmaceutical end users command the highest margin pools as Good Distribution Practice certification narrows qualified supplier bases. Blast freezer technology is displacing conventional static freezing in new builds as throughput velocity becomes the decisive operational metric for food distributors and retail chains operating just-in-time inventory models.
Regulatory Framework and Outlook
The Philippine Department of Agriculture enforces cold chain infrastructure standards for meat and seafood import handling, while the Department of Energy implements refrigeration equipment efficiency regulations that shape capital expenditure decisions for warehouse operators. BIS-equivalent Philippine National Standards for insulated panel fire ratings and ammonia safety protocols constrain retrofit options for aging facilities in dense urban zones. Stakeholders must monitor how the FDA Philippines advances pharmaceutical cold chain traceability mandates, as compliance investments will separate certified operators from general cold storage providers serving undifferentiated commodity segments.
Market Dynamics
Blast freezer technology is collapsing throughput timelines for food distributors, while the Philippine Department of Agriculture's cold chain infrastructure programs are mandating facility upgrades that favor capital-rich operators capable of ammonia-to-CO2 system conversions.
Growth Catalysts
- Pharmaceutical cold chain mandates:FDA Philippines traceability requirements for temperature-sensitive biologics are narrowing qualified supplier pools and sustaining premium pricing for certified warehouse operators.
- Metro Manila demand density:Port proximity and food processing clusters in the Calabarzon corridor create concentrated throughput requirements that justify large-scale facility investments.
- Blast freezer adoption:Food distributors and retail chains operating just-in-time inventory models are accelerating replacement of static freezing infrastructure to achieve velocity targets.
Market Restraints
- Ammonia safety compliance costs:Philippine National Standards for insulated panel fire ratings and ammonia safety protocols impose capital burdens on aging facilities in dense urban zones.
- Energy price volatility:Mechanical refrigeration systems face input cost pressure from electricity tariff fluctuations that compress operating margins for temperature-controlled facilities.
- Specialized equipment supplier concentration:CO2-based direct expansion system components rely on limited import channels, creating procurement bottlenecks for new warehouse construction.
Strategic Opportunities
- Visayas and Mindanao underpenetration:Cold storage capacity outside Luzon remains sparse relative to agricultural output, creating first-mover advantages for port-adjacent developments in Cebu and Davao.
- Department of Energy efficiency incentives:Refrigeration equipment upgrade programs subsidize capital expenditure for operators transitioning to lower-GWP cooling systems.
- Pharmaceutical-grade certification convergence:Good Distribution Practice standards and automated temperature monitoring integration enable margin capture from vaccine and biologics logistics contracts.
Industry Challenges
- Ammonia refrigeration technician scarcity:Specialized mechanical skills for industrial cooling system maintenance are concentrated among aging workforces in Metro Manila, constraining facility expansion timelines.
- Legacy electrical infrastructure incompatibility:Cold storage modernization in provincial zones requires parallel grid upgrade investments that extend project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Cold Storage Warehouse Market |
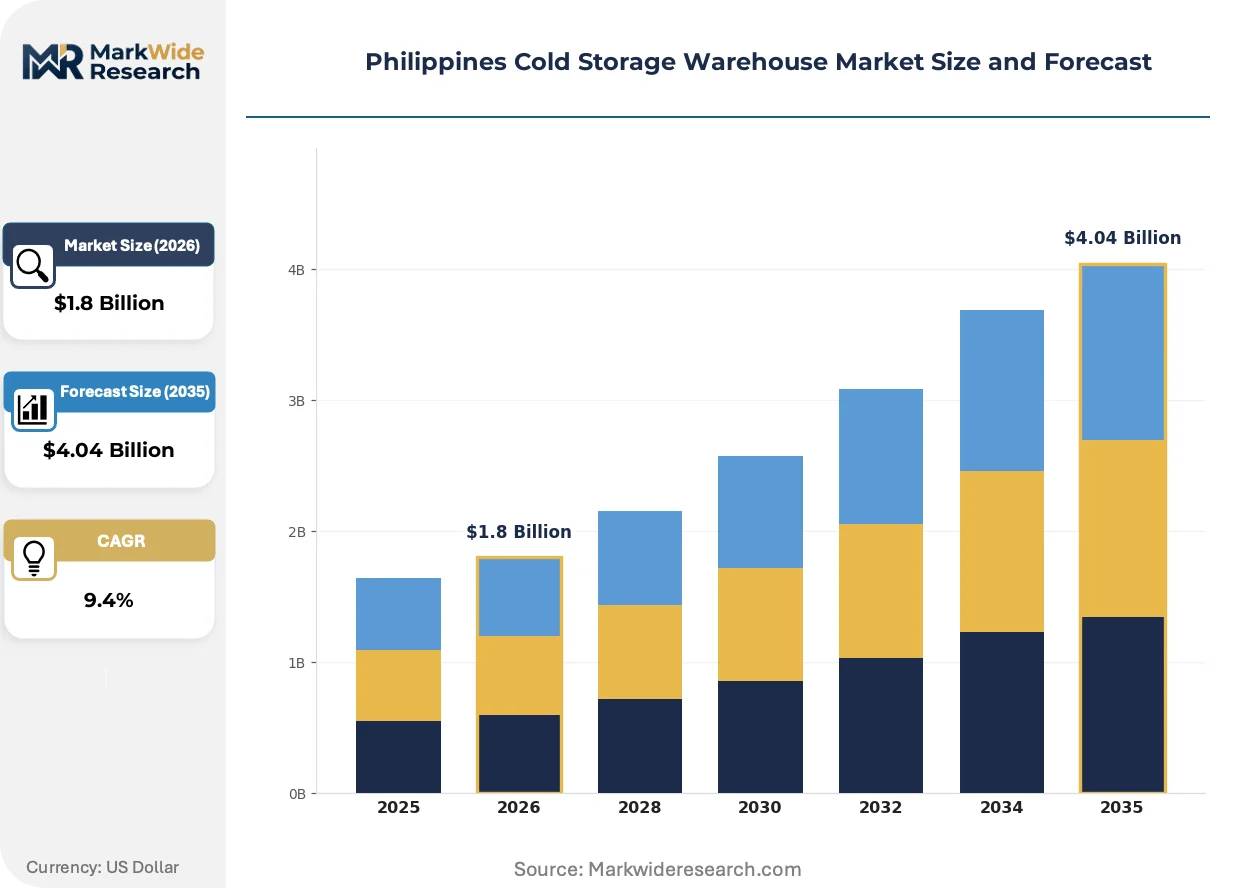
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Food, Dairy Products, Meat, Seafood End User: Food Distributors, Retail Chains, Restaurants, Pharmaceuticals Technology: Refrigerated Containers, Blast Freezers, Insulated Warehouses, Direct Expansion Systems Service Type: Storage, Packaging, Inventory Management, Transportation |
| Companies Covered | VVS Cold Storage & Processing Plant Corporation, Igloo Supply Chain Philippines, Inc., Glacier Megafridge Inc., Schuyler Refrigeration Technology, Icebox Cold Chain Solutions, FAST Logistics Group, Royale Cold Storage, Peregrine Cold Logistics, ORCA Cold Chain Solutions Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Cold Storage Warehouse Market Evolving Landscape
Automation and precision control systems are compressing operational variance in temperature-controlled logistics, while regulatory pressure on refrigerant chemistry is accelerating capital deployment toward next-generation cooling architectures.
CO2 transcritical refrigeration is collapsing the capital cost differential against ammonia systems in mid-scale warehouse builds. Food distributors with 5,000-15,000 pallet positions are adopting CO2-based direct expansion to avoid ammonia safety zoning restrictions. This technology shift is collapsing barriers to entry for developers previously excluded from urban infill sites.
Department of Energy refrigeration efficiency regulations are mandating equipment performance thresholds that disqualify legacy compressor technologies from new permits. Warehouse operators face retrofit deadlines or replacement obligations that favor integrated system providers over component vendors. Pharmaceutical-grade facilities are responding earliest due to overlapping FDA Philippines compliance calendars.
Retail chains are consolidating procurement through dedicated third-party logistics contracts that bundle warehousing with last-mile temperature control. Traditional spot-market cold storage users are migrating toward multi-year agreements with operators offering integrated blast freezing and inventory management. This pattern concentrates most visibly in Metro Manila, where supermarket consolidation has reduced the number of independent buying entities by half over the past decade.
Philippines Cold Storage Warehouse Market Segmentation
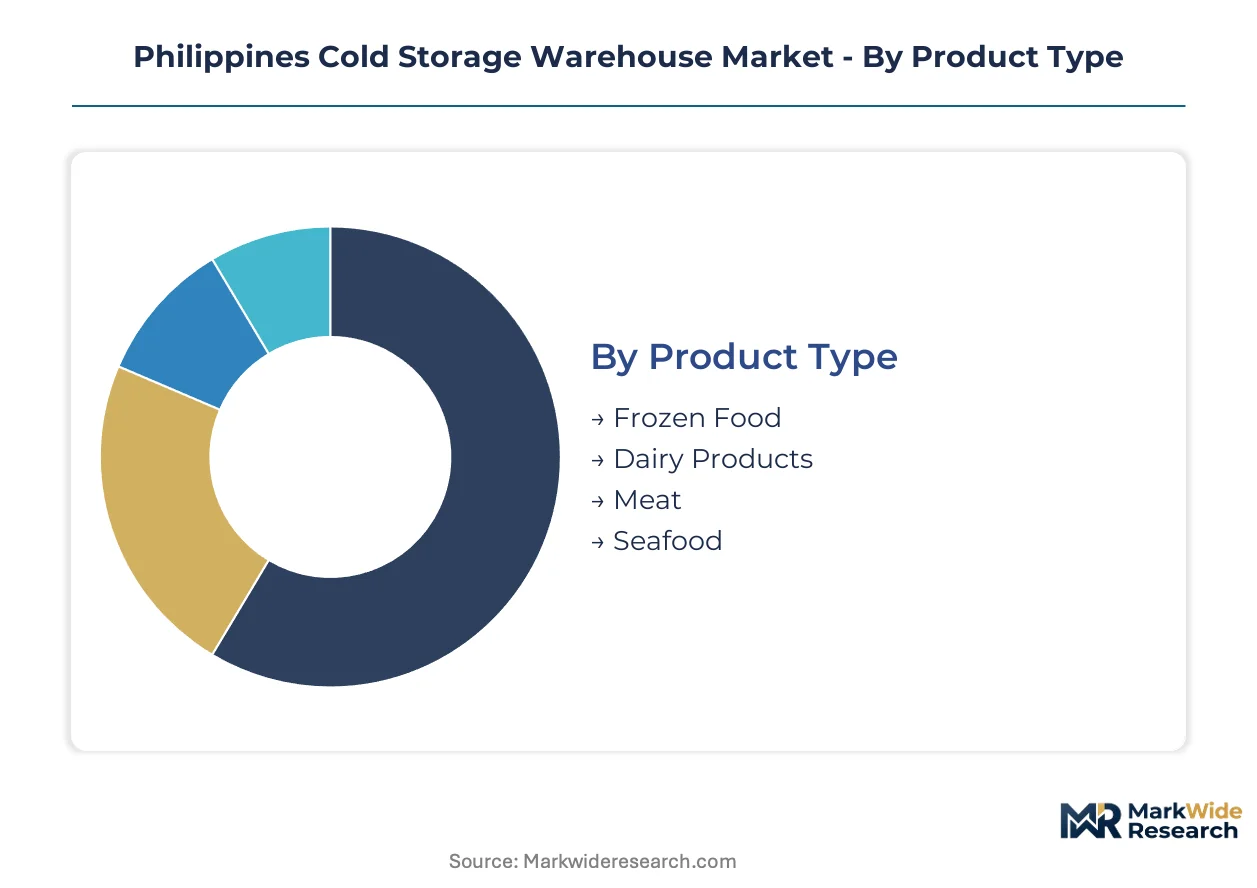
Cold storage warehouse segmentation in the Philippines reveals how product perishability, regulatory requirements, and customer operational models drive facility design and technology selection. Understanding these divisions clarifies where capital deployment concentrates and which service tiers command sustainable margins.
Product Type:
Volume concentration across commodity categories determines pallet density requirements and temperature band specifications for warehouse operators.
- Frozen Food:Processed poultry and imported proteins dominate throughput tonnage. Metro Manila food distributors and quick-service restaurant chains drive capacity absorption for frozen vegetable and ready-meal storage.
- Meat:Pork and beef imports require minus 18 degrees Celsius holding with strict Philippine Department of Agriculture quarantine protocols. Calabarzon slaughterhouse clusters and port-adjacent cold stores handle the bulk of national volume.
- Seafood:Tuna and aquaculture exports from General Santos and Zamboanga Peninsula need rapid chilling infrastructure.
- Dairy Products:Cheese and butter imports for bakery and foodservice channels operate at higher temperature bands with shorter holding periods.
Frozen food holds installed capacity. Meat is rotating up the share rankings.
End User:
Customer operational models separate spot-market users from integrated logistics buyers with divergent contract structures and service expectations.
- Food Distributors:Wholesale operators serving independent retailers and institutional kitchens require high-velocity throughput with blast freezing capabilities. These customers dominate Luzon capacity contracts and are consolidating procurement through multi-year third-party logistics agreements.
- Pharmaceuticals:Vaccine and biologics manufacturers demand FDA Philippines Good Distribution Practice certification with automated temperature monitoring. Premium pricing sustains for qualified operators as traceability mandates narrow the supplier base.
- Retail Chains:Supermarket consolidation in Metro Manila has halved independent buying entities over the past decade, concentrating demand among fewer large-format accounts.
- Restaurants:Quick-service and casual dining chains operate just-in-time inventory models with smaller pallet positions and higher delivery frequency requirements.
Food distributors anchor contract volume. Pharmaceuticals is climbing the fastest as a margin contributor.
Technology:
Refrigeration architecture choices shape capital intensity, regulatory compliance pathways, and site selection flexibility for developers.
- Blast Freezers:High-velocity air circulation systems reduce core product temperatures from plus 4 degrees Celsius to minus 18 degrees Celsius within four hours. Food distributors and retail chains are accelerating replacement of static freezing infrastructure to achieve velocity targets for just-in-time inventory models.
- Direct Expansion Systems:CO2-based configurations are displacing ammonia in mid-scale urban builds to avoid safety zoning restrictions. The Department of Energy efficiency regulations favor these systems for new permits.
- Insulated Warehouses:Philippine National Standards for panel fire ratings constrain retrofit options for aging facilities in dense urban zones.
- Refrigerated Containers:Mobile units serve temporary overflow and seasonal agricultural harvest peaks with lower capital commitment.
Blast freezers command new build investment. Direct expansion systems are gaining share fastest among technology categories.
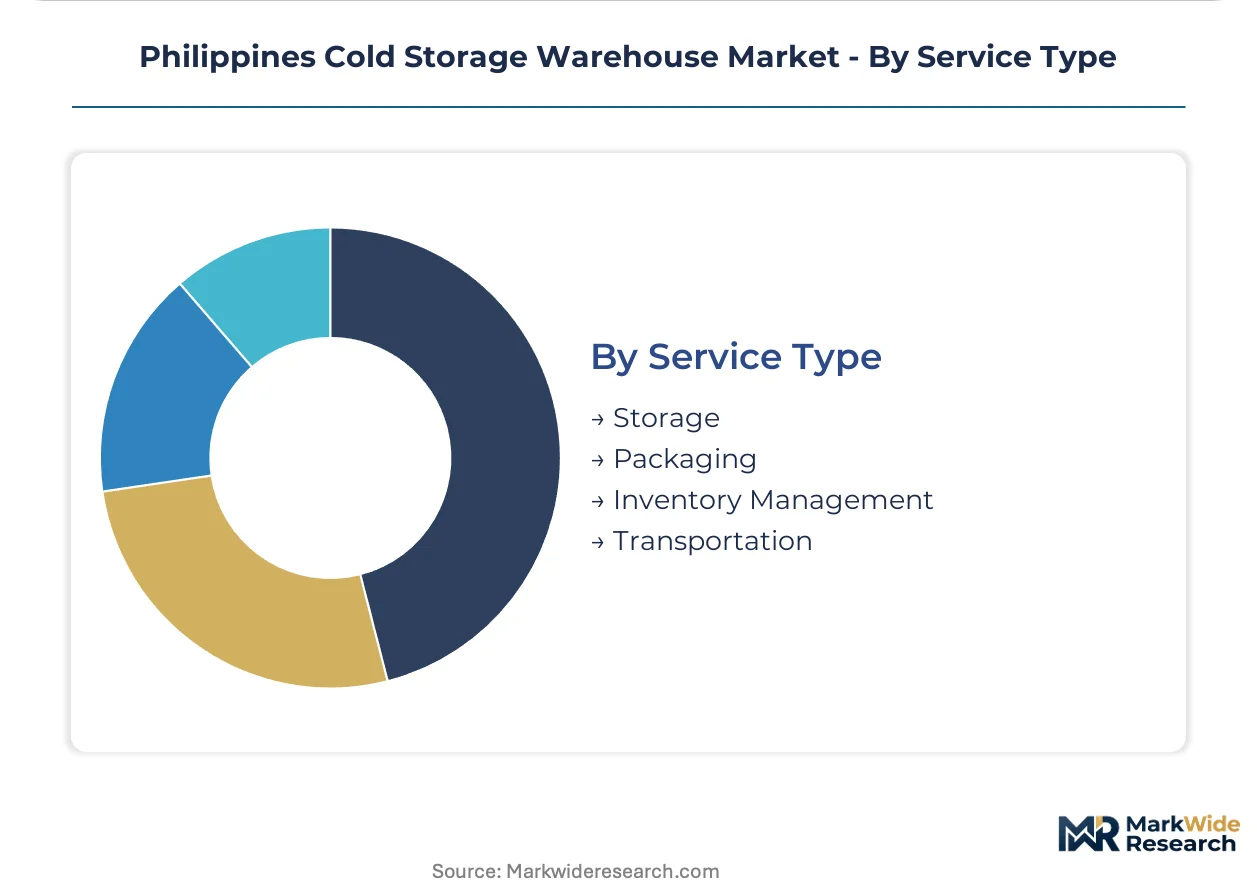
Service Type:
Value-added service bundling separates commodity storage providers from integrated cold chain operators capturing higher contract values.
- Storage:Pallet positioning and temperature holding remains the baseline revenue layer with compressed margins in undifferentiated facilities.
- Inventory Management:Warehouse management system integration and real-time stock visibility commands premium positioning with retail chain accounts.
- Packaging:Blast freezing combined with repacking and labeling services captures additional margin from food distributors requiring export-ready presentation.
- Transportation:Last-mile refrigerated delivery bundling is consolidating procurement decisions toward operators offering end-to-end temperature control.
Storage holds installed revenue base. Inventory management is expanding most quickly as a differentiation layer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across Philippine sub-regions concentrate cold storage investment near port gateways and agricultural surplus zones. Metro Manila absorbs imported protein volumes while Mindanao and Visayas processing clusters require outbound capacity for tuna and tropical fruit shipments.
Metro Manila
Port-adjacent cold storage in Manila and Subic handles the bulk of imported poultry and processed proteins for national distribution. The Philippine Department of Agriculture enforces quarantine holding requirements that mandate dedicated inspection facilities. Caloocan and Quezon City host dense clusters of third-party logistics operators serving quick-service restaurant chains and supermarket consolidation centers.
Calabarzon
Slaughterhouse clusters in Batangas and Laguna generate substantial meat storage demand for domestic redistribution. The Department of Energy's refrigeration efficiency regulations are accelerating ammonia-to-CO2 conversions in this corridor. Lipa and Santa Rosa industrial zones attract food processing investments that require integrated blast freezing capacity.
Central Luzon
Rice and vegetable surplus regions in Nueva Ecija and Pampanga need seasonal overflow storage for harvest peaks. The Department of Agriculture's cold chain infrastructure programs subsidize facility development in agricultural catchment areas. Clark Freeport Zone offers tax incentives attracting refrigerated warehouse investments serving northern Luzon distribution networks.
Visayas
Cebu City's port position creates underexploited potential for transshipment cold storage serving central Philippines. The national food security agenda prioritizes post-harvest loss reduction through temperature-controlled infrastructure. Mactan export processing zones concentrate seafood handling requiring rapid chilling for tuna and aquaculture products.
Mindanao
General Santos anchors tuna export volumes demanding specialized blast freezing and rapid cold chain transfer. The Philippine Department of Agriculture's fisheries modernization programs target this region for infrastructure investment. Davao City's growing food processing base requires expanded refrigerated warehousing for banana, pineapple, and cacao value-added operations.
Philippines Cold Storage Warehouse Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in equipment and panel supply. The Philippines cold storage market exhibits moderate consolidation where vertically integrated operators with port-adjacent land holdings secure multi-year contracts with food distributors and retail chains. Three archetypes dominate: blast freezing specialists serving high-velocity protein distributors, pharmaceutical-grade certified operators capturing vaccine logistics premiums, and diversified third-party logistics providers bundling warehousing with last-mile delivery. Competitive moves concentrate on ammonia-to-CO2 system conversions for regulatory compliance and multi-year contract consolidation with supermarket chains reducing independent buying entities.
Among Philippine-based cold storage operators, VVS Cold Storage & Processing Plant Corporation and Glacier Megafridge Inc. exemplify the vertically integrated archetype with port-adjacent positioning. ORCA Cold Chain Solutions Inc. represents the pharmaceutical-grade certification tier serving temperature-sensitive biologics. These operators occupy positions where regulatory compliance investments and specialized infrastructure create defendable contract structures against generalist competitors.
| Leading Market Players |
|---|
| VVS Cold Storage & Processing Plant Corporation |
| Igloo Supply Chain Philippines, Inc. |
| Glacier Megafridge Inc. |
| Schuyler Refrigeration Technology |
| Icebox Cold Chain Solutions |
| FAST Logistics Group |
| Royale Cold Storage |
| Peregrine Cold Logistics |
| ORCA Cold Chain Solutions Inc. |
| Others |
Value Network & Pricing Analysis
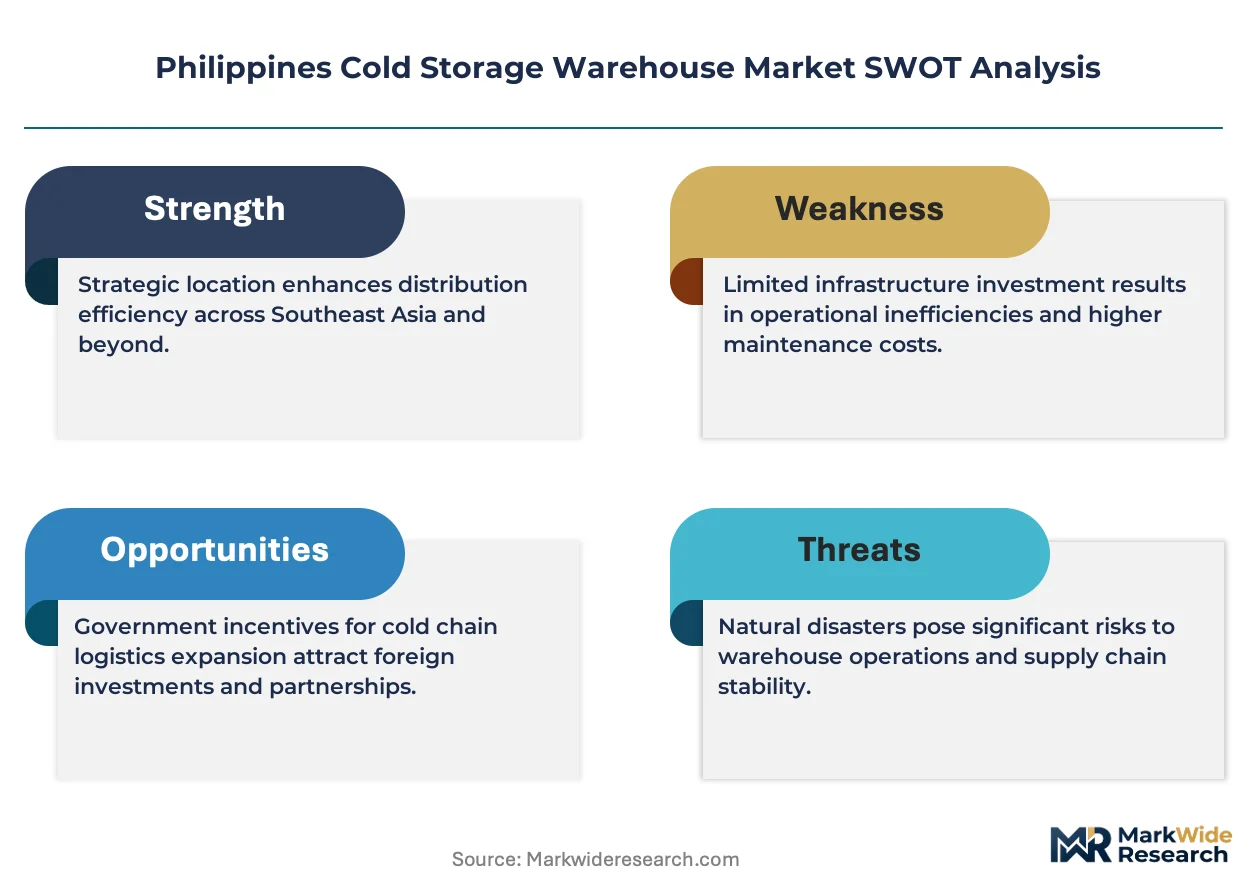
Undercapacity in Visayas and Mindanao cold storage facilities drives divergent pricing power between Luzon incumbents and regional challengers, with Metro Manila operators commanding premium contract terms while provincial developers absorb higher financing costs to capture first-mover positioning.
Pricing Analysis
Food distributors anchor contract-based long-term offtake structures across the Philippines cold storage market. Three-tier pricing structure across pharmaceutical-grade, certified food-grade, and general commodity levels reflects Good Distribution Practice certification premiums and blast freezing capability bundling. Cost compression in general storage tiers is intensifying because ammonia safety retrofit obligations and electricity tariff volatility compress margins for aging facilities. Quick-service restaurant chains exhibit highest price sensitivity due to thin foodservice margins, while vaccine manufacturers accept premium positioning for FDA Philippines traceability compliance.
Supply Chain Analysis
Extended payment terms from Japanese and South Korean refrigeration equipment suppliers strain working capital for Philippine warehouse developers undertaking CO2 transcritical system conversions. Component sourcing draws from China for insulated panel assemblies, Germany for compressor units, and Thailand for electrical control systems. Ammonia refrigeration technician scarcity in provincial zones creates single-source vulnerability for maintenance networks serving new facility deployments. Distribution runs through port-adjacent consolidation hubs in Manila and Subic before radiating to Calabarzon food processing clusters and Mindanao export zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among supermarket consolidation centers and quick-service restaurant chains, with independent retail buying entities halving over the past decade and shifting procurement toward integrated third-party logistics bundles.
For Market Incumbents: Harden ammonia-to-CO2 conversion timelines ahead of Department of Energy efficiency permit deadlines, securing port-adjacent land positions in Cebu and Davao before regional competition intensifies. Pharmaceutical-grade certification investments defend margin pools against generalist competitors as FDA Philippines traceability mandates narrow qualified supplier bases. For New Entrants and Emerging Players: Mid-scale blast freezing facilities in General Santos and Zamboanga Peninsula represent the most penetrable entry point, with tuna export volumes demanding specialized rapid chilling infrastructure underserved by Luzon-centric operators. Department of Agriculture fisheries modernization subsidies provide a go-to-market angle for port-adjacent developments targeting export-oriented seafood processors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with captive land positions and multi-year retail chain contracts, as these assets sustain pricing power through regulatory compliance cycles. The inflection signal to watch is pharmaceutical cold chain traceability mandate enforcement timing, which would accelerate certified facility premiums and compress generalist competitor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Blast Freezing Infrastructure Expansion | High-velocity throughput capabilities capture food distributor consolidation toward integrated operators. |
| CO2 Transcritical System Conversion | Department of Energy efficiency regulations favor lower-GWP cooling for new permit approvals. |
| Pharmaceutical-Grade Certification Investment | FDA Philippines Good Distribution Practice standards narrow qualified supplier pools and sustain premiums. |
| Port-Adjacent Land Acquisition | Subic, Cebu, and General Santos positions anchor export-import logistics for tuna and protein flows. |
| Multi-Year Third-Party Logistics Contracting | Retail chain procurement consolidation favors operators bundling warehousing with last-mile temperature control. |
Research Methodology
A spread of perspectives from cold storage facility operators, food distributor procurement heads, pharmaceutical logistics managers, and Department of Agriculture program officers converged on the working assumptions driving facility investment timelines. Primary fieldwork combined structured interviews with warehouse engineering consultants and refrigeration equipment procurement specialists, validated against Philippine National Standards technical documentation, Bureau of Customs import data for insulated panel and compressor units, Department of Energy efficiency regulation filings, and FDA Philippines pharmaceutical distribution guidance. Bottom-up capacity installation tracking and top-down end-use demand estimation were triangulated against trade flow data for imported poultry and protein volumes.
Demand-supply balance modeling across the projection horizon incorporated temperature band requirements by product perishability, regulatory compliance tier differentiation, and technology adoption curves for blast freezing and CO2 transcritical systems. Segmentation dimensions spanned product type, end-user operational model, refrigeration architecture, and value-added service bundling. CAGRs were derived from capacity absorption rates against import volume growth and pharmaceutical cold chain mandate implementation pacing. Forecast inputs included electricity tariff trajectory assumptions and ammonia technician workforce expansion constraints.
Macroeconomic conditions sit as an overlay; deviation in peso exchange rate volatility, agricultural import policy shifts, or energy subsidy program continuity would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and infrastructure program funding levels. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Homogenizers Market