
 Global Organic Coconut Water Market | 2026-2036
Global Organic Coconut Water Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Coconut Water Market Intelligence
Heightened consumer and retailer focus on sustainable packaging solutions, including the shift away from single-use plastics, is repositioning the value proposition for organic coconut water brands. Vita Coco leverages its extensive distribution network to maintain market presence across multiple continents. Harmless Harvest differentiates through its fair-for-life certified sourcing and proprietary micro-filtration process. Amy & Brian occupies a specific niche with its canned, non-GMO product line targeting health-conscious consumers.
Organic coconut water is the liquid extracted from young, green coconuts grown under certified farming practices that prohibit synthetic pesticides and fertilizers. Its primary commercial purpose is as a natural hydration beverage, valued for its electrolyte content, particularly potassium. The pure organic coconut water segment commands the largest share, while flavored varieties represent the fastest-growing category. Tetra Pak packaging remains the dominant format due to its shelf-stability, with PET bottles prevalent in convenience-focused channels.
Regulatory frameworks including the USDA National Organic Program, the EU's organic farming rules, and Japan's JAS standards are critical for market access. These regulations define production and labeling requirements, creating a distinct premium product category that commands higher price points. Securing a consistent supply of certified organic coconuts from diverse geographic sources will be a key determinant of future competitive success.
Market Dynamics
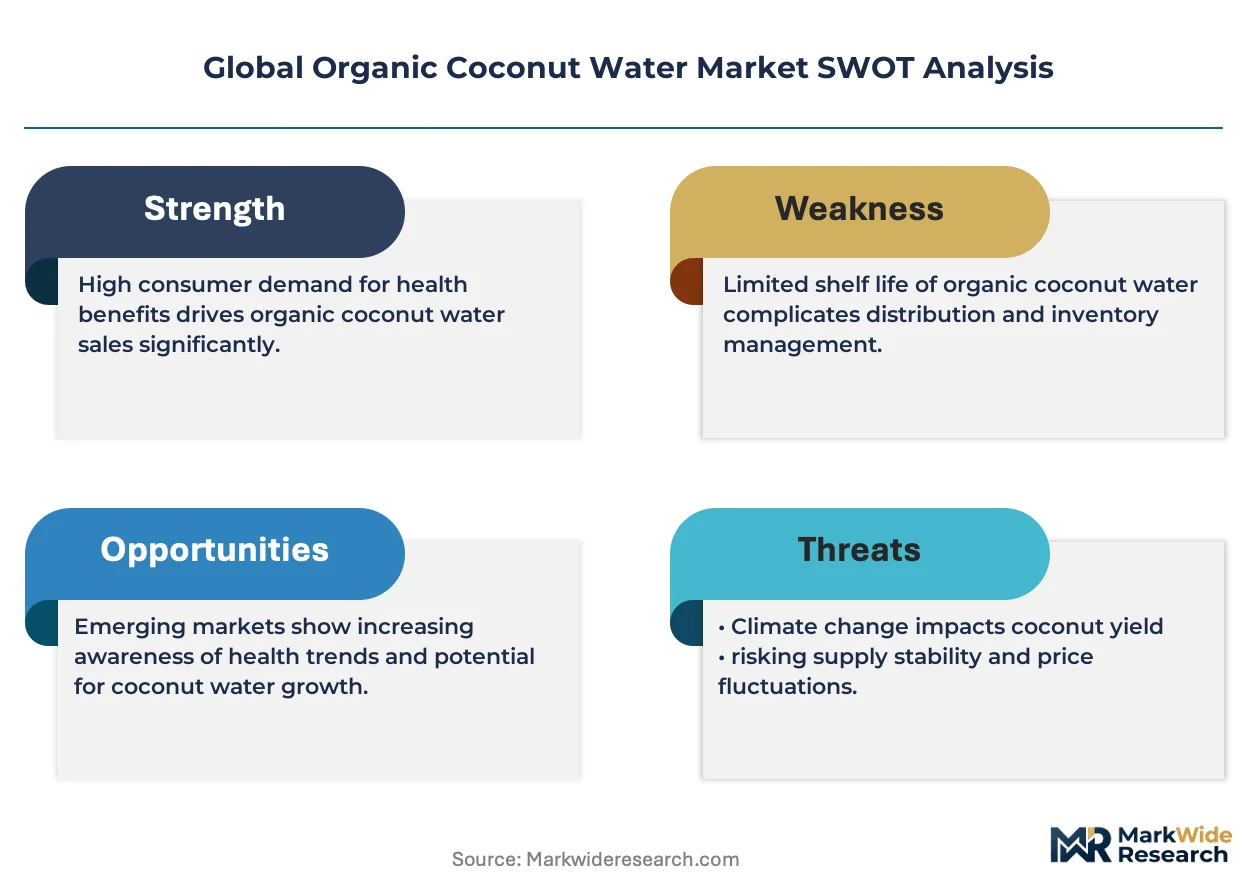
The central tension within the organic coconut water market is the persistent gap between escalating consumer demand for certified, ethically sourced products and the climate-vulnerable, geographically concentrated supply of young green coconuts.
Growth Catalysts
- Consumer Health Focus:Athletes and wellness-oriented shoppers are integrating organic coconut water into their diets as a natural hydration and electrolyte source, particularly for its potassium content.
- Regulatory Standards:The enforcement of USDA Organic and EU organic farming regulations creates a clear, premium market segment, justifying higher price points for certified products.
- Distribution Expansion:The increasing availability of organic options in specialty health food stores and conventional supermarkets in markets like the United States and Germany expands consumer access.
Market Restraints
- Supply Chain Vulnerability:Production is susceptible to climate-related events like typhoons and droughts in key growing regions such as the Philippines and Indonesia, creating price and volume instability.
- Certification Costs:The expense and administrative burden of obtaining and maintaining organic certification can be prohibitive for small-scale coconut farmers, limiting the pool of qualified suppliers.
- Substitute Beverages:The market faces competition from other plant-based hydration drinks, including maple water, birch water, and aloe vera juice, which appeal to similar consumer segments.
Strategic Opportunities
- Functional Blends:There is an opportunity to develop new product lines by infusing organic coconut water with other functional ingredients like turmeric, ginger, or probiotics.
- New Geographic Markets:Expansion into underpenetrated markets in Eastern Europe and the Middle East, where wellness trends are gaining traction, presents a significant growth avenue.
- Foodservice Channel Growth:Targeting hotels, restaurants, and cafes with bulk or single-serve organic coconut water can open a new, high-volume distribution channel beyond retail.
Industry Challenges
- Maintaining Quality Standards:Ensuring consistent taste, quality, and nutrient profiles from geographically diverse and seasonally variable organic coconut sources is a major operational hurdle.
- Cold Chain Management:For premium, non-pasteurized products, maintaining an unbroken and costly cold chain from farm to retailer is essential to prevent spoilage and preserve quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Coconut Water Market |
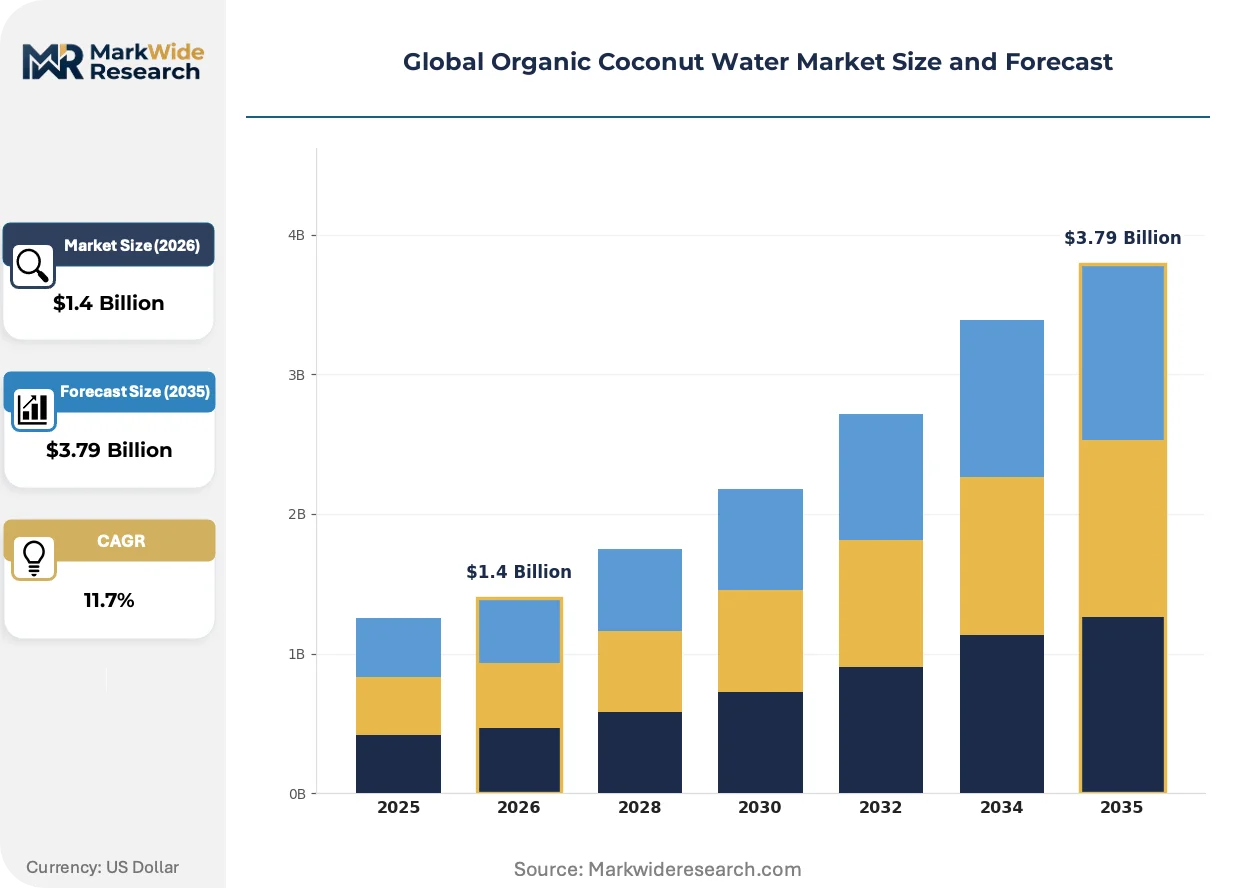
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Organic Coconut Water, Flavored Coconut Water, Concentrated Coconut Water, Ready-to-Drink Coconut Water, Organic Coconut Milk Packaging Type: Tetra Pak, PET Bottles, Glass Bottles, Cartons, Pouches Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Convenience Stores, Specialty Health Stores, Food Service Customer Type: Health-Conscious Consumers, Athletes & Fitness Enthusiasts, Vegan & Vegetarian Consumers, Organic Product Buyers, Lifestyle Consumers |
| Companies Covered | C2O Coconut Water, Amy & Brian, Vita Coco, Kalbe International, Iberia Foods, Harmless Harvest, Taste Nirvana, Goya Foods, Zico Rising, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Coconut Water Market Strategic Shifts & Innovations
Product innovation is converging with sustainability mandates, compelling brands to rethink formulation, processing, and packaging. This reevaluation balances consumer desire for purity with the commercial need for shelf stability and the regulatory pressure for environmental responsibility.
Advanced micro-filtration is a key processing technology that preserves the flavor and nutritional integrity of raw coconut water without using high heat. Premium consumer segments are actively seeking out products that use this method for its perceived freshness and quality. This technology is rewriting the value proposition for the premium tier, creating a distinct separation from traditional heat-pasteurized alternatives.
European Union directives on packaging, including the Packaging and Packaging Waste Regulation, are creating new design constraints. The regulation's focus on recycled content and recyclability forces a re-examination of material choices for both PET bottles and aseptic cartons. Brands that rely heavily on multi-layer Tetra Pak formats are most affected, prompting investment in alternative materials and monomaterial designs.
A pronounced consumer shift is occurring from viewing coconut water as a simple hydrator to a base for functional beverages. This is disrupting the pure, unflavored segment as shoppers seek flavored options infused with botanicals, vitamins, or fruit extracts. This demand for functional variety is most apparent in North American retail channels, where brands compete on flavor innovation.
Global Organic Coconut Water Market Segmentation
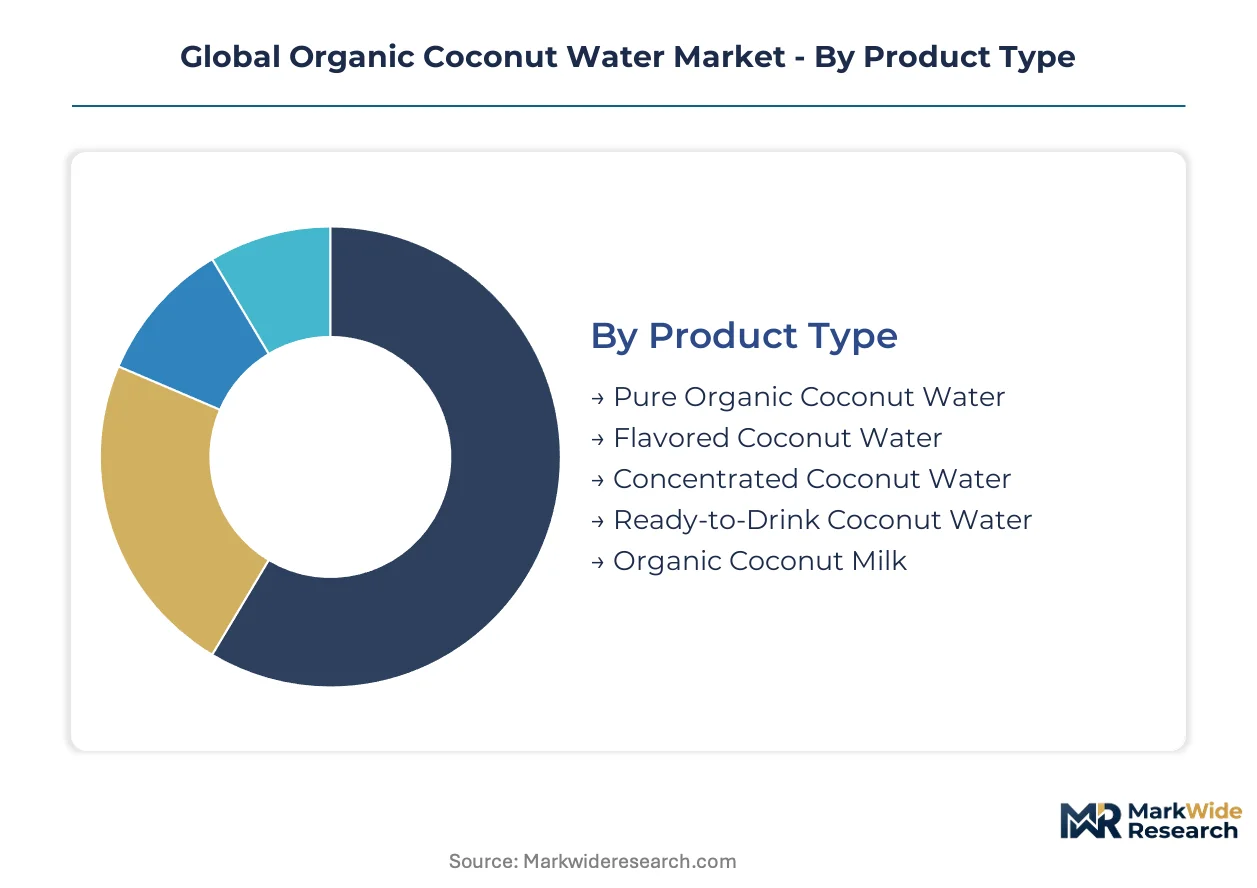
Understanding the distinct segments within the organic coconut water market is crucial for brands to tailor product offerings and marketing strategies effectively. This segmentation highlights the diverse preferences of consumers and the varying operational requirements across the value chain. Strategic focus on specific product types, packaging formats, distribution channels, and customer profiles enables targeted market penetration and sustained growth.
Product Type:
Consumer preferences for taste, purity, and functional benefits drive segmentation by product type.
- Pure Organic Coconut Water:This segment comprises liquid extracted directly from young, green coconuts without added flavors or sweeteners, valued for its natural electrolyte content. Demand concentrates in the United States and Germany, driven by wellness-oriented shoppers seeking unadulterated hydration.
- Flavored Coconut Water:These products combine organic coconut water with natural fruit extracts, botanicals, or spices, appealing to consumers desiring variety and enhanced taste. North American retail channels show strong demand for these innovative flavor profiles.
- Concentrated Coconut Water:This format is processed to remove water content, reducing volume for easier transport and storage, often used in industrial applications or as a base for other beverages.
- Ready-to-Drink Coconut Water:Pre-packaged, single-serve organic coconut water designed for immediate consumption, emphasizing convenience for on-the-go lifestyles.
- Organic Coconut Milk:A creamy liquid derived from the grated pulp of mature organic coconuts, used primarily as a dairy alternative in cooking and beverages.
Volume sits with Pure Organic Coconut Water; growth tilts toward Flavored Coconut Water, which represents the fastest-growing trajectory.
Packaging Type:
The functional requirements of shelf-stability, portability, and environmental impact dictate packaging choices.
- Tetra Pak:Multi-layer aseptic cartons providing extended shelf-life without refrigeration for organic coconut water, maintaining product integrity. This format remains dominant due to its shelf-stability and transport efficiency across global supply chains.
- PET Bottles:Lightweight, transparent plastic bottles widely used for convenience-focused organic coconut water products, particularly prevalent in grab-and-go retail settings. Demand in Australia and the United States often favors this format for immediate consumption.
- Glass Bottles:Premium packaging choice for organic coconut water, often associated with a perception of higher quality and purity, favored in specialty health stores.
- Cartons:Similar to Tetra Pak but can include other multi-layer paperboard designs, offering an alternative for aseptic packaging.
- Pouches:Flexible, lightweight packaging solutions, often with a spout, providing convenience and reduced material use for organic coconut water.
The shift towards PET Bottles reflects evolving consumer preferences for on-the-go convenience, while Tetra Pak maintains its foundational role in shelf-stable distribution.
Distribution Channel:
Consumer access points and purchasing habits define the segmentation by distribution channel.
- Supermarkets & Hypermarkets:Large retail outlets offering a wide selection of organic coconut water brands, serving as a primary point of purchase for most consumers. These channels provide broad consumer access across Germany and the United States.
- Online Retailers:E-commerce platforms facilitating direct-to-consumer sales and offering a wider variety of specialized organic coconut water products. The convenience of home delivery drives demand through these channels.
- Convenience Stores:Small retail formats providing quick access to single-serve organic coconut water products, catering to immediate consumption needs.
- Specialty Health Stores:Retailers focusing on organic, natural, and health-oriented products, often stocking premium and niche organic coconut water brands. The availability of premium products in these stores drives consumer interest in key markets.
- Food Service:Supply to hotels, restaurants, cafes, and institutional settings for bulk or single-serve organic coconut water consumption.
Expanding reach through Online Retailers creates new market opportunities, complementing established sales through Supermarkets & Hypermarkets.
Customer Type:
The motivations and lifestyles of consumers shape demand across different customer segments.
- Health-Conscious Consumers:Individuals prioritizing nutritional value, natural ingredients, and functional benefits in their dietary choices, integrating organic coconut water for hydration. This group actively seeks out products with clear organic certification.
- Athletes & Fitness Enthusiasts:Consumers who use organic coconut water as a natural electrolyte replenishment beverage for post-workout recovery and sustained hydration. Its potassium content is a primary draw for this segment.
- Vegan & Vegetarian Consumers:Individuals adhering to plant-based diets, utilizing organic coconut water as a natural, plant-derived beverage and ingredient.
- Organic Product Buyers:Consumers specifically seeking products certified organic, driven by concerns for environmental impact, ethical sourcing, and absence of synthetic chemicals.
- Lifestyle Consumers:Individuals who adopt organic coconut water as part of a broader wellness-focused lifestyle, often influenced by trends and brand perception.
Targeting Vegan & Vegetarian Consumers offers significant expansion potential, building on the core demand from Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for organic coconut water sees significant activity centered around key consumption hubs. In cities like Los Angeles and Berlin, consumer demand for natural hydration and wellness products drives market expansion. This concentration reflects lifestyle trends and robust distribution networks.
United States
Demand for pure organic coconut water concentrates in the United States, driven by wellness-oriented shoppers seeking unadulterated hydration. The USDA National Organic Program sets stringent standards for certified products, ensuring consumer trust. Retail hubs in California, particularly Los Angeles, experience high sales due to a strong health-conscious consumer base.
Germany
German consumers integrate organic coconut water into their diets as a natural hydration and electrolyte source. The EU's organic farming rules define production and labeling requirements, creating a distinct premium product category. Major metropolitan areas like Berlin show strong demand, supported by well-developed specialty health food stores.
Australia
Australian consumers increasingly favor organic coconut water for its perceived health benefits and natural electrolyte content. The TGA (Therapeutic Goods Administration) oversees certain health claims, influencing product labeling and marketing within the country. Specialty health stores in Sydney and Melbourne drive premium product availability and consumer interest.
Japan
Japanese consumers are adopting organic coconut water for its functional benefits and alignment with health-conscious lifestyles. Japan's JAS standards are critical for market access, defining specific production and labeling requirements for organic products. Distribution in Tokyo's convenience and health food stores showcases product innovation and premium offerings.
Philippines
Supply chain stability for organic coconut water relies heavily on key growing regions like the Philippines, a major producer of young green coconuts. The country's Department of Agriculture supports sustainable farming practices to meet global organic demand. Processing facilities in Mindanao are crucial for extracting and preparing organic coconut water for international export.
Global Organic Coconut Water Market Key Industry Players
The competitive structure tilts toward a blend of established beverage giants and specialized organic brands. The market exhibits a tiered structure, with premium, niche players differentiating through unique sourcing and processing methods. Larger corporations focus on extensive distribution and brand recognition to maintain market share. Dominant competitive moves include strategic partnerships for supply chain resilience and continuous portfolio diversification with new functional blends.
Within the premium and specialized organic segment, Harmless Harvest exemplifies a brand focused on fair-for-life certified sourcing and proprietary micro-filtration processes, appealing to consumers seeking purity and ethical production. This approach creates a distinct value proposition in a crowded market. Vita Coco anchors the broader market with its extensive distribution network across multiple continents, maintaining a strong presence through widespread availability and diverse product offerings. Amy & Brian occupies a specific niche with its canned, non-GMO product line, targeting health-conscious consumers who prioritize convenience and specific ingredient profiles, carving out a specialized demand.
| Leading Market Players |
|---|
| C2O Coconut Water |
| Amy & Brian |
| Vita Coco |
| Kalbe International |
| Iberia Foods |
| Harmless Harvest |
| Taste Nirvana |
| Goya Foods |
| Zico Rising |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed brands often influence organic coconut water supply. Their investment strategies directly impact raw material sourcing and subsequent market pricing dynamics.
Pricing Analysis
Value-based pricing for organic coconut water ties directly to its certified organic status and perceived health benefits. Price differentiation stems from organic certification levels, such as USDA Organic or EU organic, and the premium associated with specialized processing like micro-filtration. Upward pricing pressure arises from supply chain vulnerability, including climate events and certification costs. Health-conscious consumers and athletes typically exhibit lower price sensitivity for premium pure organic options, while general consumers are more sensitive to flavored, ready-to-drink product pricing.
Supply Chain Analysis
Local content mandates in Southeast Asia could reshape organic coconut sourcing, particularly from key growing regions like the Philippines and Indonesia. The market draws from young green coconuts as its primary raw material, alongside packaging components such as Tetra Pak materials. Single-source vulnerability, particularly from climate-related events like typhoons, presents a significant supply chain risk. Retail channels, including supermarkets and specialty stores, serve as the primary conduit for distribution, with the foodservice sector representing an expanding segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic coconut water market is undergoing a technology-transition phase where advanced micro-filtration is replacing traditional heat pasteurization. This shift influences product quality and market positioning.
For Market Incumbents: Deploy strategic partnerships to secure diverse organic coconut supply. Brands like Vita Coco should invest in long-term contracts with certified organic farmers to mitigate climate-related supply disruptions. Controlling distribution channels and investing in robust certification processes can counter competition from substitute plant-based beverages. Focus on sustainable farming practices to enhance supply chain resilience against environmental threats.
For New Entrants and Emerging Players: Price-point gaps between premium micro-filtered and standard pasteurized organic coconut water create opportunities. Target the functional beverage segment with novel ingredient blends, such as turmeric or probiotics, to attract health-conscious consumers. Expansion into underpenetrated markets like Eastern Europe and the Middle East offers significant growth potential. A direct-to-consumer online sales model with subscription options can provide a nimble go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile, specialized organic brands in climate-vulnerable growing regions. The market shows sustained growth over the next decade, driven by wellness trends and increasing consumer awareness. Acquisition targets should possess strong ethical sourcing credentials, such as fair-for-life certification, and proprietary processing technology like micro-filtration. Increasing consumer demand for transparently sourced products serves as a key signal for investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify Sourcing Geographies | Mitigates climate-related supply chain risks in the Philippines and Indonesia. |
| Invest in Micro-filtration Technology | Enhances product quality and extends shelf-life for premium organic coconut water offerings. |
| Develop Functional Blends | Attracts wellness-oriented consumers seeking enhanced health benefits beyond simple hydration. |
| Expand Foodservice Distribution | Opens new high-volume channels beyond traditional retail in hotels and cafes. |
| Sustainable Packaging Innovations | Aligns with EU directives and consumer demand for environmentally responsible products. |
Research Approach
Document review covered industry reports, regulatory filings from USDA and EU organic bodies, and academic literature on coconut agriculture, complemented by interviews with industry stakeholders. Primary interviews included organic coconut farmers, brand managers, retail buyers, and regulatory experts in the United States and Germany. This approach ensured bottom-up and top-down triangulation of market data and insights.
Cross-referencing historical market data with expert panel input established baseline figures and growth trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, packaging type, distribution channel, customer type, and regional market penetration. Compound annual growth rates were derived from comprehensive trend analysis and projected certified organic coconut yield per hectare and consumer wellness trend adoption rates.
Inputs from certified organic suppliers and market reports were available through the study window; gaps in real-time climate impact data introduce uncertainty bands. Forecasts reflect assumptions regarding consumer preferences and regulatory stability in key markets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Non-GMO Food Market