
 Drip Coffee Machine Market | 2026-2036
Drip Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Drip Coffee Machine Market Foresight
EU Ecodesign Directive is expanding compliance costs for new market entrants, raising the engineering threshold for heating system efficiency and standby power management. De'Longhi Appliances S.r.l. leverages its in-house thermoblock development to absorb these regulatory costs without outsourcing. Hamilton Beach Brands, Inc. sustains volume leadership in North American mass retail through dedicated factory capacity and direct importer relationships. JURA Elektroapparate AG dominates the super-automatic adjacent segment, channeling R&D spillover into precision drip platforms.
A drip coffee machine brews ground coffee by heating water to optimal extraction temperature and dispersing it evenly over a filter basket, typically operating between 195°F and 205°F with wattage ranging from 600W to 1500W depending on capacity class. The device serves commercial and residential users requiring batch brewing with minimal manual intervention. Programmable units with brew timers command premium shelf positioning in household channels, while thermal carafe configurations capture margin pools from hospitality buyers seeking extended holding without burnt flavor degradation. Single-serve drip hybrids represent the fastest-growing product type as office end users balance convenience against pod waste regulations.
EMA and ECHA frameworks in Europe govern material safety for food-contact plastics and heating element coatings, while the FDA sets extraction temperature and material migration limits in the United States. These bodies collectively shape product development pipelines, with compliance timelines often determining regional launch sequencing. Stakeholders must monitor pending amendments to standby power rules and filter material bans, as these will force hardware redesigns ahead of enforcement windows.
Market Dynamics
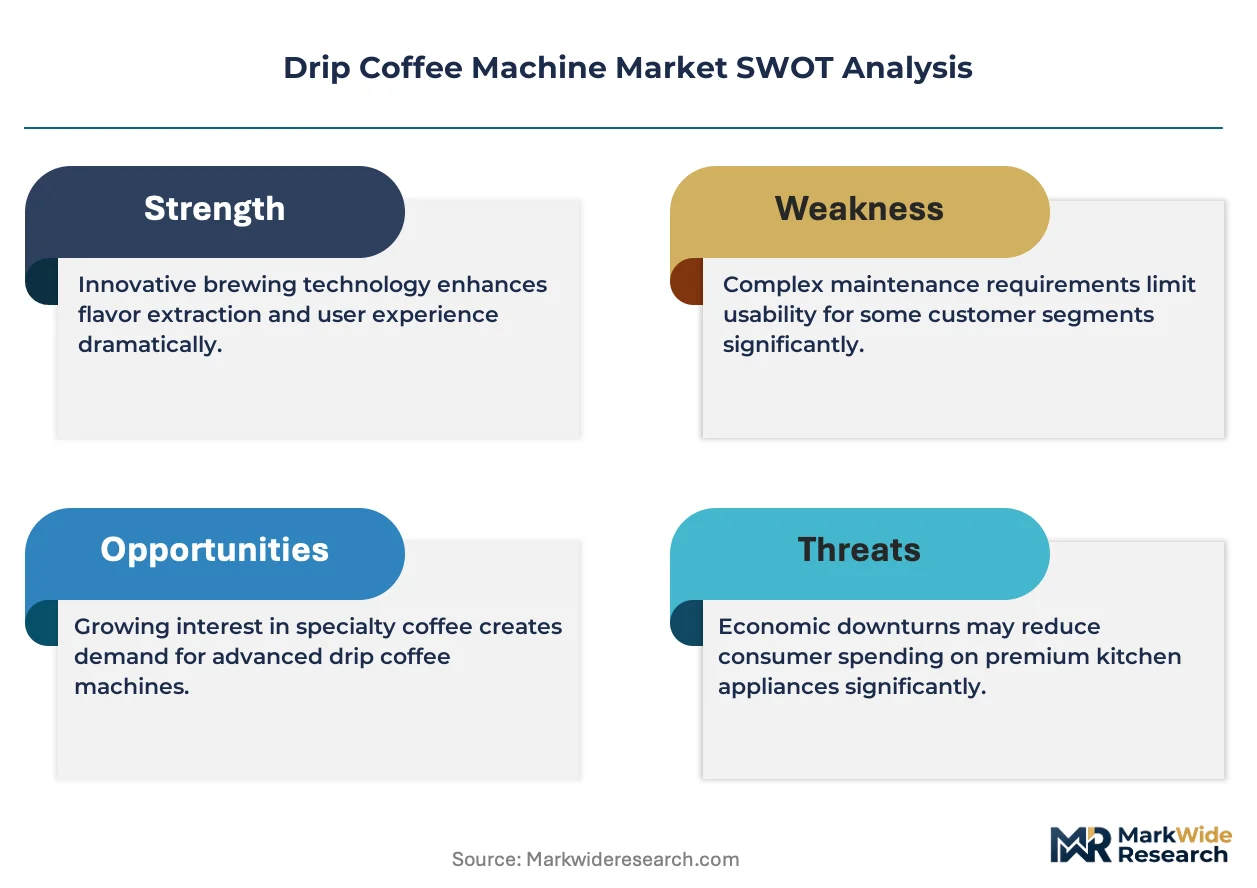
EU Ecodesign Directive standby power limits are forcing heating element redesigns across the supply base, compressing margins for manufacturers lacking captive thermoblock engineering.
Growth Catalysts
- Specialty coffee shop expansion:Back-of-house equipment refresh cycles are accelerating as chains standardize on programmable batch brewers with thermal carafe configurations.
- REACH compliance spillover:Food-contact plastic safety frameworks are elevating material specifications, creating preference premiums for verified heating element coatings.
- Office channel hybridization:Single-serve drip hybrids are displacing pod systems as waste regulations tighten in municipal jurisdictions.
Market Restraints
- Heating element cost volatility:Nickel-chromium alloy prices fluctuate with stainless steel feedstock markets, squeezing margin on entry-class units.
- Thermoblock supply concentration:Precision casting capacity clusters in German and Italian supplier networks, creating bottleneck risk for new entrants.
- Pod waste substitution threat:Compostable pod alternatives and manual pour-over equipment capture premium household segments seeking ritual engagement.
Strategic Opportunities
- German premium adoption:Manual brewing culture intersects with automatic drip upgrade cycles, opening positioning for precision temperature control platforms.
- CSRD disclosure mandates:Corporate sustainability reporting requirements drive hospitality procurement toward repairable designs with documented lifecycle footprints.
- Smart home convergence:Wi-Fi connectivity and voice assistant integration enable subscription-filter replenishment models in residential channels.
Industry Challenges
- Thermodynamics engineering scarcity:Optimal extraction temperature control across variable batch sizes demands specialized fluid dynamics expertise concentrated in legacy appliance makers.
- CE-MDR dual certification timelines:Parallel electrical safety and medical device adjacent compliance pathways delay launch sequencing for wellness-positioned brewers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drip Coffee Machine Market |
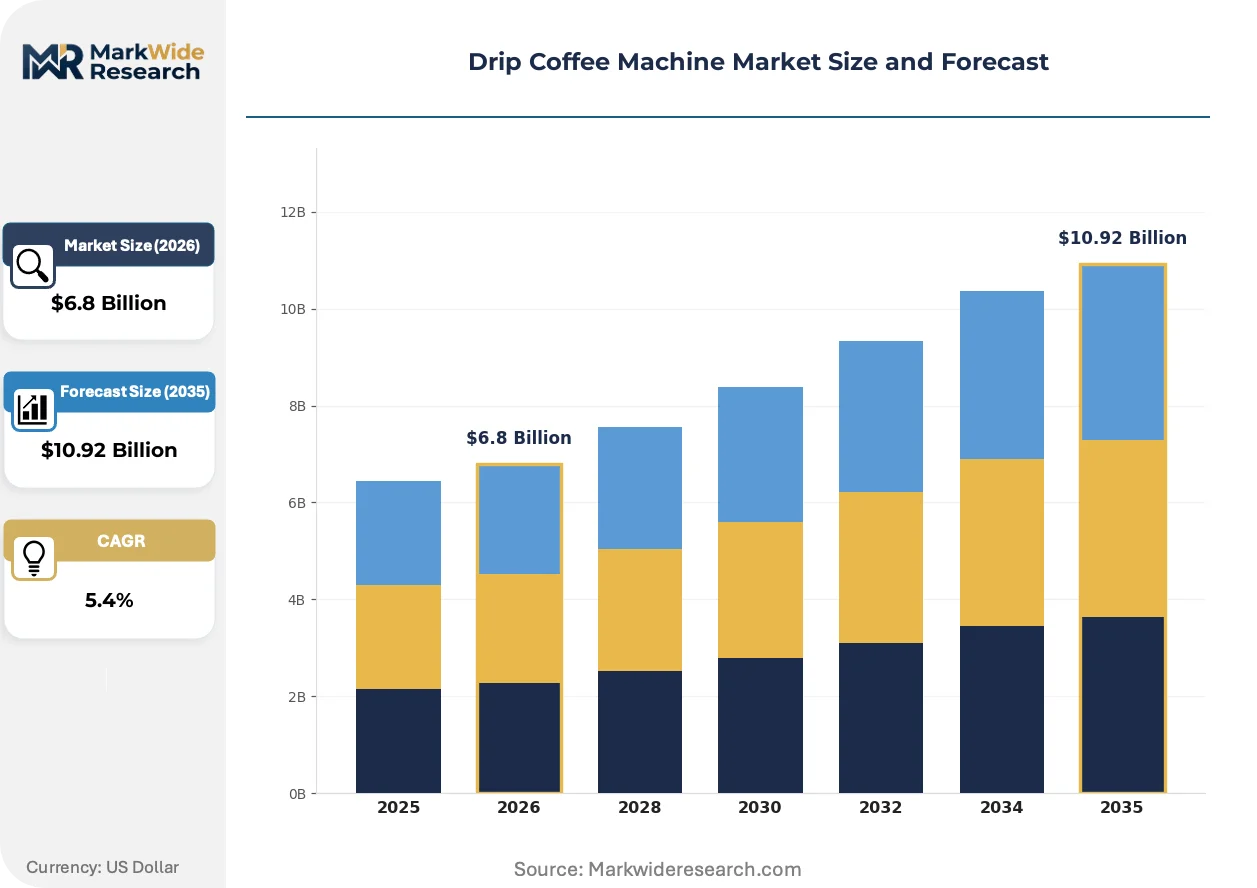
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable, Single-Serve, Thermal, Standard End User: Office, Household, Hospitality, Retail Capacity: 2-Cup, 4-Cup, 10-Cup, 12-Cup Feature: Brew Timer, Auto Shut-Off, Built-In Grinder, Reusable Filter |
| Companies Covered | Koninklijke Philips N.V., De'Longhi Appliances S.r.l., Krups GmbH, BUNN-O-Matic Corporation, Melitta Group, Hamilton Beach Brands, Inc., Cuisinart, Shark Ninja, JURA Elektroapparate AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drip Coffee Machine Market Shifts & Advancements
Precision temperature profiling and embedded connectivity are redefining hardware value propositions, shifting competitive differentiation from capacity specifications to extraction control and data-enabled service layers.
Thermoblock heating systems with PID temperature control are absorbing engineering investment from traditional boiler architectures. Specialty coffee chains in Germany and the Netherlands are specifying these platforms for back-of-house consistency. The technology is absorbing margin pressure from EU standby power regulations by eliminating thermal mass energy losses.
EU Ecodesign Directive standby power thresholds are compressing control board architectures across the supply base. Manufacturers must redesign power management circuits to meet sub-1-watt idle limits. German and Italian producers with in-house electronics development are responding fastest, while outsourced engineering houses face 12-18 month redesign cycles.
Subscription-filter replenishment models are displacing traditional retail attachment sales in North American residential channels. Direct-to-consumer platforms bundle scheduled filter delivery with connected machine diagnostics. This pattern is most visible in urban coastal markets where smart home penetration intersects with specialty coffee consumption habits.
Drip Coffee Machine Market Segmentation
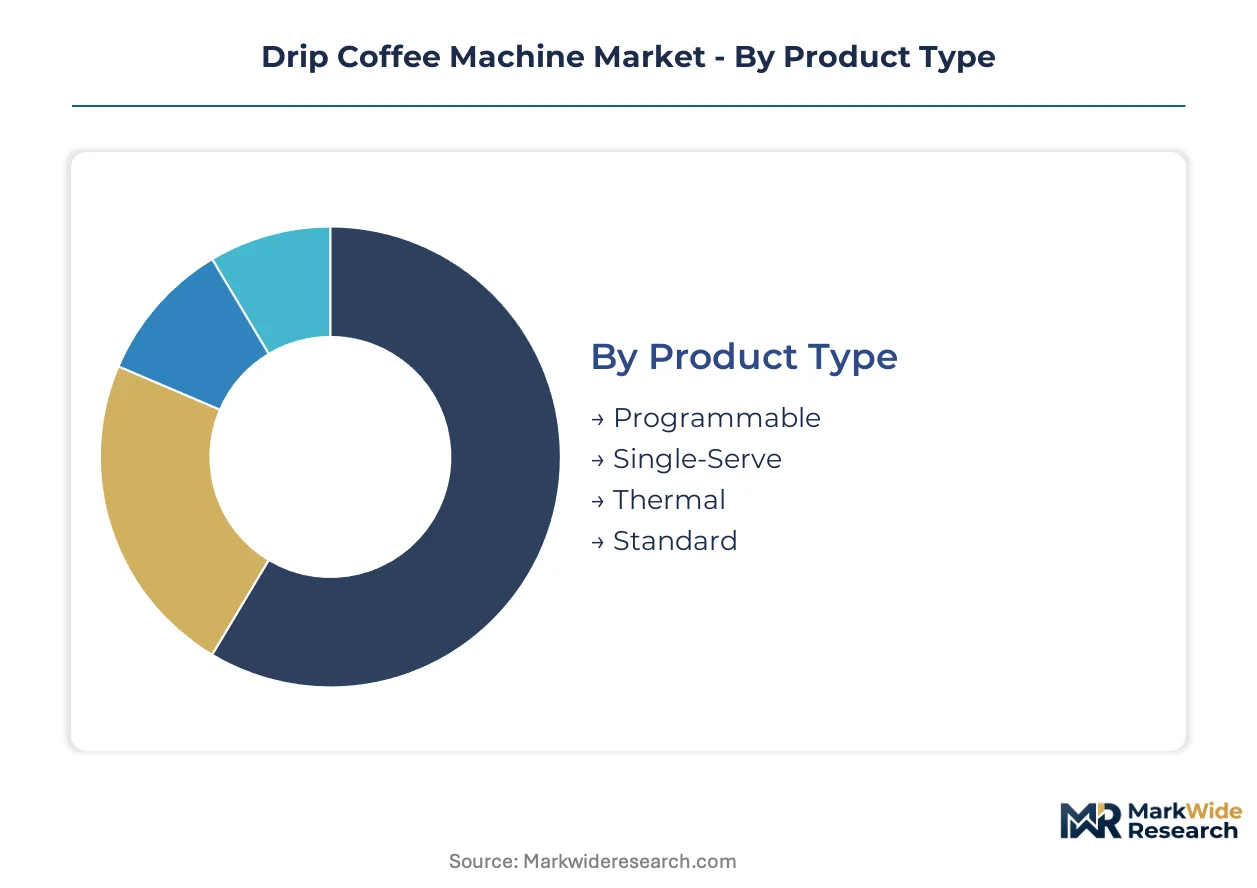
Product architecture in the drip coffee machine market clusters around brewing control interfaces, thermal management systems, and user-programmable functions. Understanding how these technical dimensions intersect with buyer procurement patterns reveals where engineering investment concentrates and margin pools form.
Product Type:
Supply concentration in thermoblock casting and PID controller sourcing shapes which product architectures achieve viable unit economics at scale.
- Programmable:Units integrate microprocessor-controlled brew timers and temperature staging with wattage modulation between 900W and 1500W. Demand concentrates in German specialty coffee chains standardizing back-of-house batch protocols, driven by EU Ecodesign standby power compliance requirements that favor sophisticated power management circuits.
- Single-Serve:Hybrid architectures combine drip brewing mechanics with portion-controlled dosing, typically operating at 600W to 800W with rapid-cycle thermoblocks. Office procurement in Netherlands municipal jurisdictions is displacing pod systems as waste regulations tighten, making this configuration the priority refresh category.
- Thermal:Double-walled stainless carafes replace hot plates, maintaining extraction temperature above 175°F for 90 minutes without burnt flavor degradation.
- Standard:Glass carafe configurations with warming plate architectures dominate entry-class residential channels in North American mass retail.
Programmable units absorb the bulk of installed capacity in commercial back-of-house deployments; Single-Serve is expanding most quickly as office channel procurement shifts away from pod-based systems.
End User:
Procurement authority and lifecycle replacement frequency vary sharply across buyer categories, with hospitality and office segments driving premium feature adoption.
- Office:Centralized purchasing departments specify batch capacity, energy efficiency metrics, and connected diagnostics for fleet management. Demand concentrates in German corporate campuses and Netherlands co-working operators, driven by CSRD disclosure mandates requiring documented equipment lifecycle footprints.
- Household:Individual consumers prioritize counter footprint and aesthetic integration with kitchen cabinetry. Urban coastal markets in the United States with elevated smart home penetration are adopting Wi-Fi connected units with subscription filter replenishment.
- Hospitality:Boutique hotel procurement specifies thermal carafe configurations for breakfast service consistency.
- Retail:Specialty coffee shop chains accelerate equipment refresh cycles to standardize extraction protocols across locations.
Office procurement absorbs the bulk of premium-tier volume; Hospitality is climbing the fastest as boutique property development accelerates in Portugal and Croatia.
Capacity:
Batch volume specifications determine heating element wattage requirements and thermoblock thermal mass engineering, with mid-capacity platforms achieving optimal unit economics.
- 10-Cup:1.5-liter brew volumes with 1200W to 1500W heating elements serve commercial batch requirements and large household segments. Demand concentrates in German household upgrade cycles where manual brewing culture intersects with automatic convenience, driven by precision temperature control specifications from specialty coffee associations.
- 12-Cup:Maximum residential batch configurations with extended warming plate or thermal carafe options target multi-generational households and small hospitality operations.
- 2-Cup:Compact thermoblock systems with 600W power draw prioritize counter space efficiency.
- 4-Cup:Mid-compact formats bridge single-serve convenience and small-batch brewing for one to two person households.
10-Cup platforms absorb the bulk of engineering investment and component sourcing scale; 4-Cup is gaining share fastest as urban household formation trends toward smaller unit sizes.
Feature:
Feature bundling strategies differentiate price tiers while regulatory compliance mandates reshape which functions become baseline rather than premium.
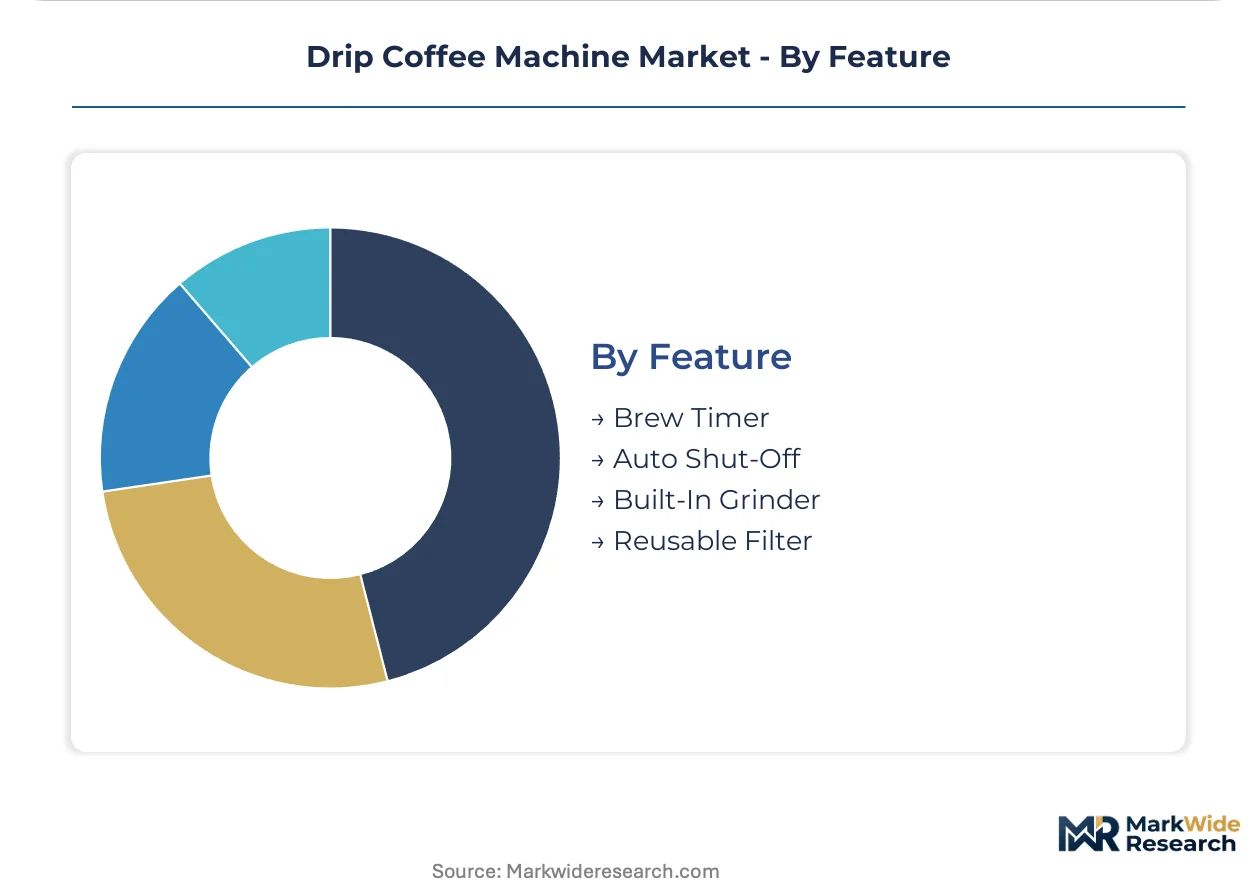
- Auto Shut-Off:Mandatory under EU Ecodesign Directive standby power thresholds and proliferating US state-level energy efficiency codes. Demand concentrates in California and New York retail channels where regulatory enforcement is strictest, driven by retailer compliance requirements that effectively make this feature non-negotiable for shelf placement.
- Brew Timer:Programmable start functions with LCD or LED interfaces command premium positioning in North American residential channels.
- Built-In Grinder:Integrated burr systems with dose control add 200W to 300W power draw and significant unit cost.
- Reusable Filter:Stainless mesh or gold-tone basket systems reduce ongoing consumable costs and address waste reduction preferences.
Auto Shut-Off absorbs the bulk of control board engineering resources as regulatory mandates expand; Built-In Grinder is expanding most quickly as single-serve hybrid architectures integrate grinding functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial zones anchor European production concentration, with Bavarian precision engineering clusters absorbing thermoblock casting capacity and Milanese design houses controlling aesthetic specification flows for premium residential channels.
Germany
Specialty coffee chains in Berlin and Hamburg accelerate back-of-house equipment refresh cycles, standardizing on programmable batch brewers with thermal carafe configurations. EU Ecodesign Directive standby power limits under REACH enforcement tighten heating element efficiency mandates. Bavarian supplier networks around Munich concentrate precision thermoblock casting capacity, creating bottleneck conditions for new market entrants lacking captive engineering resources.
United States
Urban coastal markets in California and New York drive Wi-Fi connected unit adoption with subscription filter replenishment models. FDA extraction temperature and material migration limits govern food-contact plastic specifications for heating element coatings. Seattle and Portland specialty coffee cultures intersect with smart home penetration, creating demand concentration for precision temperature control platforms in residential channels.
Netherlands
Co-working operators and corporate campuses in Amsterdam specify batch capacity equipment with documented lifecycle footprints under CSRD disclosure mandates. Municipal waste regulations tighten against pod systems, displacing single-serve formats toward drip hybrid architectures. Eindhoven-region electronics suppliers provide PID controller components for programmable unit power management circuits.
Italy
Milanese design houses and Venetian appliance manufacturers control aesthetic specification flows for premium European residential channels. CE marking and RoHS compliance frameworks elevate material specifications for heating element coatings. Northern Italian industrial clusters around Treviso concentrate thermoblock engineering expertise, supplying German and French OEM assembly operations.
Japan
Tokyo metropolitan households prioritize compact 4-cup formats as urban unit sizes shrink, driving fastest-growing capacity segment demand. METI energy efficiency standards and JIS product safety certifications shape control board architecture requirements. Osaka-based precision manufacturers supply compact thermoblock systems for Asian export markets, leveraging miniaturization expertise from adjacent consumer electronics sectors.
Drip Coffee Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with consolidated volume leadership in mass retail channels coexisting with fragmented premium positioning around precision engineering capabilities. Three archetypes dominate: European heritage appliance houses with captive thermoblock development, North American mass-market brands with dedicated factory capacity and direct importer relationships, and Swiss-German precision specialists channeling R&D spillover from adjacent super-automatic segments. Competitive moves concentrate on backward integration into heating system engineering and strategic partnerships for connected platform development.
Among European heritage appliance houses, De'Longhi Appliances S.r.l. and JURA Elektroapparate AG occupy positions exemplifying thermoblock engineering specialization, while Hamilton Beach Brands, Inc. anchors North American mass-market scale operations. These three entities represent distinct competitive vectors: Italian engineering integration, Swiss precision automation heritage, and volume manufacturing efficiency.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| De'Longhi Appliances S.r.l. |
| Krups GmbH |
| BUNN-O-Matic Corporation |
| Melitta Group |
| Hamilton Beach Brands, Inc. |
| Cuisinart |
| Shark Ninja |
| JURA Elektroapparate AG |
| Others |
Supply & Pricing Matrix
Thermoblock heating system adoption across programmable drip platforms simultaneously compresses per-unit manufacturing costs and concentrates supplier power among Bavarian and Northern Italian precision casting networks. This technology transition forces manufacturers to absorb upfront retooling investments while competing on extraction temperature precision as the primary price differentiator.
Pricing Analysis
Lead-time premiums for rapid thermoblock delivery command pricing advantages over spot inventory purchases from secondary distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by PID temperature control sophistication and thermal carafe configuration. Pricing pressure stems from nickel-chromium alloy feedstock volatility squeezing entry-class unit margins. Mass retail buyers in North American channels exhibit highest price sensitivity, while German specialty coffee chains prioritize extraction consistency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian thermoblock casting capacity, where Treviso-region and Bavarian supplier networks anchor precision heating component production. Raw material dependencies center on nickel-chromium resistance wire, food-grade stainless steel feedstock, and PID controller semiconductors sourced from Eindhoven-region electronics suppliers. Tariff exposure on Chinese-sourced control board assemblies creates cost uncertainty for outsourced engineering houses. Distribution runs through dedicated factory capacity relationships for volume leaders and direct importer channels for premium European heritage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive thermoblock engineering and in-house PID controller development determine who absorbs EU Ecodesign compliance costs without margin erosion.
For Market Incumbents: To counter thermoblock supply concentration bottlenecks, secure captive casting capacity in Bavarian or Northern Italian supplier networks through equity partnerships or long-term offtake agreements. Invest in in-house electronics development to compress 12-18 month control board redesign cycles into 6-9 month response windows for standby power regulation amendments. For New Entrants and Emerging Players: EU Ecodesign Directive standby power limits in Germany open a window for precision temperature control platforms targeting specialty coffee chain back-of-house refresh cycles. White-space concentrates in 4-cup compact formats for Tokyo metropolitan households and subscription-filter replenishment models for North American urban coastal markets. Prioritize direct-to-consumer launch with bundled consumable logistics over mass retail shelf placement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified appliance conglomerates seeking thermoblock engineering capabilities. Long-term viability hinges on backward integration into heating system design rather than assembly-only positioning. Watch for CSRD disclosure mandate enforcement intensity in Netherlands corporate procurement as the inflection signal for repairable-design premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Thermoblock Development | Absorbs EU Ecodesign compliance costs without outsourcing margin erosion to German suppliers. |
| PID Controller Integration | Enables precision temperature platforms for specialty coffee chain extraction protocol standardization. |
| Subscription Filter Replenishment | Captures recurring revenue streams through Wi-Fi connected diagnostics in North American residential channels. |
| Compact Format Miniaturization | Addresses Tokyo metropolitan household space constraints through Osaka-derived thermoblock expertise. |
| Thermal Carafe Configuration | Commands hospitality procurement premiums by eliminating burnt flavor degradation in boutique hotel breakfast service. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving appliance R&D directors, specialty coffee chain procurement managers, thermoblock casting plant engineers, and hospitality equipment buyers. FDA extraction temperature standards, EU Ecodesign Directive amendments, and METI energy efficiency benchmarks provided regulatory boundary conditions. Bottom-up unit shipment modeling triangulated against top-down value estimates from customs trade flows and retail audit databases.
Granularity-level modeling disaggregated volume and value across product type, end user, capacity class, and feature configuration throughout the projection horizon. CAGRs derived from segmented growth rate analysis incorporating replacement cycle dynamics, regulatory enforcement timelines, and channel shift patterns. Forecast inputs included specialty coffee shop expansion trajectories, nickel-chromium alloy price volatility assumptions, and smart home penetration rates in urban coastal markets.
The model assumes a particular technology adoption path; alternative pathways for boiler-to-thermoblock transition timing would alter the outlook for component supplier margin capture. Forecasts reflect assumptions about EU standby power rule enforcement consistency and REACH compliance spillover into food-contact plastic specifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Beans Market
Coffee
Coffee Roaster Machine Market
Coffee
India Coffee Roaster Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Raw Coffee Beans Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Coffee Pods and Capsules Market
Coffee
Decaffeinated Coffee Market
Coffee
Organic Coffee Market
Coffee
Green Coffee Extract Market
Coffee
Tea and Coffee Bags Market
Coffee
Cold Brew Coffee Makers Market
Coffee
South America Coffee Market