
 Germany Food Sweetener Market | 2026-2036
Germany Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Sweetener Market Foresight
Enzymatic conversion of starch into high-intensity sweeteners is tilting production economics toward biotech-derived alternatives. Cargill Incorporated leverages its European bioprocessing footprint to supply fermentation-based erythritol and stevia extracts to German formulators. Nordzucker AG anchors beet sugar supply through its dominant Central European agricultural contracts. Tate & Lyle competes with specialty soluble fibers that double as bulking agents in reduced-sugar bakery applications.
Germany food sweeteners encompass caloric and non-caloric substances that impart sweetness to food matrices, spanning carbohydrate-based sugars, sugar alcohols, and high-potency compounds such as steviol glycosides with sweetness intensities 200–400 times that of sucrose. These ingredients function as flavor modulators, preservatives, and texture agents across industrial food production. Sucrose and fructose still occupy the largest volume share in confectionery and bakery, though margin pools are migrating toward stevia and sucralose as beverage brands reformulate for clean-label positioning. Liquid formulations lead in dairy and beverage integration, while powder and granulated forms dominate dry-mix manufacturing for nutritional supplements.
The Federal Ministry of Food and Agriculture enforces strict labeling under the German Food and Feed Code, while EFSA evaluates novel sweetener safety dossiers prior to EU-wide authorization. REACH compliance and the EU Green Deal's carbon border adjustments are forcing importers to document supply chain emissions for biotech-derived inputs. Stakeholders must monitor EFSA's evolving stance on stevia glycoside specifications and KBA-adjacent sustainability audits for agricultural feedstock transport.
Market Dynamics
Enzymatic bioprocessing is compressing production economics for plant-derived sweeteners, forcing beet sugar refiners to defend margin positions through captive agricultural contracts and fermentation scale-up.
Growth Catalysts
- EU Farm to Fork Strategy:Sustainability mandates under the European Green Deal accelerate beverage reformulation toward steviol glycosides and sugar alcohols. German dairy processors in Bavaria's food corridor drive bulk procurement of reduced-calorie systems.
- Clean-label positioning:Confectionery brands abandon artificial high-intensity sweeteners for fermentation-based erythritol. Consumer packaged goods manufacturers prioritize ingredient transparency on front-of-pack labeling.
- Bioprocessing scale-up:Starch-to-sweetener enzymatic conversion reduces unit costs for high-potency compounds. Industrial biotechnology infrastructure in Central European chemical clusters enables captive supply integration.
Market Restraints
- Beet sugar supply concentration:Agricultural contracts lock processors into fixed crop cycles, limiting feedstock flexibility for seasonal demand swings in beverage manufacturing.
- EFSA novel food authorization timelines:Safety dossier evaluations for emerging stevia glycoside specifications create 18-24 month market entry delays for biotech-derived variants.
- Natural sugar substitution ceiling:Sucrose retains irreplaceable functionality in caramelization and Maillard reactions, capping penetration in premium confectionery segments.
Strategic Opportunities
- North Rhine-Westphalia beverage clusters:Soft drink concentration around Cologne-Düsseldorf logistics hubs creates localized demand for liquid sweetener formulations with just-in-time delivery.
- EU carbon border adjustment mechanism:Documented supply chain emissions for imported biotech inputs favor domestic fermentation capacity expansion over Asian sucralose sourcing.
- Bakery soluble fiber convergence:Specialty fibers doubling as bulking agents in reduced-sugar applications open dual-function ingredient positioning against pure sweetener competitors.
Industry Challenges
- Fermentation technician scarcity:Industrial biotechnology scale-up requires specialized bioprocess engineering talent that German technical universities produce insufficiently for current expansion timelines.
- REACH compliance documentation:Biotech-derived sweetener importers face complex substance registration requirements for novel enzymatic conversion intermediates, extending customs clearance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Sweetener Market |
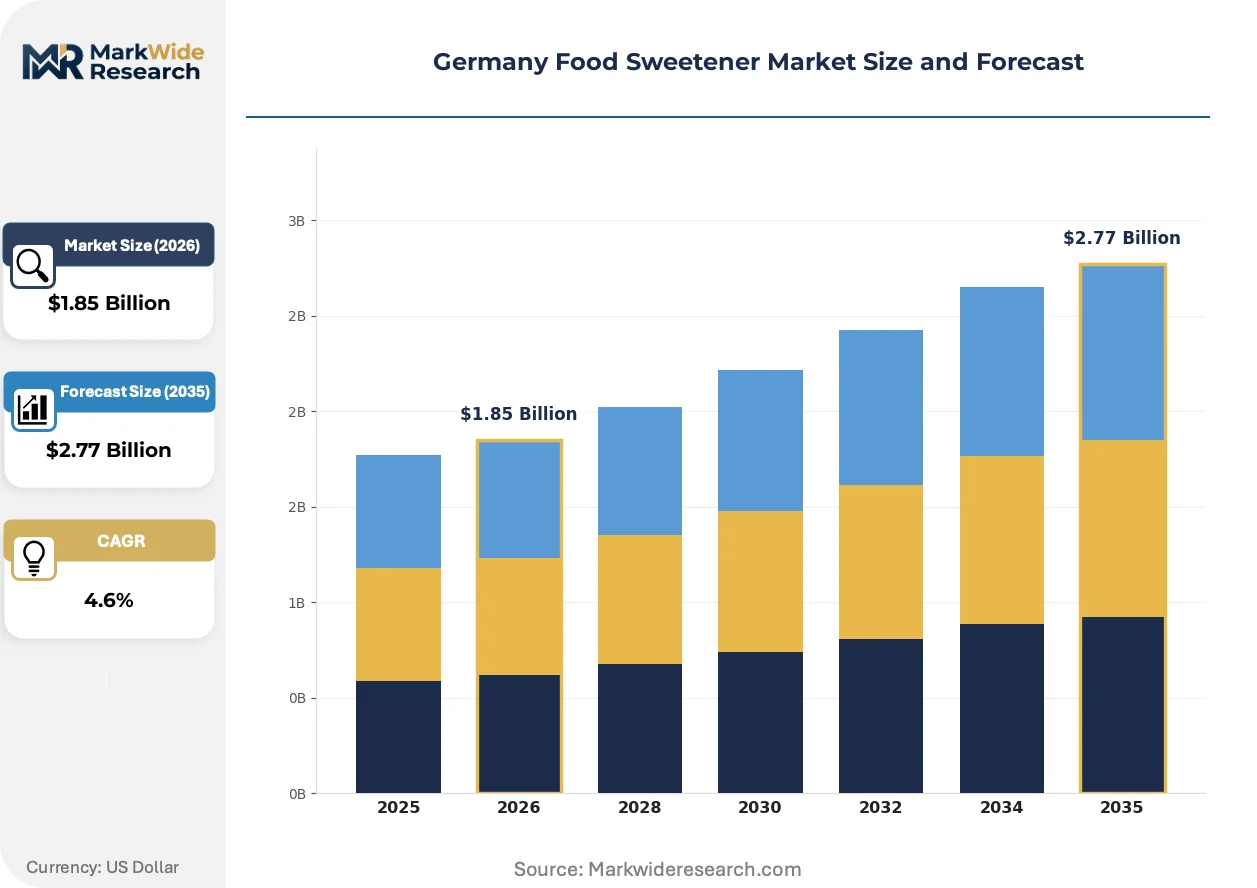
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Fructose, Stevia, Aspartame, Sucralose, Acesulfame Potassium Form: Liquid, Powder, Granulated, Syrup, Tablet Application: Beverages, Confectionery, Bakery, Dairy Products, Nutritional Supplements, Sauces & Dressings End User: Food & Beverage Manufacturers, Nutraceutical Companies, Restaurants, Catering Services |
| Companies Covered | Tate & Lyle, Nordzucker AG, Cargill Incorporated, Denk Ingredients, Organic Stevia GmbH, Archer Daniels Midland Company, Ingredion Incorporated, Stevialine GmbH & Co KG, Roquette Frères, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Sweetener Market Shifts & Advancements
Biotechnology and regulatory transparency are converging to redefine competitive advantage in German sweetener supply, with enzymatic processes and carbon-accounted sourcing becoming baseline requirements rather than differentiators.
Fermentation-based erythritol production is hybridizing with traditional sucrose refining infrastructure. Bavarian dairy processors adopt hybrid sweetening systems at accelerated pace, blending sugar alcohols with high-potency extracts to achieve 30-50% calorie reduction without sensory compromise. This hybridization is compressing margins for single-ingredient suppliers while rewarding integrated bioprocessing platforms.
REACH and the EU Green Deal's carbon border adjustments are forcing documented emissions accounting across agricultural feedstock transport. German importers now face mandatory supply chain disclosure for biotech-derived inputs, with KBA-adjacent sustainability audits becoming standard for Central European beet sugar logistics. Beverage manufacturers in North Rhine-Westphalia respond by shortening supply chains to domestic fermentation facilities.
Clean-label procurement now prioritizes certified sustainable sourcing over cost minimization. German retail chains demand third-party verification for stevia and erythritol origin claims, displacing spot-market purchasing with long-term offtake agreements tied to agricultural audit standards. This behavioral shift concentrates procurement leverage among large-scale food processors with dedicated sustainability compliance teams.
Germany Food Sweetener Market Segmentation
Sweetener procurement patterns in Germany diverge sharply across product chemistry, physical form, and end-use specifications. Bavarian dairy processors and North Rhine-Westphalia beverage clusters drive divergent demand profiles that reward suppliers with flexible formulation capabilities.
Product Type:
Plant-derived high-intensity compounds and fermentation-based sugar alcohols now command premium positioning against legacy carbohydrate sweeteners.
- Sucrose:Beet-derived crystalline sugar retains dominant volume share in caramelization-dependent confectionery applications. Bavarian chocolate manufacturers anchor procurement through Nordzucker AG's captive agricultural contracts, though margin compression from biotech alternatives intensifies pricing pressure.
- Stevia:Steviol glycosides with 200–400x sucrose potency enable deep calorie reduction in clean-label beverage reformulation. North Rhine-Westphalia soft drink producers drive bulk demand for Reb M and Reb D variants as EFSA evaluates expanded glycoside specifications.
- Fructose:Fruit-derived monosaccharide concentrated in liquid formulations for beverage manufacturing.
- Aspartame:Methyl ester dipeptide facing accelerated displacement in German retail channels due to clean-label procurement mandates.
- Sucralose:Chlorinated disaccharide imported primarily from Asian manufacturing bases, now disadvantaged under EU carbon border adjustment documentation requirements.
- Acesulfame Potassium:Synthetic high-intensity compound concentrated in cost-optimized industrial applications with limited front-of-pack visibility.
The dominant share belongs to sucrose, while stevia is closing the gap fastest.
Form:
Physical state determines integration economics across Germany's distinct manufacturing clusters, with liquid and powder formats commanding divergent logistics infrastructures.
- Liquid:Pumpable concentrates dominate North Rhine-Westphalia beverage manufacturing where just-in-time dosing systems enable continuous production lines. Cologne-Düsseldorf logistics hubs favor tanker-delivered formulations that eliminate dry-mix handling costs.
- Powder:Fine-milled particles serve dual-function roles as bulking agents in reduced-sugar bakery applications. Tate & Lyle's soluble fiber powders capture this positioning through texture-modification properties that pure sweeteners cannot replicate.
- Granulated:Free-flowing crystals preferred in tabletop and small-format packaging for retail channels.
- Syrup:Viscous solutions concentrated in industrial confectionery where moisture retention properties prove critical.
- Tablet:Compressed formats limited to foodservice and institutional catering segments with portion-control requirements.
Powder formats hold the largest installed base, yet liquid formulations are expanding most quickly in beverage-centric regions.
Application:
Calorie-reduction targets and clean-label positioning create divergent technical requirements across Germany's food processing verticals.
- Beverages:The most aggressive reformulation activity concentrates here, with stevia-erythritol hybrid systems achieving 30–50% calorie reduction. KBA-adjacent sustainability audits now govern sweetener logistics for major producers.
- Bakery:Maillard reaction requirements and moisture retention properties sustain sucrose's irreplaceable role in premium segments, though soluble fiber bulking agents gain traction in reduced-sugar formulations.
- Confectionery:Caramelization chemistry and crystallization control favor traditional sugar alcohols in chocolate and hard candy manufacturing.
- Dairy Products:Fermented milk applications in Bavaria's processing corridor drive demand for heat-stable high-intensity compounds.
- Nutritional Supplements:Powder and tablet formats dominate this specification-driven segment with stringent purity requirements.
- Sauces & Dressings:Viscosity modification and shelf-stability requirements favor liquid syrup formulations with preservative functionality.
Beverages command the dominant procurement volume, while bakery applications show the steepest expansion trajectory for hybrid sweetening systems.
End User:
Scale and compliance capability stratify Germany's sweetener demand between industrial manufacturers and fragmented foodservice operators.
- Food & Beverage Manufacturers:Integrated procurement teams with dedicated sustainability compliance functions concentrate demand among large-scale processors. Long-term offtake agreements with documented supply chain emissions displace spot-market purchasing.
- Nutraceutical Companies:Specification-intensive buyers prioritizing certified origin claims and third-party verification for stevia and erythritol inputs.
- Restaurants:Fragmented demand with limited negotiating leverage, concentrated in standard granulated and liquid formats.
- Catering Services:Portion-control and cost-optimization priorities drive tablet and bulk syrup procurement.
Food and beverage manufacturers capture the dominant share, while nutraceutical companies are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial food processors with integrated procurement functions concentrate sweetener demand across Germany's manufacturing belt. Bavarian dairy clusters and North Rhine-Westphalia beverage corridors anchor volume procurement. Federal sustainability mandates reshape logistics networks toward documented low-carbon supply chains.
Bavaria
Dairy processors in the Munich-Ingolstadt corridor drive bulk demand for heat-stable high-intensity compounds in fermented milk applications. The German Food and Feed Code enforces strict labeling requirements for reduced-calorie claims. Chocolate manufacturers around Würzburg anchor beet sugar procurement through long-term agricultural contracts.
North Rhine-Westphalia
Soft drink concentration around Cologne-Düsseldorf logistics hubs creates localized demand for liquid sweetener formulations with just-in-time delivery systems. REACH compliance documentation requirements extend customs clearance cycles for biotech-derived imports. Beverage manufacturers respond by shortening supply chains to domestic fermentation facilities.
Baden-Württemberg
Premium confectionery producers in the Stuttgart region sustain sucrose demand for caramelization-dependent applications. KBA-adjacent sustainability audits govern agricultural feedstock transport emissions. Specialty food manufacturers around Karlsruhe pilot hybrid sweetening systems blending sugar alcohols with steviol glycosides.
Lower Saxony
Beet sugar refining infrastructure concentrates around the Magdeburg-Braunschweig agricultural zone with captive crop cycles. The EU Green Deal's carbon border adjustment mechanism disadvantages imported Asian sucralose. Regional processors defend margin positions through fermentation scale-up investments.
Hesse
Nutraceutical and pharmaceutical sweetener specifications concentrate around Frankfurt-Rhine-Main logistics hubs with stringent purity requirements. EFSA novel food authorization timelines create entry delays for emerging stevia glycoside variants. Third-party verification services cluster here to serve certified origin claim demands.
Germany Food Sweetener Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structurally tiered supplier base. Large-scale agricultural processors and integrated bioprocessing platforms dominate volume contracts, while niche extractors capture premium positioning in certified organic segments. Two strategic archetypes predominate: beet sugar refiners with captive agricultural contracts and fermentation-based specialty ingredient platforms. Competitive moves concentrate on backward integration into feedstock supply and portfolio diversification toward dual-function bulking agents.
Among the named entities in this market, Cargill Incorporated exemplifies the integrated bioprocessing archetype with European supply infrastructure, while Nordzucker AG represents the agricultural contract model anchored in Central European beet cultivation. Tate & Lyle occupies a position bridging specialty soluble fiber positioning with reduced-sugar formulation expertise. These three companies illustrate the competitive tension between legacy sugar refining and enzymatic conversion technologies reshaping procurement economics.
| Leading Market Players |
|---|
| Tate & Lyle |
| Nordzucker AG |
| Cargill Incorporated |
| Denk Ingredients |
| Organic Stevia GmbH |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Stevialine GmbH & Co KG |
| Roquette Frères |
| Others |
Supply & Pricing Matrix
KBA-adjacent freight corridors along the Cologne-Düsseldorf logistics belt compress transport costs for liquid sweetener tankers, amplifying pricing power for domestic fermentation facilities while forcing importers to absorb carbon border adjustment documentation expenses that widen the landed cost gap against beet sugar refiners with captive agricultural contracts.
Pricing Analysis
Cost-plus contracts indexed to EU agricultural commodity benchmarks dominate procurement between Bavarian dairy processors and Central European beet sugar suppliers. Price differentiation rests on certification grade—organic stevia extracts command substantial premiums over conventional fermentation-derived erythritol—and volume scale, with annual offtake agreements above ten thousand metric tons unlocking preferential terms. Pricing pressure stems from enzymatic bioprocessing scale-up compressing unit economics for high-intensity compounds, eroding legacy sucrose margins. Industrial food and beverage manufacturers exhibit lowest price sensitivity due to long-term compliance investments, while fragmented foodservice operators remain most exposed to spot-market volatility.
Supply Chain Analysis
Export-control regimes governing enzymatic conversion technologies limit flow of specialized bioprocessing equipment from Germany to non-EU destinations, constraining technology diffusion. Geographic supply concentrates in Germany, China, and India—German fermentation capacity anchors European demand, Chinese manufacturers dominate sucralose synthesis, and Indian extractors supply raw steviol glycosides. Raw material dependencies include Central European sugar beet, Southeast Asian stevia leaf, and starch feedstocks from Black Sea grain corridors. Single-source vulnerability pervades the Reb M stevia glycoside segment where patented extraction methods concentrate supply. Distribution runs through integrated processor-direct channels for large manufacturers, with specialty distributors serving nutraceutical and foodservice segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement leverage is concentrating among large-scale food and beverage manufacturers with dedicated sustainability compliance teams, fragmenting negotiating power for smaller processors and forcing supplier consolidation around integrated bioprocessing platforms.
For Market Incumbents: Harden defensive positions through backward integration into captive agricultural feedstock supply and accelerated fermentation capacity expansion in North Rhine-Westphalia. The threat of enzymatic bioprocessing newcomers with lower carbon intensity profiles demands immediate response. Certification investment in EU organic and carbon-neutral labeling schemes becomes essential for maintaining premium positioning against clean-label competitors. For New Entrants and Emerging Players: Nutraceutical specifications around Frankfurt-Rhine-Main logistics hubs present underpenetrated white space where stringent purity requirements and third-party verification demands deter commodity suppliers. Soluble fiber bulking agents for reduced-sugar bakery applications offer parallel entry vector with less entrenched incumbent control. Go-to-market success requires direct technical sales engagement with formulation chemists rather than procurement-led selling. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized food ingredient divisions lacking dedicated sustainability compliance infrastructure. Long-term viability favors fermentation-based specialty platforms over legacy beet sugar refining exposed to margin compression. Watch EFSA authorization timelines for novel stevia glycoside specifications as inflection indicator for biotech-derived variant market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Domestic scale-up in Cologne-Düsseldorf corridor reduces carbon border exposure for beverage manufacturers. |
| Backward Integration into Feedstock Supply | Captive agricultural contracts with Bavarian beet growers lock in volume against biotech substitution. |
| Certification Investment | EU organic and carbon-neutral labeling defends premium positioning in clean-label procurement channels. |
| Joint Venture for Enzymatic Technology | Partnerships with Central European chemical clusters accelerate steviol glycoside cost competitiveness. |
| Long-term Supply Agreement | Documented emissions contracts with KBA-audited logistics meet EU Green Deal compliance mandates. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in documented sourcing patterns. Conversations with fermentation plant managers, procurement leads at dairy and beverage processors, distribution channel partners, and technical R&D directors at ingredient suppliers informed supply chain dynamics. Secondary validation drew from EFSA novel food dossiers, REACH substance registrations, EU customs trade data, and German Federal Ministry of Food and Agriculture enforcement records. Bottom-up volume estimates from segment-level procurement patterns triangulate against top-down market sizing from production capacity and trade flow analysis.
Calibration against historical price indices for beet sugar and stevia extracts stabilizes the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry, physical form, end-use application, and regional manufacturing cluster concentration. CAGRs derive from trend extrapolation of enzymatic bioprocessing adoption curves and regulatory-driven reformulation timelines. Industry-specific inputs encompass EFSA authorization pipeline status and EU carbon border adjustment implementation schedules.
Practitioners should monitor EFSA safety dossier evaluations and EU Green Deal carbon border enforcement intensity for early signals of forecast deviation. Material shifts in enzymatic conversion cost curves or novel stevia glycoside regulatory approvals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Japan Allulose Market
Sweeteners
Sucrose Esters Market
Sweeteners
China Food Sweetener Market
Sweeteners
Methyl Glucose Market
Sweeteners
Sucralose Market
Sweeteners
Sweet Modulator Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
Australia Allulose Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Food Sweetener Market
Sweeteners
Allulose Powder Market