
 Packaged Natural Mineral Water Market | 2026-2036
Packaged Natural Mineral Water Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Natural Mineral Water Market Insights
Recycled polyethylene terephthalate is repositioning cost structures across the bottled water sector, trimming virgin plastic dependency while preserving shelf stability. Nestle SA leverages its European spring network to sustain premium positioning. PepsiCo Inc. anchors North American volume through direct-store-delivery infrastructure. Danone S.A. differentiates via specialized glass bottling for hospitality channels.
Packaged natural mineral water denotes water sourced from protected underground formations, containing minimum total dissolved solids of 250 parts per million, and bottled at origin without chemical treatment. Its primary commercial purpose centers on delivering microbiologically safe hydration with consistent mineral composition for consumer and institutional use. Non-carbonated variants dominate household replenishment cycles, while glass bottles command margin pools in fine-dining and hotel minibars. Online retailers represent the fastest-growing distribution vector as subscription models lock in recurring residential demand.
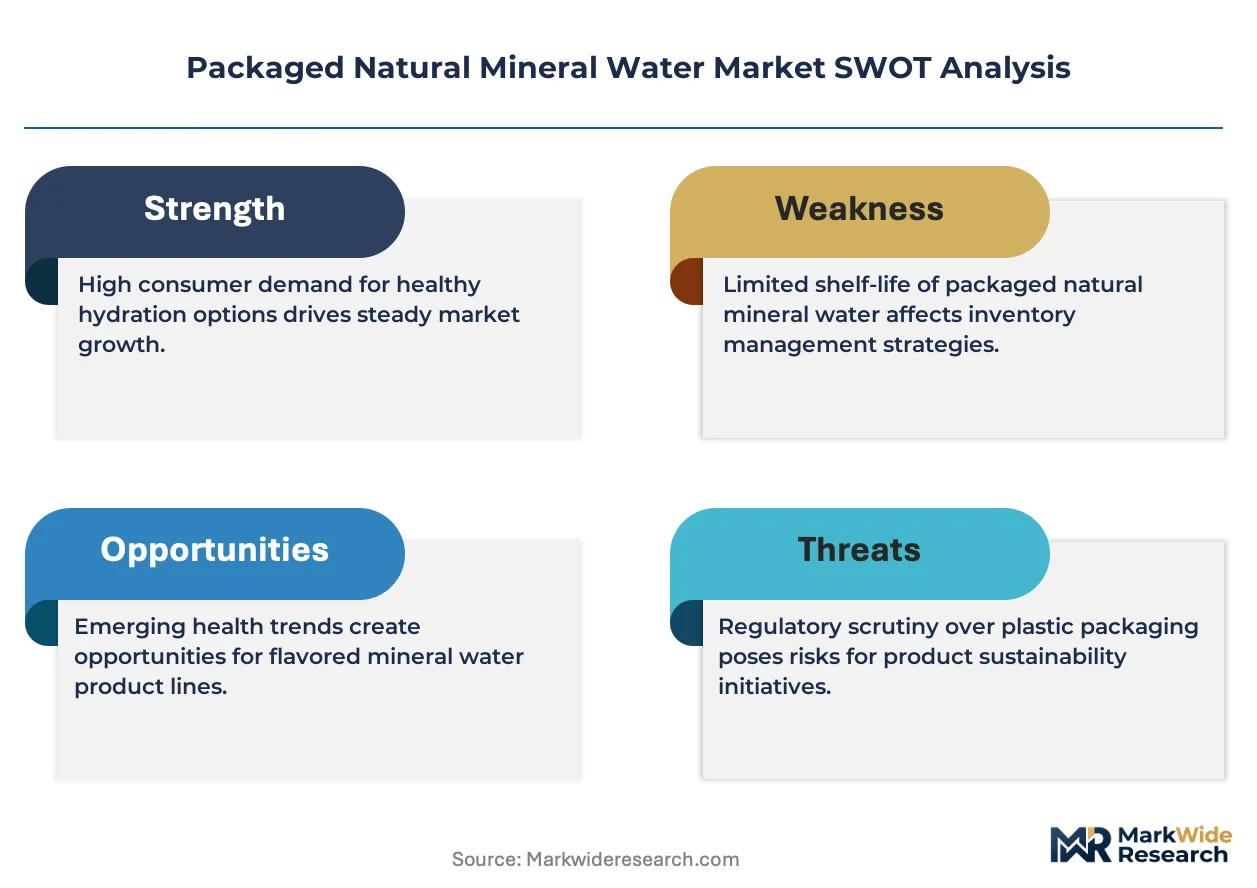
The FDA enforces standards of identity and quality for bottled water under 21 CFR 165, while EPA regulations on source protection shape extraction permitting across American aquifers. EU member states apply the Drinking Water Directive and Packaging Waste Directive to govern mineral content claims and end-of-life obligations. Stakeholders must weigh source certification investments against packaging material transitions as regulatory thresholds tighten on both product integrity and environmental compliance.
Market Dynamics
Recycled PET mandates across the EU and ASEAN are forcing packaging line retrofits while preserving shelf-life performance, compressing virgin resin demand and rewiring supplier relationships toward chemical recyclers.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content thresholds for PET bottles create compliant supply pull, accelerating converter investment in food-grade rPET capacity across Germany, France, and Italy.
- Hospitality channel premiumization:Jakarta's five-star hotels and Bali's resort corridors now specify glass-bottled mineral water for minibars and banquet service, expanding margin pools for certified spring sources.
- Direct-store-delivery infrastructure:PepsiCo's North American route density enables cold-chain placement in convenience stores, capturing impulse replenishment cycles that e-commerce cannot match.
Market Restraints
- Virgin PET price volatility:Ethylene feedstock swings tied to naphtha cracking economics compress converter margins when rPET premiums widen beyond 15 percent.
- Source concentration risk:Premium European spring extraction permits cluster in France's Vosges and Italy's Dolomites, creating bottleneck exposure for brands dependent on specific aquifer chemistry.
- Glass logistics cost structure:Weight-based freight penalties and breakage rates limit glass bottle distribution radius to 300 kilometers, constraining premium format reach.
Strategic Opportunities
- Subscription e-commerce penetration:Recurring residential delivery models in Germany and the Netherlands lock in household replenishment cycles while bypassing retail slotting fees.
- Indonesia's secondary city expansion:Surabaya and Bandung retail modernization creates underpenetrated distribution whitespace as Jakarta saturation intensifies.
- Chemical recycling scale-up:Eastman and Carbios technologies promise bottle-to-bottle molecular recycling, enabling infinite loop PET without quality degradation.
Industry Challenges
- Source certification timelines:FDA 21 CFR 165 aquifer protection documentation and EU mineral content verification require 18-24 month approval cycles, delaying new spring commercialization.
- Packaging line reconfiguration:Lightweighting and rPET integration demand blow-molding equipment retrofits that strain mid-tier bottler capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Natural Mineral Water Market |
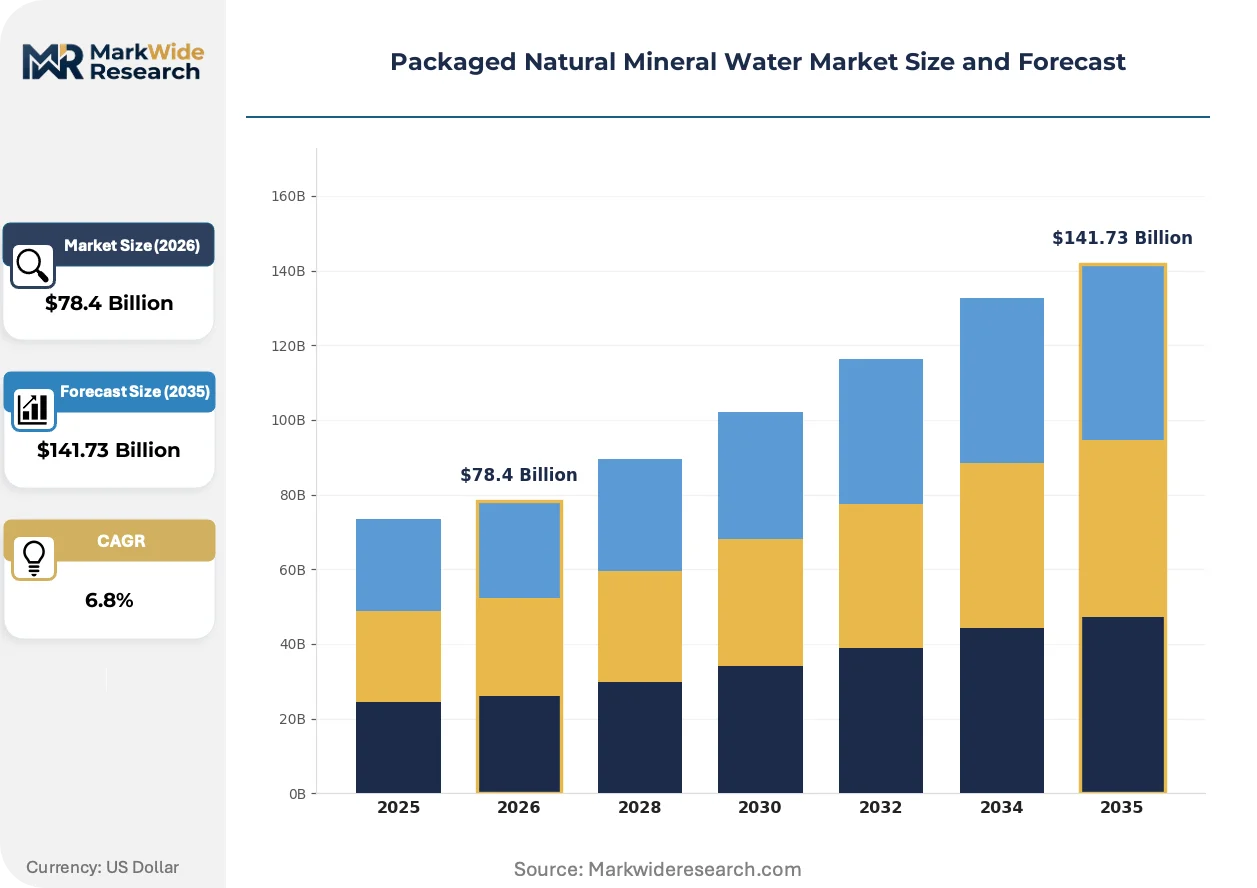
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Flavored, Spring Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines End User: Residential, Commercial, Sports, Hospitality |
| Companies Covered | Danone S.A., Nestle SA, The Coca Cola Co., PepsiCo Inc., Gerolsteiner Brunnen GmbH, Bisleri International Pvt. Ltd., Agthia Group PJSC, Mountain Valley Spring Co. LLC, China Resources Beverages Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Natural Mineral Water Market Trends and Innovations
Packaging material science and digital channel architecture are rewiring how mineral water reaches end-users, with sustainability credentials now functioning as table stakes rather than differentiation.
Biodegradable barrier coatings for paper-based bottles are absorbing technical validation resources from Nestle and Danone R&D divisions, though scalability remains constrained by moisture resistance thresholds. European retail buyers are piloting these formats in Nordic markets where extended producer responsibility fees penalize conventional plastic. The technology is absorbing shelf-life testing cycles that would otherwise flow into next-generation rPET blends, delaying mainstream deployment until 2027-2028.
REACH restrictions on intentionally added microplastics are compelling cap and label redesigns across EU bottling operations, with tethered closures becoming mandatory in France during 2025. The regulation forces mold modification investments that smaller regional bottlers defer, consolidating production share toward integrated converters with in-house tooling capabilities. Still water SKUs in 500ml-1L formats face the steepest compliance cost escalation given their volume dominance in private-label retail.
Hotel procurement departments are consolidating beverage suppliers into single-source contracts that bundle mineral water with soft drinks and juices, compressing the number of approved vendors per property. This vendor reduction is displacing fragmented local spring brands in favor of multinational portfolios with national distribution coverage. The pattern is most visible in Southeast Asia's hospitality construction pipeline, where management companies standardize amenity specifications across multi-property portfolios.
Packaged Natural Mineral Water Market Segmentation
Mineral water segmentation separates mass-market volume engines from premium margin pools. Product chemistry and packaging format together determine which extraction sources, distribution investments, and regulatory pathways each SKU requires.
Product Type:
The volume versus premium split runs through carbonation status and flavor layering, with still water anchoring household replenishment and sparkling variants commanding restaurant markups.
- Carbonated:Naturally effervescent or CO2-injected variants with dissolved carbon dioxide above 250 mg/L. Demand concentrates in Italy's restaurant channels and Germany's retail shelves, where table water culture sustains premium pricing over still alternatives.
- Non-Carbonated:Still mineral water without added gas, representing the default hydration format for daily consumption. Residential bulk purchases in Indonesia's Jakarta corridor and France's hypermarket chains lock in recurring volume through multi-pack SKUs.
- Flavored:Mineral water infused with natural or nature-identical extracts, typically citrus or berry profiles. Emerging segment absorbing R&D resources from Nestle and Danone innovation pipelines.
- Spring:Sourced from protected underground formations without mineral content standardization, often marketed on provenance narrative rather than certified composition. Regional bottlers in the US Appalachian basin and Italy's Alpine valleys dominate this fragmented tier.
Today's leader: Non-Carbonated. Tomorrow's challenger: Flavored.
Packaging Type:
Material selection rewires cost structures and distribution radius, with lightweight PET enabling scale and glass preserving margin in controlled hospitality environments.
- Plastic Bottles:PET containers from 330ml to 2L, optimized for blow-molding efficiency and logistics density. EU recycled content mandates under the Single-Use Plastics Directive are forcing rPET integration that preserves shelf-life performance while trimming virgin resin dependency.
- Glass Bottles:Returnable and single-use formats for premium positioning, constrained by 300-kilometer distribution radius due to weight-based freight penalties. Jakarta's five-star hotels and Bali's resort corridors specify these for minibar and banquet service.
- Tetra Packs:Aseptic cartons with aluminum barrier layers, penetrating Nordic retail where extended producer responsibility fees penalize conventional plastic formats.
- Pouches:Flexible film formats for single-serve impulse channels, limited by structural integrity concerns in ambient storage conditions.
Plastic Bottles capture the deepest volume penetration. Glass Bottles hold the steepest expansion trajectory in hospitality procurement.
Distribution Channel:
Channel selection determines cold-chain requirements, slotting fee exposure, and customer acquisition economics, with digital routes bypassing retail gatekeepers entirely.
- Supermarkets:Hypermarket and supermarket chains with dedicated beverage aisles and promotional calendar dependence. German and Dutch subscription models are displacing these for household replenishment cycles.
- Convenience Stores:Impulse-oriented small-format retail with cooler placement premiums. PepsiCo's North American direct-store-delivery infrastructure dominates cold-chain positioning here.
- Online Retailers:E-commerce platforms and direct-to-consumer subscription services, climbing the fastest as recurring delivery models lock in residential demand without retail slotting fees.
- Vending Machines:Automated dispensing in transit hubs, offices, and educational institutions, constrained by restocking frequency and payment system maintenance costs.
Supermarkets anchor current volume. Online Retailers are gaining share fastest through subscription lock-in.
End User:
Customer type dictates packaging specification, delivery frequency, and certification requirements, with institutional buyers consolidating vendor counts into single-source contracts.
- Residential:Individual households purchasing for daily hydration, fragmenting across bulk retail, subscription delivery, and convenience impulse. German and Netherlands markets show strongest subscription penetration.
- Commercial:Corporate offices and institutional cafeterias with bulk dispensing systems or single-serve coolers. Procurement departments are bundling mineral water with soft drink portfolios.
- Sports:Athletic facilities and event venues requiring portable formats with resealability. Volume spikes around seasonal tournament calendars.
- Hospitality:Hotels, restaurants, and catering operations with premium glass specifications and private-label co-manufacturing relationships. Southeast Asia's construction pipeline is standardizing amenity specifications across multi-property portfolios.
Residential commands absolute volume. Hospitality delivers the highest per-liter margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Vosges-Dolomites spring corridor anchors extraction capacity for premium mineral water, while Southeast Asian hospitality construction and North American direct-store-delivery infrastructure reshape consumption geography.
France
Volvic and Evian source clusters in the Massif Central and Alps drive premium export volume. The EU Drinking Water Directive governs mineral content verification and extraction permitting. Paris and Lyon retail channels sustain glass-bottled hospitality specifications for banquet service.
Indonesia
Jakarta's upscale retail corridors and Bali's resort construction pipeline absorb imported and domestic premium brands. The national food and drug regulator enforces bottled water safety standards under Ministry of Health mandates. Surabaya and Bandung secondary city modernization creates distribution whitespace beyond capital saturation.
Germany
Sparkling mineral water culture sustains per-capita consumption leadership through restaurant and household channels. The Packaging Waste Directive mandates extended producer responsibility fees that accelerate rPET converter investment. Hamburg and Munich retail networks pilot subscription e-commerce models displacing hypermarket replenishment.
United States
PepsiCo's direct-store-delivery route density captures impulse replenishment in convenience stores and gas stations. FDA 21 CFR 165 standards govern source protection documentation and quality enforcement. The Appalachian spring belt in West Virginia and Tennessee supplies regional bottlers with provenance-marketed extraction sources.
Italy
Carbonated table water tradition sustains restaurant channel premiumization through naturally effervescent sources. REACH restrictions on intentionally added microplastics compel tethered closure redesigns across bottling operations. Lombardy and Veneto industrial clusters concentrate blow-molding equipment retrofits for lightweight PET integration.
Packaged Natural Mineral Water Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit lines for rPET integration and hospitality procurement consolidates vendor counts. The market structures around three tiers: multinational beverage conglomerates with route-to-market infrastructure, European spring specialists with protected aquifer portfolios, and regional bottlers serving localized distribution radii. Strategic archetypes separate scale-driven volume players from premium-source specialists and private-label co-manufacturers. M&A activity and packaging line reconfiguration represent the dominant competitive vectors.
Among European spring specialists, Gerolsteiner Brunnen GmbH exemplifies protected-source premium positioning, while Danone S.A. and Nestle SA occupy positions spanning volume and premium tier portfolios. These three represent contrasting archetypes: the single-origin specialist with geographic concentration, the diversified conglomerate leveraging spring network breadth, and the integrated multinational with cross-category procurement bundling power.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestle SA |
| The Coca Cola Co. |
| PepsiCo Inc. |
| Gerolsteiner Brunnen GmbH |
| Bisleri International Pvt. Ltd. |
| Agthia Group PJSC |
| Mountain Valley Spring Co. LLC |
| China Resources Beverages Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hospitality procurement consolidation across Southeast Asia's resort corridors is forcing spring-source suppliers to absorb glass-bottling freight penalties and certification documentation costs, compressing margin pools for mid-tier bottlers while rewarding integrated multinationals with national distribution coverage.
Pricing Analysis
Input-cost pass-through from rPET premiums and virgin resin volatility is fragmenting pricing power across converter tiers. Three-tier pricing structure across premium glass, certified spring PET, and private-label economy lines separates hospitality-specified provenance narratives from mass retail replenishment. Pricing pressure stems from EU recycled content mandates widening rPET premiums beyond converter tolerance thresholds. Residential subscription buyers in Germany and the Netherlands show lowest price sensitivity, while convenience store impulse purchasers in North America exhibit highest elasticity.
Supply Chain Analysis
Domestic-content requirements under Indonesia's Ministry of Health bottled water safety standards are redirecting sourcing toward Javanese spring networks and local blow-molding capacity. Extraction concentrates in France's Vosges Massif, Italy's Dolomite valleys, and Indonesia's volcanic aquifers. Raw material dependencies span food-grade rPET resin, virgin PET pellets, and aluminum barrier laminates for aseptic formats. Single-source vulnerability runs through European spring permit clustering in protected Alpine formations. Distribution runs through direct-store-delivery infrastructure in North America and subscription e-commerce platforms in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on chemical recycling scale-up dissolving rPET quality degradation constraints, enabling premium positioning without virgin resin cost exposure.
For Market Incumbents: To counter hospitality vendor consolidation displacing fragmented local spring brands, anchor national distribution coverage through multi-property portfolio contracts and deepen backward integration into captive spring extraction permits in France and Italy. For New Entrants and Emerging Players: Subscription-resistant household segments in Indonesia's Surabaya and Bandung corridors offer white-space penetration through retail-modernization partnerships, while chemical recycling technology licensing creates differentiation without legacy converter capex burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with European spring specialists holding protected aquifer portfolios in the Vosges-Dolomites corridor, where FDA 21 CFR 165 and EU Drinking Water Directive compliance timelines create moats against rapid replication. Watch chemical recycling capacity announcements from Eastman and Carbios as inflection signals for rPET cost-structure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Eastman and Carbios technologies enable infinite-loop PET without quality degradation, preserving premium shelf-life performance. |
| Hospitality Single-Source Consolidation | Multi-property portfolio contracts in Southeast Asia displace fragmented local spring brands from minibar and banquet specifications. |
| Subscription E-Commerce Penetration | Recurring delivery models in Germany and Netherlands lock in household replenishment cycles without retail slotting fees. |
| Spring Permit Backward Integration | Captive extraction rights in France's Massif Central and Italian Alps secure provenance-marketed supply against regulatory delay. |
| rPET Blow-Molding Retrofit | Lightweighting equipment upgrades satisfy EU Single-Use Plastics Directive thresholds while trimming virgin resin dependency. |
Research Methodology
Coverage spans France, Indonesia, Germany, Italy, and the United States, with primary inputs from each market combining interviews with spring source operators, hospitality procurement directors, retail category buyers, and blow-molding equipment suppliers alongside secondary validation from FDA 21 CFR 165 filings, EU Drinking Water Directive implementation reports, Ministry of Health bottled water safety standards, and customs trade data. Bottom-up volume triangulation across extraction permits, converter capacity, and channel shipment data reconciles with top-down macroeconomic elasticity assumptions.
Granularity-level modeling disaggregates volume and value across carbonation status, packaging material format, distribution channel architecture, and end-user segment throughout the forecast period. CAGRs derive from segment-level growth rate blending weighted by base-year share, with inputs including hospitality construction pipeline data, rPET capacity expansion announcements, and subscription e-commerce penetration rates by postal code clustering.
Underlying measurement precision varies by segment; non-carbonated PET volume through supermarket channels carries tighter precision than flavored mineral water innovation pipelines. Forecasts reflect assumptions on regulatory enforcement timing and chemical recycling commercialization velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Global Vinegar Market
Beverages
Semillon Market
Beverages
Hot Cocoa Mix Market
Beverages
South America Mate Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
US Bubble Tea Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Beverage Dispenser Market
Beverages
Nitro-Infused Beverages Market
Beverages
Crystal Boba Market
Beverages
Beverage Premix Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Beverages Market
Beverages
Health Drinks Market
Beverages
Soft Serve Premix Market
Beverages
North America Juices Market