
 Sarsaparilla Market | 2026-2036
Sarsaparilla Market Size, Share, and Industry Trends Forecast 2026-2036
Sarsaparilla Market Analytics
Wild-harvesting expertise among traditional root collectors is collapsing across Central American supply zones, constraining raw material availability for premium extract grades. Mountain Rose Herbs leverages direct relationships with harvester cooperatives to secure traceable supply chains. Starwest Botanicals anchors its position through vertical integration into cleaning and milling operations. Sabinsa Corporation differentiates via R&D intensity in standardized saponin extraction protocols.
Sarsaparilla comprises the dried root and rhizome of Smilax species, typically containing steroidal saponins such as sarsasapogenin and smilagenin that deliver bitter-aromatic flavor profiles and traditional therapeutic associations. Primary commercial purpose centers on natural flavoring for beverages and botanical extracts for dietary supplements, with root material undergoing washing, drying, and solvent or aqueous extraction to isolate active fractions. Root extract commands the dominant margin pool due to concentration and standardization requirements, while syrup formats compete on nostalgia-driven beverage applications and powder forms serve functional food fortification. Specialty stores and direct sales channels capture premium pricing for certified organic grades, whereas supermarket distribution drives volume in ready-to-drink sarsaparilla beverages.
FDA botanical ingredient guidelines and USDA organic certification requirements shape labeling claims and import documentation burdens for root-derived products. The EPA and corresponding state agricultural departments in Mexico and Honduras regulate pesticide residue limits on exported botanical raw materials. Stakeholders must monitor evolving extraction solvent regulations and organic integrity verification protocols as supply chain transparency becomes a non-negotiable purchasing criterion.
Market Dynamics
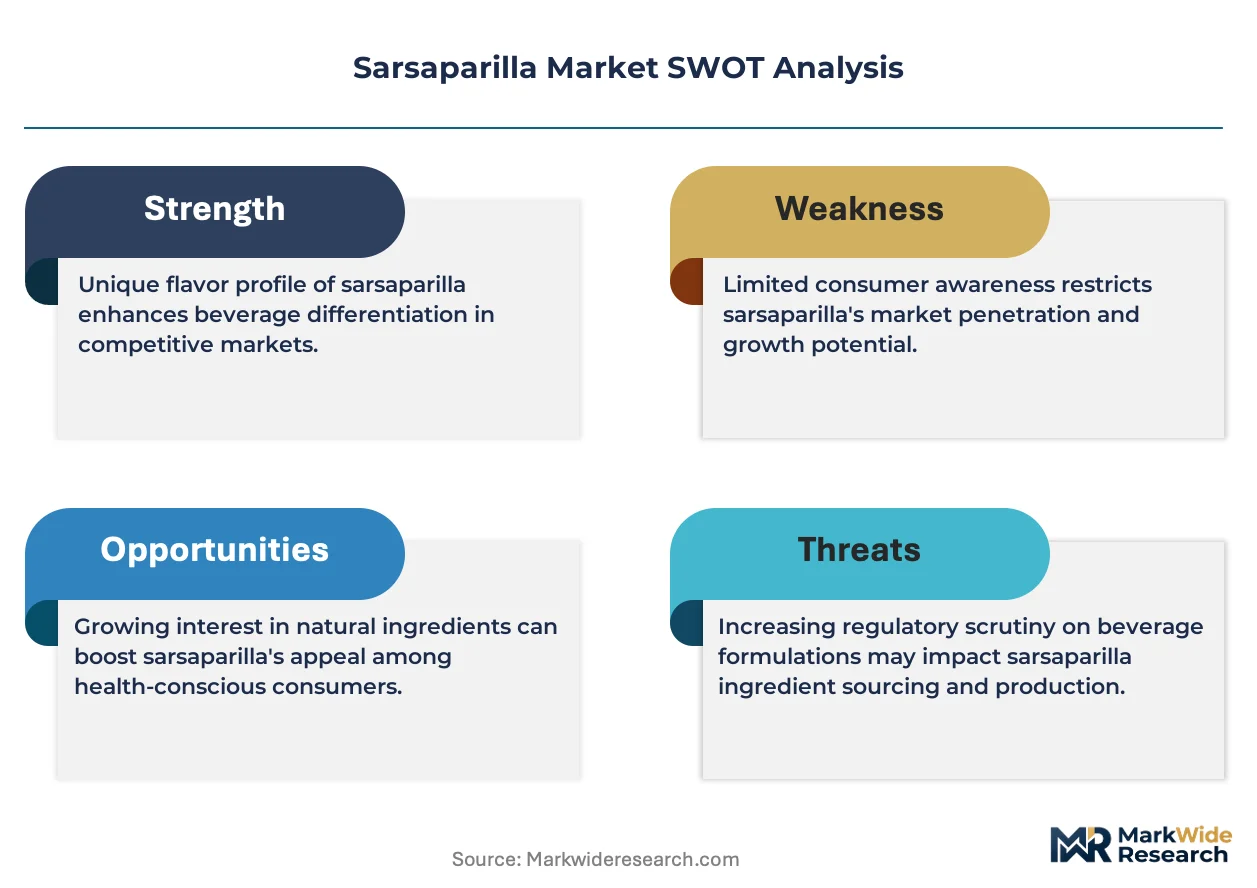
Wild-harvesting expertise collapse across Central American supply zones is constraining premium extract grades, forcing processors to rebuild collector networks or invest in cultivation alternatives.
Growth Catalysts
- FDA Botanical Ingredient Guidelines:Updated labeling requirements for root-derived products are accelerating traceability investments among U.S. extract suppliers, creating competitive moats for compliant operators.
- Natural Beverage Formulation:Mexican and U.S. beverage manufacturers are scaling sarsaparilla procurement as a bitter-aromatic alternative to synthetic flavoring agents in craft soda portfolios.
- Chiapas Harvester Cooperatives:Direct sourcing relationships with traditional root collectors in southern Mexico are securing supply chain transparency for premium organic grades.
Market Restraints
- Wild Root Availability Volatility:Smilax species regeneration cycles and deforestation pressure in Honduran highlands are creating raw material intermittency for solvent extraction facilities.
- USDA Organic Certification Burden:Documentation requirements for imported botanical raw materials are extending lead times and raising compliance costs for small-scale extract importers.
- Standardized Saponin Substitution:Yucca and quillaja extracts are displacing sarsaparilla in some beverage applications where foam stability rather than flavor complexity drives formulation decisions.
Strategic Opportunities
- Functional Food Fortification:Powdered sarsaparilla extract is penetrating protein bar and adaptogenic beverage formulations in U.S. direct-to-consumer channels.
- Regenerative Harvesting Protocols:Incentives under Mexico's SEMARNAT sustainable use permits are enabling cultivated Smilax pilots that reduce pressure on wild populations.
- Specialty Retail Expansion:Certified organic sarsaparilla syrup is capturing shelf space in U.S. natural grocery chains previously dominated by conventional soft drink portfolios.
Industry Challenges
- Extraction Solvent Compliance:Evolving EPA regulations on residual solvent limits in botanical extracts are forcing capital expenditure on supercritical CO2 equipment upgrades.
- Traditional Knowledge Documentation:Harvester cooperatives lack standardized protocols for transferring wild-harvesting expertise to younger collectors, threatening supply continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sarsaparilla Market |
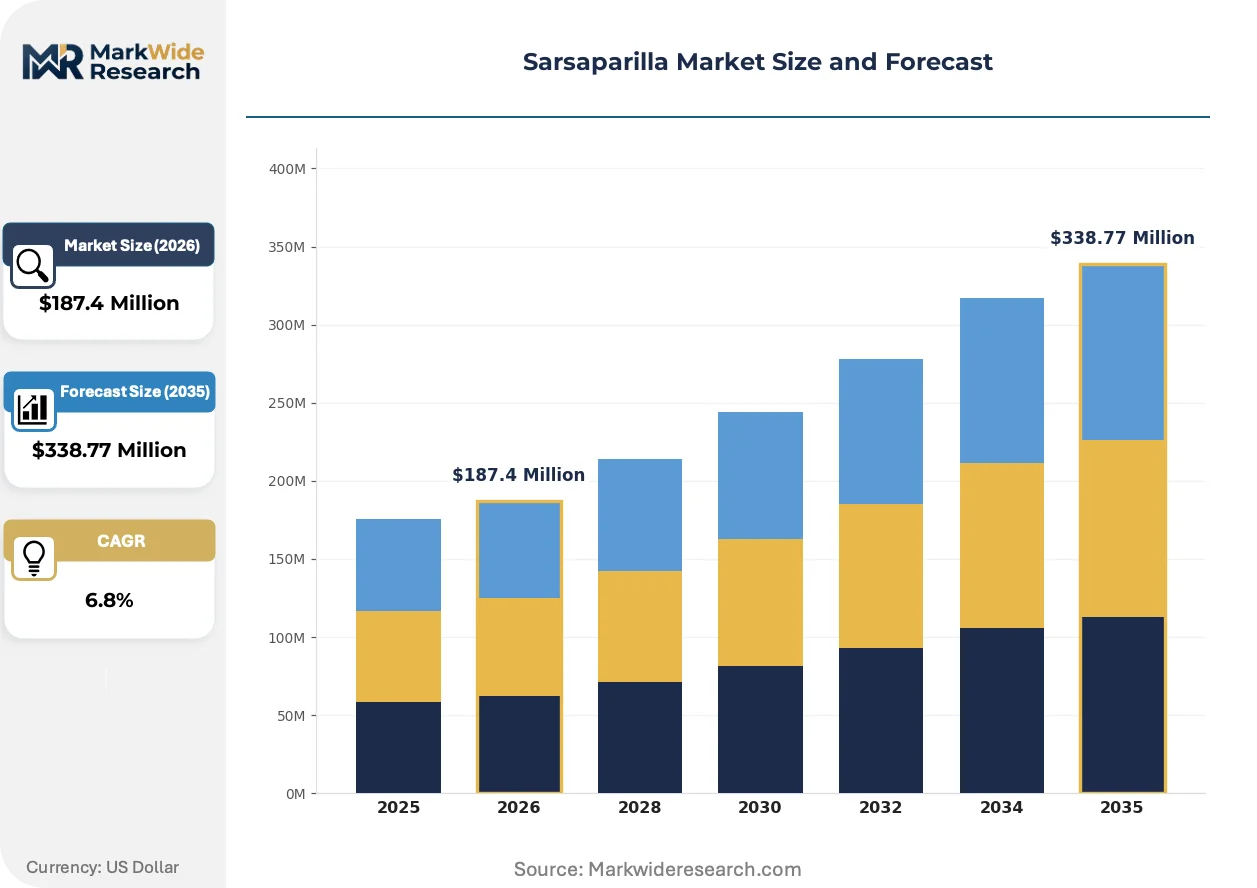
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Root Extract, Syrup, Beverage, Powder End User: Food Industry, Beverage Manufacturers, Health Shops, Retailers Application: Soft Drinks, Herbal Remedies, Culinary Uses, Cosmetic Products Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Mountain Rose Herbs, Starwest Botanicals, Naturex, Sabinsa Corporation, Bio-Botanica, Kpital Life-science, Herb Pharm, Penn Herb Company, Ltd., Himalayan Herbaria Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sarsaparilla Market Evolving Landscape
Processing technology and procurement transparency are converging to reshape competitive positioning, with standardization and traceability emerging as the primary axes of differentiation.
Supercritical CO2 extraction systems are miniaturizing from industrial-scale installations to modular units deployable at regional processing hubs in Veracruz and Oaxaca. Mid-size extract suppliers in Mexico are adopting these compact systems to reduce solvent handling costs and meet EPA residual limits without capital-intensive facility builds. The technology is miniaturizing quality control infrastructure, enabling smaller operators to produce standardized saponin grades previously requiring multinational-scale investment.
REACH registration requirements for botanical substances entering EU cosmetic and food applications are tightening purity documentation standards for sarsaparilla-derived ingredients. European extract importers are demanding batch-level steroidal saponin certificates and pesticide residue testing that exceeds baseline USDA organic requirements. Dietary supplement manufacturers targeting EU distribution are reformulating around extract grades with pre-validated REACH dossiers, compressing margins for suppliers lacking regulatory affairs capabilities.
Direct-to-harvester digital platforms are replacing layered broker networks in Central American sourcing corridors. U.S. botanical processors are deploying mobile payment and GPS-tracking applications to verify collection coordinates and ensure fair compensation in Chiapas and Campeche supply zones. This channel disintermediation is most visible among certified organic operators competing on supply chain storytelling for premium beverage and supplement markets.
Sarsaparilla Market Segmentation
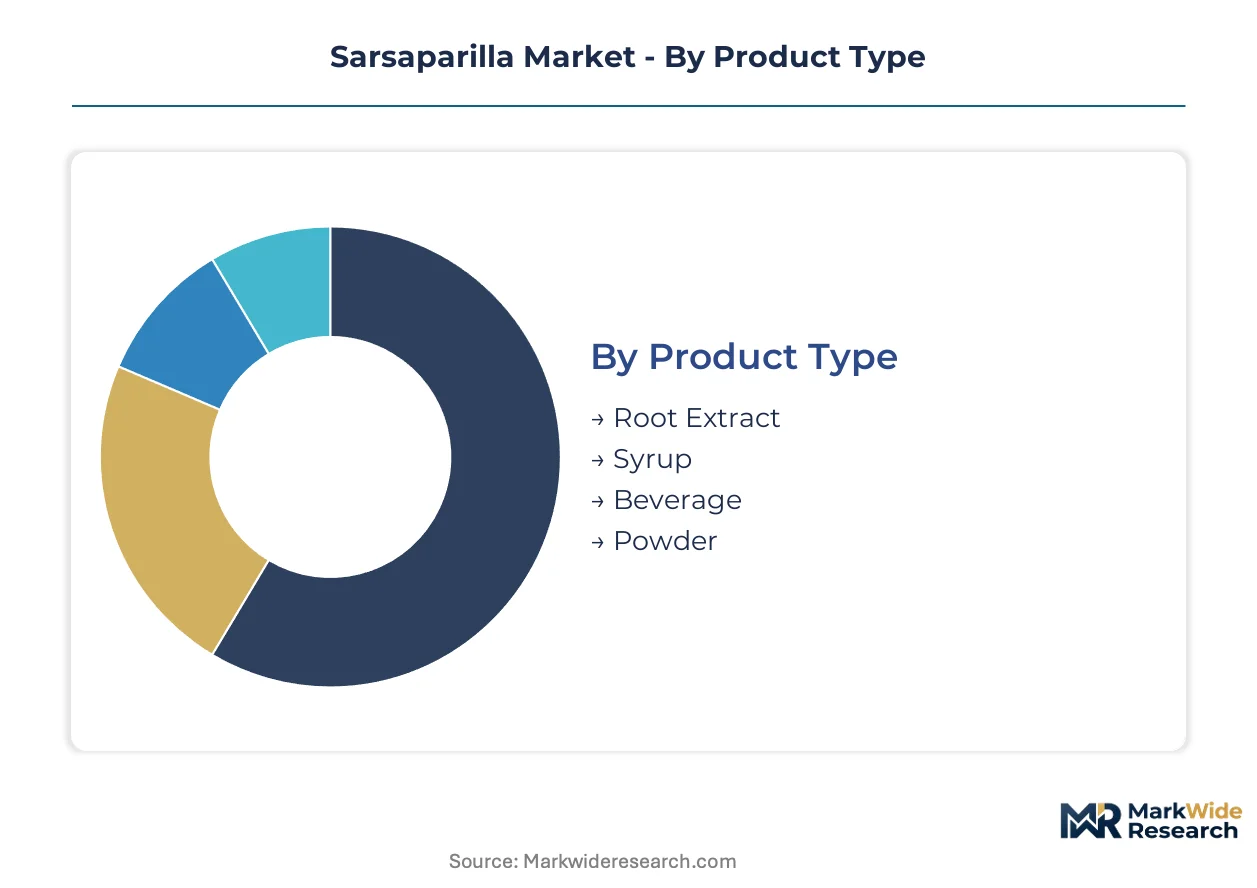
Sarsaparilla's commercial structure fragments across four distinct dimensions, each mapping to divergent margin profiles and regulatory exposure. Product type determines extraction complexity and standardization burden, while end-user concentration shapes procurement scale and certification requirements.
Product Type:
Root extract commands the dominant margin pool due to concentration protocols and steroidal saponin standardization requirements.
- Root Extract:Solvent or aqueous extraction isolates active saponin fractions including sarsasapogenin and smilagenin for dietary supplement and functional food applications. Demand concentrates among U.S. and Canadian processors seeking standardized grades for adaptogenic beverage formulations, constrained by wild-harvest intermittency in Honduran highlands.
- Syrup:Nostalgia-driven formulations for craft soda portfolios leverage bitter-aromatic flavor profiles without standardization overhead. Mexican beverage manufacturers in Jalisco and Guanajuato are scaling procurement as synthetic flavoring alternatives face clean-label pressure.
- Beverage:Ready-to-drink formats compete on volume through supermarket distribution channels with lower per-unit margins.
- Powder:Functional food fortification applications in protein bars and adaptogenic blends serve direct-to-consumer channels.
Root extract holds installed capacity. Syrup is rotating up the share rankings.
End User:
Procurement scale and certification stringency separate large-volume manufacturers from premium-channel specialists.
- Food Industry:Ingredient buyers prioritize batch-level steroidal saponin certificates and pesticide residue documentation exceeding baseline USDA organic thresholds. REACH-registered extract grades command premium positioning for EU-bound functional food formulations.
- Beverage Manufacturers:Mexican and U.S. craft soda producers drive volume procurement of syrup and extract formats, with formulation decisions increasingly favoring foam stability alternatives where flavor complexity is secondary.
- Health Shops:Certified organic grades with supply chain storytelling capture shelf space in natural grocery channels.
- Retailers:Supermarket distribution concentrates on ready-to-drink beverages with conventional price positioning.
Beverage manufacturers anchor volume throughput. Health shops are climbing the fastest on margin contribution.
Application:
Regulatory jurisdiction and formulation complexity create divergent compliance cost structures across use cases.
- Soft Drinks:FDA botanical ingredient labeling requirements accelerate traceability investments among U.S. extract suppliers, creating competitive moats for compliant operators serving craft soda portfolios.
- Herbal Remedies:Dietary supplement applications face USDA organic certification burdens and EPA residual solvent limits that extend lead times for small-scale importers.
- Culinary Uses:Traditional flavoring applications in Mexican and Central American cuisines maintain steady demand through ethnic food channels.
- Cosmetic Products:REACH registration requirements for EU cosmetic applications tighten purity documentation standards beyond food-grade specifications.
Soft drinks maintain formulation dominance. Herbal remedies are expanding most quickly on regulatory tailwinds.
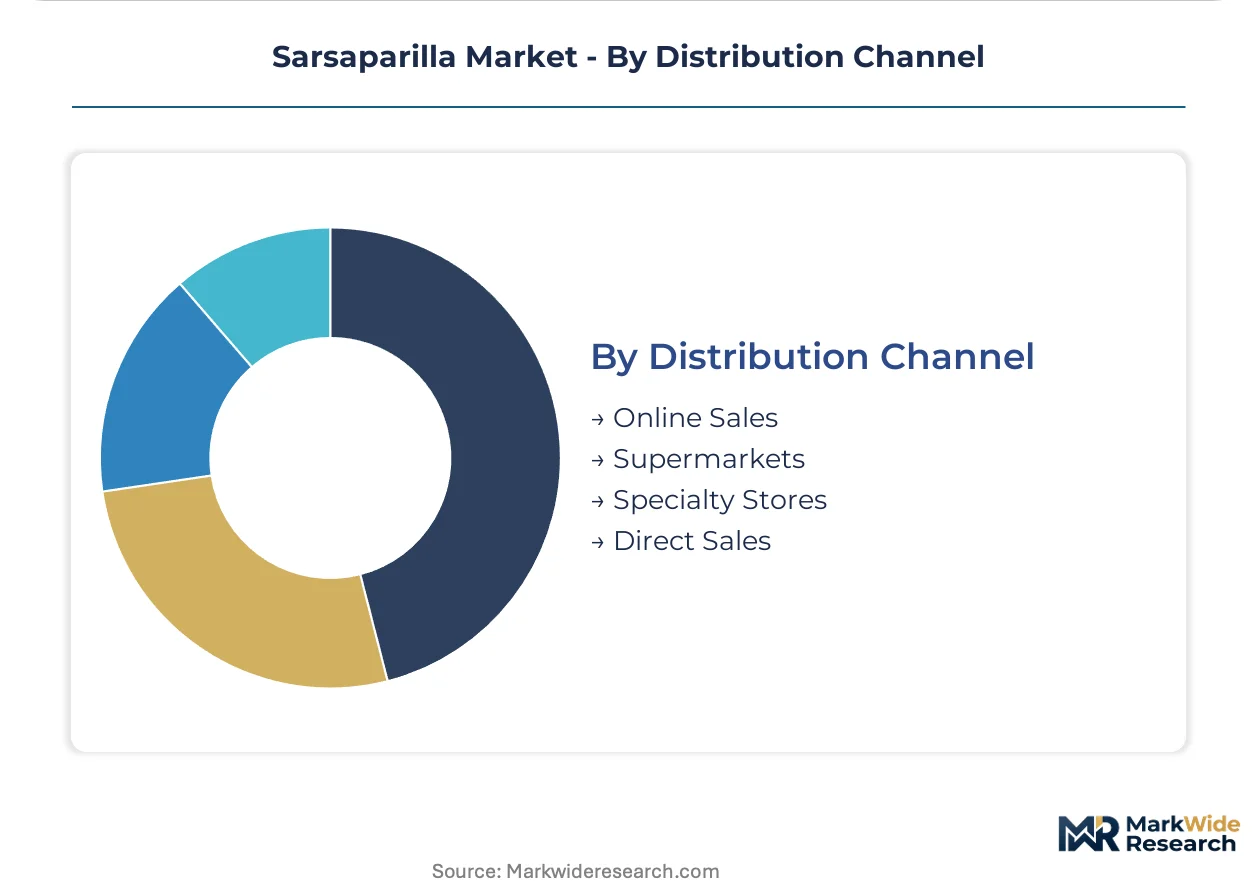
Distribution Channel:
Channel selection determines price realization and supply chain transparency verification depth.
- Online Sales:Direct-to-consumer platforms enable supply chain storytelling and premium pricing for certified organic grades with GPS-verified collection coordinates from Chiapas harvester cooperatives.
- Supermarkets:Volume-driven ready-to-drink beverage distribution competes on price positioning against conventional soft drink portfolios.
- Specialty Stores:Natural grocery chains in the U.S. capture margin premiums for organic syrup formats previously dominated by conventional alternatives.
- Direct Sales:Mobile payment and GPS-tracking applications deployed by U.S. botanical processors verify fair compensation and collection coordinates in Campeche supply zones.
Supermarkets hold throughput scale. Online sales are gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA botanical ingredient guidelines anchor procurement compliance for U.S. extract suppliers, while wild-harvest intermittency in Central American supply zones concentrates sourcing investments across Mexico, Honduras, and Guatemala. Beverage manufacturers in North America and Europe drive formulation demand, with regulatory divergence shaping regional competitive positioning.
United States
Craft soda producers in Texas and California scale sarsaparilla syrup procurement as clean-label alternatives displace synthetic flavoring agents. FDA updated labeling requirements for root-derived products accelerate traceability investments among extract suppliers. Veracruz-based processors supply standardized saponin grades to Los Angeles-area beverage formulators facing EPA residual solvent compliance burdens.
Mexico
Traditional root harvesting clusters in Chiapas and Campeche supply raw material to U.S. and Canadian processors seeking supply chain transparency. SEMARNAT sustainable use permits enable cultivated Smilax pilots that reduce pressure on wild populations. Jalisco beverage manufacturers anchor domestic syrup consumption, with Guanajuato processors expanding extraction capacity for export-grade organic certifications.
Canada
Health Canada botanical regulations shape import documentation requirements for sarsaparilla-derived dietary supplements entering Vancouver and Toronto distribution channels. Natural health product licensing burdens extend lead times for small-scale extract importers. British Columbia-based specialty retailers capture premium pricing for certified organic grades with GPS-verified collection coordinates.
Honduras
Deforestation pressure in Copán and Olancho highlands creates raw material intermittency for solvent extraction facilities serving North American markets. Central bank agricultural export financing programs support harvester cooperative formalization. San Pedro Sula processors face USDA organic certification documentation requirements that raise compliance costs for wild-root consignments.
Germany
REACH registration requirements for botanical substances entering EU cosmetic and food applications tighten purity documentation standards beyond baseline organic thresholds. ECHA dossier validation compresses margins for suppliers lacking regulatory affairs capabilities. Hamburg-based extract importers demand batch-level steroidal saponin certificates for dietary supplement formulations targeting EU distribution.
Sarsaparilla Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with procurement transparency and standardization capabilities separating competitive positions. The market structure concentrates margin capture among operators with direct harvester relationships and in-house extraction infrastructure. Three archetypes dominate: vertically integrated botanical processors with captive supply chains, regulatory affairs specialists with pre-validated REACH dossiers, and direct-to-harvester platform operators leveraging mobile verification technologies. Competitive moves center on backward integration into cleaning and milling operations and strategic partnerships with Chiapas harvester cooperatives.
Within the integrated processor tier, Mountain Rose Herbs and Starwest Botanicals exemplify archetypes built on supply chain control and quality infrastructure. Mountain Rose Herbs occupies a position anchored by direct relationships with harvester cooperatives, while Starwest Botanicals represents backward integration into upstream processing stages. Sabinsa Corporation sits within the regulatory-specialist vector, with its R&D intensity in standardized extraction protocols serving as a reference point for compliance-forward positioning. These three entities collectively illustrate how procurement depth and technical infrastructure determine competitive differentiation in premium extract grades.
| Leading Market Players |
|---|
| Mountain Rose Herbs |
| Starwest Botanicals |
| Naturex |
| Sabinsa Corporation |
| Bio-Botanica |
| Kpital Life-science |
| Herb Pharm |
| Penn Herb Company, Ltd. |
| Himalayan Herbaria Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for USDA organic-certified root consignments from Chiapas harvester cooperatives concentrate pricing power among processors with established direct-sourcing relationships, while intermittent wild-harvest availability in Honduran highlands forces spot-market premiums for non-contracted buyers. FDA botanical ingredient labeling requirements and EPA residual solvent compliance costs are compressing margins for small-scale extract importers lacking captive supply chains.
Pricing Analysis
Chiapas-to-Los Angeles price spreads for certified organic root extract exceed those for conventional grades by multiples reflecting documentation burdens and GPS-verified collection protocols. Three-tier pricing structure across premium organic, standard conventional, and economy syrup tiers separates buyers by certification requirements and end-use application. Pricing pressure stems from yucca and quillaja extract substitution in foam-stability-driven beverage formulations. Beverage manufacturers exhibit highest price sensitivity due to volume procurement and clean-label cost trade-offs, while dietary supplement formulators absorb premiums for standardized saponin grades.
Supply Chain Analysis
Seventy-five-day inventory cycles for wild-harvested Smilax root reflect seasonal collection windows and drying facility bottlenecks in Veracruz and Oaxaca processing hubs. Supply concentrates in Mexico, Honduras, and Guatemala, with raw material dependencies on traditional harvester cooperatives, supercritical CO2 extraction equipment, and REACH-registered laboratory certification. Single-source vulnerability runs through Chiapas collector networks where generational knowledge transfer gaps threaten supply continuity. Distribution runs through direct-to-harvester digital platforms for premium organic grades and layered broker networks for conventional syrup volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sarsaparilla market rewards operators who control scarce capabilities in wild-harvester relationship management and steroidal saponin standardization, while penalizing those dependent on spot-market procurement without traceability infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into cleaning and milling operations in Jalisco and Guanajuato, and accelerate supercritical CO2 equipment upgrades to meet tightening EPA residual solvent limits. Secure exclusive supply agreements with SEMARNAT-permitted cultivated Smilax pilots before regenerative harvesting protocols mature. Yucca extract substitution in craft soda formulations represents the primary demand-side threat requiring formulation partnership responses. For New Entrants and Emerging Players: Direct-to-consumer supply chain storytelling services for certified organic grades present an under-served layer where incumbent processors lack digital marketing infrastructure. Target online sales channels for GPS-verified Chiapas harvester cooperative products, where premium pricing tolerance exceeds supermarket beverage distribution. Pursue mobile payment and collection-coordinate verification platform partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational botanical processors divesting non-core sarsaparilla extraction units lacking REACH dossier capabilities. Long-term viability hinges on regulatory affairs depth and harvester cooperative relationship durability rather than commodity scale. Monitor FDA botanical ingredient guideline enforcement intensity as the inflection indicator for compliance-premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Harvester Cooperative Partnership | Direct relationships with Chiapas collectors secure traceable supply chains for premium organic grades. |
| Supercritical CO2 Equipment Upgrade | Modular extraction systems in Veracruz and Oaxaca meet EPA residual solvent limits without capital-intensive builds. |
| REACH Dossier Pre-validation | Batch-level steroidal saponin certificates enable EU cosmetic and food application market access. |
| Cultivated Smilax Pilot Investment | SEMARNAT sustainable use permits reduce wild-population pressure and supply intermittency risk. |
| Direct-to-Consumer Platform Launch | Online sales channels capture premium pricing for GPS-verified collection coordinate storytelling. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extract procurement managers at U.S. beverage manufacturers, regulatory affairs directors at dietary supplement formulators, harvester cooperative leaders in Chiapas and Campeche, and supercritical CO2 equipment suppliers; and secondary validation through FDA botanical ingredient guidance documents, USDA organic certification databases, SEMARNAT sustainable use permit records, and ECHA REACH registration dossiers. Bottom-up volume modeling from harvester cooperative output estimates triangulated against top-down demand aggregation from North American and European extract importers.
Across the analysis window, the forecasting framework modeled product type segmentation by extraction complexity and standardization burden, end-user concentration by procurement scale and certification stringency, application differentiation by regulatory jurisdiction, and distribution channel variation by price realization potential. CAGRs were derived from segment-level growth rate blending weighted by margin contribution. Forecast inputs incorporated wild-harvest intermittency patterns in Honduran highlands and FDA labeling requirement enforcement trajectories.
Underlying assumptions cover sustained clean-label beverage formulation trends and SEMARNAT permit program continuity, with deviation risk concentrated in generational knowledge transfer collapse among traditional root collectors and yucca extract substitution acceleration in foam-stability applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Juices Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Growlers Market
Beverages
US Bubble Tea Market
Beverages
Yerba Mate Market
Beverages
Juice Market
Beverages
Powdered Soft Drinks Market
Beverages
Rose Floral Water Market
Beverages
Carbonated Beverages Market
Beverages
United States and Australia Coconut Water Market
Beverages
Sparkling Bottled Water Market
Beverages
South America Bottled Water Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Europe Ready-To-Drink Beverages Market